
 Global Industrial Oils Market | 2026-2036
Global Industrial Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Oils Market Outlook
Heavy machinery operators in construction and energy are rotating toward synthetic and biolubricant formulations as equipment OEMs tighten fluid specifications for warranty compliance. ExxonMobil Corporation leverages its integrated base oil production network to supply high-viscosity Group III synthetics to mining and power generation customers. Shell plc anchors its position through backward integration into gas-to-liquids technology, while China Petroleum & Chemical Corporation dominates domestic blending capacity with captive supply of additive packages.
Industrial oils are formulated lubricants designed to reduce friction, dissipate heat, and prevent corrosion in mechanical systems operating under extreme pressure, temperature, or contamination loads, with viscosities typically ranging from ISO VG 32 to 680 and incorporating anti-wear chemistries such as zinc dialkyldithiophosphate. Their primary purpose is to extend equipment life and maintain operational efficiency in continuous-duty industrial environments. Mineral oils still occupy the largest volume share across metalworking and legacy manufacturing applications, though biolubricants represent the fastest-expanding category as food processing and agriculture buyers adopt plant-based formulations to meet sustainability procurement criteria. Synthetic oils command the deepest margin pools in energy and transportation end uses, where drain-interval extension justifies premium pricing.
The US EPA and OSHA frameworks govern workplace exposure limits and waste oil handling protocols, while REACH and the EU F-Gas Regulation restrict certain additive chemistries and mandate biodegradability thresholds for environmentally sensitive applications. China's GB standards and MEE enforcement are pushing domestic blenders toward cleaner base oil refining and tighter emissions reporting. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to segment supply chains and force regional formulation customization.
Market Dynamics
Equipment OEMs are tightening fluid specifications for warranty compliance, forcing blenders to reformulate around higher-performance base stocks and additive packages that can sustain extended drain intervals under extreme operating conditions.
Growth Catalysts
- EU F-Gas Regulation:The framework mandates lower-emission chemistries, pulling food processing and agriculture buyers toward biodegradable formulations that command premium positioning.
- China infrastructure spending:State-backed capital deployment in construction and power generation is concentrating volume demand among domestic blenders with captive additive supply.
- Gas-to-liquids technology:Synthetic base oil production via GTL processes enables Group III+ formulations that satisfy mining equipment OEM warranty requirements.
Market Restraints
- Group II/III base oil supply concentration:Refinery capacity for high-viscosity synthetics clusters in the US Gulf Coast and Middle East, exposing buyers to logistics bottlenecks.
- REACH additive restrictions:ECHA scrutiny of zinc dialkyldithiophosphate and other anti-wear chemistries forces costly reformulation cycles for metalworking fluid suppliers.
- Used oil re-refining economics:Collection infrastructure gaps in emerging markets limit circular feedstock availability for lower-cost base oil production.
Strategic Opportunities
- India manufacturing scale-up:PLI scheme incentives for domestic machinery production are creating first-mover positioning for blenders establishing local formulation capacity.
- Wind turbine drivetrain fluids:Offshore installations require synthetic lubricants with decade-long service life, opening specification capture opportunities at OEM design stage.
- Digital fluid monitoring:IoT sensor integration enables predictive drain scheduling, creating subscription revenue models that displace transactional bulk sales.
Industry Challenges
- Tribology expertise scarcity:Formulation chemists with simultaneous competence in synthetic base oil behavior and extreme-pressure additive synergy command compensation premiums that compress blender margins.
- Biodegradability certification timelines:OECD 301B and EU Ecolabel approval processes extend product launch cycles, delaying revenue recognition for sustainable formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Oils Market |
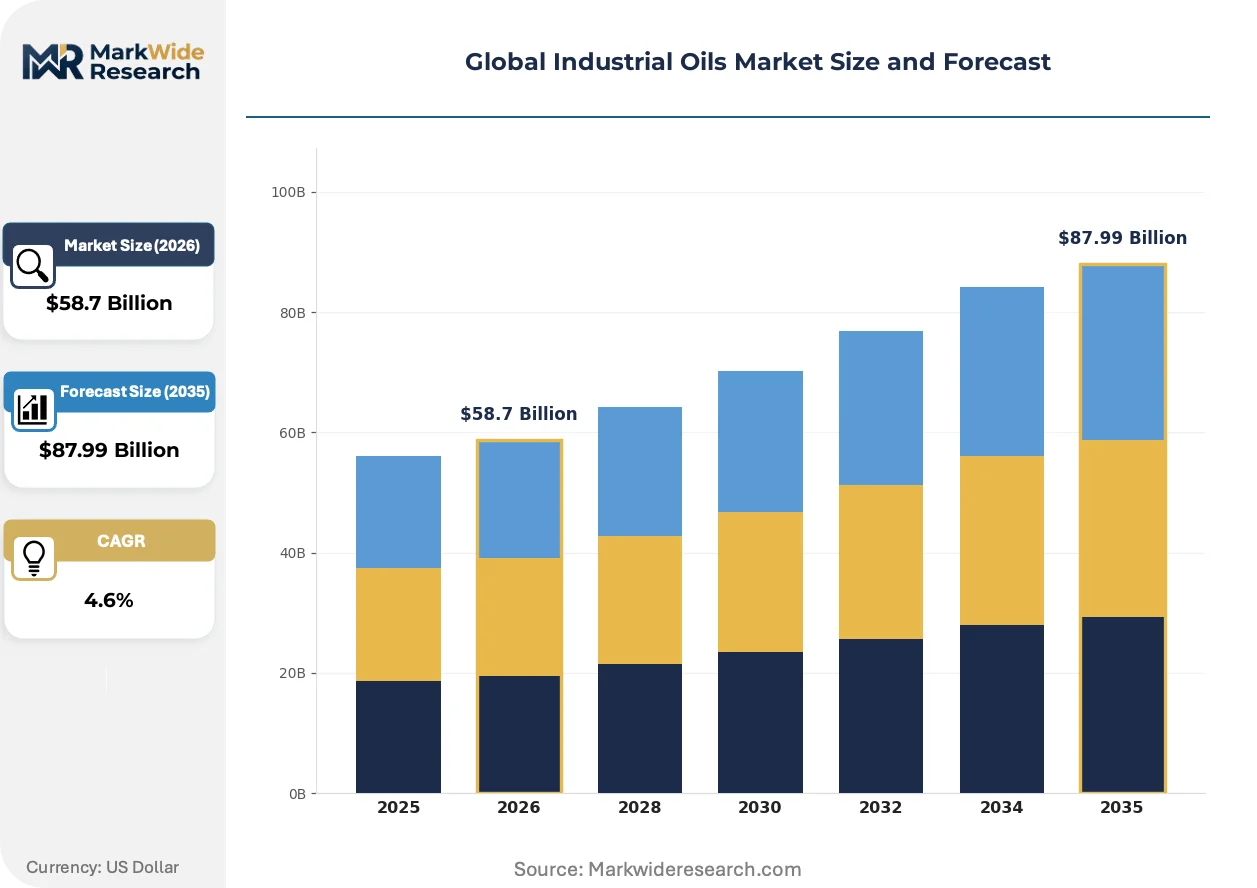
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $87.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oils, Vegetable Oils, Synthetic Oils, Biolubricants Application: Automotive, Metalworking, Food Processing, Agriculture End User: Manufacturing, Transportation, Construction, Energy Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | ExxonMobil Corporation, Shell plc, BP p.l.c., Chevron Corporation, TotalEnergies SE, China Petroleum & Chemical Corporation, China National Petroleum Corporation, Petroliam Nasional Berhad, ENEOS Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Oils Market Strategic Shifts
Synthetic lubricant technology is fragmenting into performance tiers that align with equipment complexity gradients, while regulatory chemistry restrictions and buyer procurement recalibration reshape competitive positioning across end-use verticals.
Polyalkylene glycol formulations are bifurcating the compressor lubricant segment. These water-soluble synthetics deliver thermal stability beyond mineral oil limits. Food and beverage processors are adopting them aggressively to eliminate hydrocarbon contamination risks. The technology is bifurcating supplier tiers into PGL-capable blenders and legacy mineral specialists facing margin compression.
REACH authorization requirements for persistent, bioaccumulative substances are constraining anti-wear additive palettes. ECHA sunset dates for certain organometallic compounds force reformulation investments. Metalworking fluid suppliers serving automotive component manufacturers are accelerating phosphate ester and ionic liquid alternatives to maintain European market access.
Power generation utilities are consolidating lubricant procurement through corporate-level framework agreements that displace site-by-site purchasing. Centralized technical specification authority now resides with engineering headquarters rather than plant maintenance departments. This concentration is most visible in US and German utility fleets, where approved vendor lists have compressed to three or fewer national distributors.
Global Industrial Oils Market Segmentation
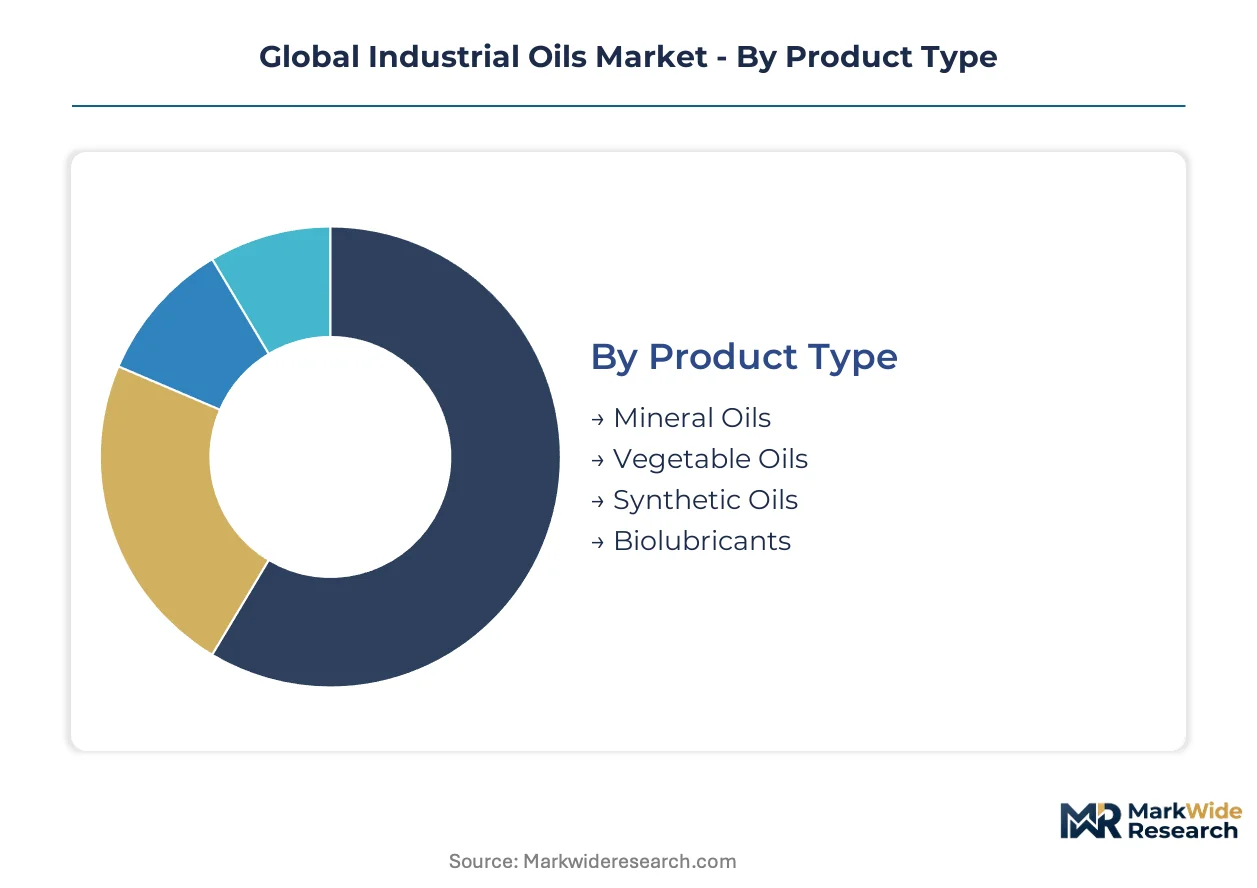
Industrial oils fragment across four distinct category axes, each governing different margin architectures and procurement behaviors. Product type determines base stock chemistry and regulatory compliance burden. Application verticals dictate performance specifications and drain interval economics. End user concentration shapes volume contracting power. Distribution channel selection reflects customer scale and technical service requirements.
Product Type:
Margin pools concentrate in synthetic and biolubricant formulations where performance premiums offset higher production costs.
- Mineral Oils:Refined petroleum distillates with ISO VG viscosity grading from 32 to 680 dominate metalworking and legacy manufacturing applications. Demand concentrates in China and India where state infrastructure spending pulls volume toward domestic blenders with captive base oil supply. Mineral formulations face margin compression as OEM warranty specifications tighten.
- Synthetic Oils:Group III and Group IV base stocks manufactured through hydrocracking or gas-to-liquids processes deliver extended drain intervals under extreme pressure and temperature loads. Mining equipment operators in Australia and power generation utilities in Germany specify these formulations for warranty compliance. Synthetics command the deepest margin pools in energy and transportation end uses.
- Vegetable Oils:Triglyceride-based formulations derived from rapeseed, soybean, or sunflower feedstocks serve niche applications requiring rapid biodegradability.
- Biolubricants:Plant-based formulations meeting OECD 301B biodegradability thresholds and EU Ecolabel criteria are climbing the fastest as food processing and agriculture buyers adopt sustainability procurement mandates.
Mineral oils hold installed capacity. Biolubricants are rotating up the share rankings.
Application:
Volume concentration follows equipment complexity gradients, with metalworking and automotive commanding the largest absolute demand.
- Metalworking:Cutting fluids, grinding oils, and forming lubricants incorporating extreme-pressure additives like chlorinated paraffins or phosphate esters manage heat generation and tool wear in precision machining operations. Automotive component manufacturers in Germany and Japan drive specification tightening as REACH sunset dates force reformulation away from bioaccumulative chemistries.
- Automotive:Transmission fluids, brake fluids, and assembly line lubricants serve vehicle production and aftermarket maintenance. Electric vehicle battery thermal management fluids represent an emerging specification battleground as OEMs redesign thermal systems.
- Food Processing:NSF H1-registered lubricants eliminate hydrocarbon contamination risks in packaging and processing equipment. Polyalkylene glycol formulations are displacing mineral oils in compressor applications.
- Agriculture:Tractor hydraulic fluids and implement lubricants face procurement recalibration as EU Farm-to-Fork sustainability targets cascade through equipment purchasing.
Metalworking anchors volume demand. Food processing is expanding most quickly on regulatory pull.
End User:
Customer scale and contracting sophistication separate national distributors from direct technical sales relationships.
- Manufacturing:Discrete and process manufacturers operate the largest installed base of circulating systems and hydraulic equipment. US and German automotive tier suppliers consolidate procurement through corporate framework agreements that compress approved vendor lists.
- Energy:Power generation utilities and oilfield service companies specify synthetic formulations for gas turbines and drilling equipment. Offshore wind turbine drivetrain fluids require decade-long service life specifications.
- Transportation:Fleet operators and logistics providers optimize total cost of ownership through extended drain interval programs.
- Construction:Heavy machinery operators rotate toward higher-performance synthetics as equipment complexity rises and OEM warranty terms tighten.
Manufacturing retains the broadest installed base. Energy is climbing fastest on infrastructure investment cycles.
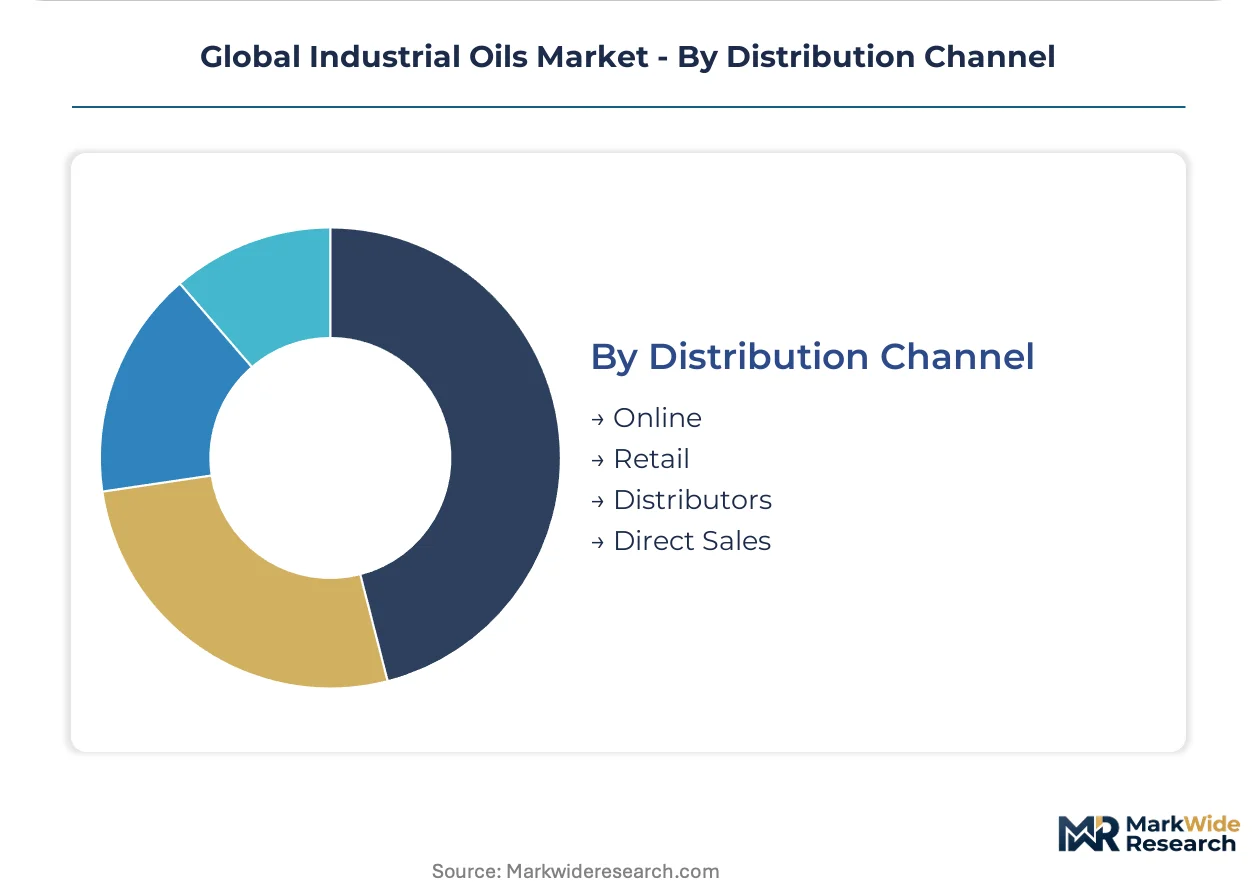
Distribution Channel:
Channel selection maps directly to customer technical service requirements and procurement centralization.
- Distributors:National and regional lubricant distributors maintain local inventory and field engineering support for mid-scale manufacturing and transportation accounts. US and European distribution networks face consolidation pressure as utilities centralize procurement authority.
- Direct Sales:Multinational oil companies deploy technical sales engineers for large energy and mining accounts requiring custom formulation and predictive maintenance programs.
- Online:E-procurement platforms serve small and mid-sized maintenance shops with standardized product grades and rapid replenishment.
- Retail:Automotive parts retailers and farm supply cooperatives capture aftermarket and agricultural implement demand.
Distributors hold relationship density. Direct sales is rotating up the share rankings on specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Aramco and ADNOC export Group II/III base oils to Indian blenders and European formulators, creating a trade-flow corridor that shapes regional pricing benchmarks and supply security calculations across buyer geographies.
United States
Gulf Coast refineries concentrate high-viscosity synthetic base oil capacity serving mining equipment operators in Australia and power utilities in Germany. EPA enforcement of waste oil handling protocols tightens compliance costs for metalworking fluid suppliers. Houston anchors formulation R&D activity as blenders develop phosphate ester alternatives to zinc dialkyldithiophosphate chemistries.
China
State-backed infrastructure spending in construction and power generation pulls volume toward domestic blenders with captive additive supply chains. MEE enforcement of GB standards pushes refiners toward cleaner base oil processing and tighter emissions reporting. The Yangtze River Delta concentrates joint-venture blending capacity serving automotive component manufacturers.
Germany
Automotive tier suppliers and power generation utilities consolidate procurement through corporate framework agreements that compress approved vendor lists to three national distributors. REACH sunset dates for organometallic anti-wear compounds force reformulation investments across metalworking fluid portfolios. The Ruhr industrial cluster hosts tribology research centers developing ionic liquid alternatives.
India
PLI scheme incentives for domestic machinery production create first-mover positioning for blenders establishing local formulation capacity. BIS standards alignment with ISO viscosity grading simplifies import substitution strategies. Maharashtra and Gujarat concentrate automotive component manufacturing demand pulling synthetic hydraulic fluid specifications.
Japan
METI-supported gas-to-liquids technology development enables Group III+ base oil production for precision machinery and robotics applications. JIS standards for food-grade lubricants align with NSF H1 registration requirements. The Chubu region around Nagoya anchors compressor lubricant formulation serving semiconductor manufacturing equipment OEMs.
Global Industrial Oils Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and formulation complexity dimensions, creating a tiered structure where integrated majors control base oil supply while regional blenders capture specification-driven niches. Three strategic archetypes dominate: integrated oil majors with captive refining, national oil companies with domestic distribution density, and specialized blenders with tribology service capabilities. Competitive moves concentrate on backward integration into additive manufacturing and geographic expansion through joint ventures in high-growth demand centers.
Within the integrated major tier, ExxonMobil Corporation and Shell plc exemplify players leveraging upstream control over base oil quality to secure long-term supply agreements with mining and power generation accounts. China Petroleum & Chemical Corporation anchors the national oil company archetype through domestic blending scale and state-supported infrastructure project offtake. These three entities represent distinct competitive positioning vectors—technology-led premium formulation, GTL-derived synthetic supply security, and volume-captive domestic market capture—without implying specific strategic initiatives or financial performance metrics.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| BP p.l.c. |
| Chevron Corporation |
| TotalEnergies SE |
| China Petroleum & Chemical Corporation |
| China National Petroleum Corporation |
| Petroliam Nasional Berhad |
| ENEOS Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Group II/III base oil refiners and mining equipment operators lock in supply access while providing price visibility across volatile feedstock cycles. These contracts tie volume commitments to API Group specifications, insulating blenders from spot market swings in crude-derived feedstocks while exposing them to pass-through clauses on additive package costs.
Pricing Analysis
The technology-generation pricing gap separates legacy mineral formulations from synthetic Group III+ and emerging biolubricant tiers. Three-tier pricing structure across premium synthetic, standard mineral, and economy re-refined grades anchors the market, with differentiation driven by ISO VG viscosity certification and OEM warranty compliance levels. Pricing pressure stems from REACH-mandated reformulation costs as ECHA sunset dates force substitution of zinc dialkyldithiophosphate anti-wear chemistries. Small metalworking shops exhibit the highest price sensitivity, while power generation utilities prioritize drain-interval economics over unit cost.
Supply Chain Analysis
Inbound logistics costs from US Gulf Coast and Middle Eastern refineries to European and Asian blenders fluctuate with Red Sea container availability and Suez Canal routing decisions. Geographic supply concentration clusters in the United States, Saudi Arabia, and South Korea for high-viscosity Group III base stocks, while additive package production draws from Germany, the United States, and Japan. Single-source vulnerability around specialized extreme-pressure chemistries threatens formulation continuity as REACH restrictions narrow supplier pools. Distribution runs through national lubricant distributors with field engineering capabilities, though direct sales channels are rotating up share rankings on specification complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial oils market is approaching a platform-economics inflection as digital fluid monitoring systems create interoperability standards between sensor hardware, predictive analytics software, and lubricant formulation databases. Equipment OEMs are consolidating technical specification authority at corporate headquarters, transforming procurement from transactional bulk purchasing into integrated performance-contracting relationships.
For Market Incumbents: Fortify backward integration into captive additive manufacturing to secure supply continuity amid ECHA authorization tightening. ExxonMobil Corporation and Shell plc exemplify this positioning through in-house production of detergent and dispersant chemistries. Capacity expansion in India's Maharashtra and Gujarat industrial corridors captures PLI-scheme machinery demand before domestic blenders achieve formulation parity. Certification investment in OECD 301B biodegradability and EU Ecolabel registration creates switching costs for food processing accounts migrating from mineral to biolubricant formulations. For New Entrants and Emerging Players: NSF H1 fast-track certification for food-grade compressor lubricants opens specification capture opportunities in polyalkylene glycol formulations displacing mineral oils. The most penetrable white space sits in Indian automotive component manufacturing, where BIS standards alignment with ISO viscosity grading simplifies import substitution. Wind turbine drivetrain fluids for offshore installations represent a second target, as decade-long service life specifications favor new entrants with synthetic formulation expertise over legacy mineral suppliers. Go-to-market positioning should emphasize IoT-enabled predictive maintenance partnerships rather than transactional bulk supply. For Investors and Strategic Acquirers: Regional blenders with tribology service capabilities and established OEM approval relationships represent the most defensible acquisition archetype in a five-to-ten-year viability window. These targets combine formulation chemistry expertise with direct technical sales relationships that national distributors cannot replicate. The signal to watch is consolidation in German and US utility procurement, where approved vendor list compression to three or fewer distributors indicates tipping-point market structure shift toward specification-captured incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive supply of detergent and dispersant chemistries insulates blenders from REACH authorization disruptions. |
| Capacity Expansion in India | PLI scheme incentives for domestic machinery production pull volume toward local formulation facilities. |
| Digital Fluid Monitoring Platform Launch | IoT sensor integration enables subscription revenue models displacing transactional bulk lubricant sales. |
| Biodegradability Certification Investment | OECD 301B and EU Ecolabel registration captures food processing procurement mandates. |
| Joint Venture in China | Yangtze River Delta blending capacity serves automotive component manufacturers with captive additive supply. |
Study Parameters
The analysis maps mineral oil, synthetic, and biolubricant sub-sectors, each validated through interviews with plant maintenance directors, OEM procurement teams, lubricant distribution channel partners, and tribology R&D directors. Primary fieldwork combined with secondary validation from customs and trade flow data, ACC and Cefic industry reports, SEC 10-K filings, and national oil company production disclosures established baseline volumes. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators refined demand estimates across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including refinery capacity utilization reports and additive manufacturing output data. The analytical framework modeled product type, application vertical, end-user concentration, and distribution channel dimensions across the analysis window. CAGRs derived from equipment fleet growth rates, drain-interval extension trends, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs incorporated OEM warranty specification tightening timelines and REACH sunset date implementation schedules.
Decision-makers should treat outputs as directional under assumptions of continued infrastructure spending in China and India, stable base oil refining capacity in the US Gulf Coast and Middle East, and gradual REACH enforcement without accelerated sunset date advancement; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Cryogenic Column Market