
 Global Continuous Stirred Tank Reactors Market | 2026-2036
Global Continuous Stirred Tank Reactors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Continuous Stirred Tank Reactors Market Intelligence
The CSTR market is pivoting on a widening split between premium corrosion-resistant alloy systems and commodity carbon-steel vessels. Thermo Fisher Scientific leverages its magnetically driven technology portfolio to command premium positioning in pharmaceutical-grade installations. Parr Instrument Company anchors North American demand through specialized high-pressure reactor designs for research and pilot-scale operations. Nano-Mag Technologies competes aggressively in Asia through cost-optimized electrically operated units tailored for mid-volume chemical processors.
A continuous stirred tank reactor maintains uniform composition and temperature through continuous feed input and product withdrawal while mechanical or magnetic agitation sustains homogeneous mixing, with typical operating pressures spanning vacuum to 200 bar and temperature ranges from cryogenic to 500°C depending on alloy specification. Jacketed reactors dominate installed base value due to their thermal control precision in exothermic synthesis, while magnetically driven technology captures fastest-growing demand by eliminating seal contamination risks in bioprocessing applications. Glass-lined reactors occupy a mature, defensible niche in pharmaceutical manufacturing where product purity mandates override capital cost sensitivity.
EPA emissions enforcement under the Clean Air Act shapes vessel sealing and venting standards in United States process industries, while REACH and the EU Green Deal drive material substitution toward lower-carbon alloy formulations across European chemical parks. China's MEE enforces stricter effluent thresholds that accelerate replacement of legacy mechanically agitated units with sealed magnetically driven systems. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading impact on reactor material sourcing decisions.
Market Dynamics
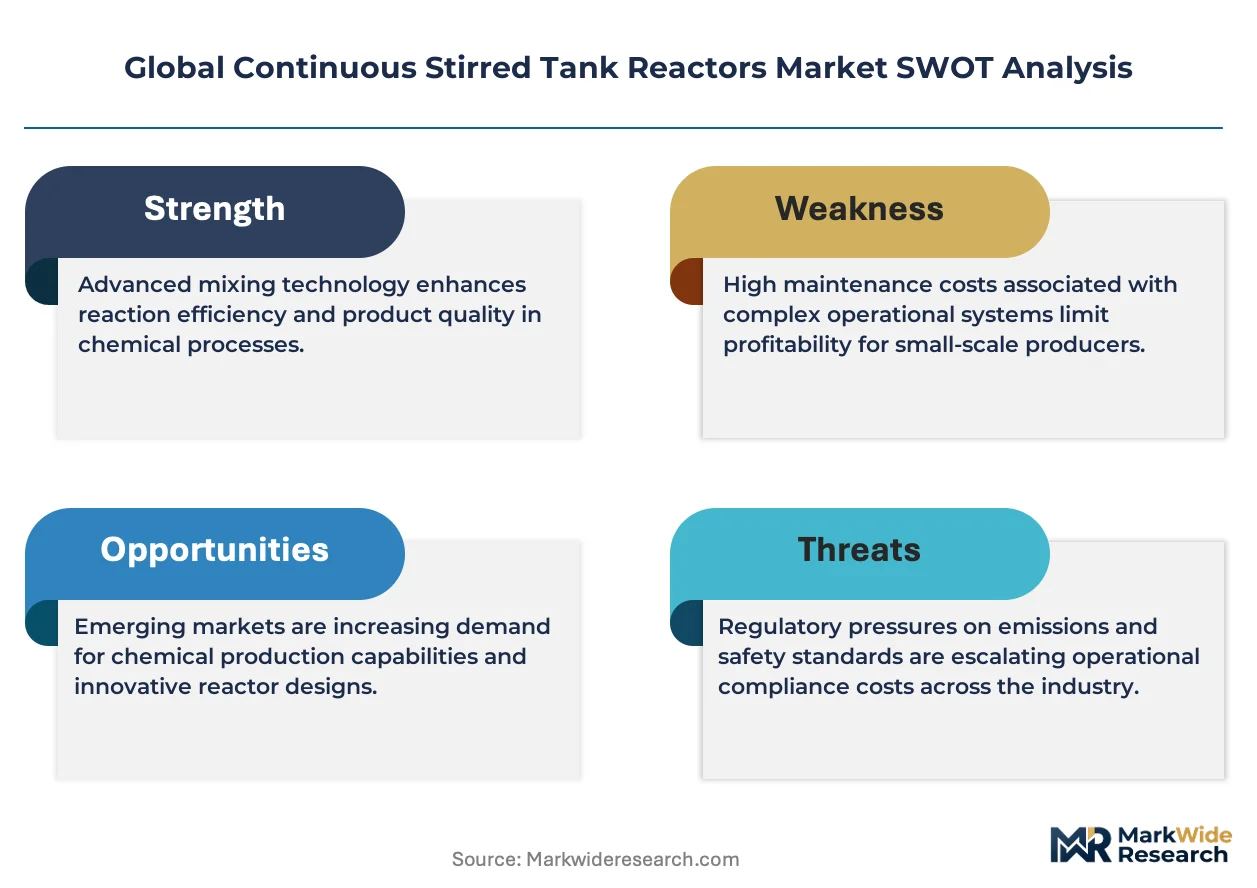
Magnetically driven agitation systems are compressing the addressable market for mechanically sealed reactors by eliminating contamination pathways in sterile synthesis environments. Specialty chemical producers in Germany and pharmaceutical manufacturers in the United States are accelerating this substitution as regulatory scrutiny intensifies on fugitive emissions from dynamic seals.
Growth Catalysts
- REACH material mandates:ECHA's evolving substance restrictions are compelling European processors to upgrade legacy carbon-steel vessels toward corrosion-resistant alloys, sustaining replacement demand across Rhine-Ruhr chemical parks.
- China's coastal petrochemical buildout:Integrated refinery-chemical complexes around Ningbo and Shanghai are procuring jacketed CSTR trains at accelerated cadences to capture olefins derivatives margins.
- Bioprocessing purity requirements:Cell culture media and active pharmaceutical ingredient manufacturers are specifying magnetically driven units to satisfy FDA sterility guidance on seal-less containment.
Market Restraints
- Nickel and molybdenum price volatility:Hastelloy and Inconel alloy feedstock costs swing with London Metal Exchange pricing, compressing fabricator margins on corrosion-resistant reactor quotations.
- Specialized vessel fabricator concentration:Premium alloy reactor construction concentrates among a handful of certified pressure vessel shops in Germany, Japan, and the United States, creating procurement bottlenecks during capacity crunches.
- Mechanical seal reliability thresholds:Legacy mechanically agitated units remain technically adequate for non-sterile commodity chemical production, slowing replacement cycles in cost-sensitive segments.
Strategic Opportunities
- Modular skid-mounted reactor systems:Prefabricated CSTR trains with integrated controls are enabling faster deployment timelines for specialty chemical startups in India and Southeast Asia.
- EU Green Deal carbon accounting:The EU's carbon border adjustment mechanism creates preferential positioning for European fabricators sourcing low-carbon alloy feedstocks, rewarding early supply chain decarbonization investments.
- Continuous manufacturing transition:Pharmaceutical batch-to-continuous conversion programs at FDA-regulated facilities are specifying dedicated CSTR lines for real-time release testing integration.
Industry Challenges
- ASME and PED certification timelines:Pressure vessel code compliance documentation stretches project delivery schedules, particularly for novel alloy formulations lacking established welding procedure qualifications.
- Legacy DCS integration complexity:Retrofitting magnetically driven CSTRs into existing distributed control architectures requires custom I/O mapping and vendor-specific communication protocol bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Stirred Tank Reactors Market |
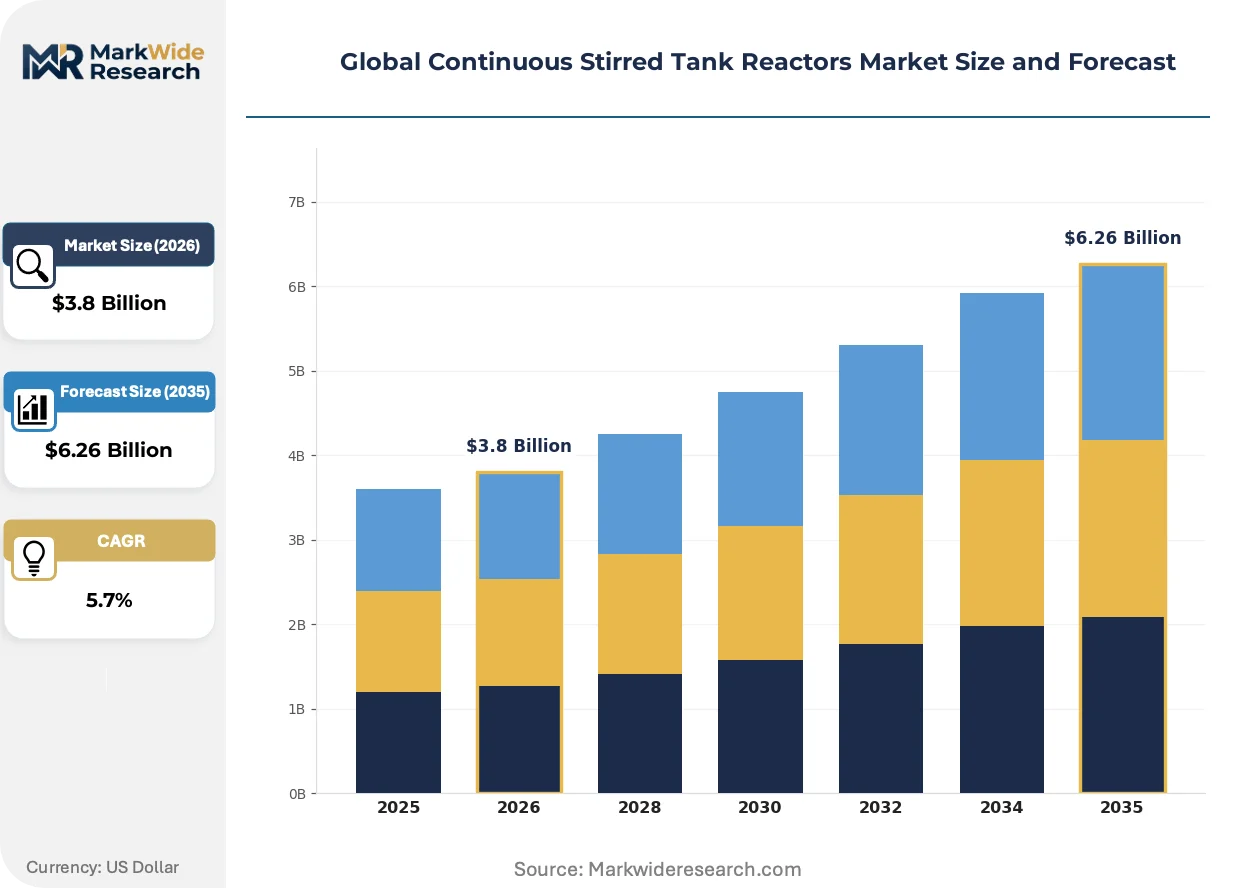
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jacketed Reactors, Agitated Tanks, Enclosed Vessels, Glass-Lined Reactors, Portable Reactors Technology: Magnetically Driven, Mechanically Agitated, Hydraulic, Pneumatic, Electrically Operated Application: Chemical Synthesis, Bioprocessing, Food Processing, Petrochemical Production, Waste Treatment End User Industry: Pharmaceutical Manufacturers, Biotechnology Firms, Food & Beverage Producers, Specialty Chemical Makers, Environmental Agencies |
| Companies Covered | Vapourtec, Thermo Fisher Scientific, Amar Equipment Pvt Ltd, Parr Instrument Company, IKA Works, Armfield Limited, Erich Stallkamp ESTA GmbH, UD Technologies, Nano-Mag Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Stirred Tank Reactors Market Strategic Shifts & Innovations
Digital twin implementations are compressing reactor commissioning timelines by enabling virtual validation of thermal and mixing performance before physical installation. Fabricators are embedding sensor arrays directly into vessel walls to feed real-time operational data back to predictive maintenance platforms.
Modular, containerized CSTR skids are decentralizing reactor deployment economics by eliminating field fabrication requirements and reducing site civil works. Mid-volume chemical processors in India and Brazil are adopting these plug-and-play configurations to bypass lengthy pressure vessel permitting cycles. The shift is compressing traditional project timelines from eighteen months to under six months for standardized unit operations.
EPA enforcement of Clean Air Act leak detection and repair provisions is tightening permissible emissions thresholds from mechanical pump and agitator seals. Process industries in Texas and Louisiana are responding by specifying magnetically driven alternatives for volatile organic compound service. The regulatory pressure is accelerating retirement of legacy mechanically sealed reactors ahead of their technical end-of-life.
Equipment-as-a-service contracting is restructuring capital deployment patterns among specialty chemical manufacturers. Reactor vendors are retaining ownership and charging per-batch processing fees, transferring operational risk and maintenance burden from cash-constrained processors. This model is gaining traction in European chemical parks where balance sheet optimization outweighs traditional capex preference.
Global Continuous Stirred Tank Reactors Market Segmentation
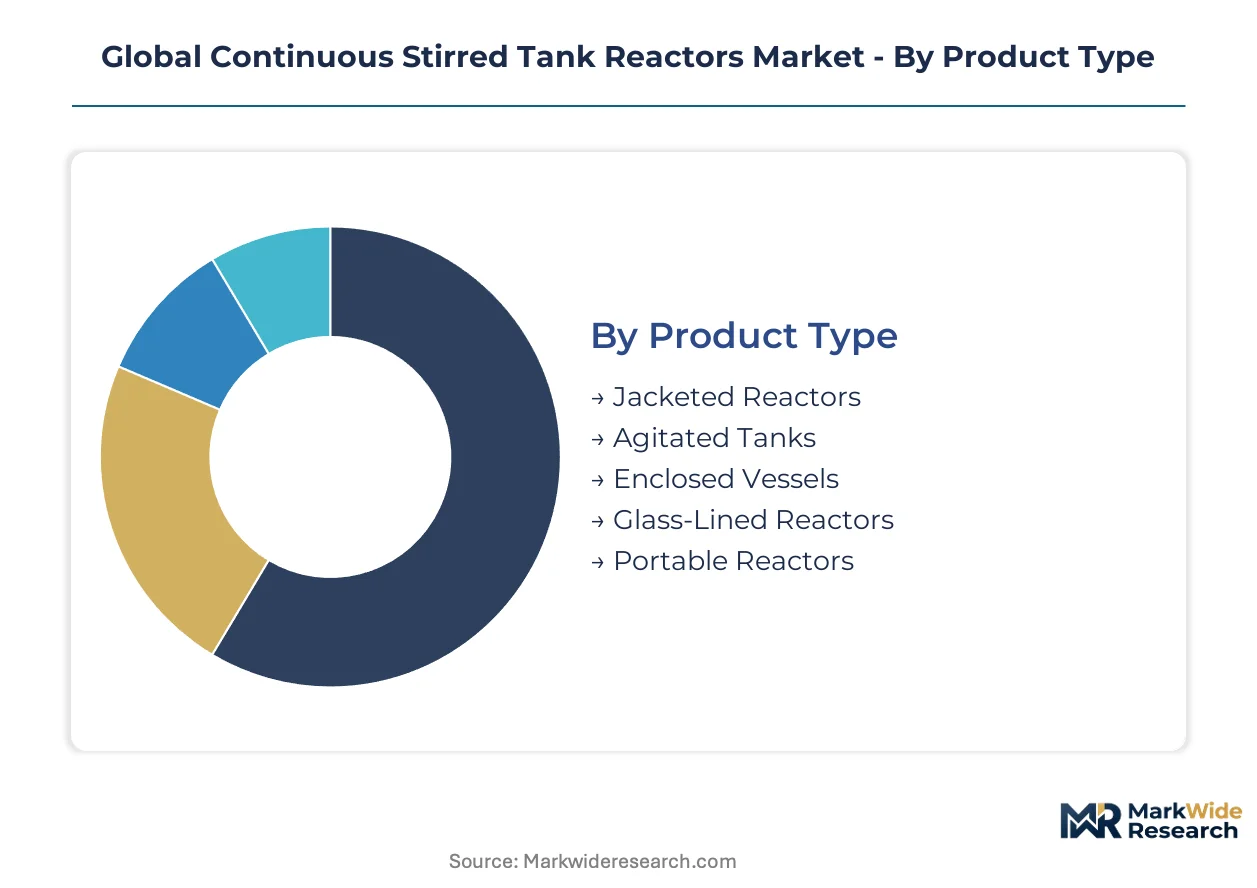
CSTR procurement patterns diverge sharply between standardized commodity vessels and engineered-to-order systems for sterile applications. Fabricators align production capacity across these segments based on alloy certification timelines and pressure vessel code complexity.
Product Type:
Standardization dominates at the commodity end with carbon-steel jacketed designs, while corrosion-resistant alloys and glass-lined constructions command premium engineering cycles and extended delivery schedules.
- Jacketed Reactors:Double-walled vessels with thermal fluid circulation enable precise temperature control across exothermic reactions. Rhine-Ruhr specialty chemical makers specify Hastelloy-clad jackets to satisfy REACH substance restrictions on process equipment corrosion resistance.
- Glass-Lined Reactors:Borosilicate-coated steel construction delivers absolute product purity for active pharmaceutical ingredient synthesis. FDA-regulated facilities in the United States specify these units despite capital cost premiums that exceed alloy alternatives.
- Agitated Tanks:Open or partially sealed vessels serve non-sterile commodity chemical blending where atmospheric pressure operation suffices.
- Enclosed Vessels:Fully sealed pressure-rated designs contain volatile organic compound emissions under EPA Clean Air Act leak detection mandates.
- Portable Reactors:Skid-mounted configurations with integrated controls reduce deployment timelines for mid-volume processors in India and Southeast Asia.
Leading the category by volume: Jacketed Reactors. Expanding most quickly: Portable Reactors.
Technology:
Cost tiers separate seal-less magnetic drives from mechanically sealed alternatives, with pneumatic and hydraulic systems occupying intermediate positions based on torque requirements and maintenance accessibility.
- Magnetically Driven:Coupling transmits torque through containment shell, eliminating dynamic seals and contamination pathways. China's MEE effluent enforcement accelerates replacement of legacy mechanical units with sealed magnetic systems in coastal chemical clusters.
- Mechanically Agitated:Direct shaft penetration with packed or mechanical seals remains technically adequate for non-sterile commodity production. Nickel price volatility on the London Metal Exchange compresses fabricator margins when specifying corrosion-resistant alloys for these units.
- Hydraulic:Fluid power transmission delivers high torque density for viscous polymerization media.
- Pneumatic:Compressed air drives suit explosion-risk environments where electrical spark containment is mandatory.
- Electrically Operated:Variable frequency motor control enables precise speed modulation for shear-sensitive bioprocessing applications.
Mechanically Agitated systems retain installed base dominance. Magnetically Driven configurations gain share fastest in pharmaceutical and fine chemical specifications.
Application:
Volume scale differentiates continuous petrochemical trains from batch bioprocessing installations, with margin concentration favoring sterile synthesis over commodity chemical production.
- Chemical Synthesis:Fine chemical and specialty intermediate production demands precise stoichiometric control. Germany's ECHA material mandates compel upgrades from carbon-steel to alloy construction across legacy Rhine-Ruhr installations.
- Bioprocessing:Cell culture media and recombinant protein production requires absolute sterility assurance. FDA guidance on seal-less containment drives magnetic drive specification for new capacity additions.
- Food Processing:Edible oil hydrogenation and fermentation operations require sanitary-grade surface finishes.
- Petrochemical Production:Olefins derivative synthesis operates at scale in integrated refinery-chemical complexes.
- Waste Treatment:Hazardous effluent neutralization and advanced oxidation processes deploy corrosion-resistant vessel specifications.
Petrochemical Production commands greatest unit volume. Bioprocessing delivers steepest expansion trajectory on cell therapy manufacturing buildouts.
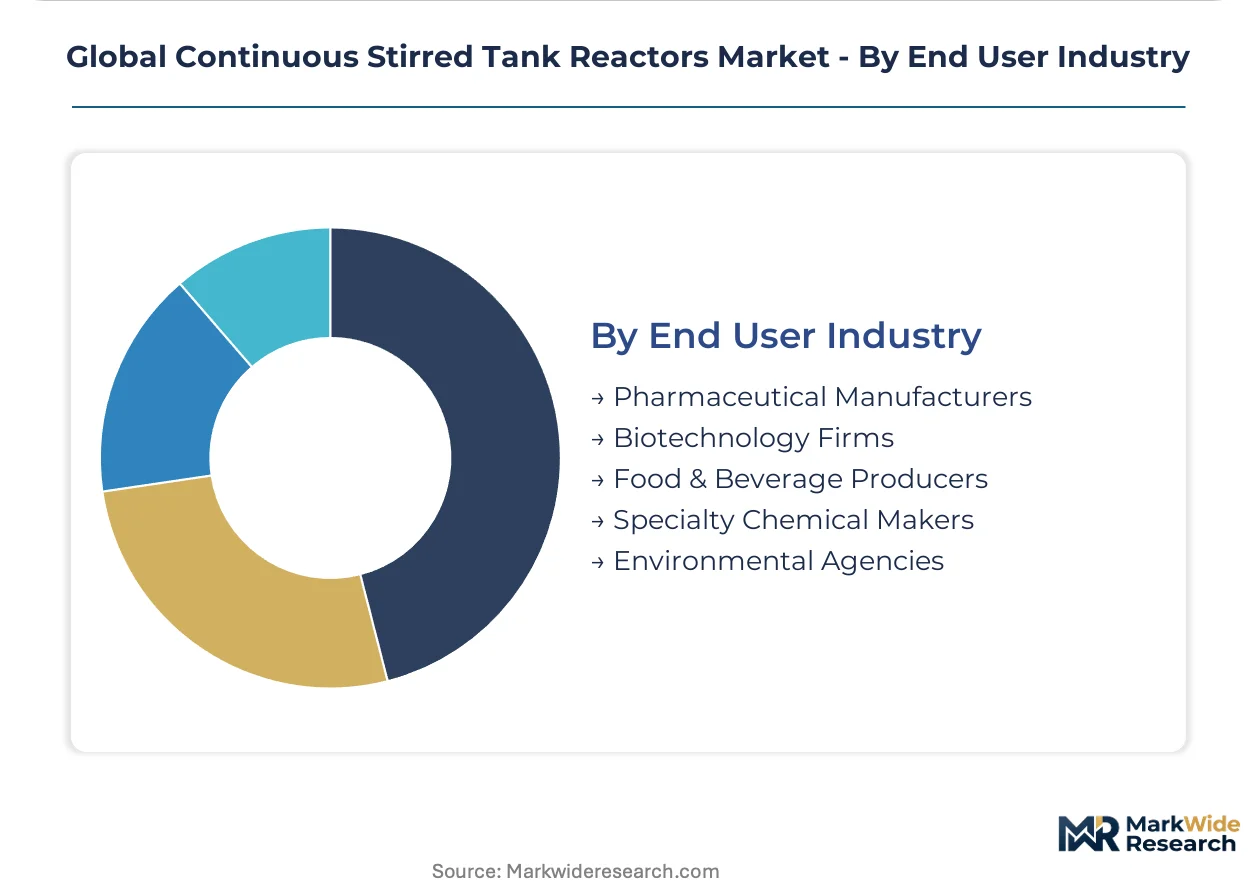
End User Industry:
Customer type determines procurement sophistication, with pharmaceutical manufacturers demanding extensive documentation and environmental agencies prioritizing capital efficiency over performance optimization.
- Pharmaceutical Manufacturers:Batch-to-continuous conversion programs specify dedicated CSTR lines for real-time release testing integration. FDA sterility guidance mandates seal-less magnetic drive technology for new active pharmaceutical ingredient capacity.
- Specialty Chemical Makers:Fine chemical producers in Germany and the United States scale jacketed reactor deployments for complex multi-step synthesis. REACH compliance tightens vessel material specifications and agitation efficiency thresholds across European chemical parks.
- Biotechnology Firms:Cell and gene therapy developers procure small-scale magnetically driven units for clinical manufacturing.
- Food & Beverage Producers:Fermentation and processing operations specify sanitary-grade surface finishes and clean-in-place compatibility.
- Environmental Agencies:Municipal and industrial wastewater treatment procurement emphasizes capital efficiency and operational simplicity.
Specialty Chemical Makers generate largest order volume. Biotechnology Firms represent the fastest-climbing customer segment on cell therapy capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo and Shanghai anchor the world's most intensive CSTR procurement activity, with integrated refinery-chemical complexes driving olefins derivative capacity expansion along China's eastern seaboard.
United States
Specialty chemical makers in Texas and Louisiana scale jacketed reactor deployments for fine chemical production. EPA Clean Air Act enforcement tightens permissible emissions thresholds from mechanical seals, accelerating magnetically driven system specifications. The Gulf Coast petrochemical corridor concentrates procurement for olefins and derivatives synthesis.
Germany
Rhine-Ruhr chemical parks sustain replacement demand as ECHA REACH mandates compel upgrades from legacy carbon-steel vessels toward corrosion-resistant alloys. The EU Green Deal drives material substitution toward lower-carbon alloy formulations across European chemical parks. Bavarian and North Rhine-Westphalian fabricators face procurement bottlenecks during capacity crunches.
China
Coastal chemical clusters around Shanghai and Ningbo accelerate reactor procurement cycles to capture petrochemical expansion margins. MEE enforces stricter effluent thresholds that accelerate replacement of legacy mechanically agitated units with sealed magnetically driven systems. Yangtze River Delta processors dominate volume demand for jacketed CSTR trains.
India
Mid-volume chemical processors in Gujarat and Maharashtra adopt modular skid-mounted reactor systems to bypass lengthy pressure vessel permitting cycles. BIS certification requirements shape vessel material specifications for domestic fabricators. Mumbai-Pune industrial corridor concentrates specialty chemical startup activity driving plug-and-play configuration demand.
Japan
Premium alloy reactor construction concentrates among certified pressure vessel shops serving pharmaceutical and fine chemical manufacturers. METI industrial policy supports continuous manufacturing transition programs at regulated facilities. Osaka-Kobe chemical belt maintains demand for high-pressure reactor designs in research and pilot-scale operations.
Global Continuous Stirred Tank Reactors Market Key Industry Players
Premium-margin players sit above commodity-margin players across alloy certification and pressure vessel code complexity. The vendor base stratifies between standardized carbon-steel jacketed fabricators and engineered-to-order specialists serving sterile applications. Three archetypes dominate: magnetically driven technology specialists, high-pressure research reactor designers, and cost-optimized electrically operated unit suppliers. Competitive moves concentrate on modular skid system development and supply chain decarbonization positioning for EU carbon border adjustment mechanisms.
Among scientific instrumentation conglomerates, Thermo Fisher Scientific exemplifies premium-tier positioning through magnetically driven technology portfolios. Parr Instrument Company anchors North American demand through specialized high-pressure designs. Nano-Mag Technologies occupies the cost-optimized tier competing aggressively in Asia for mid-volume chemical processors.
| Leading Market Players |
|---|
| Vapourtec |
| Thermo Fisher Scientific |
| Amar Equipment Pvt Ltd |
| Parr Instrument Company |
| IKA Works |
| Armfield Limited |
| Erich Stallkamp ESTA GmbH |
| UD Technologies |
| Nano-Mag Technologies |
| Others |
Cost & Logistics Intelligence
Certified pressure vessel welders concentrated in Germany's North Rhine-Westphalia and Japan's Osaka-Kobe corridor command wage premiums that widen spreads between premium alloy and commodity carbon-steel reactor tiers. Labor-cost differentials between these fabrication hubs and emerging Asian shops compress margins on standardized jacketed units while sustaining premium positioning for REACH-compliant corrosion-resistant systems.
Pricing Analysis
Value-based pricing anchored to batch yield assurance and sterility compliance separates pharmaceutical-grade magnetically driven systems from commodity mechanically agitated alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by alloy certification grade and pressure vessel code complexity. Cost compression in carbon-steel segments intensifies because nickel and molybdenum volatility on the London Metal Exchange squeezes fabricator margins. Specialty chemical makers in Germany exhibit lowest price sensitivity due to REACH-mandated replacement cycles, while mid-volume processors in India prioritize capital efficiency over performance optimization.
Supply Chain Analysis
India's phased manufacturing program and domestic-content mandates for public-sector chemical projects are reshaping sourcing patterns toward certified local fabricators. Premium alloy reactor construction concentrates in Germany, Japan, and the United States, drawing from Hastelloy and Inconel feedstocks sourced through concentrated metallurgical suppliers. Single-source vulnerability in certified pressure vessel shops creates procurement bottlenecks during capacity crunches. Distribution runs through direct OEM relationships for engineered-to-order systems and regional distributors for standardized commodity vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Continuous Stirred Tank Reactors Market sits in a technology-transition phase as magnetically driven agitation systems displace mechanically sealed legacy units across sterile synthesis applications. This substitution wave rewards early movers who align certification portfolios with tightening FDA and EMA containment guidance.
For Market Incumbents: Cement alloy certification leadership by securing ASME and PED welding procedure qualifications for novel low-carbon formulations ahead of EU carbon border adjustment implementation. Expand captive heat-treatment capacity in Germany to bypass bottlenecks at third-party metallurgical service providers. Threat of modular skid-mounted entrants from India demands faster delivery timeline compression through prefabrication investments.
For New Entrants and Emerging Players: Begin with containerized plug-and-play configurations targeting mid-volume chemical processors in Gujarat and Maharashtra seeking to bypass BIS certification delays. White-space concentrates in electrically operated units for shear-sensitive bioprocessing where Nano-Mag Technologies has established cost-optimized positioning. Go-to-market leverage rests on equipment-as-a-service contracting to transfer operational risk from cash-constrained specialty chemical startups.
For Investors and Strategic Acquirers: The window for entry favors magnetically driven technology specialists with established FDA master file documentation and sterile manufacturing reference sites. Long-term viability hinges on supply chain decarbonization positioning for EU Green Deal carbon accounting. Signal to watch is acceleration of pharmaceutical batch-to-continuous conversion programs at FDA-regulated facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Feedstock | Captive sourcing of low-carbon Hastelloy secures margin protection against London Metal Exchange volatility. |
| Modular Skid System Development | Prefabricated CSTR trains compress deployment timelines from eighteen months to under six months for Indian processors. |
| Magnetic Drive Technology Licensing | Seal-less containment patents enable premium positioning in FDA-regulated bioprocessing capacity expansions. |
| EU Green Deal Certification Investment | Early supply chain decarbonization creates preferential positioning under carbon border adjustment mechanisms. |
| Equipment-as-a-Service Transition | Per-batch processing fees transfer maintenance burden and optimize balance sheets for European chemical parks. |
Research Approach
Document review covered customs and trade data, SEC 10-K filings from scientific instrumentation conglomerates, and pressure vessel code certification databases, complemented by interviews with plant engineers at specialty chemical facilities, procurement leads at pharmaceutical manufacturers, aftermarket service heads at reactor OEMs, and technical R&D directors at alloy suppliers. Secondary validation drew from ECHA substance restriction updates, EPA Clean Air Act enforcement records, and MEE effluent threshold notifications. Bottom-up unit shipment estimates triangulated against top-down value projections.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, technology configuration, application severity, and end-user industry procurement sophistication. The analytical framework incorporated alloy grade tier, pressure rating class, and regional regulatory cluster as cross-cutting dimensions. CAGRs emerged from regression against historical replacement cycle data and announced capacity expansion timelines. Forecast inputs included announced petrochemical buildouts in China's Yangtze River Delta and pharmaceutical continuous manufacturing transition programs.
Commodity nickel price swings, unexpected revisions to REACH substance restrictions, and delays in ASME welding procedure qualifications for novel alloys are the dominant revision risks to modeled projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Hydro Fluorocarbon Market