
 Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market | 2026-2036
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market Insights
The specialty chemical distributor network serving battery electrolyte formulators is rewriting procurement geography across Northeast Asia. Arkema leverages its fluorochemistry heritage to sustain European supply lines for high-grade LiFSI precursors. Do-Fluoride New Materials anchors Chinese domestic capacity through integrated fluorosulfonyl production. Syensqo differentiates via polymer-grade purity protocols originally developed for lithium-ion separator films.
Ultra-high-purity lithium bis(fluorosulfonyl)imide denotes a lithium salt with fluorosulfonyl imide anions, typically synthesized through fluorination of sulfamic acid derivatives followed by lithium exchange, achieving moisture content below 10 ppm and chloride impurities under 5 ppm to prevent electrolyte degradation in high-voltage cells. Its primary commercial purpose centers on replacing or supplementing LiPF6 in lithium-ion batteries to enhance thermal stability, widen electrochemical windows, and suppress aluminum current collector corrosion. Anhydrous LiFSI commands the dominant value share due to stringent moisture requirements in cylindrical and prismatic EV cells, while solid-state LiFSI formulations represent the fastest-growing product type as sulfide and oxide solid electrolyte developers seek compatible lithium salts. Among end user industries, electric vehicle assemblers concentrate the largest margin pools because cell-grade LiFSI qualification cycles extend 18-36 months and lock in supplier relationships.
China's SAMR enforces GB standards for battery-grade lithium salt purity that exceed legacy industrial chemical specifications, while the EU's REACH and RoHS frameworks restrict residual heavy metals in electrolyte salts destined for European cell plants. Japan's METI coordinates with JIS standards bodies to align domestic LiFSI testing protocols with next-generation solid-state battery roadmaps. Stakeholders must monitor how divergent purity certification regimes between Asian and European markets reshape toll manufacturing and regional warehouse strategies.
Market Dynamics
Chinese cell manufacturers are forcing qualification timelines to compress as they dual-source LiFSI to de-risk LiPF6 dependency, creating a structural squeeze on precursor supply chains.
Growth Catalysts
- High-voltage cathode chemistry:Nickel-rich layered oxides above 4.3V operating windows require LiFSI's electrochemical stability to suppress aluminum corrosion at current collectors. EV battery pack designers in Jiangsu province specify this salt for 800V architectures.
- REACH and RoHS frameworks:European cell plants face heavy metal residual limits that LiFSI satisfies more cleanly than phosphate alternatives, redirecting electrolyte formulation contracts toward qualified ultra-high-purity suppliers.
- Solid-state battery roadmaps:Sulfide and oxide ceramic electrolyte developers need anhydrous lithium salts with matching moisture specifications, positioning LiFSI as the bridge chemistry for pilot production lines.
Market Restraints
- Fluorosulfonyl chloride feedstock volatility:Integrated fluorspar-to-fluorochemical production concentrates in Henan and Inner Mongolia, exposing non-integrated formulators to input cost swings when mining quotas tighten.
- Moisture specification rigidity:Sub-10 ppm H2O certification requires glovebox lithiation and vacuum drying infrastructure that smaller toll manufacturers cannot amortize across low volumes.
- LiPF6 incumbent lock-in:Existing electrolyte blending assets and 18-36 month cell qualification cycles create switching friction even where LiFSI performance advantages are demonstrated.
Strategic Opportunities
- South Korean cathode integration:Posco Chemical and LG Chem are qualifying domestic LiFSI streams for their Pohang and Gumi facilities, opening a second Northeast Asian demand pole beyond Chinese provinces.
- Polymer-grade purity protocols:Separator film manufacturers require lithium salts with particulate controls below 100 nm, a specification overlap that electrolyte salt producers can exploit for margin expansion.
- Japan METI solid-state coordination:JIS standards alignment with 2030 battery roadmaps creates early-mover certification pathways for suppliers meeting oxide electrolyte compatibility benchmarks.
Industry Challenges
- Anhydrous handling expertise:glovebox operation and inert atmosphere logistics talent pools concentrate at legacy pharmaceutical fluorochemical sites, forcing electrolyte entrants to recruit from Merck KGaA and Daikin trained workforces.
- Qualification timeline compression:18-36 month cell-grade validation cycles conflict with Chinese EV assemblers' 12-month model refresh cadences, straining supplier R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market |
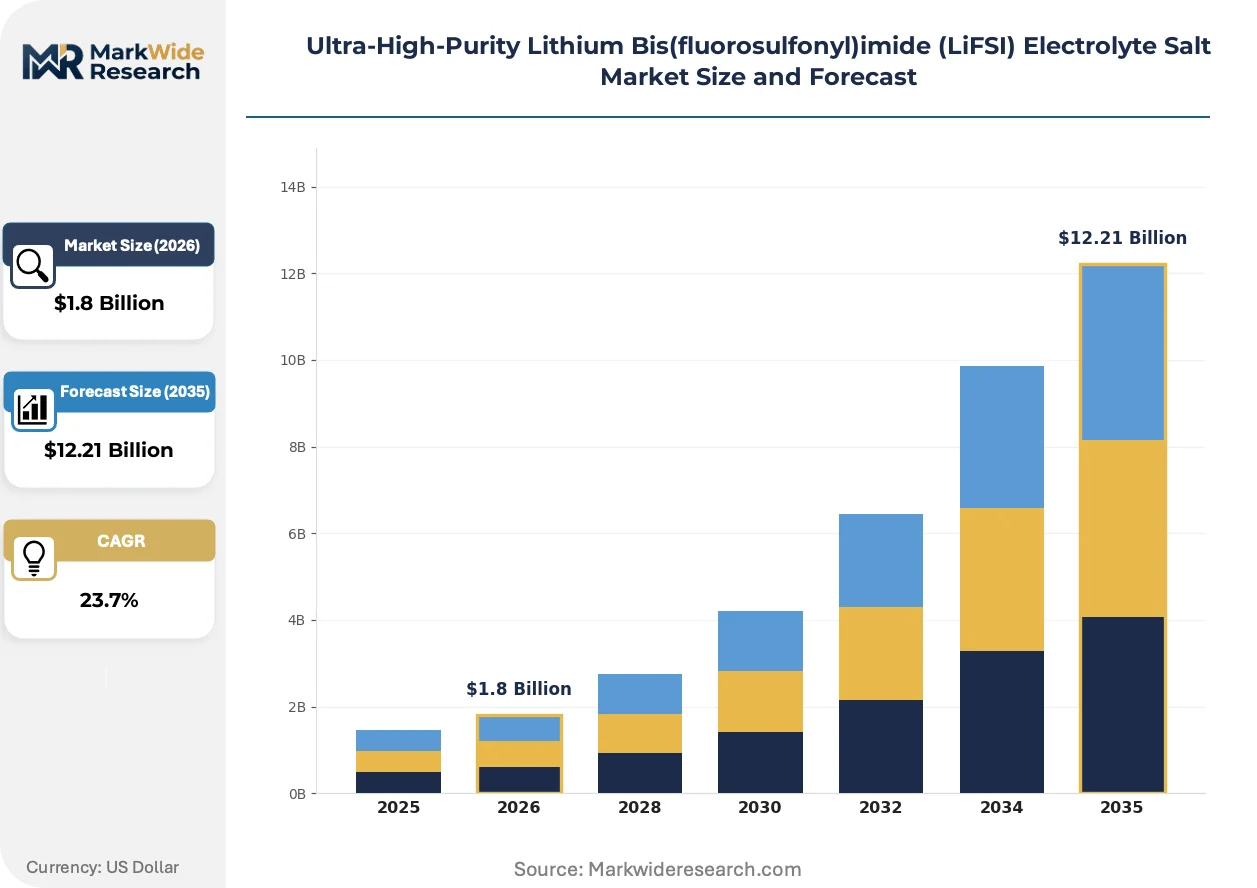
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous LiFSI, Hydrated LiFSI, Solid-State LiFSI, Mixed Salts, Custom Formulations Application: Lithium-Ion Batteries, Supercapacitors, Solid Electrolyte Interfaces, Electrochemical Devices, Industrial Electroplating End User Industry: Consumer Electronics Manufacturers, Electric Vehicle Assemblers, Aerospace Components, Energy Storage Solutions, Specialty Chemicals Companies Packaging Type: Drums, Bags, Bottles, Bulk Containers, Vacuum-Sealed Packs |
| Companies Covered | Arkema, Syensqo, Nippon Shokubai, Do-Fluoride New Materials, Shenzhen Capchem Technology, Tinci Materials, Guotai Huarong, Morita Chemical Industries, Central Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market Trends and Innovations
Process intensification and regulatory convergence are compressing the boundary between industrial fluorochemical production and battery-grade purification, reshaping where value accrues in the lithium salt supply chain.
Continuous flow fluorination is migrating from batch sulfamic acid derivatization toward modular reactor architectures that cut solvent use and lithium exchange losses. Korean electrolyte blenders at Ulsan industrial complexes pilot these systems to halve residence times while holding chloride impurities below 5 ppm. The technology is migrating from pharmaceutical fine-chemical heritage into dedicated battery salt plants, collapsing the historical separation between industrial and electronic-grade production tiers.
China's GB standards revision through SAMR tightens chloride and moisture specifications beyond legacy industrial chemical baselines, forcing domestic producers to retrofit drying trains and install online Karl Fischer monitoring. European cell plants importing Chinese LiFSI now demand dual certification against both GB and REACH protocols, adding documentation overhead but creating quality-based segmentation among export-oriented suppliers. The regulation most affects anhydrous product categories destined for cylindrical EV cells, where moisture excursions cause catastrophic gas generation.
Electrolyte formulators are consolidating their supplier base from six to two qualified LiFSI sources per plant, mirroring the concentration seen in cathode precursor purchasing. This behavior shift compresses switching options for cell makers but secures volume commitments that justify dedicated production lines. The pattern is most visible at CATL and BYD facilities in Fujian and Shenzhen, where procurement teams prioritize supply security over price arbitrage.
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market Segmentation
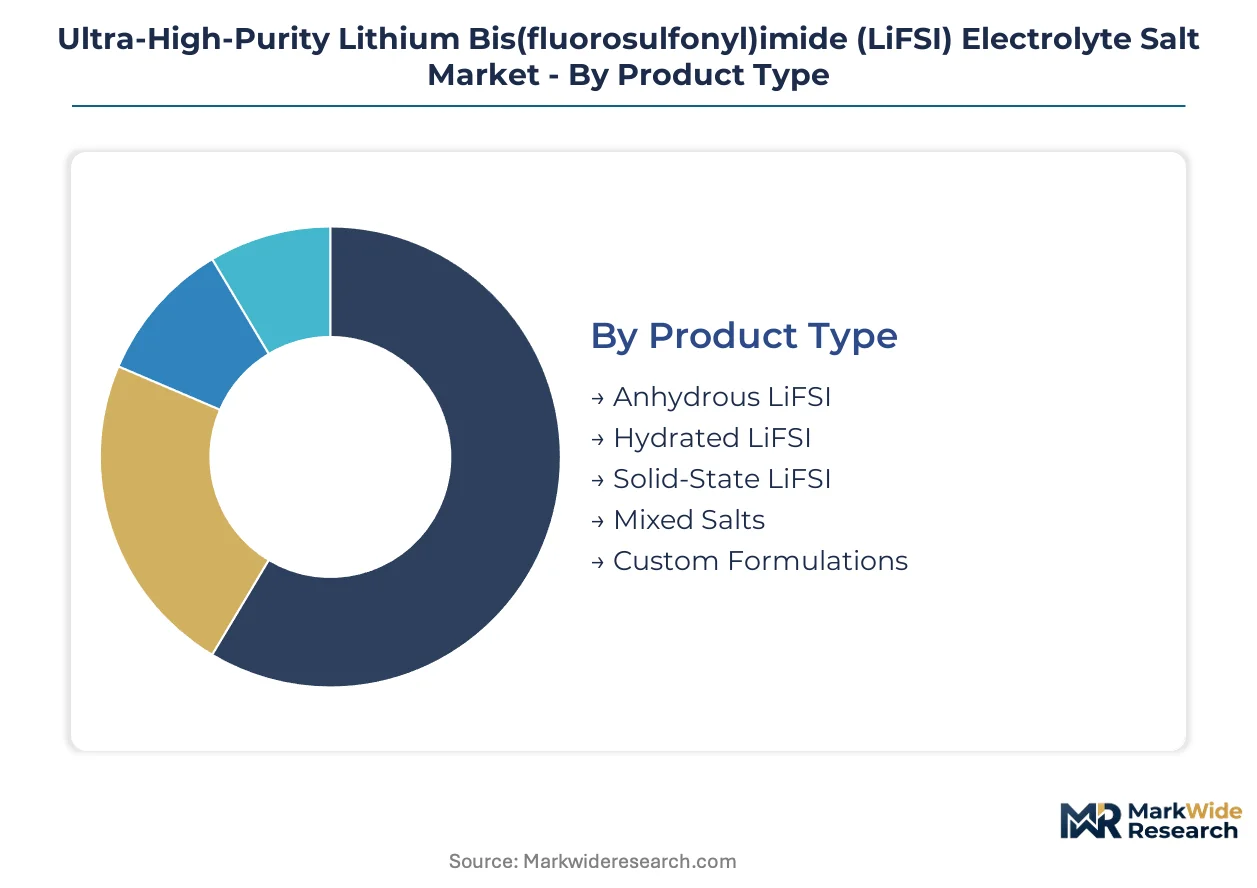
LiFSI procurement cycles vary dramatically across segment boundaries, with product qualification timelines stretching from months for industrial electroplating to years for electric vehicle cell certification. Understanding these velocity differentials helps suppliers align capacity investments with actual revenue recognition schedules.
Product Type:
Anhydrous grades turn inventory slowest due to glovebox handling requirements, while hydrated variants move fastest through toll manufacturing channels.
- Anhydrous LiFSI:Moisture content below 10 ppm specification demands vacuum drying trains and inert atmosphere packaging. Demand concentrates at CATL and BYD facilities in Fujian and Shenzhen, where procurement teams prioritize supply security over price arbitrage for cylindrical EV cell production.
- Solid-State LiFSI:Sulfide and oxide ceramic electrolyte developers require matching moisture specifications for pilot production lines. Samsung SDI and Toyota's solid-state programs in South Korea and Japan are qualifying these streams for 2030 roadmap alignment.
- Hydrated LiFSI:Relaxed moisture specifications suit supercapacitor and industrial applications with shorter qualification cycles.
- Mixed Salts:Blended formulations with LiPF6 or LiTFSI target transitional cathode chemistries.
- Custom Formulations:Particle size and chloride tuning for separator film manufacturers seeking sub-100 nm particulate controls.
Anhydrous LiFSI dominates installed base. Solid-state formulations are where expansion concentrates.
Application:
Margin tiers separate cell-grade qualification from industrial commodity sales, with electrochemical stability requirements dictating pricing power.
- Lithium-Ion Batteries:Nickel-rich layered oxides above 4.3V operating windows require electrochemical stability to suppress aluminum corrosion at current collectors. Jiangsu province EV battery pack designers specify this salt for 800V architectures.
- Solid Electrolyte Interfaces:Anhydrous lithium salts with matching moisture specifications bridge chemistry for sulfide and oxide ceramic electrolyte pilot lines. Japan's METI coordinates with JIS standards bodies to align domestic testing protocols.
- Supercapacitors:Moderate purity requirements and compressed procurement timelines.
- Electrochemical Devices:Medical and sensor applications with niche volume profiles.
- Industrial Electroplating:Lowest barrier to entry with minimal qualification overhead.
Lithium-ion batteries anchor revenue concentration. Solid electrolyte interfaces are climbing the fastest.
End User Industry:
Customer concentration patterns split between consolidated automotive assemblers and fragmented specialty chemical channels.
- Electric Vehicle Assemblers:Cell-grade LiFSI qualification cycles extend 18-36 months and lock in supplier relationships. Chinese manufacturers are forcing timelines to compress as they dual-source to de-risk LiPF6 dependency.
- Consumer Electronics Manufacturers:Cylindrical and prismatic cell demand from smartphone and laptop supply chains. Korean cathode integration at Posco Chemical and LG Chem facilities in Pohang and Gumi is opening a second Northeast Asian demand pole.
- Energy Storage Solutions:Grid-scale battery projects with emerging purity requirements.
- Aerospace Components:Satellite and aviation applications with extended certification protocols.
- Specialty Chemicals Companies:Distributor-mediated procurement with price-sensitive volume.
Electric vehicle assemblers command the largest margin pools. Consumer electronics manufacturers are gaining share fastest.
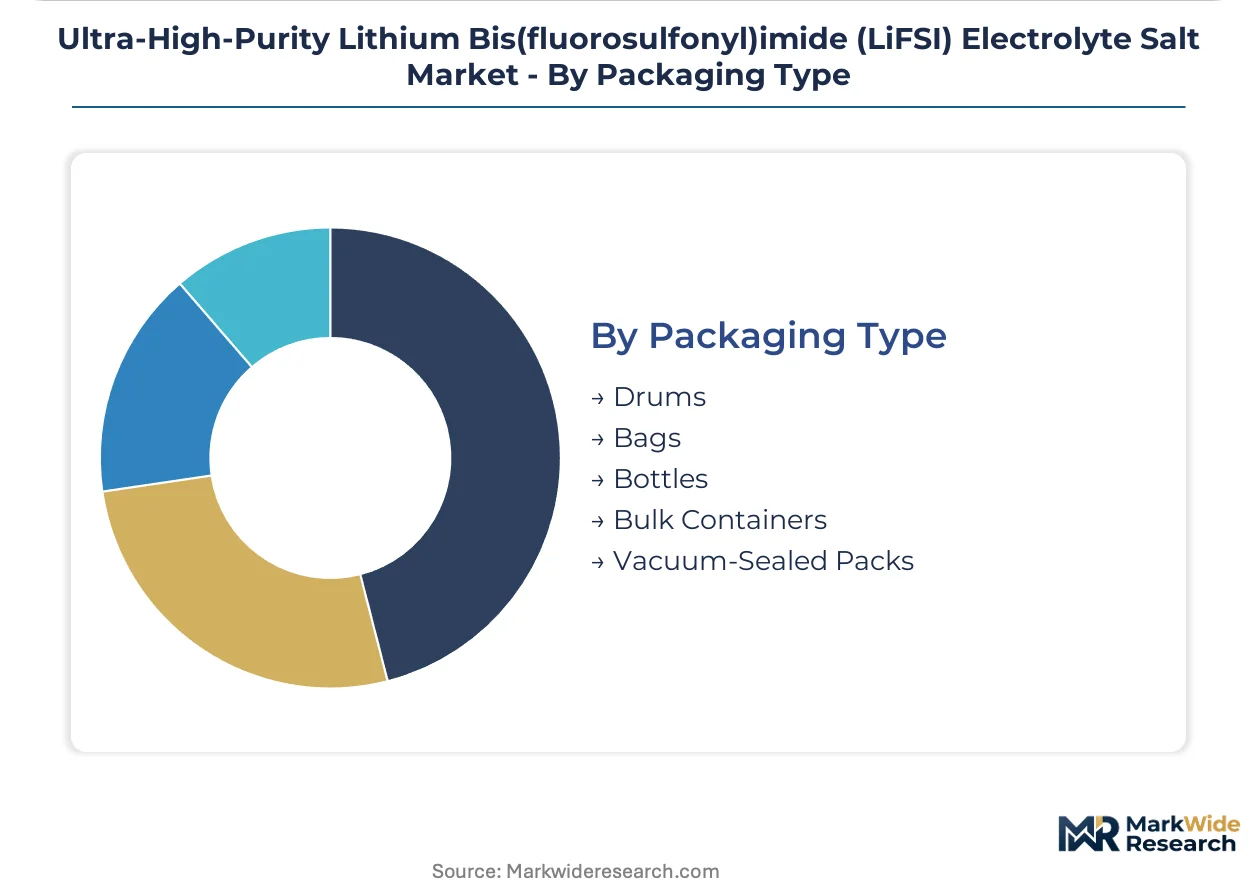
Packaging Type:
Handling infrastructure investments separate premium vacuum-sealed supply from commodity drum shipments.
- Vacuum-Sealed Packs:Sub-10 ppm H2O certification requires glovebox lithiation infrastructure that smaller toll manufacturers cannot amortize. European cell plants importing Chinese LiFSI now demand dual certification against both GB and REACH protocols.
- Bulk Containers:Integrated fluorspar-to-fluorochemical production concentrates in Henan and Inner Mongolia, exposing non-integrated formulators to input cost swings when mining quotas tighten.
- Drums:Standard industrial handling for hydrated grades and electroplating applications.
- Bags:Intermediate moisture protection for supercapacitor supply chains.
- Bottles:Laboratory and pilot-scale sampling formats.
Vacuum-sealed packs dominate high-value shipments. Bulk containers are where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in ultra-high-purity LiFSI tilts decisively toward Chinese producers, who leverage captive fluorosulfonyl chloride supply chains that European and Japanese competitors cannot replicate at scale. This asymmetry reshapes procurement geography across Northeast Asia.
China
Jiangsu and Zhejiang provinces concentrate cathode and electrolyte manufacturing clusters where CATL and BYD procurement teams dual-source LiFSI to de-risk LiPF6 dependency. SAMR enforces GB standards for battery-grade lithium salt purity that exceed legacy industrial specifications, forcing domestic producers to retrofit drying trains. Integrated fluorspar-to-fluorochemical production in Henan and Inner Mongolia anchors precursor supply security.
Japan
Solid-state battery roadmaps at Toyota and Samsung SDI drive qualification of anhydrous LiFSI streams for sulfide and oxide ceramic electrolyte pilot lines. METI coordinates with JIS standards bodies to align domestic testing protocols with 2030 battery targets. Kanto region chemical producers, particularly around Tokyo and Yokohama, supply these development programs with sub-10 ppm moisture certification.
South Korea
Posco Chemical and LG Chem facilities in Pohang and Gumi are qualifying domestic LiFSI streams, opening a second Northeast Asian demand pole beyond Chinese provinces. Korean electrolyte blenders at Ulsan industrial complexes pilot continuous flow fluorination systems to halve residence times. MFDS oversight aligns with JIS protocols for oxide electrolyte compatibility benchmarks.
Germany
European cell plants importing Chinese LiFSI demand dual certification against both GB and REACH protocols, adding documentation overhead but creating quality-based segmentation. ECHA restrictions on residual heavy metals redirect electrolyte formulation contracts toward qualified ultra-high-purity suppliers. BASF and other chemical conglomerates in Ludwigshafen evaluate toll manufacturing partnerships to bypass direct handling investments.
United States
Domestic battery manufacturing incentives under the IRA attract electrolyte formulators seeking to localize supply chains, though anhydrous handling expertise concentrates at legacy pharmaceutical fluorochemical sites. EPA oversight of fluorochemical emissions complicates greenfield LiFSI production. Michigan and Ohio EV assembly clusters create latent demand pending qualification timeline completion.
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with process chemistry advantages that resist commoditization. The vendor base concentrates around fluorochemical heritage players and battery-electrolyte specialists, creating a tiered structure where qualification lock-in matters more than unit cost. Three archetypes dominate: integrated fluorspar-to-salt producers, toll manufacturers with pharmaceutical-grade handling infrastructure, and electrolyte formulators backward-integrating into salt production. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as 18-36 month cell-grade validation cycles favor incumbent relationships over new entrant price competition.
Within the integrated production tier, Do-Fluoride New Materials and Guotai Huarong represent Chinese producers leveraging captive fluorosulfonyl supply chains. Arkema occupies a position among European heritage fluorochemical houses sustaining supply lines for high-grade precursors. Syensqo exemplifies polymer-grade purity protocols originally developed for lithium-ion separator films, now extended to electrolyte salt qualification. These three anchors illustrate how geographic concentration of fluorspar mining and fluorination expertise shapes competitive positioning.
| Leading Market Players |
|---|
| Arkema |
| Syensqo |
| Nippon Shokubai |
| Do-Fluoride New Materials |
| Shenzhen Capchem Technology |
| Tinci Materials |
| Guotai Huarong |
| Morita Chemical Industries |
| Central Glass |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor channels anhydrous LiFSI shipments where freight volatility amplifies price spreads between vacuum-sealed cell-grade material and commodity hydrated grades. Chinese producers leverage captive fluorosulfonyl chloride supply chains to compress delivered costs to European formulators, while non-integrated toll manufacturers absorb margin erosion from both feedstock volatility and certification overhead.
Pricing Analysis
The customization-premium spread separates configured-to-order anhydrous LiFSI from standard hydrated grades, with contract-based long-term offtake dominating procurement at CATL and BYD facilities. Price differentiation hinges on moisture certification tier and volume scale, where sub-10 ppm H2O specifications command substantial premia over industrial-grade alternatives. Cost compression in standard grades is intensifying because Chinese cell manufacturers compress qualification timelines to dual-source supply. Industrial electroplating buyers exhibit highest price sensitivity, while electric vehicle assemblers prioritize supply security over unit cost arbitrage.
Supply Chain Analysis
Fluorspar mining and fluorosulfonyl chloride synthesis anchor supply concentration in China, South Korea, and Japan, where integrated production draws from captive fluorspar reserves in Henan and Inner Mongolia. Raw material dependencies center on sulfamic acid derivatives, lithium carbonate, and specialized fluorination catalysts. Single-source vulnerability concentrates in fluorosulfonyl chloride feedstock, where mining quota tightening exposes non-integrated formulators to input cost swings. Distribution runs through specialty chemical distributors serving electrolyte formulators, with direct mill-to-plant shipments gaining share at qualified high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LiFSI market is recovering from qualification-cycle compression as electric vehicle assemblers accelerate dual-sourcing strategies to de-risk LiPF6 dependency.
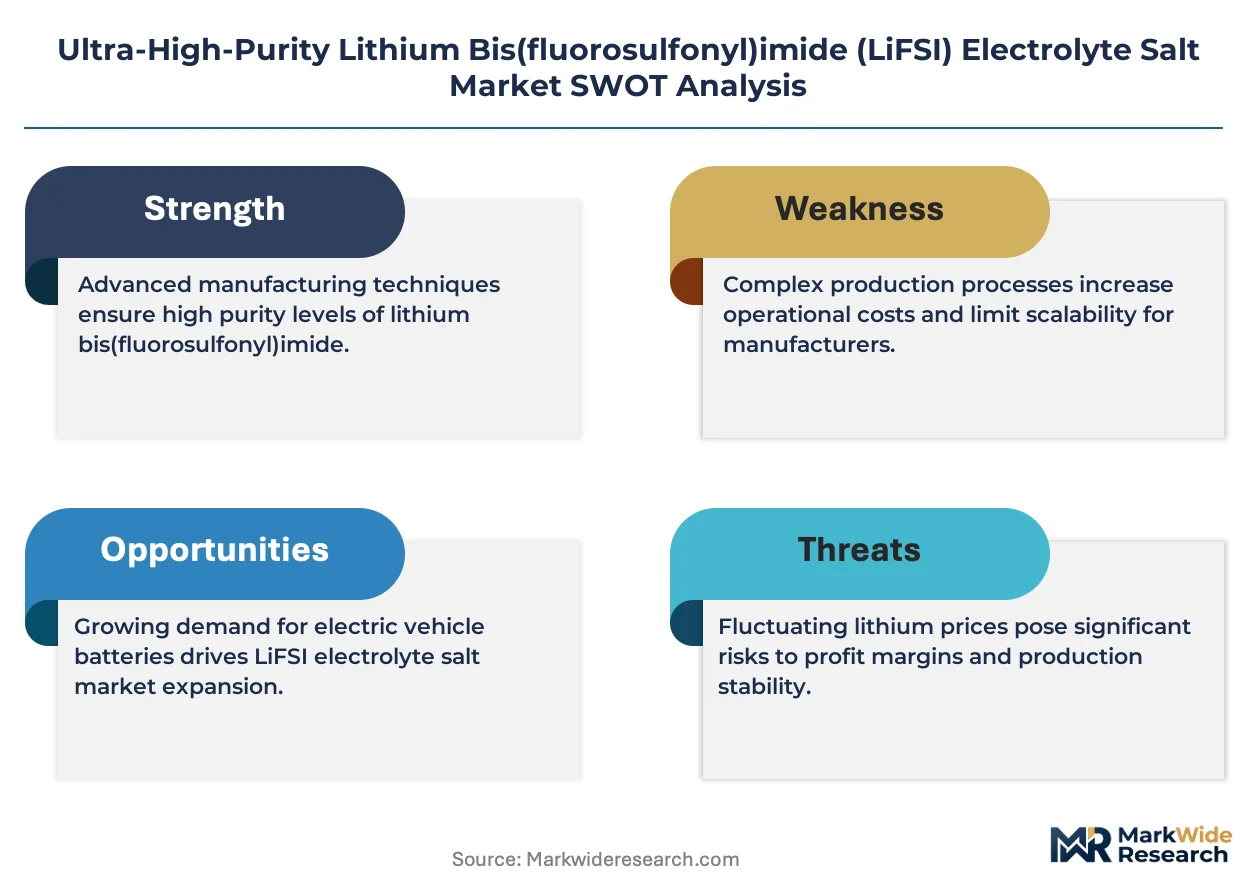
For Market Incumbents: Insulate margin position by deepening backward integration into fluorosulfonyl chloride production and securing SAMR certification ahead of GB standards revisions. The threat of toll manufacturers with pharmaceutical-grade handling infrastructure recruiting trained workforces from Merck KGaA and Daikin demands preemptive capacity addition in Jiangsu and Zhejiang provinces. For New Entrants and Emerging Players: Establish a beachhead in solid-state LiFSI formulations for sulfide and oxide ceramic electrolyte pilot lines, where qualification timelines remain elongated and incumbent relationships are less entrenched. The most penetrable white-space sits in polymer-grade purity protocols for separator film manufacturers seeking sub-100 nm particulate controls, with a go-to-market angle emphasizing JIS standards alignment for Japanese METI-coordinated development programs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant fluorochemical assets and legacy pharmaceutical-grade handling infrastructure. Long-term viability over the next decade rests on qualification lock-in rather than unit cost competition, with acquisition focus on toll manufacturers possessing glovebox lithiation and vacuum drying capabilities. The signal to watch is compression of cell-grade validation cycles below 18 months, which would erode incumbent relationship advantages and reprice strategic assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorosulfonyl Chloride | Captive feedstock supply from Henan and Inner Mongolia mining clusters secures margin control against quota volatility. |
| Continuous Flow Fluorination Scale-Up | Korean electrolyte blenders at Ulsan industrial complexes pilot modular reactor architectures that halve residence times. |
| Dual Certification Investment | European cell plants importing Chinese LiFSI demand GB and REACH protocol compliance to access qualified supplier status. |
| Polymer-Grade Purity Protocol Extension | Syensqo leverages separator film heritage to capture margin expansion from sub-100 nm particulate specifications. |
| Solid-State Electrolyte Partnership | Toyota and Samsung SDI qualification programs create early-mover pathways for oxide electrolyte compatibility benchmarks. |
Research Methodology
Desk research of customs and trade flow databases, SEC and domestic exchange filings from fluorochemical producers, and GB standards documentation preceded structured interviews with electrolyte formulator procurement leads, cathode plant technical directors, fluorochemical R&D heads, and specialty chemical distribution channel managers. Primary fieldwork validated capacity expansion announcements and qualification timeline compression trends, with bottom-up and top-down triangulation against trade volume aggregates and electrolyte blending capacity announcements.
Assumptions held fixed include SAMR enforcement of revised GB standards for battery-grade lithium salt purity and sustained IRA domestic manufacturing incentives in the United States, while variables included Chinese EV assemblers' dual-sourcing velocity and solid-state battery roadmap acceleration. The analytical framework modeled product type, end-use industry, packaging format, and regional production hub segmentation across the projection horizon. CAGRs derived from electrolyte salt demand elasticity against cathode chemistry evolution and qualification cycle compression rates, with fluorosulfonyl chloride feedstock availability and moisture specification rigidity as key forecast inputs.
Sensitivities concentrate around fluorosulfonyl chloride mining quota tightening, compression of cell-grade validation cycles below historical baselines, and divergence between Asian and European purity certification regimes. Forecasts reflect assumptions about sustained electric vehicle penetration and cathode chemistry evolution toward nickel-rich layered oxides. Cross-checking against customs export data from Chinese lithium salt producers and electrolyte formulator inventory disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
HFO (Hydrofluoro-Olefin) Refrigerants Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Chrome Plating Market