
 70MPa High Pressure Hydrogen Storage Cylinders Market | 2026-2036
70MPa High Pressure Hydrogen Storage Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
70MPa High Pressure Hydrogen Storage Cylinders Market Insights
Software-defined cylinder monitoring and predictive maintenance subscriptions is rebalancing how fleet operators contract hydrogen storage assets. Hexagon Purus leverages its integrated vehicle systems expertise to anchor long-term service agreements with transit agencies. Worthington Industries sustains manufacturing scale across North American automotive OEM supply chains. NPROXX specializes in ultra-lightweight carbon fiber winding configurations that dominate heavy-duty truck retrofit programs.
70MPa high pressure hydrogen storage cylinders are filament-wound or seamless pressure vessels engineered to contain hydrogen gas at 700 bar, utilizing carbon fiber-reinforced polymer liners or aluminum-lined composite structures to achieve weight-specific storage densities critical for mobile applications. These cylinders enable onboard fuel storage for fuel cell electric vehicles and buffer storage at dispensing infrastructure, where gravimetric efficiency directly determines vehicle range and payload capacity. Composite cylinders lead product type deployment due to superior mass efficiency, though steel and hybrid variants retain share in stationary storage solutions where weight sensitivity diminishes. Fuel cell vehicles represent the fastest-growing application segment, while hydrogen refueling stations command concentrated capital investment and margin capture.
ISO 19881, UN ECE R134, and Japan's High Pressure Gas Safety Act collectively establish burst-pressure ratios, permeation limits, and cycle-fatigue thresholds that manufacturers must satisfy for market access. The US DOT and EPA coordinate on hydrogen fuel system integrity standards that shape OEM procurement specifications and aftermarket retrofit eligibility. Stakeholders must monitor evolving harmonization between regional pressure equipment directives and emerging certification requirements for recycled carbon fiber content in cylinder production.
Market Dynamics
Carbon fiber supply concentration and filament-winding automation gaps are compressing manufacturing margins while fleet operators accelerate Type IV cylinder procurement for heavy-duty fuel cell deployments.
Growth Catalysts
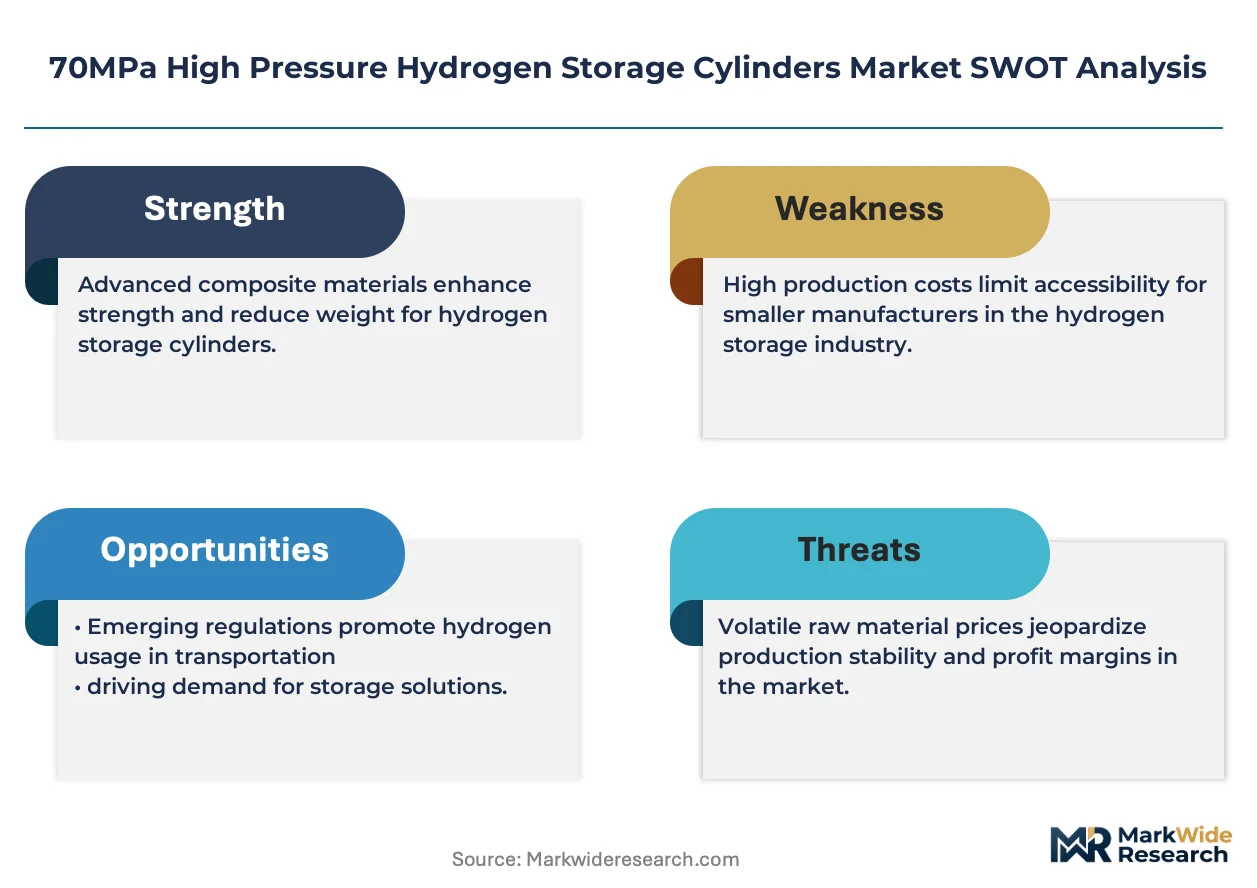
- California ZEV Mandates:The state's Advanced Clean Trucks regulation compels logistics fleets to convert diesel tractors to hydrogen powertrains, directly expanding 70MPa cylinder demand through 2035.
- ISO 19881 Harmonization:Unified burst-pressure and permeation testing protocols reduce certification duplication costs, enabling faster cross-border cylinder deployment.
- Heavy-Duty Truck Retrofit Programs:European freight operators are converting existing diesel chassis to fuel cell configurations, prioritizing lightweight composite storage over battery-electric alternatives for long-haul routes.
Market Restraints
- Toray-PAN Carbon Fiber Concentration:Japanese and Korean suppliers control aerospace-grade precursor supply, exposing cylinder manufacturers to input cost volatility and allocation rationing during demand surges.
- UN ECE R134 Certification Burden:Full vehicle-system homologation requires 18-24 month test cycles, freezing smaller cylinder vendors out of OEM supply chains.
- Liquid Hydrogen Competition:Cryogenic tank systems achieve superior volumetric density for stationary storage and maritime applications, constraining 70MPa cylinder addressable market in non-mobile segments.
Strategic Opportunities
- India National Hydrogen Mission:The country's PLI scheme for electrolyzer and fuel cell manufacturing creates first-mover advantage for cylinder suppliers establishing local filament-winding capacity.
- Software-Defined Monitoring Convergence:Integration of pressure sensors with predictive analytics platforms enables subscription-based asset management, shifting revenue from unit sales to lifecycle services.
- Germany Core Hydrogen Network:The SuedLink corridor and industrial cluster pipelines require distributed buffer storage, opening stationary 70MPa applications beyond transportation.
Industry Challenges
- Filament-Winding Technician Scarcity:Automated tow placement programming and composite NDT interpretation require specialized training pipelines that vocational institutions have not scaled.
- Recycled Carbon Fiber Certification:Emerging ISO standards for reclaimed fiber content in pressure vessels lack harmonized test protocols, delaying sustainable product line launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 70MPa High Pressure Hydrogen Storage Cylinders Market |
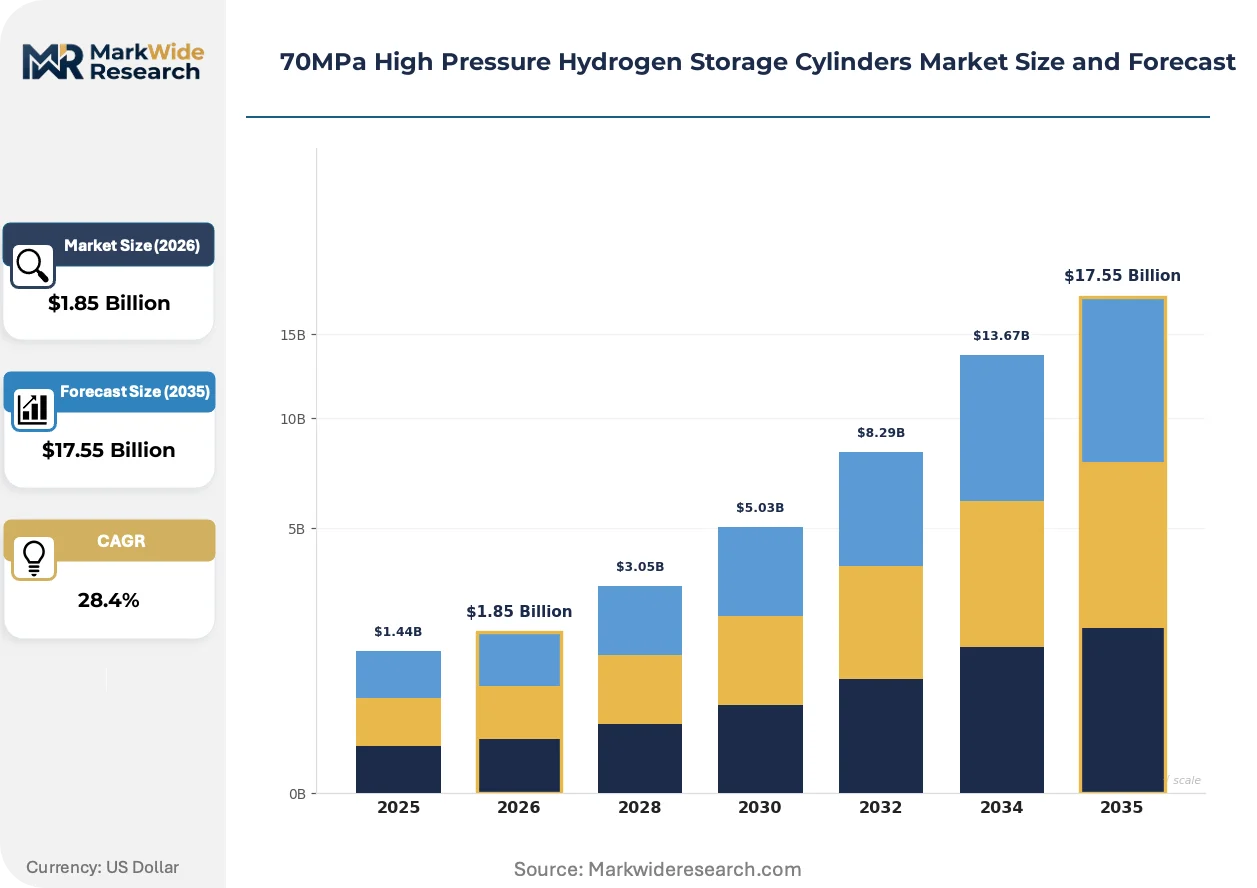
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $17.55 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Cylinders, Steel Cylinders, Aluminum Cylinders, Hybrid Cylinders End User: Automotive OEMs, Industrial Users, Research Institutions, Energy Providers Application: Fuel Cell Vehicles, Storage Solutions, High-Pressure Testing, Hydrogen Refueling Stations Material: Carbon Fiber, Aluminum Alloy, Steel Alloy, Others |
| Companies Covered | Hexagon Purus, Worthington Industries, Luxfer Group, NPROXX, Plastic Omnium, Linde plc, Air Products and Chemicals, Chart Industries, Faber Industrie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
70MPa High Pressure Hydrogen Storage Cylinders Market Trends and Innovations
Real-time structural health monitoring and automated manufacturing controls are compressing quality variance while extending certified service intervals for high-pressure composite vessels.
Embedded fiber-optic sensing arrays are unifying pressure, temperature, and strain measurement into continuous cylinder wall diagnostics. Transit agencies in Japan and Germany are mandating these systems for public bus fleets. The technology is unifying maintenance scheduling with actual structural degradation rather than fixed calendar intervals, reducing premature cylinder retirement.
Japan's METI hydrogen roadmap is tightening permeation limits for Type IV designs below 6 NmL/hr/L through revised High Pressure Gas Safety Act implementing rules. Cylinder manufacturers must redesign liner-barrier interfaces and validate new polymer formulations. Heavy-duty truck OEMs are responding by consolidating procurement around suppliers with in-house permeation testing laboratories.
Fleet operators are bundling cylinder assets into powertrain-as-a-service agreements rather than capital purchases. Logistics providers in California's San Joaquin Valley are leading this transition, contracting hydrogen storage through fuel suppliers who retain ownership and maintenance responsibility. The shift transfers residual value risk from fleet balance sheets to energy infrastructure investors.
70MPa High Pressure Hydrogen Storage Cylinders Market Segmentation
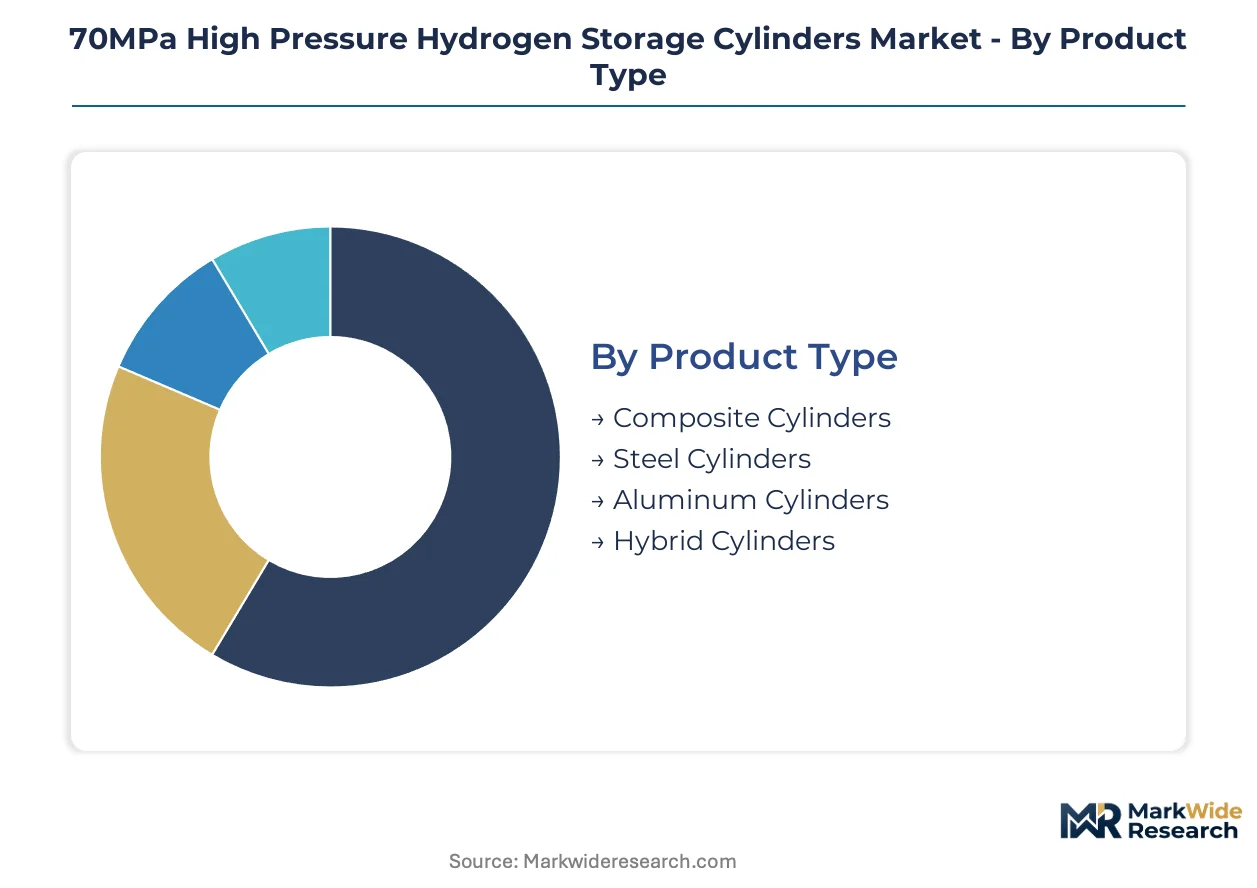
Segmentation in the 70MPa hydrogen cylinder market reveals how material science, application requirements, and procurement scale dictate manufacturing priorities. Each dimension exposes distinct margin structures and certification burdens that reshape competitive positioning across supplier tiers.
Product Type:
Standardization dominates at the high-volume automotive tier, while customization persists in stationary and retrofit applications where weight sensitivity varies.
- Composite Cylinders:Carbon fiber-reinforced polymer liners wrapped with automated filament winding deliver gravimetric efficiencies above 5.7 wt% hydrogen storage. Fleet operators in California's San Joaquin Valley specify these exclusively for Class 8 truck retrofits where payload preservation determines route economics.
- Steel Cylinders:Seamless chromium-molybdenum vessels withstand extreme cycle fatigue but impose severe weight penalties. Industrial hydrogen users in Germany's chemical clusters deploy these for stationary buffer storage where floor loading constraints are minimal.
- Aluminum Cylinders:Lined aluminum structures occupy a narrowing middle ground as composite costs decline.
- Hybrid Cylinders:Steel-aluminum or aluminum-composite combinations serve niche testing equipment and prototype vehicle validation.
Most installed capacity flows through Composite Cylinders. Expansion is steepest in Hybrid Cylinders as transitional bridge technologies for mixed-fleet operators.
End User:
Procurement scale and technical specification authority separate capital-intensive OEM programs from fragmented aftermarket demand.
- Automotive OEMs:Tier 1 suppliers manage 18-24 month homologation cycles under UN ECE R134, consolidating volume around qualified filament-winding partners. Toyota, Hyundai, and emerging Chinese fuel cell truck manufacturers drive specification evolution toward embedded fiber-optic monitoring.
- Energy Providers:Hydrogen station operators like Iwatani and Air Liquide specify buffer storage arrays with 15-year certified service life, prioritizing permeation stability over weight optimization.
- Industrial Users:Steel processing and semiconductor fabs consume cylinders for process hydrogen in captive generation setups.
- Research Institutions:National laboratories and university programs purchase small lots for materials testing and safety protocol development.
Automotive OEMs concentrate procurement value. Energy Providers are expanding most quickly as Germany's Core Hydrogen Network and Japan's METI-backed station buildout accelerate.
Application:
Mobile versus stationary use cases split the market between gravimetric efficiency imperatives and volumetric density tolerance.
- Fuel Cell Vehicles:Onboard storage systems must survive 11,000+ pressure cycles, vibration spectra, and crash loads while maintaining NWP certification. Heavy-duty truck platforms in Europe's retrofit programs are displacing earlier bus and passenger car demand as the primary growth vector.
- Hydrogen Refueling Stations:Cascade storage banks enable rapid 700 bar dispensing without compressor oversizing. California's zero-emission corridor infrastructure mandates dominate procurement specifications here.
- Storage Solutions:Industrial buffer tanks and backup power systems accept heavier vessel configurations.
- High-Pressure Testing:Certification laboratories and manufacturer QA facilities consume cylinders for burst validation and cycle-fatigue protocols.
Fuel Cell Vehicles anchor installed base value. Hydrogen Refueling Stations are climbing the fastest as infrastructure investment outpaces vehicle fleet scaling in multiple geographies.
Material:
Supply concentration and precursor grade requirements stratify manufacturing cost structures across fiber and metal categories.
- Carbon Fiber:Aerospace-grade PAN-based precursors from Toray, Hexcel, and SGL Carbon dominate Type IV liner reinforcement. Japanese and Korean supply concentration exposes cylinder manufacturers to allocation rationing during demand surges in automotive program ramp-ups.
- Aluminum Alloy:6061-T6 and similar alloys form liners for Type III designs, with extrusion and flow-forming capabilities concentrated in European and North American metalworking centers.
- Steel Alloy:Chromium-molybdenum seamless tubing retains cost advantage for low-cycle stationary applications.
- Others:Glass fiber hybrids and experimental basalt composites occupy pre-commercial testing phases.
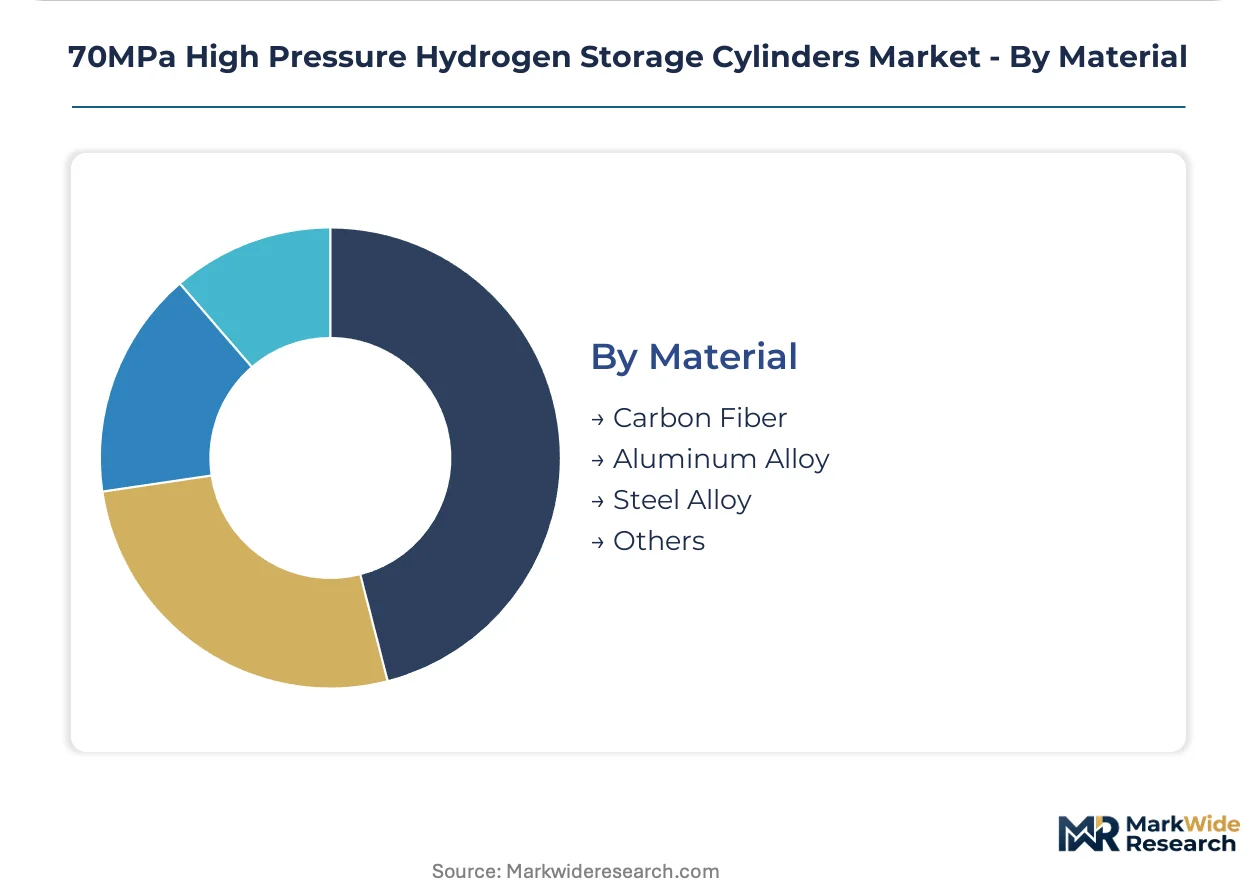
Carbon Fiber commands the dominant share of material value. Aluminum Alloy is gaining share fastest as Type III designs stage a partial resurgence in cost-sensitive heavy-duty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's national hydrogen backbone commands infrastructure investment intensity that Japan's METI-backed station buildout matches only in select urban corridors. California's zero-emission mandates outpace both in fleet conversion velocity.
United States
California's Advanced Clean Trucks regulation compels Class 8 diesel conversions to hydrogen powertrains through 2035. The EPA coordinates with DOT on fuel system integrity standards that shape OEM procurement specifications. The San Joaquin Valley logistics cluster anchors heavy-duty retrofit demand as fleet operators contract storage assets through fuel suppliers.
Germany
The SuedLink corridor and industrial hydrogen backbone projects require distributed buffer storage beyond transportation applications. KBA homologation protocols under UN ECE R134 govern 18-24 month certification cycles for vehicle-system integration. The Ruhr industrial cluster concentrates stationary cylinder deployment for chemical process hydrogen buffering.
Japan
METI's hydrogen roadmap tightens Type IV permeation limits below 6 NmL/hr/L through revised High Pressure Gas Safety Act implementing rules. Transit agencies in Tokyo and Osaka mandate embedded fiber-optic sensing arrays for public bus fleet monitoring. Heavy-duty truck OEMs consolidate procurement around suppliers with in-house permeation testing laboratories.
China
MIIT fuel cell vehicle subsidies accelerate commercial truck program ramp-ups that strain aerospace-grade carbon fiber allocation. GB standards for high-pressure gas equipment converge with ISO 19881 testing protocols for export market access. The Yangtze River Delta manufacturing belt concentrates filament-winding automation investment for domestic and export cylinder production.
India
The National Hydrogen Mission's PLI scheme for electrolyzer and fuel cell manufacturing creates first-mover positioning for cylinder suppliers establishing local capacity. BIS pressure equipment directives are harmonizing with emerging ISO standards for composite vessel certification. The Gujarat industrial corridor attracts preliminary filament-winding facility announcements from multinational suppliers.
70MPa High Pressure Hydrogen Storage Cylinders Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated vehicle system providers anchoring long-term service agreements while pure-play cylinder fabricators compete on manufacturing scale. The vendor base concentrates around three strategic archetypes: composite materials specialists with captive carbon fiber relationships, diversified industrial gas equipment manufacturers leveraging existing pressure vessel expertise, and automotive Tier 1 suppliers integrating storage into powertrain systems. Capacity expansion and strategic partnerships dominate competitive moves, with particular emphasis on co-location with OEM assembly plants and hydrogen hub infrastructure zones.
Among Norway-based composite specialists, Hexagon Purus occupies a position exemplifying integrated vehicle systems expertise, while NPROXX represents the ultra-lightweight carbon fiber configuration archetype. Worthington Industries anchors the North American manufacturing scale tier, sustaining supply chain relationships across automotive OEM programs. These three entities collectively illustrate how geographic proximity to demand clusters and manufacturing process specialization stratify competitive positioning in cylinder procurement.
| Leading Market Players |
|---|
| Hexagon Purus |
| Worthington Industries |
| Luxfer Group |
| NPROXX |
| Plastic Omnium |
| Linde plc |
| Air Products and Chemicals |
| Chart Industries |
| Faber Industrie |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between UN ECE R134-homologated OEM systems and aftermarket retrofit cylinders manifests in both unit pricing spreads and supply chain tiering, with automotive-grade filament-winding capacity commanding 40-60% premiums over industrial-grade alternatives while drawing from distinct carbon fiber precursor allocations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing belt are reshaping price floors for Type IV composite cylinders as domestic filament-winding automation reduces labor content. Contract-based long-term offtake agreements dominate OEM procurement, with pricing stratifying across aerospace-grade carbon fiber specifications, embedded fiber-optic monitoring inclusion, and volume scale commitments. Cost compression in standard-grade Type III aluminum-lined designs is intensifying because Korean and Japanese precursor suppliers ration allocations during automotive program ramp-ups. Fleet operators in California's San Joaquin Valley exhibit highest price sensitivity, prioritizing per-kilogram hydrogen storage economics over certification tier, while transit agencies in Japan and Germany demonstrate lowest sensitivity due to total-cost-of-ownership procurement frameworks.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Korean aerospace-grade PAN-based carbon fiber suppliers, particularly Toray and adjacent precursor manufacturers controlling filament-winding feedstock quality. Manufacturing draws from Japan, Germany, and China for carbon fiber reinforcement, aluminum liner extrusion, and automated tow placement equipment respectively. Supply chain risk centers on tariff exposure for US-bound cylinder assemblies incorporating Chinese-wound composite shells, compounded by export license requirements for aerospace-grade fiber under multilateral control regimes. Distribution runs through Tier 1 automotive suppliers co-located with OEM assembly plants, hydrogen hub infrastructure zones, and regional industrial gas equipment distributors serving retrofit aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India's National Hydrogen Mission, where PLI subsidies for electrolyzer and fuel cell manufacturing create 30-40% effective cost differentials versus European filament-winding operations, rewarding early local capacity establishment before BIS certification harmonization matures.
For Market Incumbents: Deepen captive relationships with aerospace-grade carbon fiber suppliers through backward integration into precursor processing or long-term offtake guarantees, defending against emerging Chinese cylinder manufacturers capturing share in cost-sensitive heavy-duty retrofit segments. Prioritize certification investment in India's BIS pressure equipment directives and embedded fiber-optic sensing arrays as channel control mechanisms for transit agency procurement. For New Entrants and Emerging Players: Direct-to-fleet digital sales platforms bypassing Tier 1 supplier intermediaries offer lowest customer acquisition costs in California's fragmented logistics operator base, where powertrain-as-a-service contracting models reduce upfront capital barriers. Target stationary buffer storage applications in Germany's Core Hydrogen Network as the most penetrable segment, lacking incumbent filament-winding specialization and tolerating longer lead times for quality validation. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale cylinder fabricators lack in-house permeation testing laboratories required by Japan's revised High Pressure Gas Safety Act implementing rules. Five-to-ten year viability favors suppliers with integrated vehicle systems expertise and software-defined monitoring subscription revenue streams. Watch carbon fiber precursor allocation announcements from Japanese suppliers as the critical inflection signal for margin compression timing across qualified OEM supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Filament-Winding Automation Investment | Reduces labor content and cycle time for Type IV cylinder production in high-volume automotive programs. |
| In-House Permeation Testing Laboratory | Accelerates METI compliance validation and consolidates procurement preference from Japanese heavy-duty truck OEMs. |
| Co-Location with Hydrogen Hub Infrastructure | Minimizes logistics costs for cascade storage banks serving California's zero-emission corridor mandates. |
| Software-Defined Monitoring Platform Development | Enables subscription-based asset management contracts shifting revenue from unit sales to lifecycle services. |
| Recycled Carbon Fiber Certification Program | Positions product lines for emerging ISO standards on sustainable pressure vessel manufacturing. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement managers, hydrogen station operators, filament-winding equipment manufacturers, and transit agency fleet directors grounded qualitative assessment, cross-referenced with customs trade data, UN ECE R134 homologation filings, METI hydrogen roadmap publications, and SEC 10-K disclosures from composite materials specialists. Bottom-up and top-down triangulation validated volume estimates across product type, end user, and application segmentation.
Bottom-up modeling aggregated individual country-level demand projections for fuel cell vehicle deployments and hydrogen refueling station buildouts, while top-down analysis triangulated against national hydrogen backbone investment commitments across the projection horizon. Segmentation dimensions included cylinder material grade, liner type, pressure cycle certification tier, and regional regulatory cluster. CAGRs derived from weighted average of deployment scenarios incorporating carbon fiber supply elasticity and filament-winding capacity expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for liquid hydrogen cryogenic storage in maritime and long-haul applications would alter the outlook for 70MPa cylinder addressable market. Forecasts reflect assumptions on ISO 19881 harmonization progress, PLI scheme disbursement rates, and aerospace-grade fiber allocation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Liquid Hydrogen Tank Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Hydrogen Recovery Market