
 Steam Jet Ejector Market | 2026-2036
Steam Jet Ejector Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Jet Ejector Market Analytics
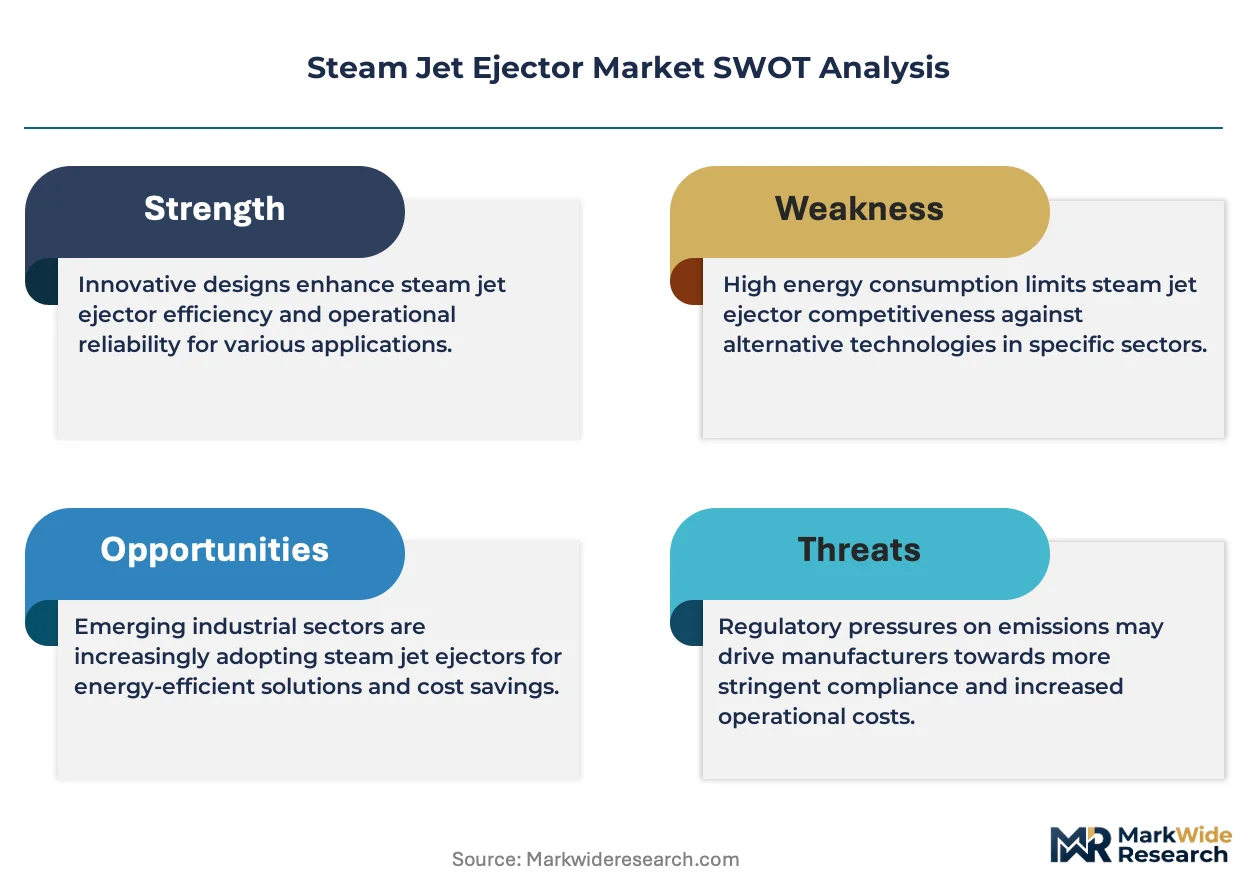
Project finance for large-scale refinery and chemical complex upgrades is narrowing the competitive field to suppliers capable of underwriting extended performance guarantees. Graham Corporation leverages its engineered vacuum systems expertise to sustain long-term service contracts with North American petrochemical operators. Croll Reynolds anchors its position through deep specialization in multi-stage ejector configurations for corrosive process environments. Körting Hannover AG competes by dominating European heavy-industry installations with robust metallurgy and thermal design capabilities.
A steam jet ejector is a momentum-transfer device that uses high-pressure steam expansion through a converging-diverging nozzle to entrain and compress secondary vapors, achieving suction pressures from atmospheric down to fractions of a millibar without moving parts. The technology serves primarily as a vacuum generation and vapor recovery mechanism in continuous process industries where reliability and absence of electrical ignition sources matter. Multi-stage ejectors command the largest product type share because deep vacuum requirements in crude oil distillation and chemical processing demand cascading compression ratios that single units cannot deliver. Vacuum generation applications lead by volume across end users, though pollution control installations are gaining traction as regulators tighten emissions from volatile organic compound handling. Chemical industry demand remains the most structurally entrenched segment, with margin pools concentrated in custom-engineered packages for high-temperature, corrosive service.
EPA New Source Performance Standards and OSHA Process Safety Management requirements in the United States shape product specifications by mandating leak-tight construction and hazard analysis documentation for vacuum systems handling hazardous chemicals. REACH restrictions on chromium and nickel alloys in Europe push manufacturers toward alternative metallurgies that maintain corrosion resistance without restricted substances. India's CEA efficiency norms for thermal power plants indirectly steer ejector selection by penalizing auxiliary steam consumption. Stakeholders must monitor how carbon border adjustment mechanisms and regional steam cost differentials redraw the total-cost-of-ownership calculus for vacuum system investments.
Market Dynamics
Steam jet ejector manufacturers face intensifying pressure from industrial decarbonization mandates that penalize auxiliary steam consumption, forcing a fundamental re-engineering of thermal efficiency ratios across vacuum system portfolios.
Growth Catalysts
- China's dual carbon goals:National emission intensity targets compel chemical processors to replace mechanical vacuum pumps with steam-driven alternatives that eliminate electrical ignition risks in hazardous environments.
- REACH restrictions on chromium alloys:European manufacturers accelerate development of corrosion-resistant metallurgies using titanium and duplex stainless steels to maintain service life without restricted substances.
- Petrochemical cluster expansion:India's Dahej and Paradip industrial corridors drive concentrated demand for multi-stage ejector systems in crude distillation and polymer degassing operations.
Market Restraints
- Steam cost volatility:Natural gas price fluctuations in European industrial hubs compress operating margins for thermal vacuum systems relative to electrically driven alternatives.
- Supplier concentration in specialty metallurgy:Limited qualified foundries for Hastelloy and titanium castings in Germany and Japan create bottlenecks for corrosive-service ejector fabrication.
- Mechanical vacuum pump substitution:Dry screw and liquid ring technologies capture mid-range vacuum applications where steam infrastructure is absent.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU CBAM implementation creates competitive advantage for low-carbon steam ejector designs in export-oriented chemical processing.
- Hydrogen economy integration:Electrolyzer and ammonia synthesis facilities require explosion-proof vacuum generation for hydrogen purification and storage systems.
- Remote monitoring convergence:Industrial IoT platforms enable predictive maintenance contracts that extend equipment lifecycle and capture recurring revenue streams.
Industry Challenges
- Thermal-hydraulic modeling expertise gap:Specialized computational fluid dynamics skills for converging-diverging nozzle design concentrate at a handful of engineering consultancies.
- Legacy system integration complexity:Retrofitting multi-stage ejectors into existing vacuum networks requires custom piping configurations that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Jet Ejector Market |
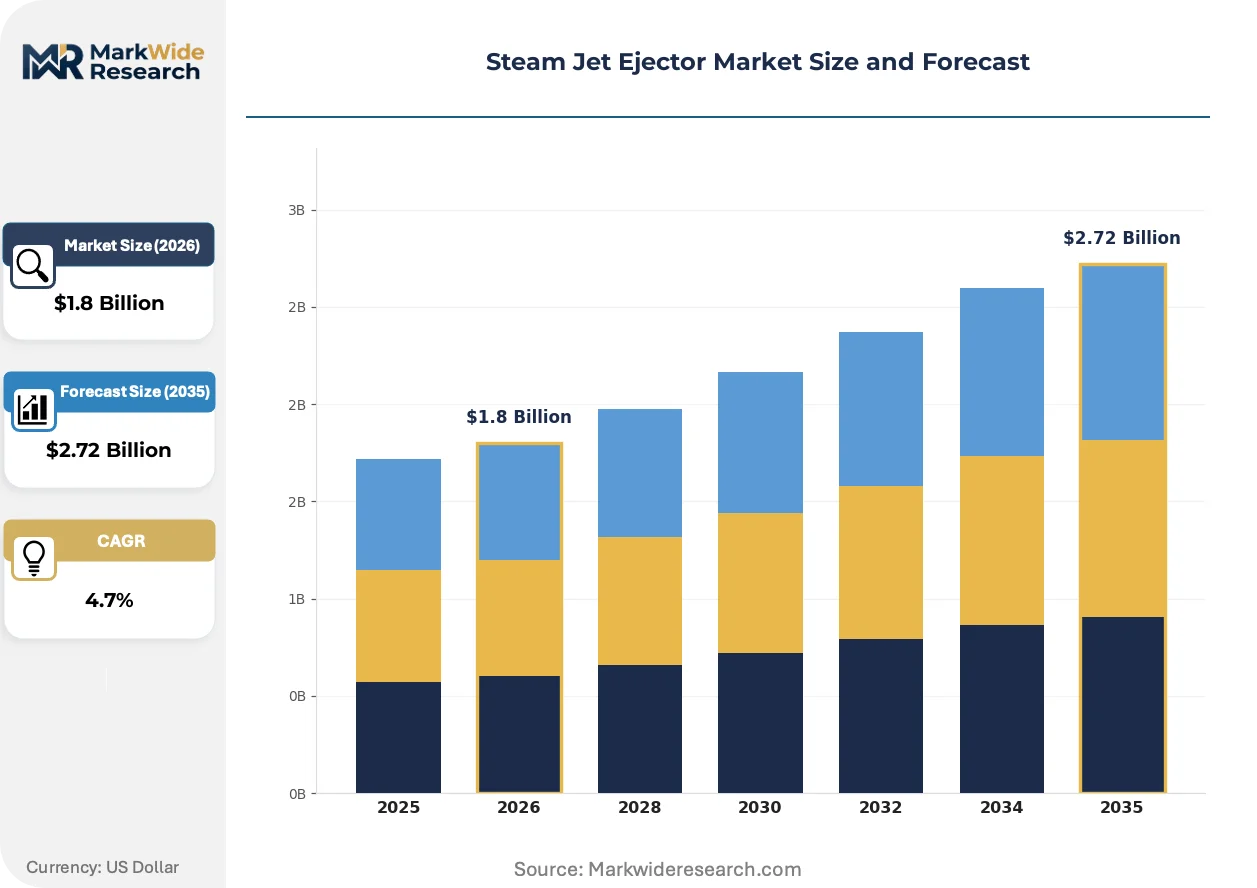
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi Stage, Condensate Ejectors, Custom Ejectors End User: Chemical Industry, Oil & Gas, Power Generation, Pharmaceuticals Application: Vacuum Generation, Liquid Removal, Gas Handling, Pollution Control Installation Type: In-line, Standalone, Portable, Custom |
| Companies Covered | Graham Corporation, Croll Reynolds, Venturi Jet Pumps Ltd., Gardner Denver Nash, Körting Hannover AG, Chem Process Systems, Unique Systems, Jet Vacuum Systems Pvt. Ltd., Ebara Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Jet Ejector Market Evolving Landscape
Steam jet ejector engineering is undergoing material and control-system transformation as process industries demand deeper vacuum levels with reduced motive steam consumption. Three interconnected developments are restructuring competitive capabilities.
Condensing surface technologies are migrating from traditional direct-contact designs to surface condenser configurations that recover motive steam as condensate. Refinery operators in the US Gulf Coast are adopting these systems to reduce boiler feedwater makeup requirements. This migration from once-through to closed-loop thermal management is compressing water treatment costs and enabling heat integration with downstream process units.
EPA New Source Performance Standards for petroleum refineries are mandating leak-tight construction and continuous emission monitoring for vacuum systems handling volatile organic compounds. Equipment suppliers must now deliver welded bellows seals and flanged connections rated for fugitive emission thresholds below 500 ppm. Chemical processors in Texas and Louisiana are responding by specifying API 682-compliant mechanical seal packages for ejector intercondensers.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into discrete performance-based agreements. Petrochemical operators in Alberta and Rotterdam are separating spare parts procurement from technical supervision, creating openings for third-party inspection specialists. This decomposition of the value chain is most visible in large integrated sites where centralized engineering departments retain in-house vacuum system expertise.
Steam Jet Ejector Market Segmentation
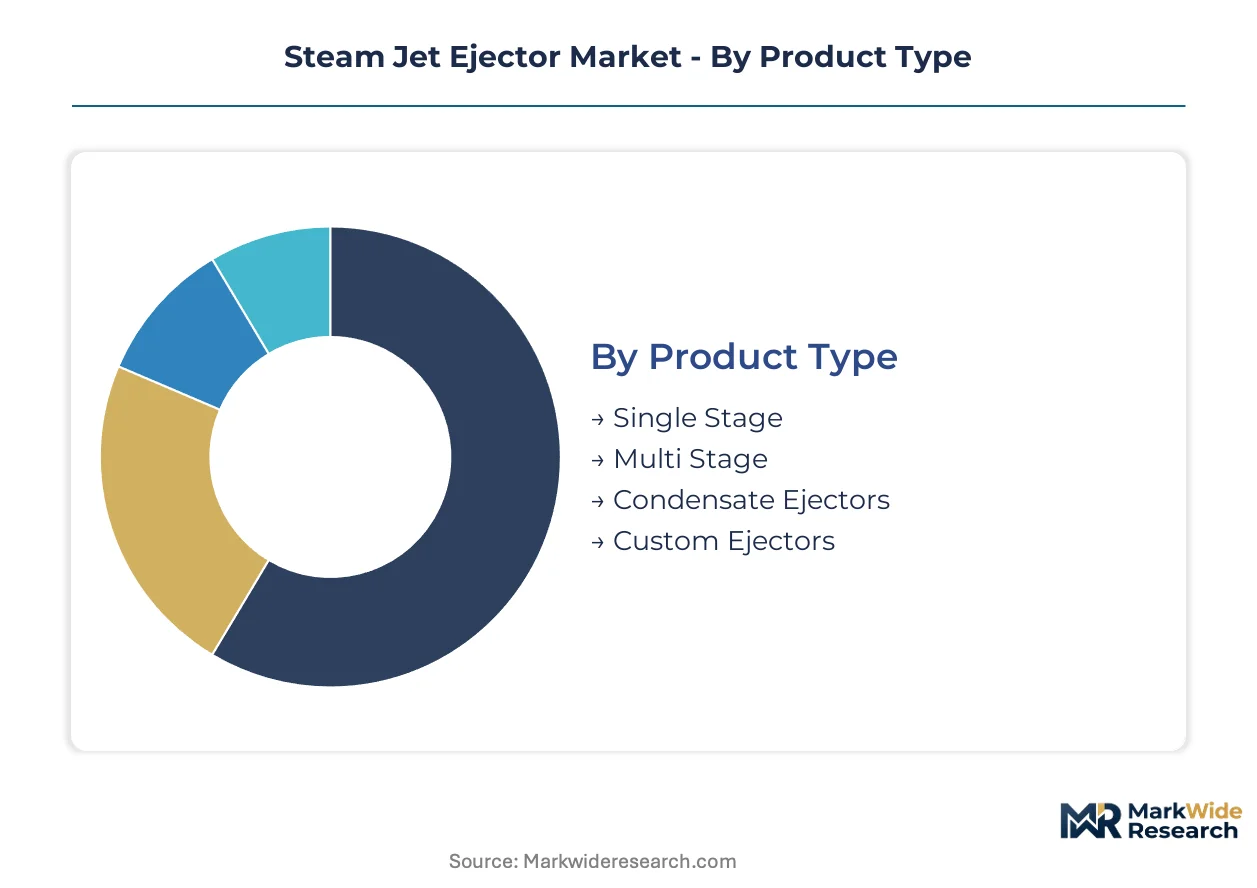
Steam jet ejector procurement patterns diverge sharply across product configurations and end-use contexts. Chemical processors prioritize corrosion-resistant metallurgy and deep vacuum capability, while power utilities emphasize thermal efficiency and steam integration.
Product Type:
Cost tier stratification separates standardized single-stage units from engineered multi-stage systems with cascading compression ratios.
- Single Stage:Compact momentum-transfer devices achieve suction pressures down to approximately 100 mbar using one converging-diverging nozzle. Refinery tank venting and simple evacuation duties in Texas and Louisiana chemical plants drive replacement demand for these units.
- Multi Stage:Cascaded ejector arrays compress secondary vapors through sequential stages, reaching fractions of a millibar for crude oil distillation vacuum towers. Dahej and Paradip petrochemical corridors in India specify these configurations for polymer degassing and solvent recovery operations.
- Condensate Ejectors:Specialized designs recover motive steam as liquid condensate for boiler feedwater reuse.
- Custom Ejectors:Engineered-to-order systems address exotic metallurgy requirements and non-standard pressure profiles.
Multi-stage configurations hold installed capacity. Single-stage units are rotating up the share rankings in mid-range vacuum applications.
End User:
Application context determines specification intensity, with hazardous chemical service demanding leak-tight construction and documented hazard analysis.
- Chemical Industry:Processors handling chlorinated solvents and sulfuric acid derivatives specify titanium or duplex stainless steel ejectors to survive corrosive vapor streams. REACH restrictions on chromium alloys push European operators toward alternative metallurgies that maintain service life without restricted substances.
- Oil & Gas:Refinery vacuum distillation units require multi-stage systems with surface condensers to reduce boiler feedwater makeup. US Gulf Coast operators adopt these configurations to compress water treatment costs and enable heat integration with downstream process units.
- Power Generation:Thermal power plants deploy ejectors for condenser air removal and deaeration duties. India's CEA efficiency norms penalize auxiliary steam consumption, indirectly steering ejector selection toward optimized thermal designs.
- Pharmaceuticals:Sterile vacuum generation for freeze-drying and solvent recovery demands surface finishes and material certifications that extend procurement cycles.
Chemical industry deployments anchor specification standards. Oil & gas applications are climbing the fastest as refinery upgrade cycles accelerate.
Application:
Functional purpose shapes motive steam consumption profiles and determines intercondenser complexity.
- Vacuum Generation:The dominant functional deployment creates suction for distillation, drying, and degassing operations across continuous process industries. China's dual carbon goals compel chemical processors to adopt steam-driven vacuum systems that eliminate electrical ignition risks in hazardous environments.
- Liquid Removal:Condensate and process liquid extraction from vapor streams requires specialized suction chamber geometries. Pulp and paper mills in Finland and Sweden deploy these configurations for black liquor evaporation duties.
- Gas Handling:Compression and transfer of non-condensable gases demands multi-stage arrays with interstage cooling.
- Pollution Control:Volatile organic compound recovery and emission containment installations are gaining traction as EPA New Source Performance Standards mandate leak-tight construction and continuous monitoring for vacuum systems handling hazardous chemicals.
Vacuum generation commands the largest installed base. Pollution control applications are expanding most quickly under tightening emission regulations.
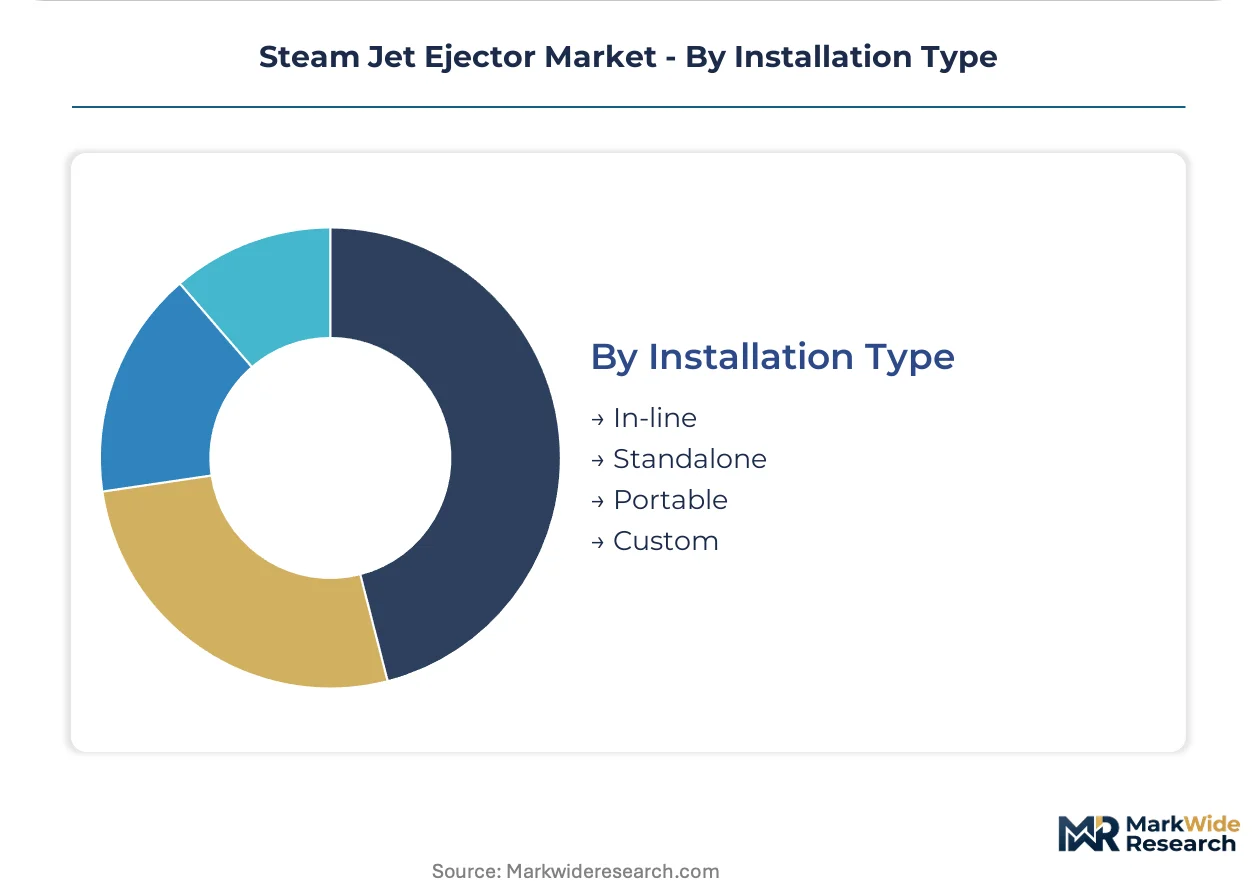
Installation Type:
Integration architecture determines piping complexity and maintenance accessibility.
- In-line:Direct insertion into process piping minimizes footprint for space-constrained chemical plants. Rotterdam refinery operators favor these configurations for retrofits where equipment bays lack expansion clearance.
- Standalone:Skid-mounted packages with dedicated condensate handling and control systems dominate greenfield petrochemical complexes. Alberta oil sands upgraders specify these units for remote locations with limited utility infrastructure.
- Portable:Trailer-mounted ejector systems serve temporary vacuum duties during turnaround maintenance and emergency response.
- Custom:Bespoke structural integration addresses seismic requirements, extreme temperatures, or confined-space constraints.
Standalone packages hold installed capacity. In-line configurations are gaining share fastest as brownfield optimization intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for steam jet ejector systems track closely with petrochemical capacity buildouts and refinery upgrade cycles. Countries with large process industry bases import specialized multi-stage configurations while exporting standardized single-stage units to adjacent markets.
China
Dual carbon targets under MEE supervision drive chemical processors toward steam-driven vacuum systems that eliminate electrical ignition hazards. National emission intensity standards compel replacement of mechanical pumps in hazardous environments. Yangtze River Delta petrochemical clusters specify deep-vacuum multi-stage ejectors for crude distillation and polymer operations.
United States
EPA New Source Performance Standards mandate leak-tight construction for vacuum systems handling volatile organic compounds. OSHA Process Safety Management requirements shape hazard analysis documentation protocols. Texas and Louisiana refinery operators adopt surface condenser configurations to reduce boiler feedwater costs and enable downstream heat integration.
Germany
REACH restrictions on chromium and nickel alloys push manufacturers toward titanium and duplex stainless steel metallurgies. ECHA compliance timelines accelerate development of corrosion-resistant alternatives without restricted substances. Industrial corridors in North Rhine-Westphalia anchor European demand for engineered vacuum packages in chemical processing.
India
CEA efficiency norms for thermal power plants penalize auxiliary steam consumption, indirectly steering ejector selection toward optimized thermal designs. Petrochemical expansions in Dahej and Paradip industrial corridors concentrate demand for multi-stage systems. Gujarat and Odisha process clusters require reliable vacuum generation for distillation and degassing operations.
Japan
METI industrial efficiency guidelines promote steam system optimization in continuous process industries. JIS standards govern pressure vessel construction and material certification requirements. Chubu region chemical manufacturers specify precision-engineered ejectors for high-purity solvent recovery and semiconductor materials processing.
Steam Jet Ejector Market Competitive Landscape
On the supply side, the industry is moderately concentrated around specialized engineering houses with deep thermal-hydraulic expertise. The competitive field narrows for corrosive-service applications requiring exotic metallurgy fabrication capabilities. Two strategic archetypes dominate: full-system integrators delivering engineered packages with long-term service contracts, and component specialists focused on nozzle design and precision machining. Capacity expansion and technology licensing represent the primary competitive moves as players seek to extend geographic reach without capital-intensive manufacturing replication.
Among North American system integrators, Graham Corporation and Croll Reynolds exemplify the full-package archetype with sustained presence in petrochemical service contracts. German-based Körting Hannover AG occupies a position within the European heavy-industry tier, anchoring demand for robust metallurgy and thermal design capabilities. These three names represent the geographic and capability spread visible across the supplier base.
| Leading Market Players |
|---|
| Graham Corporation |
| Croll Reynolds |
| Venturi Jet Pumps Ltd. |
| Gardner Denver Nash |
| Körting Hannover AG |
| Chem Process Systems |
| Unique Systems |
| Jet Vacuum Systems Pvt. Ltd. |
| Ebara Corporation |
| Others |
Value Network & Pricing Analysis
Titanium and duplex stainless steel sourcing bottlenecks in Germany and Japan determine both the spread between premium and economy ejector tiers and the geographic clustering of qualified fabrication capacity. REACH restrictions on chromium alloys compress availability of corrosion-resistant metallurgies, forcing buyers into longer procurement cycles for engineered multi-stage systems while standard single-stage units compete on expedited delivery.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium configurations command substantial markups for titanium metallurgy and API 682-compliant seal packages, while economy single-stage units compete on volume scale and minimal customization. Cost compression in the standard tier is intensifying because dry screw vacuum pump substitution erodes mid-range vacuum applications. Petrochemical operators in Texas and Louisiana exhibit the lowest price sensitivity due to total-cost-of-ownership calculations favoring reliability over capital expenditure, whereas Indian power utilities face acute price pressure from CEA efficiency norms penalizing auxiliary steam consumption.
Supply Chain Analysis
Specialized foundries in Germany, Japan, and India hold qualified capacity for Hastelloy and titanium castings required in corrosive-service ejector fabrication. Raw material procurement draws from nickel alloy suppliers in South Korea, titanium sponge producers in China, and duplex stainless steel mills in Sweden. Single-source vulnerability concentrates in precision-machined converging-diverging nozzles where thermal-hydraulic modeling expertise anchors at a handful of engineering consultancies. Distribution runs through direct sales channels for engineered multi-stage packages and regional distributors for standardized single-stage replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steam jet ejector demand sits in early-cycle expansion as hydrogen economy infrastructure and carbon border adjustment mechanisms create first-mover advantages for low-carbon thermal vacuum designs.
For Market Incumbents: Harden metallurgy partnerships with German and Japanese foundries to secure titanium casting allocation against REACH-driven demand surges. Extend predictive maintenance service contracts through industrial IoT platforms to capture recurring revenue streams and defend against third-party inspection specialists unbundling after-sales value. For New Entrants and Emerging Players: Pursue portable ejector configurations for turnaround maintenance and emergency response duties where established suppliers maintain limited presence. Target in-line retrofit specifications for Rotterdam and US Gulf Coast brownfield optimizations where space constraints favor compact momentum-transfer designs over standalone packages. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors engineering houses with captive thermal-hydraulic modeling capabilities. Long-term viability rests on consolidation of nozzle design specialists and surface condenser technology platforms. Watch hydrogen purification facility announcements as the inflection indicator for explosion-proof vacuum generation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Casting | REACH compliance timelines in Germany accelerate captive metallurgy investments. |
| Surface Condenser Technology Licensing | US Gulf Coast refineries adopt closed-loop thermal management for water cost compression. |
| Predictive Maintenance Platform Launch | Alberta petrochemical operators separate spare parts procurement from technical supervision. |
| Joint Venture in Dahej Industrial Corridor | Indian petrochemical expansions concentrate demand for multi-stage polymer degassing systems. |
| Green Manufacturing Certification Program | EU CBAM implementation creates competitive advantage for low-carbon steam ejector designs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from vacuum system integrators, and industry association reports from ACC and Cefic. Interviews with maintenance directors at Texas and Louisiana refineries, procurement leads at Indian petrochemical operators, and aftermarket service heads at European engineering houses provided operational validation. Bottom-up unit shipment estimates triangulated against top-down capital expenditure analysis across chemical processing and power generation end uses.
Forecast inputs include steam cost differentials by regional industrial hub, regulatory compliance timelines for EPA New Source Performance Standards and REACH restrictions, and hydrogen economy infrastructure buildout trajectories. Segmentation dimensions span product type, end-use industry, application function, and installation architecture. CAGRs were derived from elasticity modeling of vacuum system investment against petrochemical capacity expansion cycles and refinery upgrade intervals.
Macroeconomic conditions sit as an overlay; deviation in natural gas price volatility and carbon border adjustment mechanism implementation schedules would shift the trajectory for thermal vacuum system competitiveness. Forecasts reflect assumptions regarding sustained REACH alloy restrictions and continued dual carbon policy enforcement in China. Quarterly review of electrolyzer project announcements, refinery turnaround schedules, and foundry capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Package Pumping Station Market