
 Hydrogen Circulation Pump Market | 2026-2036
Hydrogen Circulation Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Circulation Pump Market Insights
Project finance for green hydrogen electrolysis clusters is tilting competitive dynamics toward vendors capable of multi-year service contracts and performance guarantees. Ebara Corporation leverages its centrifugal pump heritage to anchor long-term supply relationships with Japanese hydrogen infrastructure consortia. Parker Hannifin Corporation sustains engineering credibility through its integrated sealing and motion-control portfolio across North American fuel cell test facilities. KNF Neuberger differentiates via diaphragm pump specialization for laboratory and pilot-scale hydrogen loops where purity thresholds exceed industrial norms.
Hydrogen circulation pumps are precision fluid-handling devices engineered to recirculate gaseous hydrogen at pressures ranging from 30 to 700 bar while maintaining leak rates below prescribed thresholds; their primary purpose is to ensure continuous fuel delivery and thermal management within closed-loop hydrogen systems. Centrifugal pump configurations dominate current fuel cell system integrations due to maturity in high-flow, moderate-pressure duty cycles, while diaphragm pump architectures capture expanding laboratory testing applications where hermetic sealing and contamination control command premium positioning. Electrochemical technology segments remain nascent but attract R&D allocation as developers pursue elimination of mechanical wear surfaces in long-duration energy storage installations.
The EU F-Gas Regulation and REACH compliance frameworks mandate progressive reduction of fluorinated sealing materials, compelling pump manufacturers to validate alternative elastomer compounds against hydrogen embrittlement protocols. Japan's METI hydrogen safety standards and South Korea's KGS certification requirements create divergent approval pathways that fragment product platform strategies across export markets. Stakeholders must monitor evolving interoperability standards between refueling station architectures and onboard vehicle circulation systems as infrastructure rollout accelerates beyond pilot phases.
Market Dynamics
Heavy-duty trucking electrification via proton exchange membrane fuel cells is concentrating procurement authority among fleet operators seeking multi-year performance guarantees, compressing vendor selection cycles and elevating service-contract terms to parity with hardware specifications.
Growth Catalysts
- EU F-Gas Regulation:Mandates progressive fluorinated sealant phase-out, compelling pump manufacturers to validate hydrogen-compatible elastomer alternatives and creating first-mover advantages for compliant suppliers.
- Heavy-duty trucking fleets:Scale deployment of 700-bar refueling infrastructure across German autobahn corridors and California interstate corridors, anchoring demand for high-pressure circulation hardware.
- Electrochemical compression:Elimination of mechanical wear surfaces in long-duration energy storage applications attracts R&D allocation from developers targeting 20,000-hour maintenance intervals.
Market Restraints
- Specialized alloy feedstock concentration:High-nickel stainless steel and cobalt-based superalloy supply concentrates in specific mining jurisdictions, exposing pump casting costs to raw material volatility.
- Hydrogen embrittlement validation protocols:Extended certification timelines under Japan METI safety standards and South Korea KGS requirements fragment product platform strategies and delay market entry.
- Mechanical compression substitution:Electrochemical and ionic liquid compression technologies threaten diaphragm pump positioning in laboratory and pilot-scale applications where purity thresholds dominate specifications.
Strategic Opportunities
- India green hydrogen hubs:National hydrogen mission targets and PLI scheme incentives for electrolyzer manufacturing create procurement demand for circulation hardware in emerging production clusters.
- Refueling station-retail integration:Hydrogen corridor developers in Germany and California are unbundling station construction from long-term O&M contracts, opening channel entry for specialized service providers.
- Digital twin convergence:Integration of predictive maintenance algorithms with circulation pump telemetry enables outcome-based service models that lock in multi-year fleet operator relationships.
Industry Challenges
- Precision machining talent scarcity:Tolerance requirements below 10 microns for high-pressure sealing surfaces exceed output from conventional vocational training programs in Germany and Japan.
- Cross-certification complexity:Divergent approval pathways between EU F-Gas compliance, Japan METI standards, and South Korea KGS certification force redundant testing cycles that extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Circulation Pump Market |
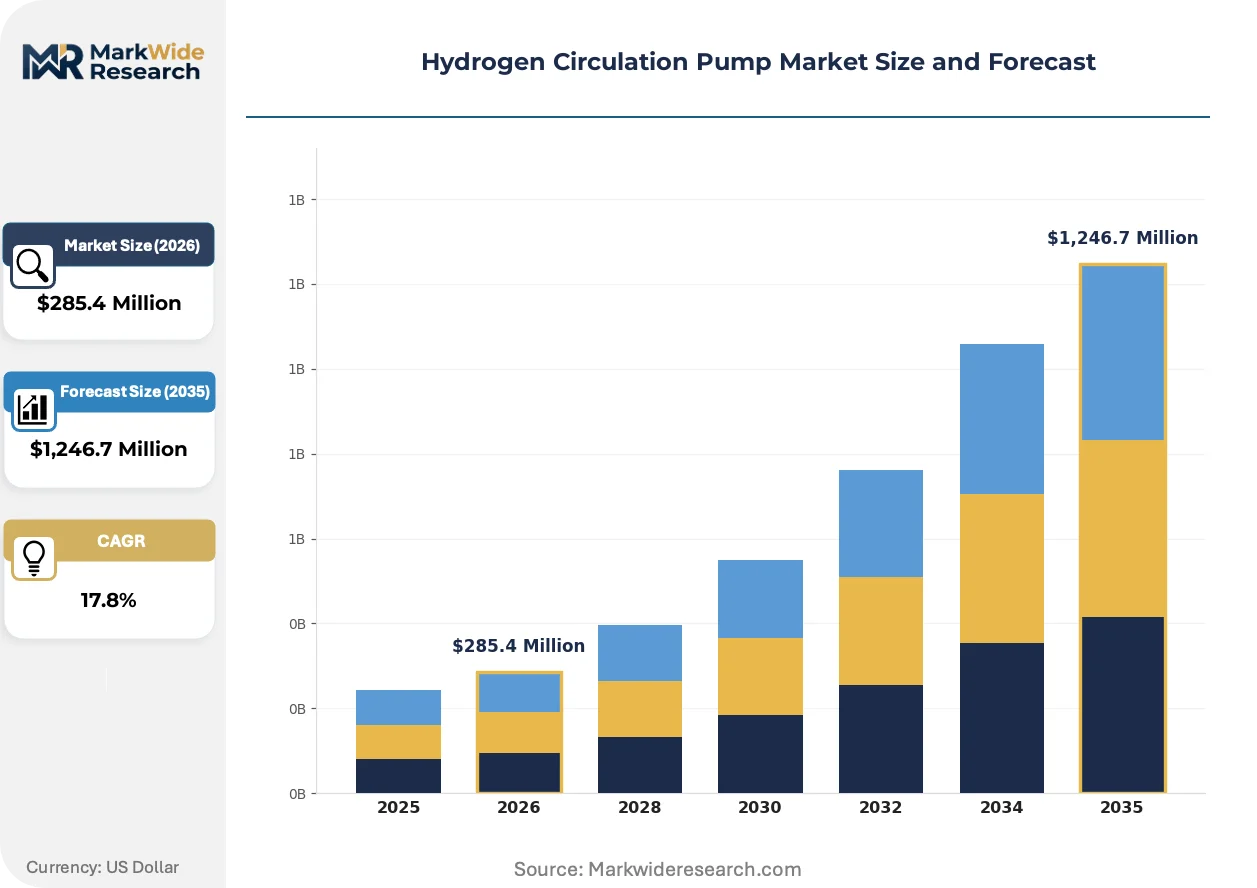
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,246.7 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pump, Centrifugal Pump, Reciprocating Pump, Diaphragm Pump End User: Power Generation, Chemical Processing, Automotive, Aerospace Technology: Electrochemical, Mechanical, Thermodynamic, Magnetic Application: Fuel Cell Systems, Energy Storage, Industrial Processes, Laboratory Testing |
| Companies Covered | Air Liquide Advanced Technologies, Bronkhorst High-Tech, Ebara Corporation, Dongel Industry, Iwaki Co. Ltd., Nikkiso Co. Ltd., KNF Neuberger, Asahi Kasei Corporation, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Circulation Pump Market Trends and Innovations
Material science advances and digitalization are compressing development cycles while regulatory pressure on fluorinated compounds is forcing sealant architecture reinvention across all pressure classes.
Magnetic bearing suspension systems are migrating from aerospace auxiliary power units into hydrogen circulation pumps for heavy-duty fuel cell applications. Fleet operators in California and Germany specify these configurations to eliminate lubricant contamination risks in 700-bar delivery loops. The technology is migrating from premium aerospace sourcing toward cost-engineered automotive-grade implementations that enable 15,000-hour maintenance intervals.
Japan's METI hydrogen safety standards now mandate real-time leak detection integration with station control systems. Pump manufacturers must embed fiber-optic sensing arrays and validate signal interoperability with refueling protocol controllers. Japanese infrastructure consortia are accelerating procurement of compliant hardware ahead of 2027 corridor completion targets, compressing supplier qualification windows.
Long-term service contracting is displacing transactional hardware sales in fleet procurement. Operators in German heavy-duty trucking corridors now specify availability guarantees and predictive maintenance inclusion rather than capital purchase with separate warranty terms. This restructuring concentrates vendor relationships among firms with captive field service networks and telemetry infrastructure.
Hydrogen Circulation Pump Market Segmentation
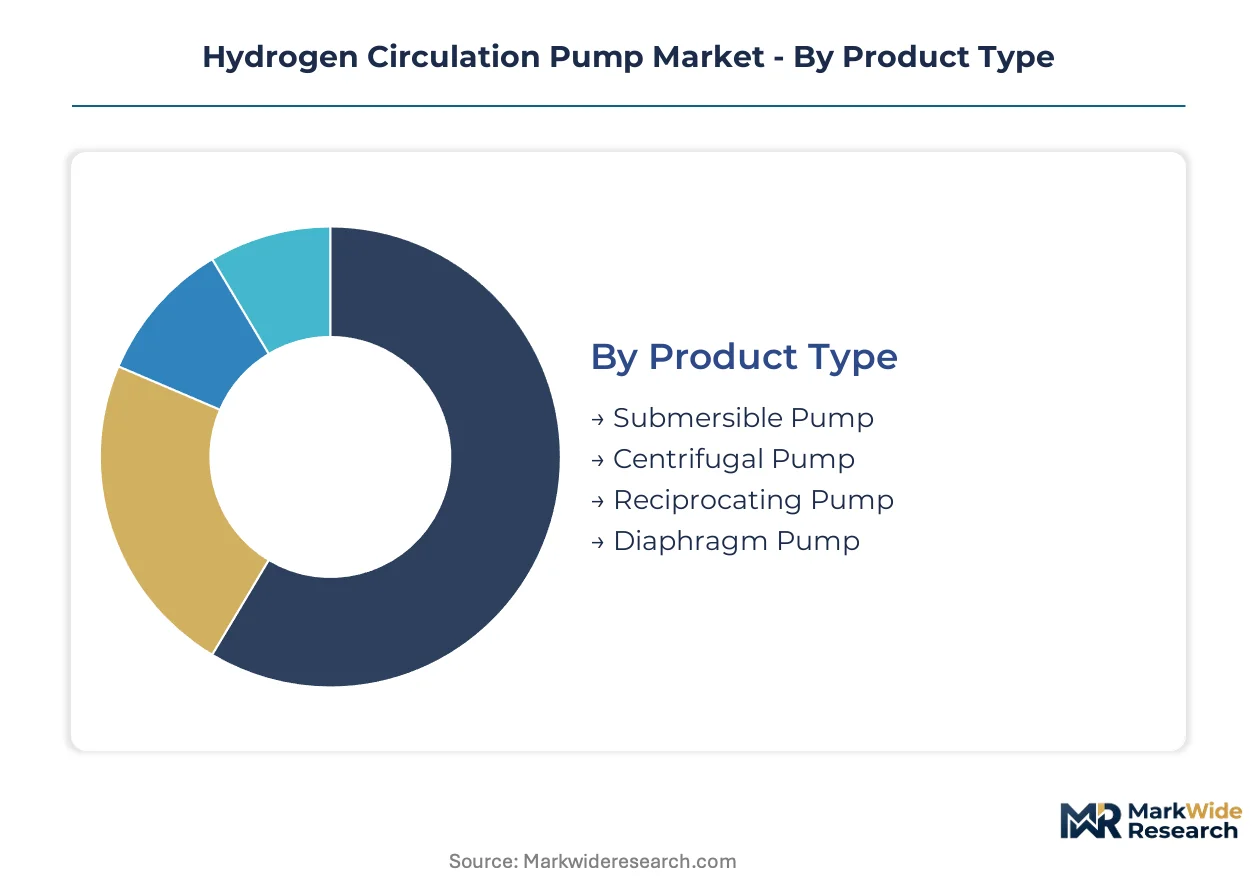
Hydrogen circulation pump procurement patterns diverge sharply across pressure ratings and duty cycles, forcing vendors to maintain parallel service infrastructures. Fleet operators in heavy-duty trucking corridors negotiate multi-year availability guarantees that reshape how product categories are bundled and priced.
Product Type:
After-sales service intensity varies dramatically by pump architecture, with high-pressure centrifugal configurations demanding dedicated field engineering networks while diaphragm units rely on modular swap programs.
- Centrifugal Pump:Dominant architecture for 350-700 bar fuel cell vehicle refueling infrastructure. German autobahn hydrogen corridors and California interstate networks anchor procurement volumes, with fleet operators specifying 15,000-hour maintenance intervals and predictive telemetry integration.
- Diaphragm Pump:Hermetic sealing design eliminates lubricant contamination pathways critical for laboratory hydrogen loop purity. Research institutions in Japan and pilot-scale electrolyzer testbeds in South Korea drive replacement-part subscription models due to seal degradation cycles.
- Submersible Pump:Limited deployment in liquid hydrogen transfer applications at export terminal installations.
- Reciprocating Pump:Niche positioning in legacy industrial hydrogen compression stations undergoing phased replacement.
By volume, centrifugal configurations lead. By growth pace, diaphragm architectures are expanding most quickly.
End User:
Customer procurement authority concentrates among fleet-scale operators seeking unified sourcing across vehicle and infrastructure assets.
- Automotive:Heavy-duty trucking electrification via proton exchange membrane fuel cells compresses vendor selection cycles. German and California fleet operators bundle onboard vehicle pumps with station hardware under single-source contracts, elevating service terms to parity with technical specifications.
- Chemical Processing:Ammonia and methanol production facilities in the US Gulf Coast and Rotterdam harbor zones require continuous-duty circulation for hydrogen feedstock delivery. Process licensors specify API-compliant sealing architectures that extend qualification timelines.
- Power Generation:Grid-scale hydrogen storage pilots in South Korea and Germany specify long-duration electrochemical compression integration.
- Aerospace:Auxiliary power unit applications drive magnetic bearing adoption for zero-lubricant operation at altitude.
Automotive end-use commands the largest installed base. Chemical processing applications show the steepest margin expansion trajectory.
Technology:
Technology selection tracks pressure-duty requirements and maintenance accessibility constraints across deployment environments.
- Mechanical:Mature centrifugal and positive-displacement architectures dominate 30-700 bar industrial applications. Japanese infrastructure consortia under METI hydrogen roadmaps validate these configurations against 20,000-hour endurance protocols for station deployment.
- Magnetic:Bearing suspension systems eliminate mechanical wear surfaces and lubricant contamination risks. California fleet specifications for 700-bar delivery loops accelerate automotive-grade cost engineering of aerospace-derived designs.
- Electrochemical:Solid-state compression without moving parts attracts R&D allocation for long-duration energy storage installations.
- Thermodynamic:Ionic liquid-based systems challenge mechanical pumps in laboratory purity-critical applications.
Mechanical technology retains volume leadership. Magnetic configurations are gaining share fastest in premium heavy-duty segments.
Application:
Application-specific purity thresholds and pressure profiles fragment vendor platform strategies across certification regimes.
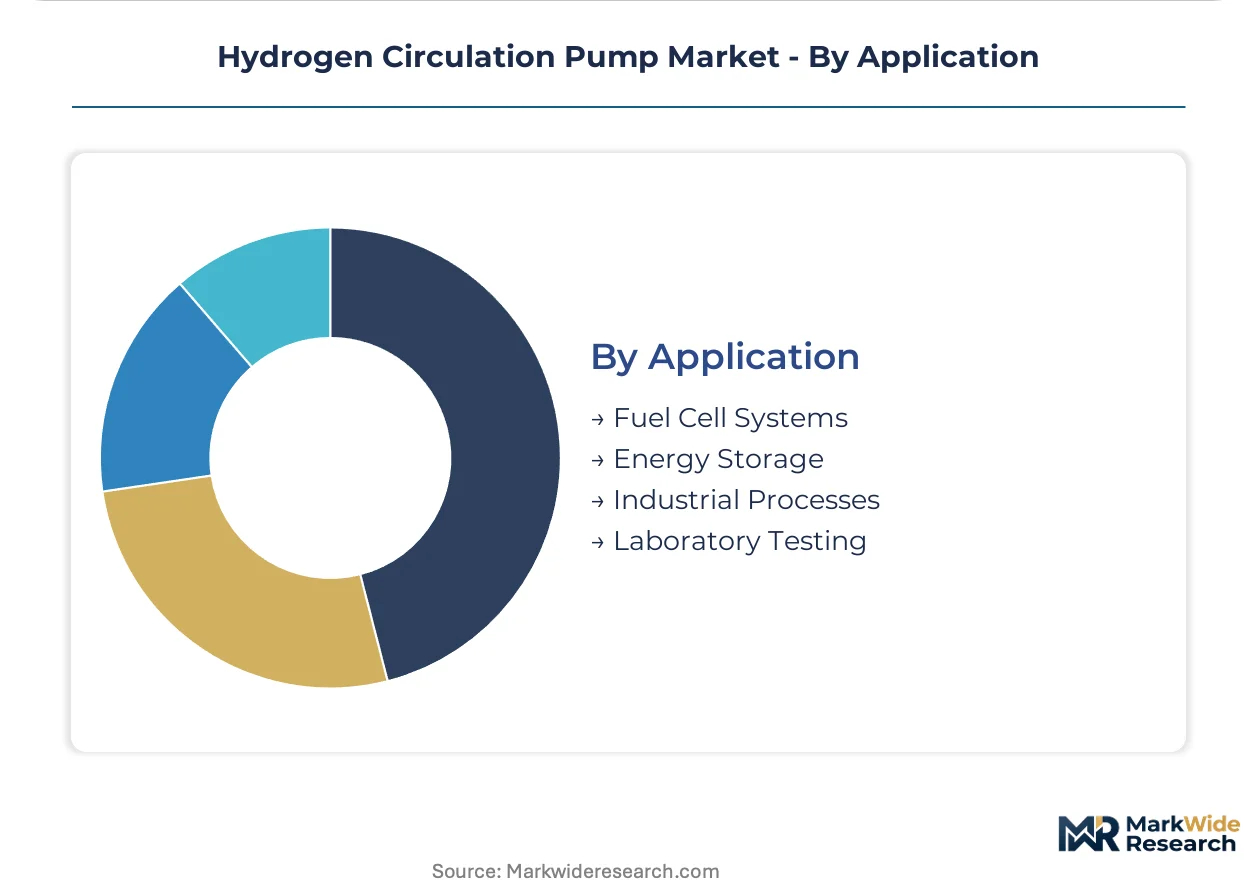
- Fuel Cell Systems:Onboard vehicle and refueling station circulation demands 99.97% hydrogen purity with real-time leak detection integration. EU F-Gas Regulation compliance for sealant materials and Japan METI safety standards create divergent approval pathways that extend product launch timelines.
- Laboratory Testing:Research and pilot-scale electrolyzer validation requires hermetic sealing and contamination control exceeding industrial norms. South Korean KGS certification and EU REACH frameworks mandate redundant testing cycles for elastomer compatibility.
- Energy Storage:Grid-scale hydrogen storage pilots specify electrochemical compression for 20,000-hour maintenance intervals.
- Industrial Processes:Ammonia synthesis and steel decarbonization applications anchor demand for high-flow, moderate-pressure duty cycles.
Fuel cell systems represent the dominant revenue concentration. Laboratory testing applications exhibit the most rapid specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German autobahn hydrogen corridors and California interstate networks anchor procurement volumes for high-pressure circulation hardware, while Japanese infrastructure consortia accelerate qualification windows ahead of 2027 completion targets.
Germany
Heavy-duty trucking electrification along autobahn corridors concentrates demand for 700-bar refueling infrastructure. The EU F-Gas Regulation mandates fluorinated sealant phase-out, compelling pump manufacturers to validate hydrogen-compatible elastomer alternatives. Industrial clusters in North Rhine-Westphalia and Bavaria host electrolyzer manufacturing hubs that anchor circulation hardware procurement.
United States
California fleet operators bundle onboard vehicle pumps with station hardware under single-source contracts exceeding prior transactional norms. The Inflation Reduction Act hydrogen production tax credits accelerate green hydrogen electrolysis clusters in Texas and the Pacific Northwest. Houston-Gulf Coast ammonia production facilities require continuous-duty circulation for hydrogen feedstock delivery.
Japan
METI hydrogen safety standards now mandate real-time leak detection integration with station control systems, compressing supplier qualification windows. Infrastructure consortia in Kanto and Kansai regions accelerate procurement of compliant hardware ahead of corridor completion targets. Ebara Corporation leverages centrifugal pump heritage to anchor long-term supply relationships with domestic hydrogen infrastructure consortia.
South Korea
KGS certification requirements for hydrogen circulation hardware fragment product platform strategies and delay market entry timelines. Grid-scale hydrogen storage pilots in the Seoul Capital Area specify long-duration electrochemical compression integration. Pilot-scale electrolyzer testbeds in Busan-Ulsan drive replacement-part subscription models for diaphragm pump architectures.
India
National hydrogen mission targets and PLI scheme incentives for electrolyzer manufacturing create procurement demand in emerging production clusters. The Bureau of Indian Standards develops hydrogen safety protocols that will shape certification requirements for circulation hardware. Gujarat and Maharashtra industrial corridors host planned green hydrogen hubs that will anchor regional demand concentration.
Hydrogen Circulation Pump Market Competitive Landscape
On the supply side, the industry is consolidating around vendors capable of multi-year service contracts and performance guarantees. Tiered competitive positioning separates firms with captive field service networks from modular component suppliers. Three archetypes dominate: precision fluid-handling specialists with diaphragm heritage, integrated motion-control conglomerates with sealing portfolios, and centrifugal pump incumbents from industrial fluid systems. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with R&D allocation toward magnetic bearing suspension and electrochemical compression technologies.
Among precision fluid-handling specialists, KNF Neuberger occupies a position exemplifying hermetic sealing expertise for laboratory and pilot-scale applications where purity thresholds exceed industrial norms. Parker Hannifin Corporation represents the integrated motion-control archetype, sustaining engineering credibility through sealing and motion-control portfolio breadth across North American fuel cell test facilities. Ebara Corporation anchors the centrifugal pump incumbent tier, leveraging industrial fluid systems heritage to secure long-term supply relationships with Japanese hydrogen infrastructure consortia.
| Leading Market Players |
|---|
| Air Liquide Advanced Technologies |
| Bronkhorst High-Tech |
| Ebara Corporation |
| Dongel Industry |
| Iwaki Co. Ltd. |
| Nikkiso Co. Ltd. |
| KNF Neuberger |
| Asahi Kasei Corporation |
| Parker Hannifin Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in precision-machined sealing surfaces across German and Japanese supplier bases compresses lead times and elevates pricing power for qualified vendors capable of meeting EU F-Gas and METI compliance thresholds. Fleet operators seeking 700-bar hardware for heavy-duty trucking corridors now accept premium positioning in exchange for guaranteed availability and embedded service contracts.
Pricing Analysis
Certification level creates the primary spread between compliant and non-compliant hardware tiers. Three-tier pricing structure across premium, standard, and economy levels bundles predictive maintenance telemetry at the premium tier while transactional spot purchases concentrate in laboratory diaphragm segments. Cost compression in standard-grade centrifugal configurations intensifies as Korean and Chinese suppliers enter with simplified sealing architectures. Chemical processing procurement teams exhibit highest price sensitivity due to API compliance overhead, whereas automotive fleet operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and China for high-nickel stainless steel castings dominates supply chain risk calculations for pump manufacturers. Precision machining capacity concentrates in Germany, Japan, and South Korea, with raw material feedstock drawing from Indonesian nickel and Australian cobalt jurisdictions. Single-source vulnerability in magnetic bearing assemblies sourced from aerospace-tier suppliers threatens production scaling for heavy-duty fuel cell applications. Distribution runs through hydrogen infrastructure consortia and OEM procurement teams rather than open aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation along German autobahn and California interstate corridors concentrates procurement authority among fewer buyers with unified vehicle-infrastructure sourcing mandates. This buyer-power shift elevates service-contract terms to parity with technical specifications.
For Market Incumbents: Pre-empt electrochemical compression substitution by accelerating magnetic bearing cost-engineering programs targeting 15,000-hour maintenance intervals. Anchor long-term supply relationships through captive field service networks in hydrogen corridor geographies. Defend against emerging Korean suppliers by deepening certification investment under Japan METI and South Korea KGS protocols. For New Entrants and Emerging Players: Build out modular diaphragm pump architectures for India's emerging green hydrogen hubs where Bureau of Indian Standards protocols remain under development. Target laboratory testing segments in South Korean pilot-scale electrolyzer testbeds where hermetic sealing requirements exceed industrial norms. Pursue replacement-part subscription models as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision fluid-handling specialists with established aftermarket service infrastructures. Long-term viability over the next decade hinges on magnetic bearing and electrochemical compression R&D pipelines rather than mechanical heritage alone. Acquisition target archetype: mid-cap diaphragm pump vendors with validated elastomer portfolios and existing KGS or METI approvals. Monitor electrochemical compression pilot deployments as the inflection signal for mechanical pump displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Cost Engineering | Automotive-grade adaptation of aerospace designs enables 15,000-hour intervals for California fleet specifications. |
| Multi-Year Service Contract Expansion | German heavy-duty operators now bundle station and onboard pump maintenance under unified availability guarantees. |
| Alternative Elastomer Validation | EU F-Gas compliance for fluorinated sealant substitutes creates first-mover positioning in refueling infrastructure procurement. |
| Real-Time Leak Detection Integration | Japan METI mandates fiber-optic sensing arrays, compressing supplier qualification windows ahead of corridor completion. |
| Electrochemical Compression R&D | Solid-state architectures without mechanical wear surfaces target 20,000-hour maintenance intervals for grid-scale storage. |
Research Methodology
Cross-validation between primary interviews with fuel cell system engineers, hydrogen infrastructure procurement leads, and aftermarket service directors anchors the qualitative findings against secondary validation from SEC filings, EU F-Gas regulatory submissions, and METI hydrogen roadmap documentation. Bottom-up triangulation of vendor production capacities and top-down calibration against electrolyzer manufacturing forecasts ensures dimensional consistency across the analysis window.
Calibration against historical penetration rates in proton exchange membrane fuel cell deployments and electrochemical compression pilot announcements informs the analytical framework. Segmentation dimensions span pressure rating, pump architecture, end-use industry, and regional regulatory cluster. CAGRs derive from modeled unit economics of refueling station buildouts and fleet electrification timelines, with hydrogen purity thresholds and certification protocol evolution as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Korean suppliers or accelerated electrochemical compression commercialization would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Centrifugal Pumps Machines Market