
 Telescopic Tool Boxes Market | 2026-2036
Telescopic Tool Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Telescopic Tool Boxes Market Analytics
Automotive fleet maintenance is consolidating its share of telescopic tool box procurement as dealerships and independent repair chains standardize mobile technician kits. Stanley Black & Decker leverages its multi-brand distribution network to sustain shelf presence across retail and industrial channels. Snap-on Incorporated dominates the premium automotive segment through company-owned route sales operations that control direct technician access. Milwaukee Tool competes aggressively in the cordless-integrated storage category, extending its battery-platform ecosystem into portable organization systems.
Telescopic tool boxes employ extendable drawer or slide-out tray mechanisms, typically fabricated from cold-rolled steel, aluminum extrusions, or structural polypropylene, to maximize volumetric efficiency within constrained footprints. The primary commercial purpose centers on protecting calibrated hand tools, power equipment, and diagnostic instruments during transit across distributed work environments. Heavy-duty steel configurations anchor the value pool due to durability premiums and longer replacement cycles in commercial construction. Aluminum variants capture growing share among electricians and HVAC technicians where weight reduction directly improves daily transport economics. Plastic and composite materials occupy the entry-level tier, serving DIY enthusiasts and residential trades with lower duty-cycle requirements.
FCC equipment authorization rules govern radio-frequency tool tracking modules increasingly embedded in high-end units, while OSHA workplace safety standards dictate load-rating disclosures and tip-prevention design for mobile storage on elevated surfaces. EPA REACH compliance for surface coatings and chemical treatments constrains material sourcing flexibility for manufacturers serving European-bound product lines. Stakeholders must monitor evolving interoperability demands between tool storage and connected inventory management platforms as job-site digitization accelerates.
Market Dynamics
Modular job-site workflows are compressing replacement cycles for portable storage equipment as construction contractors prioritize volumetric efficiency and rapid deployment capabilities over legacy fixed-cabinet systems.
Growth Catalysts
- OSHA toolbox safety mandates:Steel-grade certification requirements in the United States are forcing specification upgrades across commercial construction fleets, accelerating replacement demand for compliant units.
- Automotive fleet maintenance standardization:Dealerships and independent repair chains are consolidating mobile technician kit procurement, creating volume pull-through for integrated storage systems.
- Aluminum extrusion adoption:Electricians and HVAC technicians are migrating toward lightweight configurations that reduce daily transport burden and improve job-site mobility economics.
Market Restraints
- Cold-rolled steel price volatility:Input cost swings for heavy-duty steel configurations compress margin stability for manufacturers serving commercial construction's durability premium segment.
- Supply concentration in Asian aluminum smelting:Primary aluminum sourcing dependencies create vulnerability to export duty fluctuations and energy cost shocks in key producer jurisdictions.
- Structural polypropylene performance ceiling:Entry-tier plastic variants face substitution pressure from composite alternatives where load-bearing requirements exceed material specifications.
Strategic Opportunities
- Connected inventory management convergence:Radio-frequency tracking modules embedded in high-end units are capturing data integration budgets as job-site digitization accelerates.
- EPA REACH compliance positioning:Surface coating reformulation capabilities for European-bound product lines create differentiation against regional competitors lacking chemical treatment flexibility.
- DIY channel e-commerce penetration:Residential trades and enthusiast segments remain underpenetrated by direct-to-consumer platforms offering configuration customization.
Industry Challenges
- FCC equipment authorization timelines:Radio-frequency module certification delays compress product launch windows for connected storage variants targeting technician fleet deployments.
- Interoperability standardization gaps:Proprietary battery-platform ecosystems from power tool manufacturers fragment portable organization system compatibility, forcing multi-platform inventory duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telescopic Tool Boxes Market |
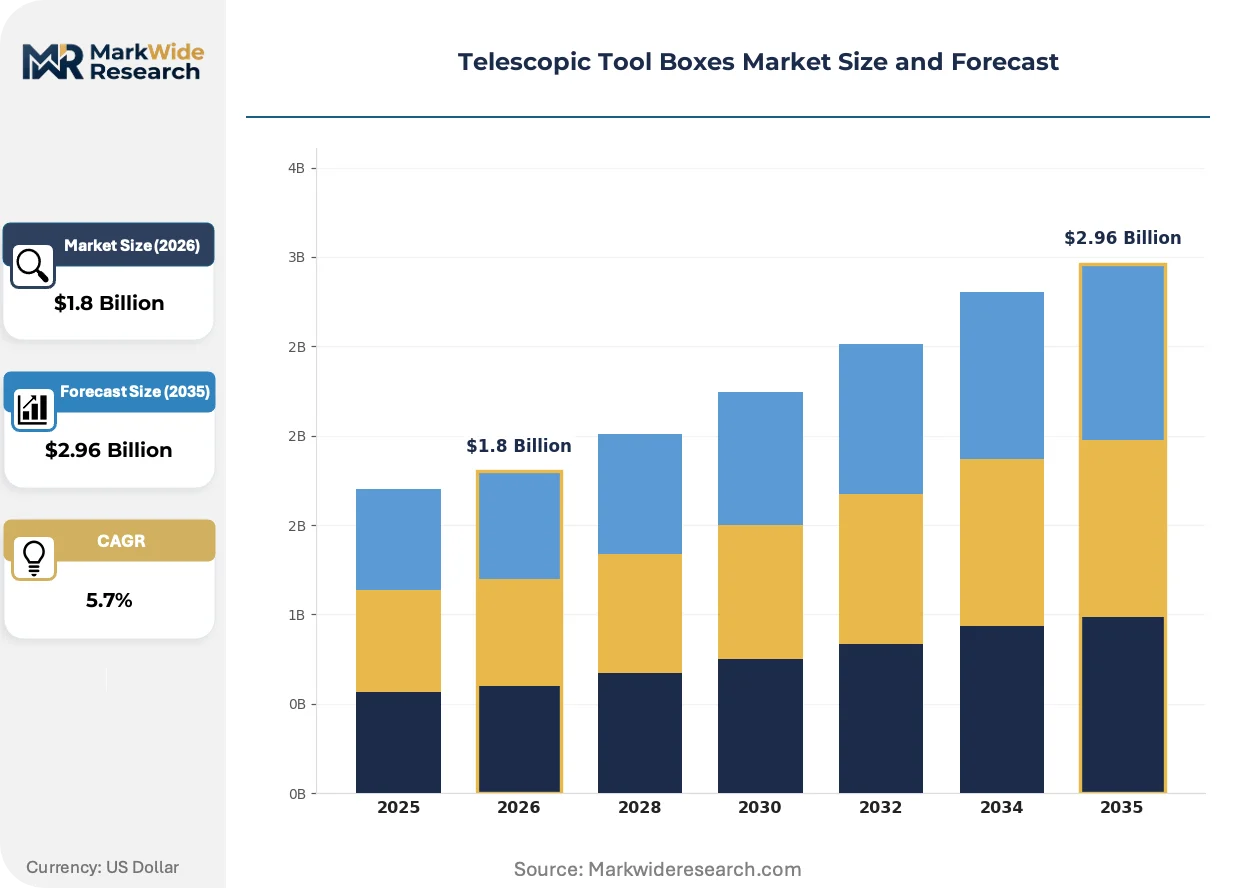
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Folding, Stackable, Heavy-Duty Material: Plastic, Aluminum, Steel, Composite Size: Compact, Medium, Large, Extra-Large End User: Construction, Automotive, DIY Enthusiasts, Electricians |
| Companies Covered | Stanley Black & Decker, Snap-on Incorporated, Montezuma, Apex Tool Group, ZARGES, DEWALT, Milwaukee Tool, Matco Tools Corporation, Kennedy Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telescopic Tool Boxes Market Evolving Landscape
Active reshaping of this market centers on three vectors: hardware modularity enabling rapid configuration changes, regulatory pressure on material traceability, and procurement centralization altering channel economics.
Cordless-integrated storage architecture is modularizing around battery-platform ecosystems, with manufacturers extending proprietary power systems into portable organization hardware. Automotive service departments and mobile technician fleets are adopting these configurations fastest, consolidating around single-brand tool and storage compatibility. This convergence is compressing standalone storage vendor margins while rewarding ecosystem-integrated suppliers with replacement pull-through.
REACH surface coating compliance is constraining European-bound production flexibility, with ECHA chemical treatment disclosures now mandatory for imported metal fabrications. Manufacturers serving EU markets must reformulate surface treatments or establish captive coating capacity within the trade bloc. Heavy-duty steel configurations face the steepest compliance burden due to corrosion protection requirements.
Route sales direct access models are displacing traditional distribution for premium automotive segments, with technician-facing representatives controlling specification decisions at the point of use. Independent repair chains and dealership service operations are consolidating procurement authority under fleet managers who negotiate enterprise terms. This concentration is most visible in the United States, where company-owned sales operations capture specification influence before competitive bidding occurs.
Telescopic Tool Boxes Market Segmentation
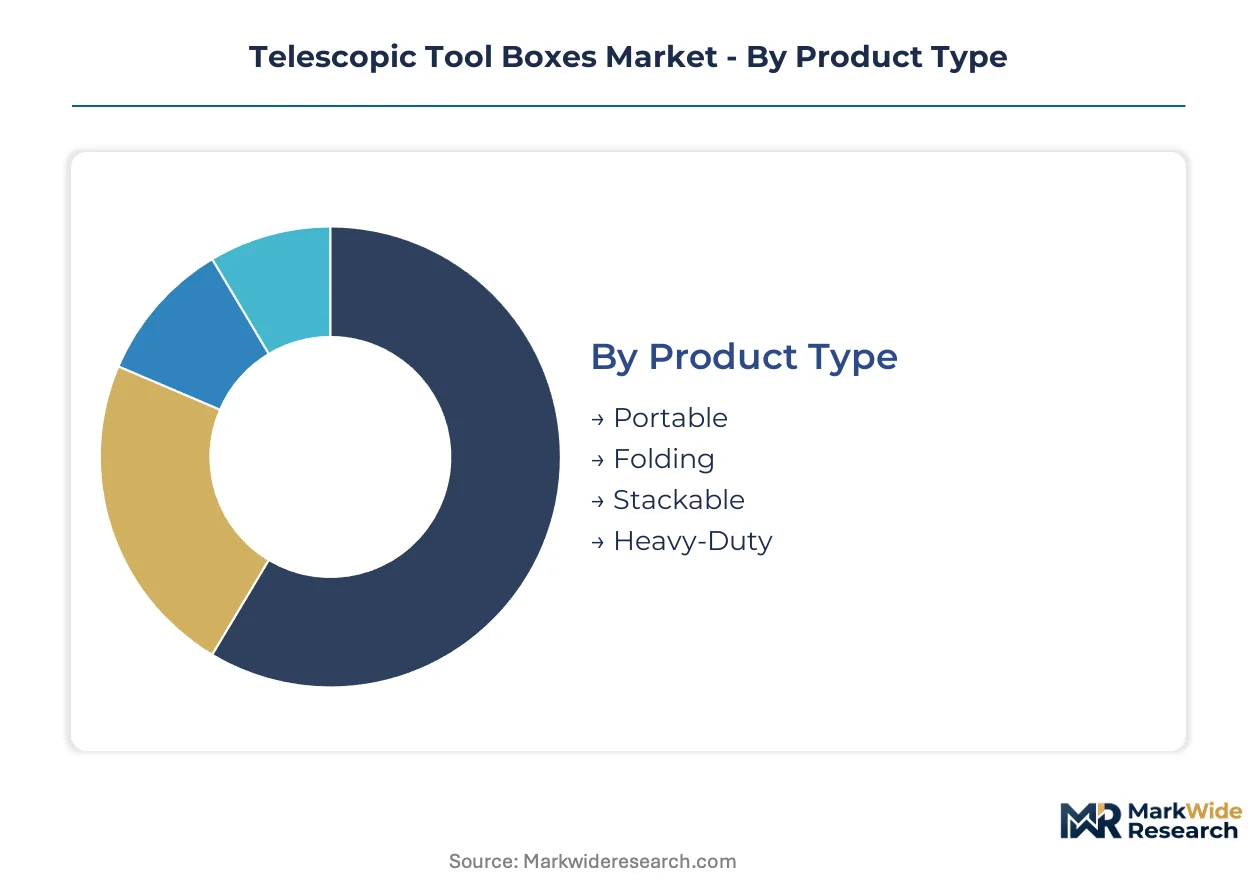
Telescopic tool box manufacturers segment offerings across four critical dimensions that determine load capacity, transport economics, and regulatory compliance. Product type and material selection drive the volume-premium split, while end-user concentration shapes channel strategy and replacement cycle timing.
Product Type:
The volume-premium split in this category separates high-mobility portable units from specification-grade heavy-duty configurations anchoring commercial construction value pools.
- Heavy-Duty:Cold-rolled steel construction with reinforced drawer slides supports calibrated power tools and diagnostic instruments across distributed job-sites. Construction contractors in the United States specify these units under OSHA toolbox safety mandates, forcing fleet-wide replacement cycles for compliant certification.
- Portable:Lightweight aluminum or composite housings with telescoping handles prioritize single-operator transport between multiple daily work locations. Electricians and HVAC technicians in residential renovation corridors favor these configurations where vehicle payload constraints limit equipment loads.
- Folding:Collapsible sidewall designs reduce empty return volume for technicians serving dispersed service calls. Automotive fleet maintenance operations deploy these for mobile technician kits requiring rapid vehicle loading.
- Stackable:Interlocking base and lid geometry enables vertical storage density in constrained workshop footprints. Independent repair chains standardize these for parts department organization and tool crib inventory density.
Today's leader: Heavy-Duty. Tomorrow's challenger: Portable.
Material:
Application requirements segment this category into weight-critical trades versus durability-prioritized commercial construction, with regulatory pressure on surface coatings adding compliance complexity.
- Steel:Cold-rolled and powder-coated configurations deliver maximum impact resistance and extended service life under continuous commercial use. OSHA certification requirements in the United States concentrate procurement authority with steel-grade suppliers capable of documented load-rating disclosures.
- Aluminum:Extruded alloy construction reduces unit weight by 40-60% versus comparable steel capacity, directly improving daily transport economics for climbing-intensive trades. Electricians servicing multi-story commercial retrofits specify these configurations for stair-accessible job-sites.
- Plastic:Structural polypropylene housings serve entry-tier DIY enthusiasts and residential trades with intermittent duty cycles. Cost positioning enables retail channel penetration where purchase frequency exceeds replacement-driven commercial procurement.
- Composite:Hybrid material formulations combining fiberglass reinforcement with polymer matrices occupy the performance gap between plastic economy and aluminum weight targets. Emerging adoption among specialty contractors balances durability premiums against transport efficiency.
Steel commands specification authority. Aluminum gains share fastest.
Size:
Customer type and vehicle integration requirements determine size selection, with fleet standardization compressing SKU proliferation among enterprise buyers.
- Large:Full-width truck bed configurations accommodate comprehensive tool inventories for lead technicians supervising multi-person crews. Commercial construction fleet managers in the United States negotiate enterprise terms for standardized large-unit deployment.
- Medium:Crossover utility vehicle compatible dimensions balance capacity against cabin intrusion for independent operators serving mixed residential-commercial portfolios. HVAC service technicians favor these for diagnostic equipment plus hand tool storage.
- Compact:Passenger vehicle trunk-compatible footprints enable rapid response technicians without dedicated service vans. Automotive dealership express maintenance lanes deploy these for oil change and inspection specialists.
- Extra-Large:Trailer-mounted or job-site stationary applications support master tool sets for specialized trades requiring infrequent transport. Infrastructure replacement contractors specify these for extended-duration commercial projects with on-site security.
Medium units dominate unit volume. Large configurations capture value concentration.
End User:
Procurement centralization varies sharply across end-user segments, altering margin structure and channel economics for manufacturers.
- Construction:General and specialty contractors drive replacement demand through modular job-site workflow adoption, prioritizing rapid deployment over fixed-cabinet systems. OSHA compliance mandates in the United States accelerate specification upgrades for steel-grade units across commercial fleets.
- Automotive:Dealership service departments and independent repair chains consolidate mobile technician kit procurement under fleet managers, creating volume concentration for integrated storage system suppliers. Route sales direct access models capture specification influence before competitive bidding.
- Electricians:Licensed electrical contractors and integrated building systems specialists prioritize weight reduction for daily transport efficiency across multi-story job-sites. Aluminum configurations capture disproportionate share in this segment versus construction averages.
- DIY Enthusiasts:Residential trades and home improvement hobbyists exhibit fragmented procurement through retail and e-commerce channels, with configuration customization demand remaining underpenetrated by direct-to-consumer platforms.
Construction anchors replacement volume. Automotive concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production flows as manufacturers seek jurisdictions with favorable coating compliance costs and steel-grade certification reciprocity. Cost-of-compliance gaps between OSHA-mandated U.S. specifications and ECHA-regulated European surface treatments are reshaping sourcing footprints across the value chain.
United States
Residential renovation cycles and commercial infrastructure replacement sustain replacement-driven procurement across construction fleets. OSHA toolbox safety mandates enforce steel-grade certification requirements that accelerate specification upgrades for compliant units. Texas and Florida construction corridors concentrate demand for heavy-duty configurations serving modular job-site workflows.
Germany
Industrial machinery maintenance and automotive service operations drive specification-grade procurement through integrated fleet management systems. ECHA REACH surface coating compliance constrains imported metal fabrications, favoring domestic coating capacity investments. Baden-Württemberg manufacturing clusters anchor production for EU-bound aluminum extrusion variants.
China
Domestic construction equipment demand and export-oriented fabrication capacity expand simultaneously across cold-rolled steel and aluminum processing. GB standards for tool storage safety create parallel certification tracks distinct from OSHA or CE marking requirements. Yangtze River Delta industrial zones concentrate structural polypropylene molding for entry-tier export markets.
Japan
Precision manufacturing maintenance and automotive technician fleets prioritize lightweight configurations for high-frequency transport scenarios. METI industrial safety guidelines influence load-rating disclosure practices across domestic suppliers. Nagoya-Toyota industrial corridor concentrates demand for cordless-integrated storage systems aligned with battery-platform ecosystems.
India
Infrastructure build-out and residential construction expansion create pull-through for portable storage across distributed contractor networks. BIS certification requirements for metal fabrications are tightening import specifications for European and Chinese suppliers. Maharashtra and Gujarat industrial zones are emerging as domestic assembly points for aluminum and composite variants.
Telescopic Tool Boxes Market Competitive Landscape
Portfolio diversification dominates the current landscape as established tool manufacturers extend proprietary battery-platform ecosystems into portable organization hardware. The vendor base clusters around three strategic tiers: ecosystem-integrated power tool suppliers capturing specification authority through cordless convergence, route-sales direct access operators controlling technician-facing distribution, and regional metal fabricators serving price-sensitive construction procurement. Two competitive moves define current positioning: backward integration into aluminum extrusion and surface coating capacity to manage REACH compliance costs, and strategic partnerships between storage specialists and inventory management software providers to capture connected-tool-crib budgets.
Among ecosystem-integrated suppliers, Stanley Black & Decker and Milwaukee Tool exemplify the convergence strategy extending power tool battery platforms into portable storage hardware. Snap-on Incorporated occupies a distinct position within the premium automotive tier through technician-facing route sales operations. These three anchors represent divergent channel strategies—multi-brand retail distribution, proprietary retail networks, and direct fleet access—each capturing different procurement centralization patterns across end-user segments.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Snap-on Incorporated |
| Montezuma |
| Apex Tool Group |
| ZARGES |
| DEWALT |
| Milwaukee Tool |
| Matco Tools Corporation |
| Kennedy Manufacturing |
| Others |
Value Network & Pricing Analysis
Automotive fleet managers consolidating mobile technician kit procurement under enterprise terms anchor pricing power in this market, compressing margins for standalone storage vendors while rewarding ecosystem-integrated suppliers with volume commitments and replacement pull-through.
Pricing Analysis
Distributor margins in the 15-25% range separate premium automotive route sales from retail channel markups. Three-tier pricing structure across premium, standard, and economy levels reflects steel-grade certification tier and battery-platform ecosystem compatibility. Pricing pressure stems from cold-rolled steel input cost volatility compressing heavy-duty configuration margins. DIY enthusiasts through e-commerce channels exhibit highest price sensitivity, while automotive fleet managers prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates under OSHA certification requirements are reshaping sourcing footprints for U.S.-bound steel-grade units. Cold-rolled steel supply draws from integrated mills in the United States, Germany, and Japan, while aluminum extrusion feeds from Yangtze River Delta and Baden-Württemberg clusters. Structural polypropylene resin faces single-source vulnerability from Asian petrochemical complexes. Distribution runs through multi-brand retail networks, company-owned route sales operations, and direct-to-consumer platforms serving fragmented DIY demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where OSHA toolbox safety mandates and ECHA REACH surface coating compliance create sustained specification upgrade cycles across commercial fleets.
For Market Incumbents: Anchor specification authority through captive aluminum extrusion and surface coating capacity investments that manage REACH compliance costs. Defend against cordless-integrated storage convergence by deepening battery-platform ecosystem partnerships. Prioritize certification documentation capabilities that satisfy OSHA load-rating disclosure requirements.
For New Entrants and Emerging Players: DIY enthusiasts remain underserved by configuration-customization platforms, presenting white-space opportunity for direct-to-consumer entrants. Specialty contractors balancing durability and transport efficiency represent the most penetrable segment for composite material variants. Target inventory management software partnerships to capture connected-tool-crib integration budgets.
For Investors and Strategic Acquirers: Power tool manufacturers are the most active acquirer in this space, seeking portable organization assets to complete battery-platform ecosystems. Long-term viability favors targets with European coating compliance capabilities and aluminum extrusion flexibility. Watch FCC equipment authorization timeline compression as inflection indicator for connected storage variant launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captures weight-reduction segment growth while insulating against Yangtze River Delta energy cost shocks. |
| REACH Surface Coating Compliance Investment | Unlocks European procurement access where ECHA chemical treatment disclosures are mandatory. |
| Cordless-Integrated Storage Platform Launch | Extends proprietary battery ecosystems into portable organization hardware for automotive technician fleets. |
| Route Sales Network Expansion | Captures specification influence before competitive bidding in dealership service department procurement. |
| Inventory Management Software Partnership | Positions for connected-tool-crib budgets as job-site digitization accelerates radio-frequency tracking adoption. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and emerging markets, with primary inputs from each region combining interviews with fleet procurement managers, maintenance directors at commercial contractors, automotive service operations heads, and aluminum extrusion specialists. Secondary validation draws from OSHA regulatory filings, ECHA substance databases, customs trade records, and SEC disclosures from listed tool manufacturers. Bottom-up demand modeling and top-down supply triangulation reconcile volume estimates across the analysis window.
Rate-of-change decomposition separates replacement cycle compression from specification upgrade premiums across product type, material grade, end-user vertical, and regional regulatory cluster dimensions. CAGRs derive from segment-level volume trajectories weighted by price realization trends. Forecast inputs include construction activity indices, automotive service bay counts, and technician fleet deployment schedules without year-specific anchoring.
Underlying measurement precision varies by segment; heavy-duty steel configurations and automotive fleet procurement carry tighter precision than fragmented DIY channel estimates. Forecasts reflect assumptions around OSHA mandate enforcement continuity and aluminum smelting energy cost stability. Regulatory timeline delays, steel price volatility spikes, and battery-platform ecosystem fragmentation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Portable Boring Machines Market
Tools
Coil Thread Insert Market
Tools
Industrial Hand Tools Market
Tools
Key Cutting Machine Market
Tools
Ripper Market
Tools
Metal Forming Tools Market
Tools
Asia Pacific Power Tools & Hand Tools Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Gear Hobbing Cutter Market
Tools
Broaching Tools Market
Tools
Mold Racks Market
Tools
Global Zero Point Clamping System Market
Tools
Handheld Blower Market
Tools
Welding Guns Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Concrete Saw Market