
 North America Power Tools Market | 2026-2036
North America Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
North America Power Tools Market Insights
Professional contractors is rotating toward cordless platforms as residential construction and renovation activity intensifies across the United States and Canada. Stanley Black & Decker leverages its DeWalt brand strength to dominate the professional cordless segment through deep hardware store distribution. Robert Bosch GmbH anchors its position with brushless motor engineering and battery interoperability across its 18V platform. Techtronic Industries Co Ltd competes aggressively through Milwaukee Tool's RedLithium battery ecosystem and trade-focused marketing.
North America power tools encompass electrically or pneumatically driven handheld and stationary devices engineered for cutting, drilling, fastening, grinding, and surface preparation, typically operating at voltages from 12V to 60V DC or 120V AC with torque ratings spanning 100 to 1,500 inch-pounds depending on application. Cordless drills and rotary hammers lead product type revenue due to universal jobsite dependency and battery platform loyalty, while angle grinders represent a mature category with replacement-driven demand. Brushless technology commands premium positioning as it extends motor life and reduces maintenance intervals for fleet operators.
OSHA workplace safety standards and NHTSA commercial vehicle equipment rules shape product certification requirements and channel compliance obligations across the United States. EPA regulations on battery disposal and recycling influence lithium-ion pack design and end-of-life program investments by manufacturers. CSA Group standards in Canada create a parallel certification pathway that affects cross-border product launches. Stakeholders must monitor evolving cordless platform consolidation and battery chemistry transitions as determinants of replacement cycle timing and brand switching economics.
Market Dynamics
Cordless lithium-ion platforms are decomposing the corded tool installed base across residential and commercial jobsites, with battery interoperability emerging as the decisive lock-in mechanism for fleet purchasing decisions.
Growth Catalysts
- OSHA silica dust rules:The Occupational Safety and Health Administration's respirable crystalline silica standard mandates dust-collection systems on grinders and rotary hammers, accelerating replacement of legacy equipment in concrete and masonry trades.
- Brushless motor engineering:Electronic commutation eliminates brush wear and thermal losses, extending motor life beyond 2,000 hours and reducing maintenance costs for fleet operators managing 50-plus tool inventories.
- Residential renovation intensity:Single-family housing stock aging beyond 40 years in Ontario, Quebec, and the Great Lakes states sustains demand for cordless fastening and cutting tools among remodeling contractors.
Market Restraints
- Lithium carbonate price volatility:Battery cell input costs fluctuate with South American and Australian mining output, compressing gross margins on 18V and 12V pack sales during commodity spikes.
- Cross-border certification friction:CSA Group testing requirements in Canada create 8-12 week launch delays versus UL listings in the United States, fragmenting product rollout timelines.
- Pneumatic tool residual base:Compressed-air systems retain cost advantages in high-torque fastening applications above 1,000 inch-pounds, limiting cordless penetration in heavy framing and industrial assembly.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring of assembly operations to Baja California and Querétaro reduces landed cost exposure and tariff uncertainty for tools sold throughout the NAFTA region.
- Battery-as-a-service models:Subscription-based pack replacement programs lock in multi-year contractor relationships while generating recurring revenue streams alongside hardware sales.
- EPA lithium-ion recycling mandates:End-of-life collection requirements create competitive differentiation for manufacturers with closed-loop material recovery infrastructure.
Industry Challenges
- Skilled technician scarcity:Brushless motor diagnostics and battery management system repair require electronics expertise that traditional small-engine mechanics lack, straining authorized service networks.
- Platform consolidation risk:Contractors face stranded asset exposure when manufacturers phase out legacy battery form factors, complicating fleet standardization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Power Tools Market |
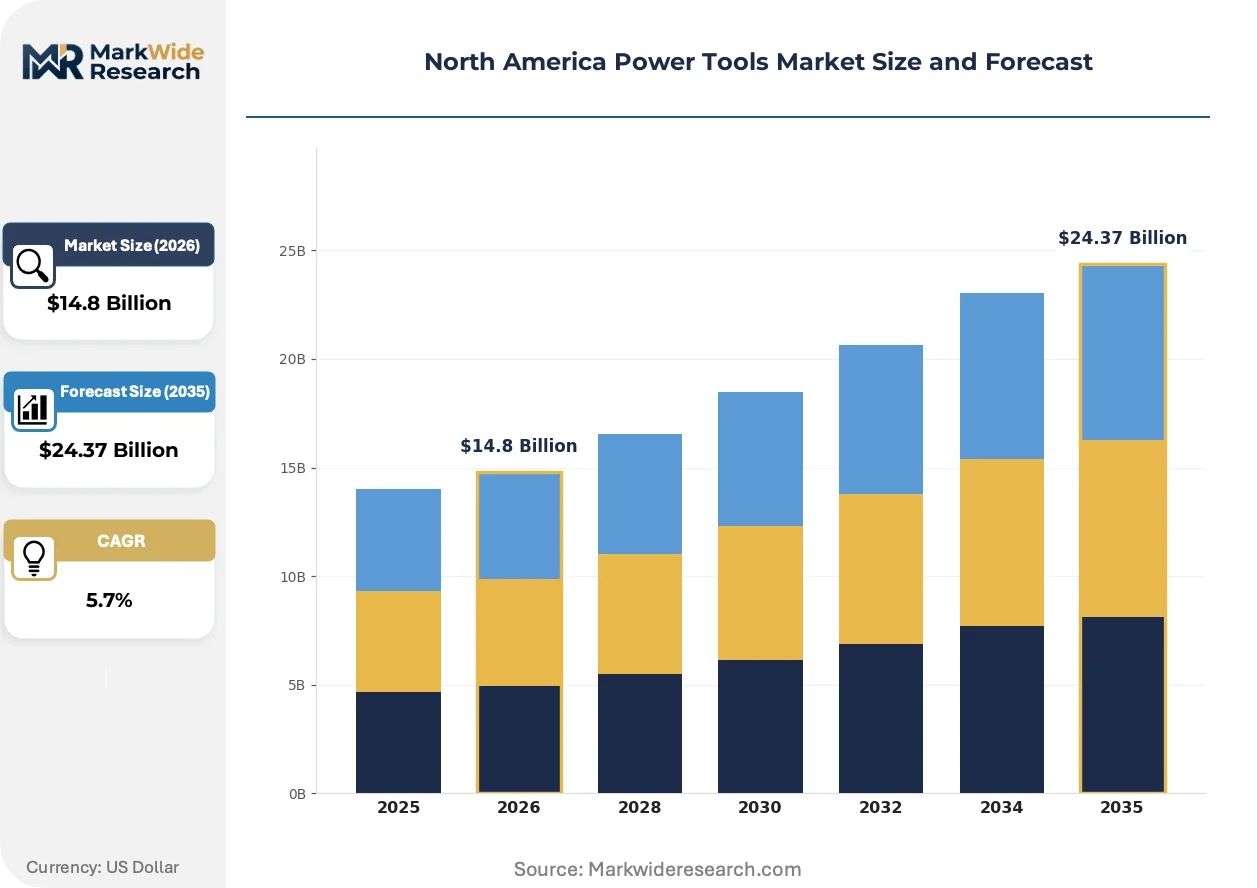
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Drills, Electric Saws, Angle Grinders, Rotary Hammers End User: Construction, Automotive, Manufacturing, DIY Enthusiasts Technology: Brushless, Lithium-Ion, Pneumatic, Hydraulic Distribution Channel: Online Retailers, Hardware Stores, Wholesalers, Direct Sales |
| Companies Covered | Stanley Black & Decker, Robert Bosch GmbH, Techtronic Industries Co Ltd, Emerson Electric Co, Ingersoll Rand, Makita Corp, Snap-on Incorporated, Apex Tool Group, Hilti Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Power Tools Market Trends and Innovations
Intelligent power management and connected tool ecosystems are redefining competitive advantage, with data capture and predictive maintenance capabilities separating premium platforms from commodity alternatives.
Brushless motor technology is decomposing the brushed motor aftermarket by eliminating wearable components and enabling sealed housings for harsh-environment operation. Fleet managers in commercial construction are specifying brushless platforms for 80% of new cordless purchases. This shift compresses replacement parts revenue while elevating initial equipment price points.
EPA hazardous waste regulations for spent lithium-ion packs are mandating manufacturer-funded takeback programs and domestic recycling partnerships. Tool OEMs must integrate reverse logistics into distribution networks. The compliance burden falls heaviest on mid-tier brands lacking scale for captive recycling infrastructure.
Hardware store loyalty programs and direct-to-contractor e-commerce are fragmenting the dealer channel that historically controlled professional tool distribution. Independent distributors in Texas and Florida are losing share to big-box pro desks and manufacturer-owned mobile retail units. This channel rotation is most advanced in metropolitan construction corridors with high contractor density.
North America Power Tools Market Segmentation
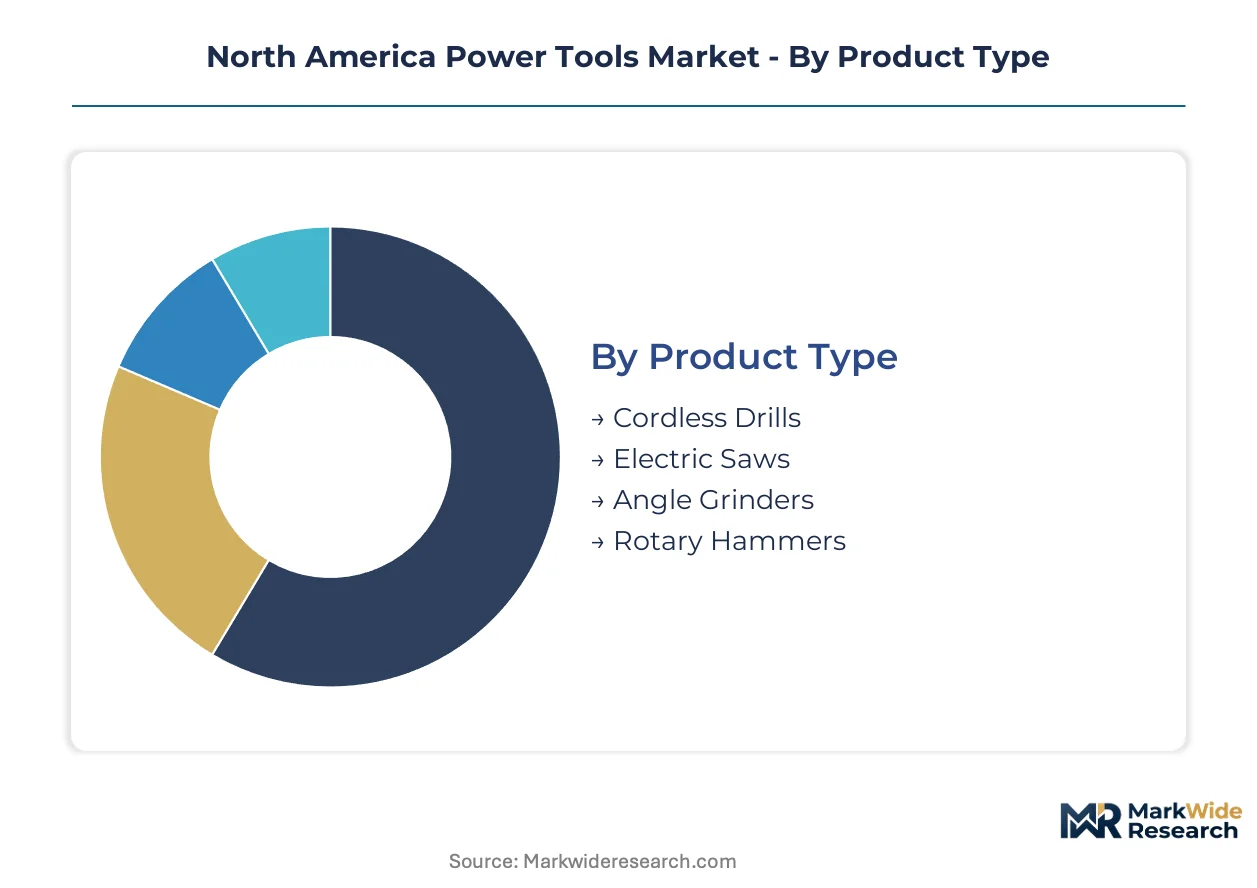
Power tool segmentation in North America reveals distinct demand profiles across professional and consumer tiers, with cordless platforms and lithium-ion chemistry driving category redefinition. Understanding these divides exposes where replacement cycles concentrate and where platform loyalty locks in recurring revenue.
Product Type:
Cordless drills and rotary hammers dominate domestic contractor procurement, while electric saws and angle grinders retain stronger export-linked manufacturing footprints in Ontario and Michigan industrial clusters.
- Cordless Drills:These 12V to 20V DC platforms combine clutch-adjustable torque delivery with interchangeable battery systems. Demand concentrates among residential renovation crews across Texas, Florida, and California where mobility between jobsites eliminates corded alternatives. OSHA silica compliance is accelerating brushless motor upgrades in this category.
- Electric Saws:Circular and reciprocating variants operate at 120V AC or 60V DC battery platforms. Manufacturing clusters in Wisconsin and Illinois supply both domestic big-box retailers and cross-border distribution into Canadian provinces, with blade compatibility driving brand stickiness.
- Angle Grinders:Pneumatic and cordless 4.5-inch to 9-inch disc tools for metal fabrication and concrete finishing.
- Rotary Hammers:SDS-plus and SDS-max chuck systems delivering 2 to 8 joules of impact energy for masonry drilling.
Cordless drills hold the largest share; momentum sits with rotary hammers as silica dust regulations force fleet replacements.
End User:
Construction contractors generate the highest volume per account, while automotive and manufacturing segments impose stricter torque calibration and traceability requirements that fragment supplier qualification.
- Construction:Residential and commercial builders operating 50-plus tool fleets with standardized battery platforms. Demand clusters in Sun Belt metropolitan corridors where housing starts sustain continuous equipment turnover. Brushless motor specifications now appear in 80% of new cordless procurement.
- Automotive:Assembly plants and aftermarket collision repair shops requiring torque-controlled fastening with audit trails. Michigan, Ohio, and Ontario vehicle manufacturing hubs drive specification-heavy procurement with multi-year supply agreements.
- Manufacturing:Metal fabrication and industrial assembly operations balancing pneumatic legacy systems against cordless conversion economics.
- DIY Enthusiasts:Homeowners and hobbyists purchasing 12V entry-level platforms through hardware store loyalty programs.
Construction commands absolute volume; automotive delivers the steepest expansion trajectory as electric vehicle assembly retools demand precision fastening systems.
Technology:
Cost tier stratification separates premium brushless and lithium-ion platforms from maintenance-intensive pneumatic and hydraulic alternatives still prevalent in heavy industrial settings.
- Brushless:Electronically commutated motors eliminating brush wear and enabling sealed housings for dust-intensive environments. Professional fleet managers in concrete and masonry trades specify these for 2,000-plus hour service life. Thermal management circuitry adds 25-40% cost premium over brushed equivalents.
- Lithium-Ion:18650 and 21700 cylindrical cell configurations delivering 2.0Ah to 12.0Ah capacity with fade-free discharge curves. Demand concentrates where battery platform interoperability locks contractors into multi-tool ecosystems. South American mining volatility for lithium carbonate inputs compresses margins during commodity spikes.
- Pneumatic:Compressed-air systems retaining cost advantages in high-torque fastening above 1,000 inch-pounds.
- Hydraulic:Fluid-power actuation for demolition and heavy construction equipment attachments.
Lithium-ion platforms dominate new unit sales; brushless engineering captures the fastest margin expansion as fleet operators amortize premium pricing through reduced downtime.
Distribution Channel:
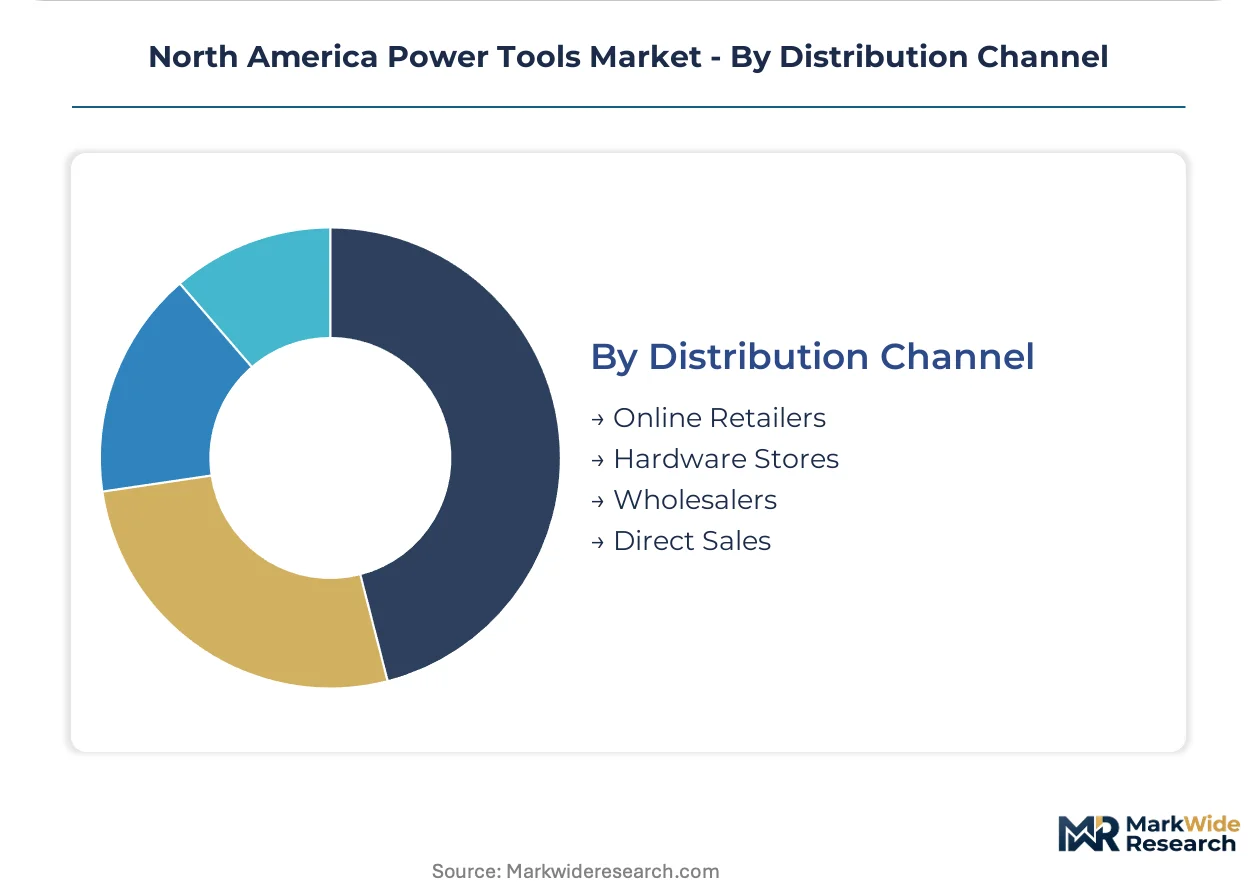
Channel concentration varies sharply by customer scale, with independent contractors fragmenting across hardware stores and online platforms while national accounts consolidate through direct sales and wholesale distribution.
- Online Retailers:Amazon, manufacturer direct-to-consumer sites, and construction supply marketplaces. These channels capture DIY and small contractor segments with price transparency and rapid delivery. Mobile-optimized purchasing now accounts for the majority of 12V platform transactions under $300.
- Hardware Stores:Home Depot, Lowe's, and independent pro desks with contractor loyalty programs and same-day pickup. Texas and Florida metropolitan corridors show the highest contractor density per store, driving localized inventory depth for DeWalt and Milwaukee flagship displays.
- Wholesalers:Industrial distributors serving multi-state construction firms with volume pricing and consignment inventory.
- Direct Sales:Manufacturer-owned mobile retail units and factory representative networks for national account management.
Hardware stores retain the largest transaction volume; online retailers are climbing the fastest as procurement shifts to smartphone-based reordering for consumables and accessories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional contractors and residential builders concentrate purchasing power across the United States, Canada, and Mexico, with battery platform standardization driving cross-border procurement patterns among multi-national construction firms.
United States
Sun Belt metropolitan corridors in Texas and Florida sustain continuous equipment turnover from housing starts and renovation intensity. OSHA silica dust standards mandate dust-collection systems on concrete and masonry tools, accelerating fleet replacements. Manufacturing clusters in Wisconsin and Illinois supply domestic big-box retailers with circular and reciprocating saw platforms.
Canada
Ontario and Quebec generate significant volume from aging single-family housing stock exceeding 40 years, driving demand for cordless fastening systems among remodeling contractors. CSA Group certification requirements create 8-12 week launch delays versus UL listings, fragmenting product rollout timelines. Toronto and Montreal construction corridors show concentrated contractor density for hardware store pro desks.
Mexico
Baja California and Querétaro assembly operations expand nearshoring capacity to reduce landed cost exposure and tariff uncertainty for NAFTA-region distribution. Mexican automotive assembly plants in Aguascalientes and Guanajuato impose torque-controlled fastening requirements with audit trails, driving specification-heavy procurement. Border state construction activity links to US contractor supply chains through integrated battery platform ecosystems.
North America Power Tools Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with deep hardware store distribution and battery platform ecosystems. Three to four multinational holdings control the majority of professional-grade cordless segments through brand portfolio layering. Strategic archetypes separate battery-platform integrators, brushless motor specialists, and pneumatic legacy defenders. Competitive moves concentrate on cross-brand battery interoperability claims and Mexico manufacturing expansion to hedge tariff exposure.
Among diversified industrial holdings, Stanley Black & Decker, Robert Bosch GmbH, and Techtronic Industries Co Ltd exemplify distinct strategic positions. The Stanley Black & Decker structure leverages DeWalt brand equity through hardware store dominance. Robert Bosch GmbH anchors engineering credibility with German-origin precision manufacturing associations. Techtronic Industries Co Ltd occupies a position as a Hong Kong-listed holding company competing through Milwaukee Tool trade-focused positioning. These three represent the battery-platform consolidation dynamic forcing smaller competitors toward niche specialization or private-label supply arrangements.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Techtronic Industries Co Ltd |
| Emerson Electric Co |
| Ingersoll Rand |
| Makita Corp |
| Snap-on Incorporated |
| Apex Tool Group |
| Hilti Corporation |
| Others |
Pricing and Supply Chain Analysis
OSHA silica dust certification requirements gate both supplier qualification and price tier separation in the North America power tools market, forcing manufacturers to absorb compliance costs into premium brushless motor platforms while corded alternatives face margin compression from regulatory obsolescence.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate battery pack procurement, exposing margins to South American mining volatility. Three-tier pricing structure across premium brushless, standard brushed, and economy corded levels separates fleet operators from DIY buyers. Pricing pressure stems from commodity-driven cell cost spikes that manufacturers cannot fully pass through to price-sensitive residential contractors. Construction contractors managing 50-plus tool inventories show lowest price sensitivity due to total-cost-of-ownership calculations, while hardware store DIY segments demand aggressive promotional pricing.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production for battery platforms, while Mexico's Baja California and Querétaro regions concentrate final tool assembly. Raw material dependencies span lithium carbonate from Chile and Argentina, rare earth magnets from China, and copper windings from domestic smelters. Tariff exposure on Chinese-sourced cells creates margin vulnerability for mid-tier brands lacking Mexico manufacturing alternatives. Distribution runs through hardware store pro desks and direct-to-contractor mobile units serving metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America power tools market rewards manufacturers with captive battery chemistry expertise and closed-loop recycling infrastructure, while generalist assemblers face stranded asset risk from platform consolidation.
For Market Incumbents: Shield core fleet relationships through battery-as-a-service subscription models that lock contractors into multi-year pack replacement cycles. Deepen backward integration into lithium-ion cell assembly to reduce exposure to South American carbonate volatility. Prioritize CSA Group pre-certification investments to compress the 8-12 week launch delays that fragment cross-border rollouts against faster UL-listed competitors. For New Entrants and Emerging Players: Lead with aftermarket battery compatibility solutions for stranded legacy platform users facing manufacturer phase-outs. Target Ontario and Quebec remodeling contractors with 12V entry-level platforms through independent hardware store channels underserved by flagship brand displays. Emphasize EPA-compliant takeback programs as differentiation against mid-tier competitors lacking recycling infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pneumatic tool specialists losing share to cordless conversion. Five-to-ten year viability hinges on battery platform interoperability rather than proprietary lock-in strategies. Monitor CSA Group certification backlog lengths as inflection indicator for brands gaining or losing Canadian market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Interoperability | Milwaukee Tool's RedLithium ecosystem demonstrates lock-in power across 200-plus cordless SKUs. |
| Mexico Manufacturing Expansion | Nearshoring to Querétaro reduces landed cost exposure and NAFTA tariff uncertainty for US-bound production. |
| Brushless Motor Engineering Investment | DeWalt's sealed-housing designs extend service life beyond 2,000 hours in silica-intensive concrete applications. |
| Closed-Loop Recycling Infrastructure | EPA hazardous waste mandates favor OEMs with domestic lithium-ion material recovery partnerships. |
| Direct-to-Contractor Mobile Retail | Manufacturer-owned units bypass independent distributors in Texas and Florida high-density corridors. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, hardware store pro desk managers, battery platform engineers, and construction procurement officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, OSHA enforcement databases, EPA hazardous waste program records, and customs trade data on lithium-ion cell imports. Bottom-up demand modeling triangulated against top-down manufacturer shipment estimates across the analysis window.
Sensitivity analysis tested forecast outputs against lithium carbonate price volatility scenarios and cordless platform adoption rate variations. Segmentation dimensions modeled include product type, end user tier, motor technology, battery chemistry, and distribution channel. CAGRs derived from replacement cycle timing, housing start correlations, and regulatory compliance-driven fleet turnover assumptions. Brushless motor penetration curves and CSA Group certification timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in OSHA silica standards and EPA battery disposal mandates; material policy shifts would require re-modeling. Commodity price spikes, cross-border tariff restructuring, or accelerated platform obsolescence could compress or extend replacement cycles. Recalibration cycles align with material shifts in lithium supply economics and cordless torque threshold breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Taps and Dies Market
Tools
Hand Saw Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Floor Saw Market
Tools
Log Splitters Market
Tools
Allen Key Market
Tools
Striking Tools Market
Tools
Machine Tools Market
Tools
Tool Storage Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Brazing Torch Market
Tools
Thread Milling Machine Market
Tools
Power Nibbler Market
Tools
US Power Tools Market
Tools
China Power Tools and Hand Tools Market
Tools
Asia Pacific Power Tools Market