
 Drywall Tool Market | 2026-2036
Drywall Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Drywall Tool Market Analytics
Commercial contractors are gaining share over DIY enthusiasts as the buyer base is bifurcating toward professional-grade equipment with higher duty cycles and serviceability. DEWALT leverages its cordless battery ecosystem to cross-sell drywall tools into existing construction portfolios. Milwaukee Tool sustains innovation velocity through brushless motor platforms that reduce thermal fatigue during extended taping operations. Bosch competes on precision manufacturing, anchoring its position in pneumatic sanding systems favored by European specialty crews.
Drywall tools encompass cutting, fastening, finishing, and lifting implements engineered to process gypsum wallboard panels with dimensional tolerances typically within one-sixteenth of an inch, serving the core function of accelerating interior enclosure timelines while reducing joint compound consumption. Taping tools command premium positioning due to their direct impact on seam quality and callback rates, while electric technology segments are capturing share from manual equivalents as jobsite electrification standards tighten. Sanders represent a mature margin pool where dust-extraction integration differentiates replacement purchases, and hybrid systems that combine pneumatic power with electric controls are emerging as the fastest-growing technology configuration among high-volume contractors.
OSHA enforces respiratory protection and silica exposure limits that compel manufacturers to integrate HEPA-class dust collection into sanding and cutting tools, while the EPA regulates volatile organic compound emissions from joint compounds that indirectly shape tool selection for application efficiency. ISO 28927 and ANSI standards govern vibration and noise exposure, forcing ergonomic redesigns that extend product development timelines. Stakeholders must monitor cordless platform consolidation decisions by major power tool brands, as battery compatibility investments will lock in contractor loyalty across multi-trade fleets for the remainder of the forecast horizon.
Market Dynamics
OSHA silica exposure standards are forcing manufacturers to redesign sanding and cutting tools around HEPA-class dust collection, compressing product development timelines while elevating entry barriers for equipment lacking certified extraction systems.
Growth Catalysts
- OSHA Respiratory Protection Mandates:Contractors across the United States must replace legacy sanding equipment with silica-compliant systems, accelerating replacement cycles for dust-extraction-integrated tools.
- Battery Platform Convergence:Cordless interoperability standards adopted by major power tool brands enable cross-selling into existing construction fleets, reducing switching costs for professional buyers.
- Commercial Construction Square Footage:Nonresidential building expansion in the United States sustains demand for high-duty-cycle taping systems capable of continuous operation.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Battery pack costs fluctuate with raw material availability from concentrated Asian refining operations, pressuring margins on cordless tool lines.
- Joint Compound VOC Regulations:EPA emission limits on volatile organic compounds from finishing materials indirectly constrain tool selection for application efficiency, limiting certain pneumatic system configurations.
- Manual Tool Substitution Persistence:Small-scale residential renovators continue selecting low-cost manual taping tools over automated systems, capping premium segment penetration.
Strategic Opportunities
- Renovation-Intensive Metro Corridors:Aging housing stock in the Northeastern and Midwestern United States generates sustained demand for compact, maneuverable finishing tools optimized for retrofit work.
- ISO 28927 Ergonomic Certification:Vibration and noise standards create differentiation pathways for manufacturers investing in brushless motor platforms that reduce operator fatigue during extended taping operations.
- Hybrid Pneumatic-Electric Convergence:Systems combining pneumatic power density with electronic control interfaces address contractor preferences for familiar power sources with precision adjustment capabilities.
Industry Challenges
- Skilled Taper Labor Scarcity:Experienced finishers capable of optimizing automated taping system settings remain concentrated in established commercial contractor networks, constraining technology transfer to mid-tier operators.
- HEPA Certification Timeline Compression:Third-party testing protocols for dust-collection validation extend product launch schedules, delaying revenue recognition for redesigned sanding platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drywall Tool Market |
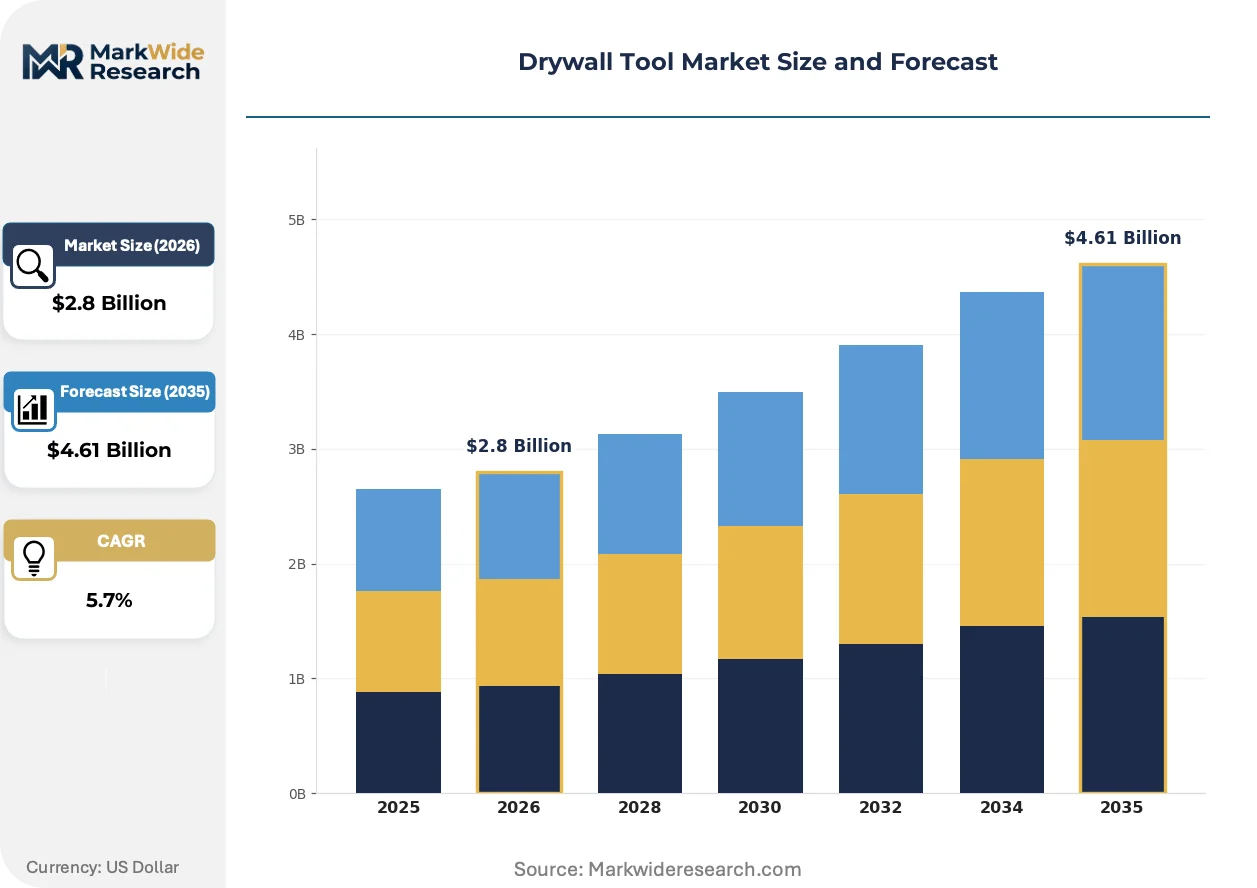
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knives, Sanders, Taping Tools, Lifts End User: Contractors, DIY Enthusiasts, Construction Firms, Remodelers Technology: Manual, Electric, Pneumatic, Hybrid Distribution Channel: Online Retailers, Hardware Stores, Distributors, Wholesalers |
| Companies Covered | TapeTech, DEWALT, Bosch, Milwaukee Tool, Stanley Black & Decker, KNAUF, USG Corporation, Hyde Tool, ProTool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drywall Tool Market Evolving Landscape
Tool electrification and dust-extraction integration are converging to reshape equipment specifications, with professional buyers prioritizing systems that reduce respiratory exposure while maintaining jobsite mobility without tethered power sources.
Brushless motor technology is decomposing the traditional tradeoff between thermal endurance and tool weight in extended taping operations. Commercial contractors operating multi-shift schedules are adopting these platforms for reduced downtime during seam finishing. The technology is decomposing established service intervals by eliminating brush wear as a maintenance trigger.
OSHA silica exposure limits are mandating respiratory protection programs that compel HEPA-class dust collection integration into all sanding and cutting equipment. Manufacturers must redesign housing geometries and airflow paths to achieve certification without compromising ergonomic handling. Specialty contractors in high-volume commercial drywall operations face the steepest compliance costs and are consolidating purchases around pre-certified tool platforms.
Equipment-as-a-service arrangements are emerging among national commercial contractors seeking to convert capital expenditures into operating costs. Traditional distributor networks are responding with rental and lease programs bundled with maintenance and certification services. This shift concentrates most visibly in the United States, where large-scale nonresidential developers prioritize balance-sheet flexibility over asset ownership.
Drywall Tool Market Segmentation
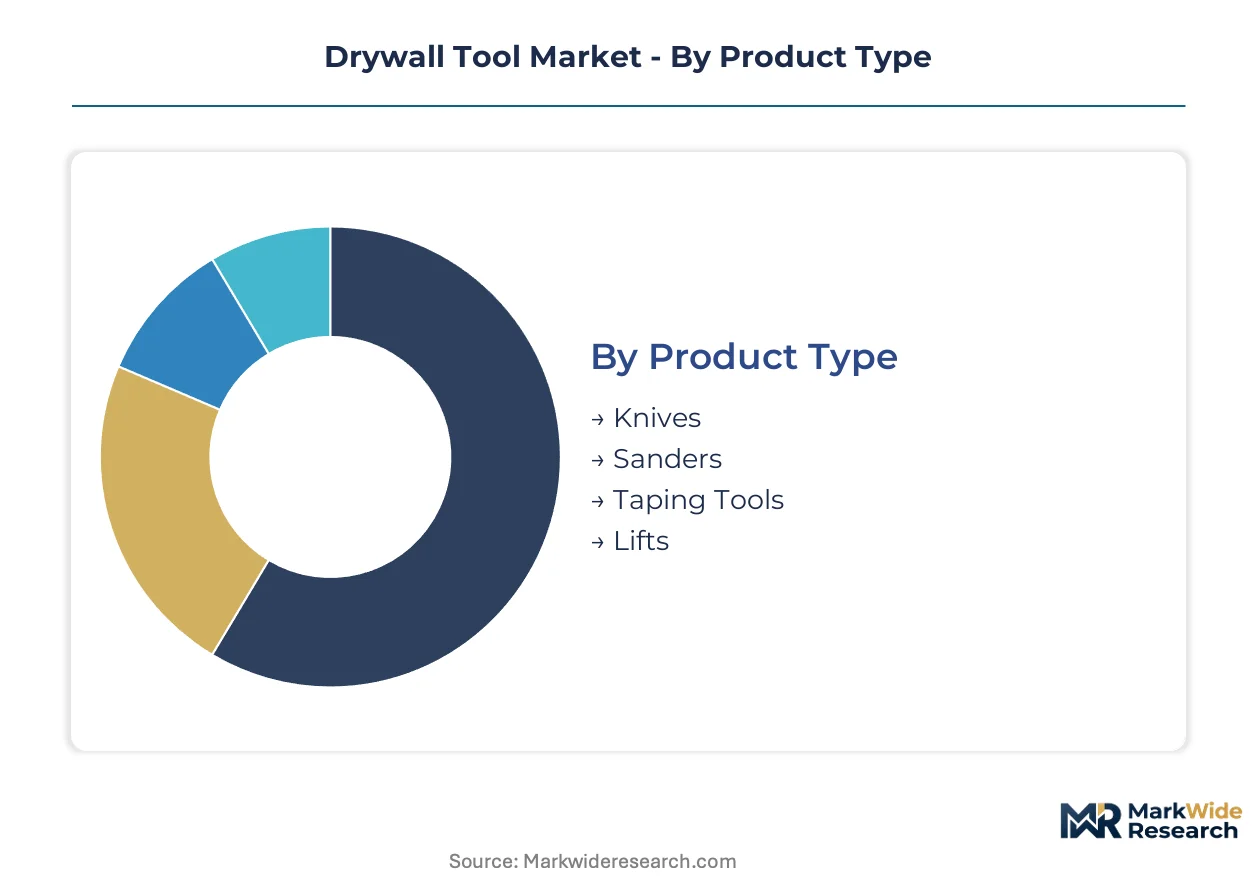
Drywall tool procurement patterns diverge sharply across user sophistication levels and jobsite power availability. Segmentation reveals where manual alternatives persist against electrification pressure and which channels capture premium versus volume transactions.
Product Type:
Substitution pressure from cordless platforms is most acute in sanding and taping categories where dust extraction and speed advantages compound.
- Taping Tools:Automated banjo guns and compound pumps apply joint material with calibrated thickness control. Demand clusters with commercial contractors in the United States facing labor scarcity and callback liability exposure.
- Sanders:Orbital and pole-mounted finishing platforms integrate HEPA vacuum ports to meet OSHA silica mandates. Replacement cycles accelerate where respiratory protection programs are audited.
- Knives:Utility and jab saw variants retain manual dominance in retrofit residential work where power access is constrained and tool cost sensitivity peaks.
- Lifts:Panel hoists and rolling jacks reduce two-person hanging crews to single-operator configurations. Rental penetration is highest among renovation specialists in aging metro housing stock.
Taping tools retain volume leadership; sanders hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-equipped fleets from price-sensitive occasional users.
- Contractors:Specialty drywall crews operating multi-shift schedules prioritize brushless motor endurance and battery platform standardization across trades. Serviceability and parts availability drive vendor selection.
- Construction Firms:General contractors managing mixed-trade portfolios specify interoperable cordless ecosystems to reduce charger redundancy and cross-train labor pools.
- Remodelers:Retrofit-focused operators demand compact, maneuverable equipment for confined residential spaces with finished surfaces requiring damage avoidance.
- DIY Enthusiasts:Homeowner renovators select entry-level manual and corded electric tools through retail channels, with purchase frequency tied to housing turnover rates.
Contractors command the premium tier; construction firms are expanding procurement scale fastest.
Technology:
Application intensity determines power source selection, with continuous operation favoring pneumatic density and intermittent use tilting toward cordless convenience.
- Electric:Lithium-ion battery platforms eliminate generator tethering and enable overhead work without trip hazards. Brushless variants reduce thermal shutdown frequency during extended taping sequences.
- Pneumatic:Compressed air systems deliver sustained torque for high-volume sanding without battery swap interruption. European specialty crews favor these configurations for finishing precision.
- Hybrid:Combined pneumatic-electric architectures merge air power density with electronic control interfaces. Adoption concentrates among commercial contractors seeking familiar power sources with programmable adjustment.
- Manual:Hand-powered knives, mud pans, and hawks persist where capital constraints or low utilization rates undermine powered tool economics.
Electric platforms lead replacement volume; hybrid configurations are climbing the fastest.
Distribution Channel:
Supply concentration shapes access patterns, with national accounts consolidating through direct distributor relationships while fragmented buyers route through retail.
- Distributors:Industrial supply houses bundle tool procurement with maintenance contracts and certification documentation. National commercial contractors leverage these relationships for fleet standardization.
- Hardware Stores:Big-box and independent retailers serve DIY and small contractor segments with immediate availability and return flexibility. Inventory depth concentrates on manual and entry-powered categories.
- Wholesalers:Regional building material suppliers integrate tools into gypsum board and joint compound orders for job-site delivery consolidation.
- Online Retailers:E-commerce platforms capture specification-driven purchases where technical documentation and comparative reviews influence selection. Battery platform compatibility verification is a critical conversion factor.
Distributors retain the largest transaction value; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial contractors dominate procurement across mature construction economies, with regional demand patterns tracking nonresidential square footage expansion and renovation intensity in aging housing stock.
United States
Residential renovation spending and commercial construction square footage sustain replacement cycles for high-duty-cycle taping systems. OSHA silica exposure standards compel HEPA-class dust collection integration across sanding and cutting equipment. Tool demand concentrates in the Northeastern and Midwestern metro corridors where aging housing stock generates retrofit work.
Germany
Precision manufacturing standards and commercial nonresidential development drive adoption of pneumatic sanding systems favored by specialty finishing crews. REACH chemical regulations influence joint compound formulation and application tool selection. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia anchor equipment distribution networks serving Central European contractors.
China
Urbanization-driven interior construction and infrastructure investment sustain volume demand for panel lifting and fastening tools. GB standards and MIIT industrial policies shape product certification requirements for domestic and export markets. Manufacturing concentration in the Yangtze River Delta supplies regional construction equipment needs while serving export channels.
Canada
Commercial building expansion in Ontario and Quebec sustains professional-grade tool procurement, particularly cordless platforms for cold-weather jobsite flexibility. Health Canada respiratory protection guidelines align with OSHA-equivalent silica management protocols. Vancouver and Toronto metro areas concentrate renovation-specialist contractor networks driving compact finishing tool demand.
United Kingdom
Commercial refurbishment activity and residential retrofit programs sustain demand for maneuverable finishing equipment in confined urban spaces. CE marking and UKCA post-Brexit conformity requirements extend product validation timelines for imported equipment. London and Southeast England construction corridors concentrate high-volume drywall contractor operations.
Drywall Tool Market Competitive Landscape
Player mix skews toward diversified power tool conglomerates with construction equipment portfolios, creating a tiered structure where battery ecosystem breadth separates premium positioning from commodity manual tool suppliers. Three strategic archetypes dominate: cordless platform leaders leveraging cross-trade battery interoperability, pneumatic precision specialists serving European commercial crews, and manual tool heritage brands defending retail channel presence. Competitive moves concentrate on cordless platform consolidation decisions and HEPA certification pre-emption for silica-compliant product lines.
Within the diversified power tool tier, DEWALT and Milwaukee Tool exemplify platform-centric strategies where battery ecosystem lock-in drives contractor loyalty across multi-trade fleets. Bosch occupies a precision-manufacturing position anchored in European pneumatic system preferences. TapeTech represents the specialized taping equipment archetype, serving commercial contractor networks with application-specific finishing systems rather than broad construction portfolios.
| Leading Market Players |
|---|
| TapeTech |
| DEWALT |
| Bosch |
| Milwaukee Tool |
| Stanley Black & Decker |
| KNAUF |
| USG Corporation |
| Hyde Tool |
| ProTool |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for brushless motor assemblies and lithium-ion cell packs concentrate procurement leverage with battery platform architects, compressing margin capture for tool assemblers lacking upstream cell supply agreements. This lead-time structure rewards cordless ecosystem consolidators while penalizing single-product specialists facing component allocation constraints.
Pricing Analysis
Current-generation brushless taping systems command substantial premiums over prior-generation brushed motor equivalents, while next-generation hybrid pneumatic-electric configurations are entering at price points between established tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor endurance rating and dust-extraction certification grade. Pricing pressure stems from lithium raw material volatility feeding into battery pack costs, with DIY enthusiasts exhibiting highest price sensitivity and commercial contractors demonstrating lowest sensitivity due to labor-cost-offset calculations.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production, while Taiwan and Japan concentrate brushless motor controller fabrication for drywall tool OEMs. Tool housings and precision-machined aluminum components draw from Mexican and Vietnamese metalworking clusters. Single-source vulnerability in rare-earth magnet supply creates exposure for motor performance specifications. Distribution runs through industrial supply houses and big-box retail networks, with direct distributor relationships capturing fleet standardization contracts from national commercial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across buyer sophistication tiers creates specialist positioning opportunities, as the bifurcation between cordless platform consolidators and manual tool heritage brands leaves mid-tier electrification gaps underserved.
For Market Incumbents: Consolidate battery platform loyalty through charger interoperability investments and HEPA certification pre-emption for silica-compliant sanding lines. Threats from emerging pneumatic-electric hybrid specialists demand backward integration into motor controller design to preserve margin structure against component commoditization. For New Entrants and Emerging Players: OSHA HEPA fast-track certification for compact retrofit-focused sanders opens immediate channel access. The remodeler segment in Northeastern United States metro corridors represents the most penetrable white space, with online technical documentation and battery compatibility verification serving as the critical go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cordless platform economics will compress standalone tool vendor viability within a multi-trade fleet standardization window. Acquisition targets should feature established distributor relationships in commercial contractor networks. The signal to watch is battery platform consolidation announcements by major power tool conglomerates, which will trigger cascade procurement decisions across multi-trade construction fleets.| Strategic Initiative | Industry Significance |
|---|---|
| HEPA Certification Pre-emption | OSHA silica enforcement accelerates replacement cycles for certified sanding platforms. |
| Battery Platform Interoperability Investment | Cross-trade charger standardization locks contractor loyalty across multi-fleet tool purchases. |
| Backward Integration into Motor Controllers | In-house brushless design protects thermal endurance specifications from component commoditization. |
| Equipment-as-a-Service Launch | National commercial contractors convert capital expenditures to operating costs through rental bundling. |
| Hybrid Pneumatic-Electric Development | Electronic control interfaces merge with air power density for precision-adjustment contractor preferences. |
Research Methodology
The analysis maps taping tools, sanding platforms, cutting implements, and lifting equipment, each validated through commercial contractor procurement directors, distributor account managers, and OEM product development leads. Primary interview intelligence triangulates against customs trade records, SEC construction equipment segment disclosures, OSHA enforcement activity databases, and power tool industry association shipment data. Bottom-up segment sizing and top-down macro construction spending reconciliation ensure internal consistency.
Forecast outputs were validated against external construction square footage projections and renovation spending indices across the analysis window. Segmentation dimensions modeled include product type, end-user sophistication tier, power source technology, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and electrification penetration curves, with brushless motor adoption rates and HEPA certification timelines serving as primary industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained commercial construction expansion and lithium supply stability assumptions; material deviation in either driver would warrant model refresh. Specific risk factors include tariff restructuring on Chinese battery components and accelerated OSHA enforcement timeline compression. Recalibration cycles align with material shifts in cordless platform consolidation decisions and silica compliance audit intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Surface Planer Market
Tools
Drill Set Market
Tools
Automatic Heat Press Machines Market
Tools
Boring-Milling Machines Market
Tools
Cordless Trim Routers Market
Tools
Hand Saw Market
Tools
Multi Spindle Machines Market
Tools
Bearing Installation Tool Kit Market
Tools
Gear Hobbing Cutter Market
Tools
Power Nibbler Market
Tools
Collated Screws Market
Tools
Floor Saw Market
Tools
Mechanical Springs Market
Tools
Metal Cutting Machine Market
Tools
Rotary Hammer Drill Market
Tools
Squeegee Market