
 Hot Chamber Die Casting Machine Market | 2026-2036
Hot Chamber Die Casting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Chamber Die Casting Machine Market Outlook
Direct equipment sales from manufacturers to tier-one suppliers is fragmenting as Chinese system integrators and Southeast Asian distributors capture middle-tier accounts. Buhler AG leverages its Swiss engineering heritage to sustain premium positioning across European automotive programs. L.K. Technology Holdings Limited anchors volume supply through its Dongguan manufacturing complex, while Idra S.r.l. competes on large-tonnage configurations for structural automotive castings.
Hot chamber die casting machines inject molten metal from an internal gooseneck and nozzle system into hardened steel dies at clamping forces ranging from 50 to 1,000 tons, producing net-shape zinc and magnesium components with cycle times under ten seconds. Zinc-dedicated machines occupy the largest installed base due to established automotive hardware and consumer electronics connector demand, while magnesium configurations represent the fastest-expanding segment as OEMs pursue further mass reduction. Pressure die casting technology dominates revenue contribution, though vacuum-assisted variants command margin premiums for aerospace-grade porosity control.
EPA emissions standards and the EU Green Deal carbon border adjustments are reshaping material selection and energy efficiency requirements for installed machine bases. OSHA lockout-tagout rules and ISO 9001 quality certifications govern retrofit and replacement cycles across North American and European facilities. Stakeholders must weigh magnesium alloy qualification timelines against zinc equipment refresh decisions as regulatory thresholds tighten.
Market Dynamics
Automotive lightweighting mandates and appliance electrification are compressing equipment replacement cycles as zinc alloy specifications tighten and magnesium qualification timelines accelerate across tier-one supplier networks.
Growth Catalysts
- EPA emissions thresholds:US automotive OEMs are expanding zinc die casting capacity for powertrain hardware as Corporate Average Fuel Economy standards drive 15-20% mass reduction targets in underhood components.
- Guangdong electronics cluster:Connector and heat sink demand from appliance OEMs in Dongguan and Shenzhen is pulling dedicated 200-400 ton hot chamber installations for precision zinc housings.
- Vacuum-assisted porosity control:Aerospace-grade quality requirements are penetrating automotive structural castings as porosity specifications tighten below 0.5% for safety-critical brake and steering components.
Market Restraints
- Magnesium feedstock volatility:Primary magnesium ingot prices fluctuate with Chinese smelter output curbs under dual carbon goals, compressing margin visibility for alloy-dedicated machine investments.
- Swiss-German engineering concentration:Premium clamping unit and control system supply concentrates among Alpine region specialists, creating 16-24 week lead time exposure for large-tonnage configurations.
- Zinc equipment refresh timing:Installed base obsolescence cycles collide with magnesium qualification delays as OEMs defer replacement decisions pending alloy specification finalization.
Strategic Opportunities
- Southeast Asian automotive buildout:Thailand and Vietnam passenger vehicle assembly expansion creates greenfield demand for 400-600 ton magnesium-capable machines without legacy zinc infrastructure constraints.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive cast components are incentivizing European in-house die casting investment to preserve OEM supply chain access.
- Real-time shot monitoring:Integration of cavity pressure sensors with machine learning process control is enabling predictive quality assurance that commands 12-18% equipment price premiums.
Industry Challenges
- Magnesium metallurgy expertise scarcity:Qualified process engineers for molten metal handling and oxidation control remain concentrated in Japanese and German supplier ecosystems, constraining operational ramp rates.
- ISO 9001/IATF 16949 certification timelines:New market entrants face 14-18 month quality system accreditation cycles before qualifying for automotive tier-one supplier lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Chamber Die Casting Machine Market |
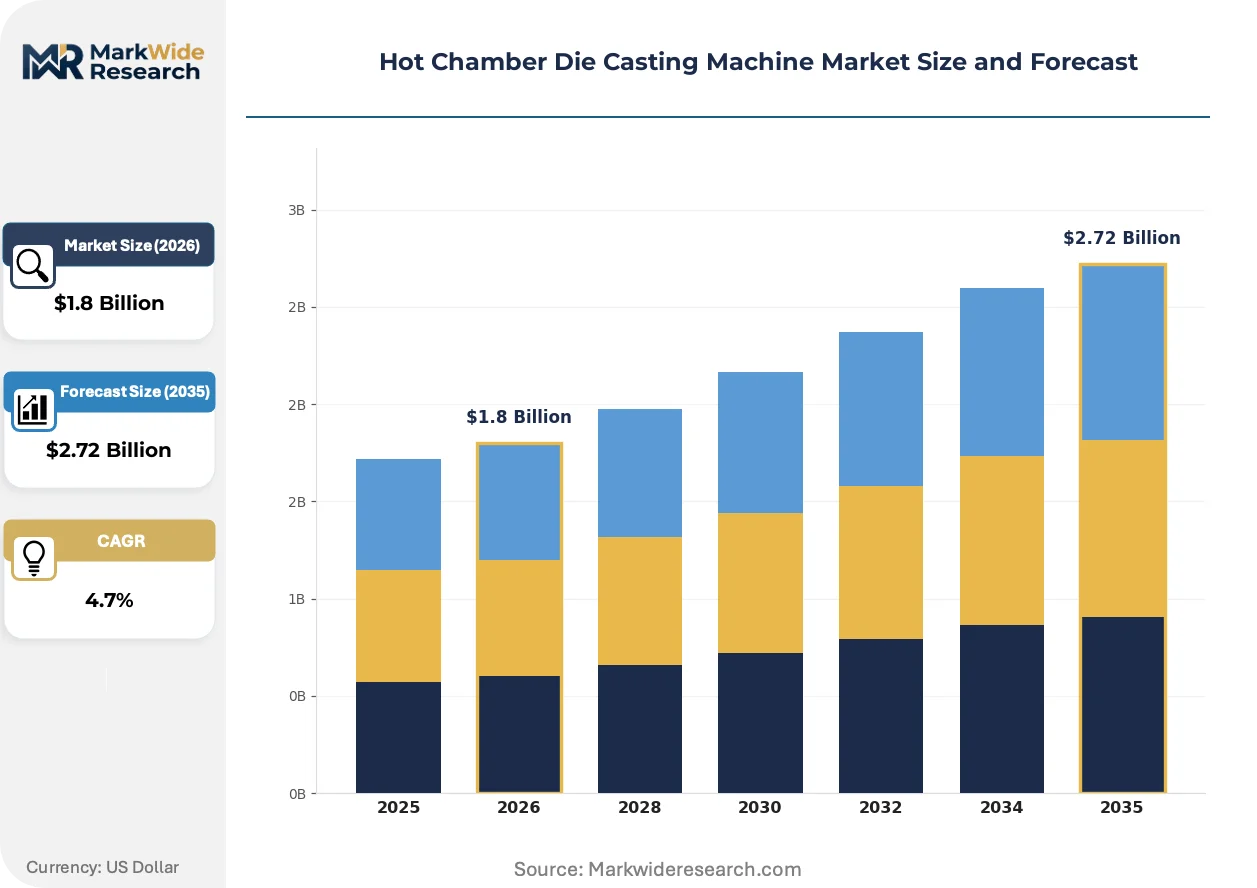
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Zinc, Magnesium, Copper Technology: Gravity Casting, Pressure Die Casting, Vacuum Die Casting, Ingot Casting End User: Aerospace, Automotive Components, Consumer Electronics, Marine Engineering Application: Electrical Parts, Engine Components, Structural Parts, HVAC |
| Companies Covered | Buhler AG, Oskar Frech GmbH, UBE Machinery Inc., Toshiba Machine Co., Ltd., Toyo Machinery & Metal Co., Ltd., Shibaura Machine, L.K. Technology Holdings Limited, Idra S.r.l., Suzhou Sanji Die-Casting Automation System Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Chamber Die Casting Machine Market Strategic Shifts
Equipment architecture is converging around modular clamping platforms and closed-loop process control as alloy flexibility becomes the decisive procurement criterion for multi-material casting operations.
Electromagnetic dosing systems are migrating from laboratory validation to production floor deployment across European automotive programs. BMW and Mercedes-Benz powertrain divisions are piloting contact-free molten metal transfer to eliminate gooseneck erosion and extend shot chamber life. This technology is migrating from premium European installations to mid-tier Chinese system integrators as patent protections expire and component costs decline.
REACH substance restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent passivation and organic coating systems for zinc die cast hardware. The regulation is compressing finishing equipment upgrade cycles and disqualifying legacy plating line configurations from EU-bound component supply. Automotive fastener and lock manufacturers in Poland and Czechia are absorbing the steepest compliance costs as export dependency exceeds 70% of output.
Direct machine-to-factory integration contracts are displacing traditional distributor-mediated procurement in high-volume electronics manufacturing. Foxconn and Luxshare Precision are negotiating captive maintenance and shot monitoring service bundles that unbundle equipment margin from lifecycle revenue. This restructuring is most visible in Guangdong province where appliance OEM procurement teams are consolidating vendor lists from twelve to four approved system suppliers.
Hot Chamber Die Casting Machine Market Segmentation
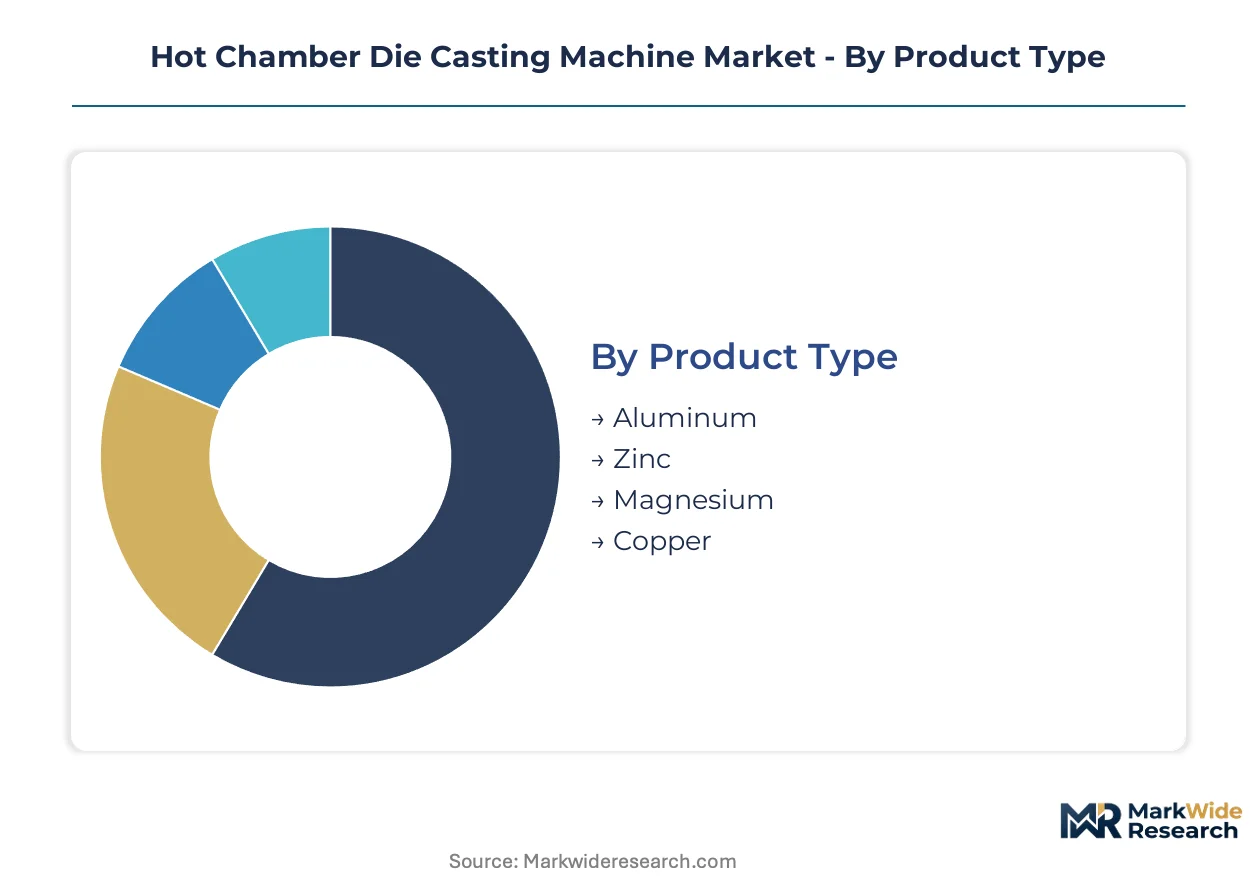
Hot chamber die casting machine procurement patterns diverge sharply by material chemistry, process technology, and end-use quality requirements. Equipment specifications, clamping force ranges, and control system architectures align to distinct segment demands rather than universal configurations.
Product Type:
Use-case spectrum spans high-volume automotive hardware through precision aerospace castings, with alloy selection dictating machine thermal management and shot chamber design.
- Zinc:Established automotive fastener and consumer electronics connector demand anchors the largest installed base. Guangdong appliance OEMs specify dedicated 200-400 ton configurations for precision housings with cycle times under ten seconds. Established volume favors zinc; emerging adoption favors magnesium.
- Magnesium:Molten metal handling and oxidation control requirements demand specialized shot chamber inerting systems. OEMs in Germany and Japan are qualifying structural automotive castings as mass reduction targets tighten under EPA emissions thresholds. Climbing the fastest among alloy-dedicated machine investments.
- Aluminum:Cold chamber architectures dominate automotive structural applications; hot chamber configurations remain niche for small precision components.
- Copper:Electrical contact and thermal management applications in power distribution equipment drive limited specialized demand.
Zinc maintains equipment refresh velocity; magnesium captures greenfield specification momentum.
Technology:
Process selection determines porosity control capability, cycle economics, and qualification pathways for safety-critical applications.
- Pressure Die Casting:Dominant revenue contribution across automotive and electronics manufacturing with clamping forces from 50 to 1,000 tons. Tier-one suppliers in Thailand and Vietnam specify 400-600 ton magnesium-capable configurations for passenger vehicle assembly expansion. Margin compression is accelerating as Chinese system integrators capture mid-tier accounts.
- Vacuum Die Casting:Aerospace-grade porosity specifications below 0.5% command 12-18% equipment price premiums for brake and steering component suppliers. BMW and Mercedes-Benz powertrain divisions are specifying vacuum-assisted configurations for structural safety-critical castings. Steepest expansion trajectory in automotive structural applications.
- Gravity Casting:Lower tooling complexity serves prototype and low-volume production requirements.
- Ingot Casting:Primary metal production and alloy feedstock preparation rather than net-shape component manufacturing.
Standard pressure equipment anchors volume throughput; vacuum configurations capture margin in safety-critical specifications.
End User:
Industry-specific quality certifications and lot traceability requirements segment machine procurement by compliance burden and service integration depth.
- Automotive Components:IATF 16949 accreditation mandates govern tier-one supplier qualification with 14-18 month system implementation timelines. Underhood powertrain hardware and structural castings drive specification of 400-800 ton configurations with real-time shot monitoring integration.
- Consumer Electronics:Foxconn and Luxshare Precision are negotiating captive maintenance and shot monitoring service bundles that unbundle equipment margin from lifecycle revenue. Connector and heat sink demand concentrates procurement consolidation in Guangdong province.
- Aerospace:Porosity and mechanical property specifications exceed automotive thresholds, limiting qualified machine suppliers.
- Marine Engineering:Corrosion resistance requirements in saltwater environments drive specialized surface treatment integration.
Electronics procurement is consolidating vendor lists; automotive qualification timelines are extending equipment replacement cycles.
Application:
Functional performance requirements determine alloy selection, wall thickness capability, and secondary machining integration.
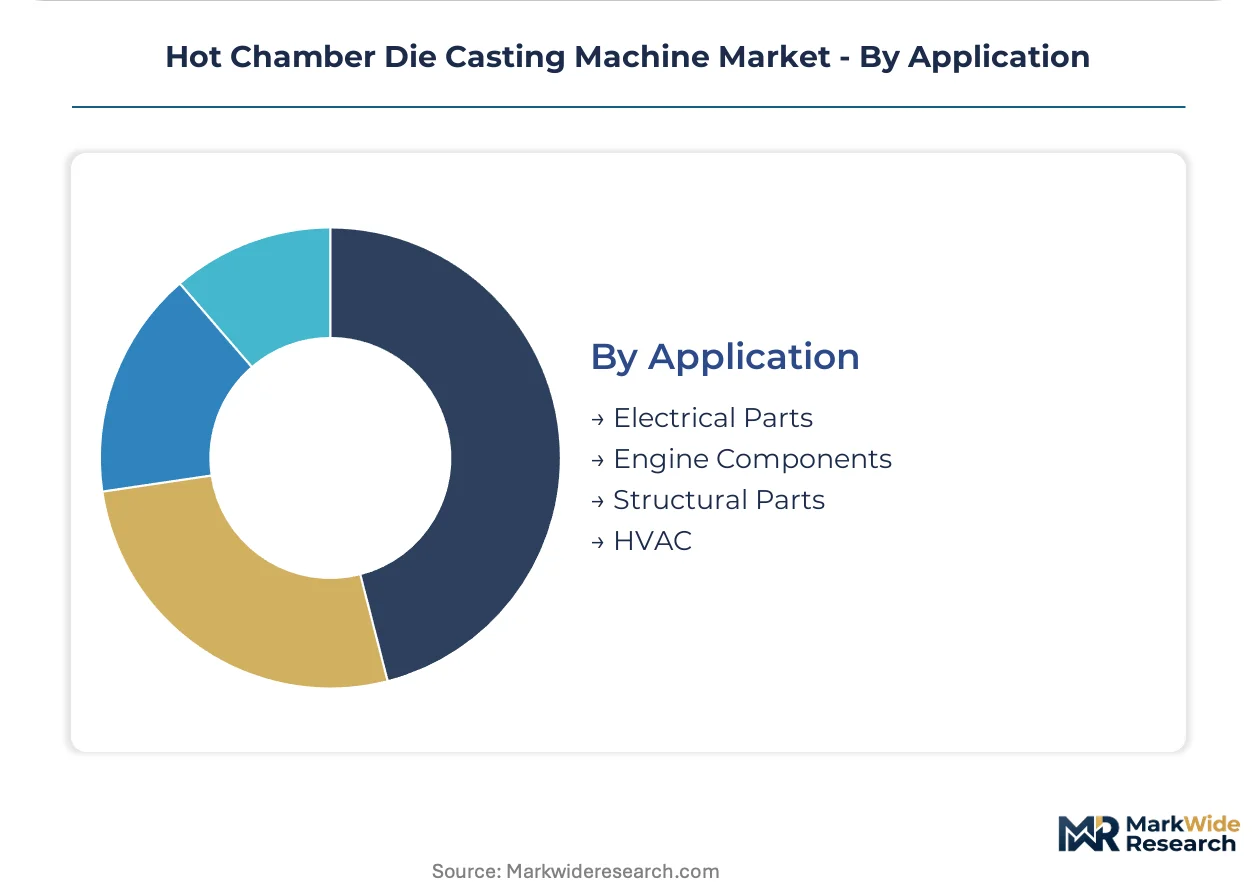
- Engine Components:Thermal cycling resistance and pressure containment specifications demand high-integrity zinc and magnesium castings for underhood hardware. EPA Corporate Average Fuel Economy standards are compressing equipment replacement cycles as 15-20% mass reduction targets reshape alloy specifications.
- Structural Parts:Crashworthiness and fatigue performance requirements are penetrating vacuum-assisted porosity control from aerospace into automotive safety-critical applications. REACH substance restrictions on hexavalent chromium surface treatments are forcing finishing equipment upgrade cycles for EU-bound component supply.
- Electrical Parts:Conductivity and EMI shielding specifications drive copper and zinc alloy selection for connector housings.
- HVAC:Thermal efficiency and corrosion resistance requirements in heat exchanger applications.
Powertrain hardware maintains replacement velocity; structural casting specifications are accelerating magnesium qualification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions thresholds in the United States are accelerating equipment replacement cycles as automotive OEMs pursue underhood mass reduction. Demand concentrates in manufacturing corridors where tier-one suppliers cluster near final assembly plants.
United States
NHTSA Corporate Average Fuel Economy standards are compressing zinc alloy specification timelines for powertrain hardware. EPA emissions rules drive 15-20% mass reduction targets in underhood components. Michigan and Ohio manufacturing corridors anchor die casting investment near Detroit and Cleveland automotive assembly clusters.
Germany
BMW and Mercedes-Benz powertrain divisions are specifying vacuum-assisted configurations for structural safety-critical castings. EU Green Deal carbon border adjustments incentivize in-house die casting investment to preserve OEM supply chain access. Bavaria and Baden-Württemberg host the densest concentration of magnesium qualification programs for automotive structural applications.
China
Guangdong province appliance OEMs are consolidating vendor lists from twelve to four approved system suppliers for connector and heat sink procurement. MIIT dual carbon goals constrain primary magnesium smelter output, feeding feedstock price volatility. Dongguan and Shenzhen electronics clusters pull dedicated 200-400 ton hot chamber installations for precision zinc housings.
Japan
METI industrial efficiency standards govern retrofit and replacement cycles across automotive supplier facilities. Qualified process engineers for molten metal handling remain concentrated in Japanese supplier ecosystems. Nagoya and Osaka manufacturing basins sustain magnesium metallurgy expertise for oxidation control systems.
Thailand
Passenger vehicle assembly expansion creates greenfield demand for 400-600 ton magnesium-capable machines without legacy zinc infrastructure constraints. Board of Investment incentives target automotive component localization for export-oriented assembly. Eastern Economic Corridor industrial zones attract die casting investment serving Japanese and European OEM supply chains.
Hot Chamber Die Casting Machine Market Competitive Environment
Swiss-German engineering specialists and Chinese volume manufacturers split the market into premium and scale tiers. Alpine-region clamping unit suppliers concentrate 16-24 week lead time exposure for large-tonnage configurations. Three archetypes dominate: heritage European precision engineering houses, Dongguan-based volume integrators, and Japanese technology licensors. Competitive moves center on electromagnetic dosing system patent expiration exploitation and captive maintenance service bundling.
Within the heritage engineering tier, Buhler AG exemplifies Swiss precision positioning sustained across European automotive programs. L.K. Technology Holdings Limited anchors the volume supply archetype through its Dongguan manufacturing complex presence. Idra S.r.l. occupies the large-tonnage specialization position for structural automotive casting configurations.
| Leading Market Players |
|---|
| Buhler AG |
| Oskar Frech GmbH |
| UBE Machinery Inc. |
| Toshiba Machine Co., Ltd. |
| Toyo Machinery & Metal Co., Ltd. |
| Shibaura Machine |
| L.K. Technology Holdings Limited |
| Idra S.r.l. |
| Suzhou Sanji Die-Casting Automation System Co. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Swiss-German clamping unit manufacturing is extending lead time premiums for large-tonnage configurations while compressing margin visibility for tier-one automotive suppliers. This utilization squeeze simultaneously empowers Alpine engineering specialists to sustain price premiums and forces Chinese system integrators to absorb cost compression through volume scale.
Pricing Analysis
Equipment price spreads between European heritage manufacturers and Dongguan-based volume suppliers now exceed three-to-one for comparable tonnage ratings. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in control system architecture and after-sales service bundling rather than clamping force alone. Pricing pressure stems from electromagnetic dosing patent expirations commoditizing once-proprietary shot chamber technologies. Electronics OEM procurement teams in Guangdong province demonstrate highest price sensitivity through captive maintenance negotiations, while German automotive powertrain divisions remain least sensitive given IATF 16949 certification barriers.
Supply Chain Analysis
Swiss and German dual-use technology controls restrict export of precision clamping unit servo systems to certain end-user certifications. Manufacturing concentration in Switzerland, Germany, and China feeds global supply, with Alpine specialists controlling premium hydraulic component architectures. Primary magnesium ingot, hardened steel die alloys, and high-purity zinc feedstock constitute critical input dependencies. Single-source vulnerability concentrates in electromagnetic dosing system controller supply. Distribution runs through tier-one supplier direct procurement in automotive and consolidated vendor lists in electronics manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated electronics OEM procurement teams in Guangdong, where vendor lists have compressed from twelve to four approved suppliers. This concentration enables captive maintenance bundling and unbundles equipment margin from lifecycle revenue capture.
For Market Incumbents: Build switching-cost moats through real-time shot monitoring integration and predictive quality assurance algorithms. Defend against Chinese system integrator encroachment by embedding machine learning process control that commands 12-18% price premiums. Anchor capacity in Thailand's Eastern Economic Corridor to serve Japanese and European OEM supply chains without legacy zinc infrastructure displacement costs.
For New Entrants and Emerging Players: Build out magnesium metallurgy service capabilities to address qualified process engineer scarcity constraining operational ramp rates. Target Thailand and Vietnam greenfield automotive assembly expansion where 400-600 ton magnesium-capable machine demand lacks incumbent zinc equipment refresh obligations. Penetrate through electromagnetic dosing system retrofit kits as patent protections expire and component costs decline.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European heritage manufacturers with captive maintenance and shot monitoring service bundles. Long-term viability across the analysis window favors acquisition targets with vacuum-assisted porosity control capabilities penetrating automotive structural applications. Monitor magnesium alloy qualification timeline acceleration at BMW and Mercedes-Benz powertrain divisions as inflection signal for greenfield equipment specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Dosing Patent Exploitation | Contact-free molten metal transfer eliminates gooseneck erosion and extends shot chamber life for BMW and Mercedes-Benz programs. |
| Captive Maintenance Service Bundling | Foxconn and Luxshare Precision negotiations unbundle equipment margin from lifecycle revenue in Guangdong electronics clusters. |
| Vacuum-Assisted Configuration Expansion | Aerospace-grade porosity specifications below 0.5% command equipment price premiums for brake and steering component suppliers. |
| Southeast Asian Greenfield Capacity | Thailand Board of Investment incentives target automotive component localization without legacy zinc infrastructure constraints. |
| Magnesium Metallurgy Talent Acquisition | Qualified process engineers for oxidation control remain concentrated in Japanese and German supplier ecosystems. |
Study Parameters
Cross-validation between primary interviews with die casting plant managers and secondary analysis of SEC filings and customs data anchors the qualitative findings. Stakeholder engagement spanned OEM procurement teams at tier-one automotive suppliers, maintenance directors at appliance manufacturing facilities, aftermarket service heads at Chinese system integrators, and technical R&D directors at electromagnetic dosing system developers. Secondary sources incorporated MIIT production statistics, EPA emissions compliance filings, EU Green Deal carbon border adjustment documentation, and IHS Markit vehicle production databases. Bottom-up equipment shipment analysis triangulated against top-down end-use demand modeling.
Calibration against historical replacement cycle patterns and alloy qualification timeline data informs the projection framework. Segmentation modeling spans alloy chemistry, process technology, clamping force tier, end-use industry, and regional regulatory cluster. CAGRs derive from equipment shipment trajectories weighted by average selling price evolution across configuration tiers. Forecast inputs incorporate magnesium feedstock price volatility indices and IATF 16949 certification pipeline visibility.
Sensitivities concentrate around magnesium smelter output curbs under Chinese dual carbon goals and REACH substance restriction enforcement timelines. Forecasts reflect documented assumptions regarding EPA emissions threshold stringency and EU carbon border adjustment implementation scope. Material shifts in magnesium alloy automotive qualification velocity or electromagnetic dosing patent litigation outcomes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market