
 Post Drivers Market | 2026-2036
Post Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
Post Drivers Market Insights
The capital-intensity divergence between players is bifurcating competitive posture across the Post Drivers landscape. Paladin Company leverages integrated manufacturing scale to sustain pricing power in hydraulic attachments for skid-steer and excavator mounts. Rabaud anchors its position through specialized vineyard and orchard post-driving systems that dominate European viticulture corridors. Gripple competes via gripple-wire tensioning accessories bundled with driver sales, creating installed-base lock-in across Australian and UK fencing markets.
Post drivers are mechanical or powered implements designed to drive fence posts, signposts, utility poles, or deck pilings into soil or substrate, typically rated by blow energy, stroke frequency, or compatible carrier weight class. Pneumatic and hydraulic variants deliver high-impact force for rocky or compacted ground conditions, while electric units serve noise-restricted urban landscaping and residential fencing sites. The 4-6 HP and 7-10 HP power rating bands capture the bulk of commercial rental fleet investment, as these brackets balance portability with sufficient impact energy for treated-wood and steel-post substrates across construction and agriculture verticals. Manual post drivers retain share in remote mining exploration and temporary fencing where fuel logistics outweigh labor cost concerns.
OSHA excavation and struck-by hazard standards shape operator-guard and dead-man switch requirements for US-sold equipment, while EU machinery directives enforce CE-marked noise and vibration exposure limits that elevate electric-platform R&D spending. EPA Tier 4 Final and EU Stage V particulate regulations constrain diesel-hydraulic model refresh cycles, channeling OEM engineering resources toward battery-electric architectures. Buyers and fleet managers must weigh total-cost-of-ownership trajectories against residual-value risk as regulatory compliance windows tighten and electrified alternatives expand their performance envelope into traditionally hydraulic-dominated ground conditions.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions standards are compressing diesel-hydraulic refresh cycles while channeling OEM engineering budgets toward battery-electric architectures. This regulatory compression is bifurcating fleet replacement patterns across rental yards and contractor operations.
Growth Catalysts
- Rural Broadband Deployment:USDA ReConnect program funding sustains above-average equipment replacement cycles among utility contractors driving fiber-optic infrastructure into underserved counties.
- CE Marking Noise Directives:EU machinery directives enforcing vibration exposure limits accelerate electric-platform R&D spending among manufacturers targeting European viticulture and landscaping verticals.
- Skid-Steer Attachment Standardization:Universal quick-attach interfaces expand addressable market for hydraulic post drivers across construction equipment rental fleets.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Battery pack cost volatility constrains electric unit pricing parity against established diesel-hydraulic alternatives.
- Steel Input Cost Fluctuation:Treated-post and steel-post substrate prices expose fencing contractors to margin compression during commodity spikes.
- Rocky Substrate Performance Gap:Battery-electric impact energy limitations exclude electrified units from compacted ground conditions where pneumatic systems retain dominance.
Strategic Opportunities
- Vineyard Electrification Mandates:French and Italian regional environmental incentives create pull for zero-emission post drivers in European wine-growing corridors.
- Telematics-Enabled Fleet Management:IoT hour-meter and geofencing integration allows rental yards to monetize usage-based pricing models.
- Utility Hardening Programs:Grid resilience investments across storm-prone US states sustain demand for high-capacity pole-driving equipment.
Industry Challenges
- EPA Certification Timeline Compression:Tier 4 Final compliance windows strain engineering bandwidth at mid-cap OEMs with limited regulatory affairs staffing.
- Legacy Hydraulic Fleet Stranding Risk:Residual value uncertainty complicates total-cost-of-ownership calculations for buyers evaluating electrified alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post Drivers Market |
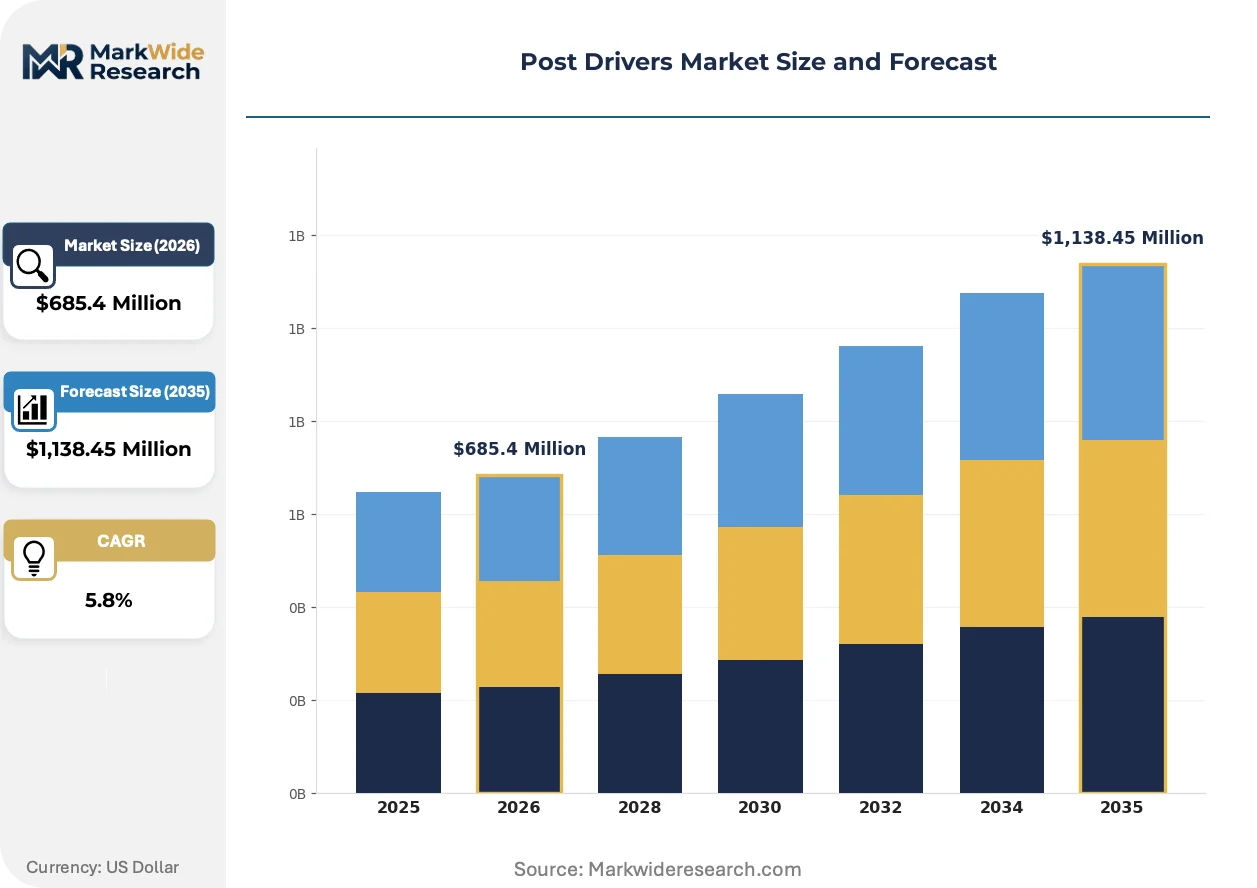
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Pneumatic, Hydraulic, Electric, Manual Industry Vertical: Construction, Agriculture, Landscaping, Mining Application: Fencing, Sign Installation, Utility Poles, Deck Foundations Power Rating: 0-3 HP, 4-6 HP, 7-10 HP, Above 10 HP |
| Companies Covered | Paladin Company, Binger Seilzug GmbH & Co. KG, Rabaud, Clavaestacas, The ERO Group, Gripple, Carmo, Spezia Company, Eterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post Drivers Market Trends and Innovations
Battery-electric drivetrains are penetrating ground conditions previously reserved for pneumatic systems. Telematics integration and operator-assist automation are redefining fleet management economics.
Brushless DC motor systems paired with high-density lithium-polymer packs are supplanting small-displacement gasoline engines in sub-10 HP equipment classes. Landscaping contractors in noise-restricted municipalities adopt these configurations for residential fencing contracts. The shift compresses maintenance intervals and eliminates fuel logistics for urban job sites.
EU Stage V particulate regulations now enforce real-driving emission monitoring for diesel-powered construction equipment. OEMs face accelerated engineering spend to maintain compliance across hydraulic attachment lines. German and French rental fleets respond by front-loading electric unit procurement to hedge residual value risk.
Usage-based rental contracts displace flat-rate daily pricing in North American equipment yards. Telemetry integration enables precise hour-meter billing and remote diagnostics. Fencing contractors in Texas and Florida operationalize this shift through seasonal demand spikes tied to agricultural fencing cycles.
Post Drivers Market Segmentation
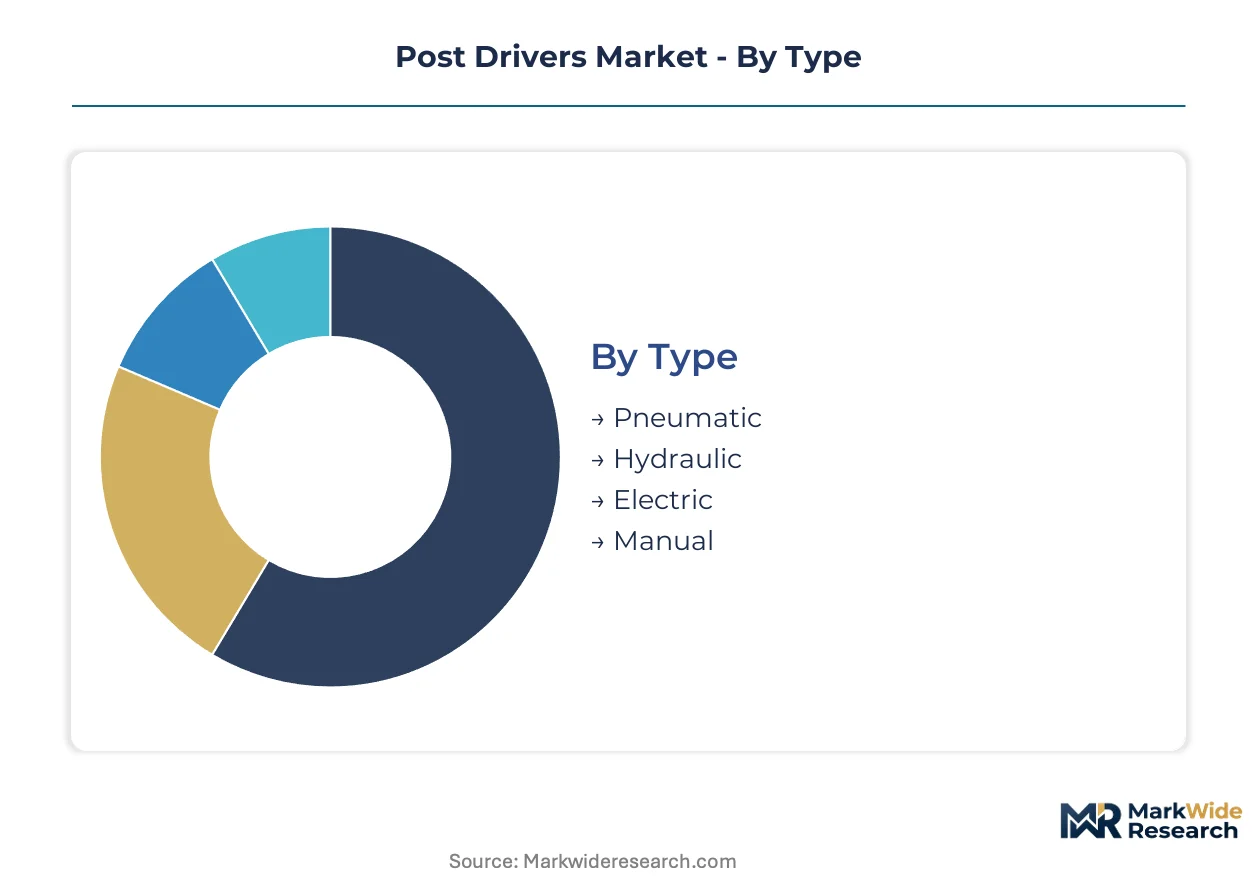
Post driver segmentation reveals divergent margin pools across power technologies and end-use applications. Equipment rental yards and fencing contractors prioritize different performance attributes, creating tiered pricing structures that OEMs exploit through targeted platform development.
Type:
Hydraulic and pneumatic variants command the highest attachment premiums in commercial fleet procurement, while electric units capture emerging margin pools in noise-regulated municipalities.
- Hydraulic:These units deliver blow energy exceeding 1,000 ft-lbs through skid-steer and excavator carrier interfaces. Demand concentrates among utility contractors in Texas and Florida executing grid hardening programs, where carrier compatibility and impact force justify premium rental rates.
- Pneumatic:Compressed-air systems achieve penetration rates in rocky substrates that battery-electric platforms cannot yet match. Mining exploration camps in remote Canadian territories specify pneumatic drivers where fuel logistics for compressors still outperform manual labor economics.
- Electric:Brushless DC motor architectures eliminate exhaust emissions for urban landscaping contracts in California municipalities with air quality mandates. Battery pack energy density constraints limit deployment to treated-wood posts in uncompacted soils.
- Manual:Simple drop-weight mechanisms serve temporary fencing at remote construction sites where power source logistics prove prohibitive. Australian cattle stations deploy manual units for seasonal boundary repairs on low-density grazing leases.
Hydraulic holds installed capacity. Electric is rotating up the share rankings.
Industry Vertical:
Construction and agriculture absorb the majority of unit shipments, though mining applications sustain above-average equipment utilization rates through harsh operating conditions.
- Construction:Fencing contractors drive treated-wood and steel posts for residential subdivisions and commercial perimeter security. OSHA struck-by hazard standards mandate dead-man switches and operator guards on US-sold equipment, elevating compliance costs for rental fleet operators.
- Agriculture:Pasture fencing and livestock containment systems require high-duty-cycle performance across variable soil conditions. USDA ReConnect program funding for rural broadband infrastructure sustains replacement demand among utility contractors serving agricultural counties.
- Landscaping:Noise-restricted urban municipalities in Germany and France specify electric units for residential fencing contracts. CE marking noise directives enforce vibration exposure limits that compress diesel-hydraulic refresh cycles.
- Mining:Exploration camps and temporary site perimeter fencing prioritize portability over impact energy. Manual and pneumatic configurations dominate where grid power remains unavailable and fuel logistics strain supply chains.
Construction anchors volume throughput. Landscaping is expanding most quickly.
Application:
Fencing applications generate recurring rental demand through seasonal agricultural cycles, while utility pole installation commands specialized high-capacity equipment with extended depreciation schedules.
- Fencing:Agricultural boundary maintenance and residential perimeter construction drive the majority of commercial rental transactions. Telematics-enabled hour-meter billing allows Texas and Florida equipment yards to monetize seasonal demand spikes.
- Sign Installation:Highway and roadway signage requires precise vertical alignment capabilities. State transportation departments in storm-prone US regions specify rapid-deployment units for emergency signage replacement.
- Utility Poles:Fiber-optic and electrical distribution infrastructure demands high-torque driving force for treated-wood and composite poles. Grid resilience investments sustain demand for above-10 HP equipment classes.
- Deck Foundations:Residential and marine construction applications favor compact electric units for pier and boardwalk pilings. Coastal municipalities with environmental protection mandates accelerate zero-emission procurement.
Fencing holds installed capacity. Utility poles is climbing the fastest.
Power Rating:
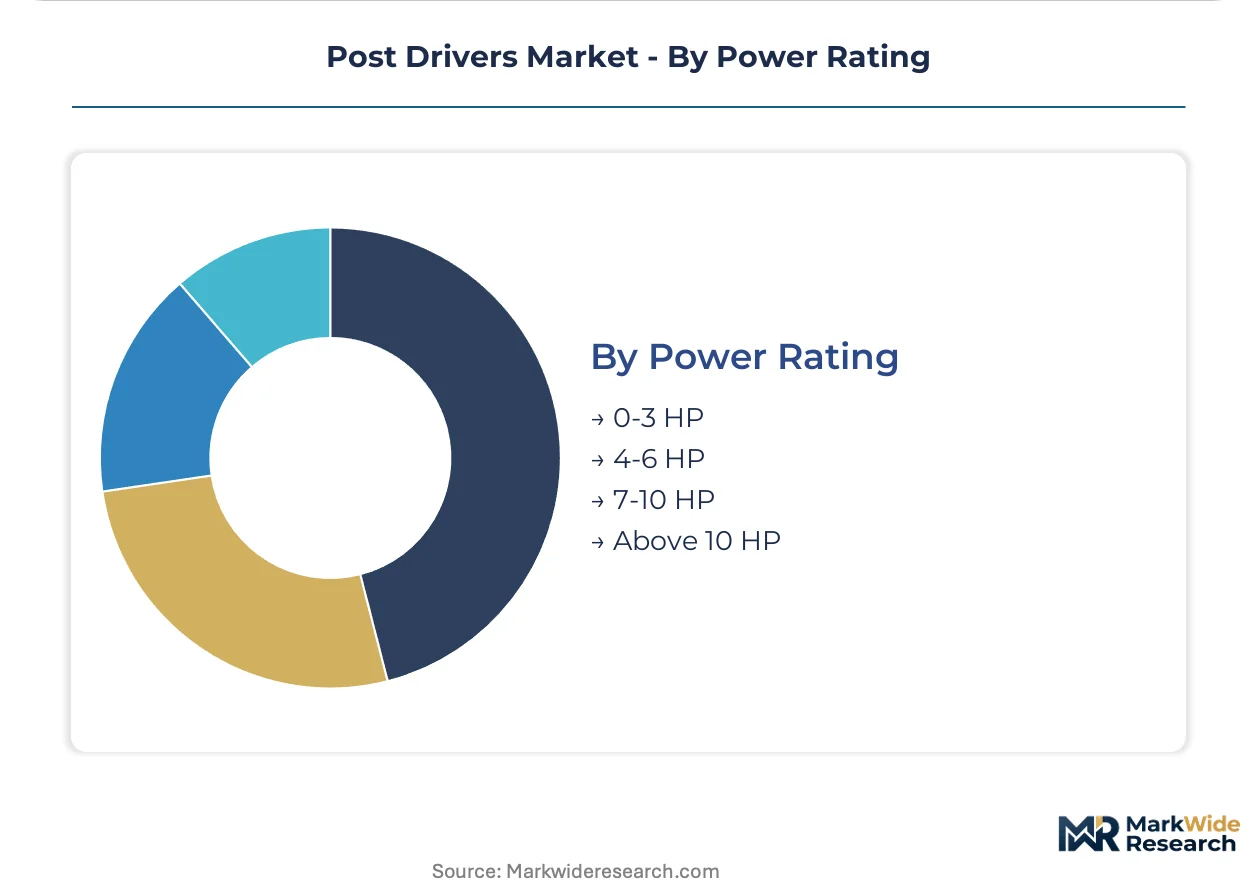
The 4-6 HP and 7-10 HP brackets balance portability with sufficient impact energy, capturing the bulk of rental fleet investment and OEM engineering focus.
- 4-6 HP:This bracket serves commercial fencing contractors with sufficient blow energy for treated-wood posts in moderate soil conditions. Universal quick-attach interfaces expand addressable market across construction equipment rental fleets.
- 7-10 HP:Higher displacement hydraulic systems penetrate compacted soils and rocky substrates for utility pole installation. EPA Tier 4 Final compliance costs compress margin structures for diesel-hydraulic platforms in this range.
- 0-3 HP:Compact electric and gasoline units target residential DIY and light landscaping applications. Brushless DC motor systems paired with lithium-polymer packs supplant small-displacement engines in noise-restricted municipalities.
- Above 10 HP:Specialized carrier-mounted systems execute high-capacity pole driving for electrical transmission and telecommunications infrastructure. Grid hardening programs across storm-prone US states sustain demand despite elevated capital requirements.
4-6 HP holds installed capacity. Above 10 HP is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany, where utility hardening programs and vineyard electrification mandates sustain equipment replacement premiums that undercut rental rates in peripheral markets.
United States
USDA ReConnect rural broadband funding drives fiber-optic pole installation across agricultural counties, while OSHA struck-by hazard standards mandate dead-man switches on commercial fleet equipment. Texas and Florida equipment rental yards monetize seasonal demand spikes through telematics-enabled hour-meter billing.
Germany
EU Stage V particulate regulations compress diesel-hydraulic refresh cycles among construction equipment lessors, accelerating electric unit procurement. Bavarian and Baden-Württemberg rental fleets front-load battery-electric post drivers to hedge residual value risk ahead of compliance deadlines.
France
Regional environmental incentives in Champagne and Bordeaux wine-growing corridors create pull for zero-emission vineyard post drivers. ANSM noise enforcement in urban landscaping contracts elevates electric-platform specifications above hydraulic alternatives in Île-de-France municipalities.
Australia
Cattle stations in Queensland and New South Wales deploy manual post drivers for seasonal boundary repairs on low-density grazing leases. TGA-equivalent state-level machinery safety standards govern commercial fencing contractor equipment specifications across the Murray-Darling basin.
Canada
Mining exploration camps in remote Yukon and Northwest Territories territories specify pneumatic drivers where fuel logistics for compressors outperform manual labor economics. Health Canada particulate exposure guidelines shape equipment selection for temporary perimeter fencing at extraction sites.
Post Drivers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Post Drivers landscape. Integrated manufacturing specialists command attachment premiums through carrier compatibility standardization, while regional fabricators compete on fleet replacement timing and maintenance bundling. The vendor base separates into three strategic archetypes: hydraulic attachment integrators, vineyard specialization houses, and wire-tensioning system bundlers. Dominant competitive moves include telematics integration partnerships and battery-electric platform licensing agreements that accelerate compliance-driven fleet turnover.
Among European vineyard specialization houses, Rabaud occupies a position exemplifying the viticulture-corridor focus, while Gripple anchors the wire-tensioning bundling archetype across Australian and UK fencing markets. Paladin Company represents the integrated manufacturing scale vector that sustains pricing power in hydraulic attachments for skid-steer and excavator mounts.
| Leading Market Players |
|---|
| Paladin Company |
| Binger Seilzug GmbH & Co. KG |
| Rabaud |
| Clavaestacas |
| The ERO Group |
| Gripple |
| Carmo |
| Spezia Company |
| Eterra |
| Others |
Pricing and Supply Chain Analysis
Long-term equipment lease contracts with embedded maintenance provisions lock in supply access for North American rental yards while stabilizing price visibility against lithium-ion cell cost volatility. These arrangements tether fleet procurement decisions to battery pack pricing trajectories and EPA Tier 4 Final compliance timelines.
Pricing Analysis
The customization-premium spread separates skid-steer-compatible hydraulic units from standard manual configurations by a factor reflecting carrier interface engineering and blow energy ratings. Pricing stratifies across premium, standard, and economy tiers driven by certification level (OSHA-compliant guarding vs. unguarded manual units) and geographic delivery cost to remote mining camps. Cost compression in electric platforms is intensifying because lithium-polymer pack economies remain immature against diesel-hydraulic alternatives. Agricultural fencing contractors exhibit highest price sensitivity, while utility pole installation contractors absorb premium pricing for above-10 HP equipment classes.
Supply Chain Analysis
Just-in-time assembly preferences dominate hydraulic attachment manufacturing, though strategic stockpiling of lithium-ion cells is emerging among electric-platform OEMs hedging supply concentration risk. Component sourcing draws from China for battery packs, Germany for precision hydraulic valves, and the United States for treated-post substrate compatibility testing. Single-source vulnerability concentrates in rare-earth magnet supply for brushless DC motors. Distribution runs through construction equipment rental yards and agricultural implement dealers serving fencing contractors across Texas, Florida, and the Murray-Darling basin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated equipment rental chains capable of standardizing fleet procurement across multi-state operations, fragmenting pricing leverage previously held by regional fencing contractors.
For Market Incumbents: Secure carrier compatibility certification across major skid-steer OEM platforms to defend attachment premium positioning against emerging electric-platform specialists. Deepen backward integration into lithium-ion pack assembly to capture margin compression from cell cost volatility. Prioritize telematics integration partnerships that enable usage-based billing models for rental yard customers. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission creates regulatory beachhead for vineyard electrification mandates in French and Italian wine-growing corridors. Target Australian cattle station manual unit replacement cycles with pneumatic-electric hybrid configurations. Deploy direct-to-fleet sales channels bypassing traditional agricultural implement dealer networks. For Investors and Strategic Acquirers: Regional fabricators with captive vineyard specialization capabilities represent acquisition targets positioned for EU Stage V compliance-driven fleet turnover. Long-term viability hinges on electric-platform R&D spend ratios exceeding diesel-hydraulic refresh cycle investments. Monitor lithium-ion cell supply contract renegotiation frequency as inflection indicator for electric unit pricing parity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Licensing | Accelerates EU Stage V compliance for mid-cap OEMs lacking in-house electrification engineering. |
| Telematics Integration Partnership | Enables Texas and Florida rental yards to monetize hour-meter billing for seasonal agricultural demand spikes. |
| Carrier Compatibility Expansion | Universal quick-attach interfaces broaden addressable market across construction equipment rental fleets. |
| Vineyard Specialization Acquisition | Captures French and Italian regional environmental incentive flows for zero-emission post driver procurement. |
| Backward Integration into Battery Assembly | Reduces exposure to lithium-ion cell supply concentration and pack cost volatility. |
Research Methodology
Desk research of customs trade databases, equipment registration filings, and EPA certification records preceded structured interviews with fencing contractor operations managers, construction equipment rental fleet directors, OEM product development engineers, and agricultural extension service equipment specialists. Primary fieldwork across Texas, Florida, Germany, and Australia validated secondary indicators of fleet replacement timing and electrification adoption rates. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions derived from rental rate benchmarks and equipment depreciation schedules.
Variance decomposition across power technology segments, industry verticals, and regional regulatory clusters anchored the analytical framework throughout the projection horizon. Modeled dimensions spanned hydraulic-pneumatic-electric-manual typology, construction-agriculture-landscaping-mining end-use classification, and 4-6 HP versus 7-10 HP versus above-10 HP power rating tiers. CAGRs were synthesized from replacement cycle analysis, broadband infrastructure deployment trajectories, and vineyard electrification mandate compliance timelines. USDA ReConnect funding disbursement patterns and EU Stage V enforcement phase-in schedules served as industry-specific forecast inputs.
Underlying assumptions cover lithium-ion cost decline trajectories, EPA Tier 4 Final enforcement continuity, and rural broadband deployment sustaining utility pole installation demand, with deviation risk concentrated in battery chemistry substitution breakthroughs and trade policy disruptions affecting hydraulic component sourcing. Revision becomes warranted when electric platform blow energy performance crosses thresholds competitive with pneumatic systems in rocky substrate conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Reamer Market
Tools
Digital Levels Market
Tools
Adoption of Benelux Power Tools Market
Tools
End Mill Holder Market
Tools
Global Vertical Grinding Machine Market
Tools
Digital Cutting Machine Market
Tools
Global Diamond Tools Market
Tools
Construction Anchors Market
Tools
Hand Tools Market
Tools
Bandsaw Market
Tools
3D Milling Machines Market
Tools
Woodcarving Tool Market
Tools
Total Station Market
Tools
Global Cordless Power Tools Market
Tools
Woodworking Tools Market
Tools
Tool Pliers Market