
 Pruning Saw Market | 2026-2036
Pruning Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Pruning Saw Market Analytics
Carbon fiber-reinforced nylon is decoupling pruning saw handles from traditional aluminum die-cast economics, trimming unit weight by nearly half without sacrificing torque tolerance. Husqvarna AB leverages captive composite molding to protect margin pools in its professional pole saw line. STIHL Incorporated anchors its North American position through dense dealer-service networks that competitors cannot replicate at equivalent coverage. Felco SA specializes in Swiss-precision blade hardening, commanding premium positioning among arborists who prioritize edge retention over initial cost.
A pruning saw is a handheld cutting tool with a tapered, toothed blade designed for live-wood severance in arboriculture and horticulture, typically operating at pull-stroke cutting angles between 12 and 18 degrees to minimize bark tearing and promote rapid cambium healing. Its primary commercial purpose spans canopy maintenance, fruit-wood renewal, and structural pruning across vineyards, municipal tree inventories, and managed forest understories. Manual saws retain dominant volume in developing markets where capital constraints and intermittent use patterns suppress powered-tool penetration. Electric saws, spanning corded and battery platforms, represent the fastest-expanding segment as lithium-ion energy density improvements extend runtime beyond single-shift thresholds for professional crews.
The US EPA and California Air Resources Board enforce escalating emission thresholds on gasoline-powered outdoor equipment, compressing two-stroke engine viability and redirecting manufacturer R&D toward battery-electric architectures. The EU F-Gas Regulation and Machinery Directive (2006/42/EC) impose parallel conformity burdens on products sold across European member states, raising compliance costs for non-integrated importers. Stakeholders must monitor battery-platform interoperability standards and regional subsidy trajectories to avoid stranded inventory as electrification mandates tighten across jurisdictions.
Market Dynamics
Battery-electric motor platforms are compressing two-stroke engine viability across professional arboriculture, as lithium-ion energy density improvements extend runtime beyond single-shift thresholds and California Air Resources Board emission thresholds tighten compliance windows.
Growth Catalysts
- Urban tree-canopy mandates:Municipalities across the United States Pacific Coast corridor are expanding managed tree inventories, forcing landscape contractors to expand tool inventories for compliance-driven maintenance cycles.
- F-Gas Regulation pressure:The European Union's escalating conformity burdens on gasoline-powered outdoor equipment redirect manufacturer R&D toward battery-electric architectures for products sold across member states.
- Wildfire-fuel-reduction programs:Vineyard replanting and fuel-load management in California overlap with seasonal demand spikes, concentrating procurement timelines for professional-grade cutting tools.
Market Restraints
- Lithium-ion cell cost volatility:Raw material concentration in Asian processing facilities creates input price instability for battery pack assembly, compressing margin pools for mid-tier manufacturers.
- Dealer-service network density:Sparse authorized service coverage in rural agricultural zones limits powered-tool penetration where intermittent use patterns already suppress capital expenditure.
- Two-stroke engine phase-out friction:The EPA and California Air Resources Board emission thresholds strand existing inventory and force premature fleet turnover for contractors with recent gasoline equipment investments.
Strategic Opportunities
- Carbon fiber-reinforced nylon adoption:Composite handle materials decouple pruning saw economics from aluminum die-cast supply chains, enabling weight reduction without torque tolerance sacrifice.
- Interoperability standard emergence:Battery-platform standardization across outdoor power equipment categories creates cross-brand ecosystem plays for professional crews seeking fleet simplification.
- Developing market manual-tool persistence:Capital constraints and intermittent use patterns in emerging agricultural economies sustain demand for premium manual saw configurations where powered alternatives face adoption barriers.
Industry Challenges
- Arborist certification alignment:Professional crews must reconcile tool specifications with ANSI Z133 safety standards and municipal procurement requirements, extending sales cycles for non-certified configurations.
- Blade hardening process IP fragmentation:Proprietary Swiss-precision and Japanese metallurgy techniques create licensing complexity for manufacturers seeking premium positioning without captive heat-treatment facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pruning Saw Market |
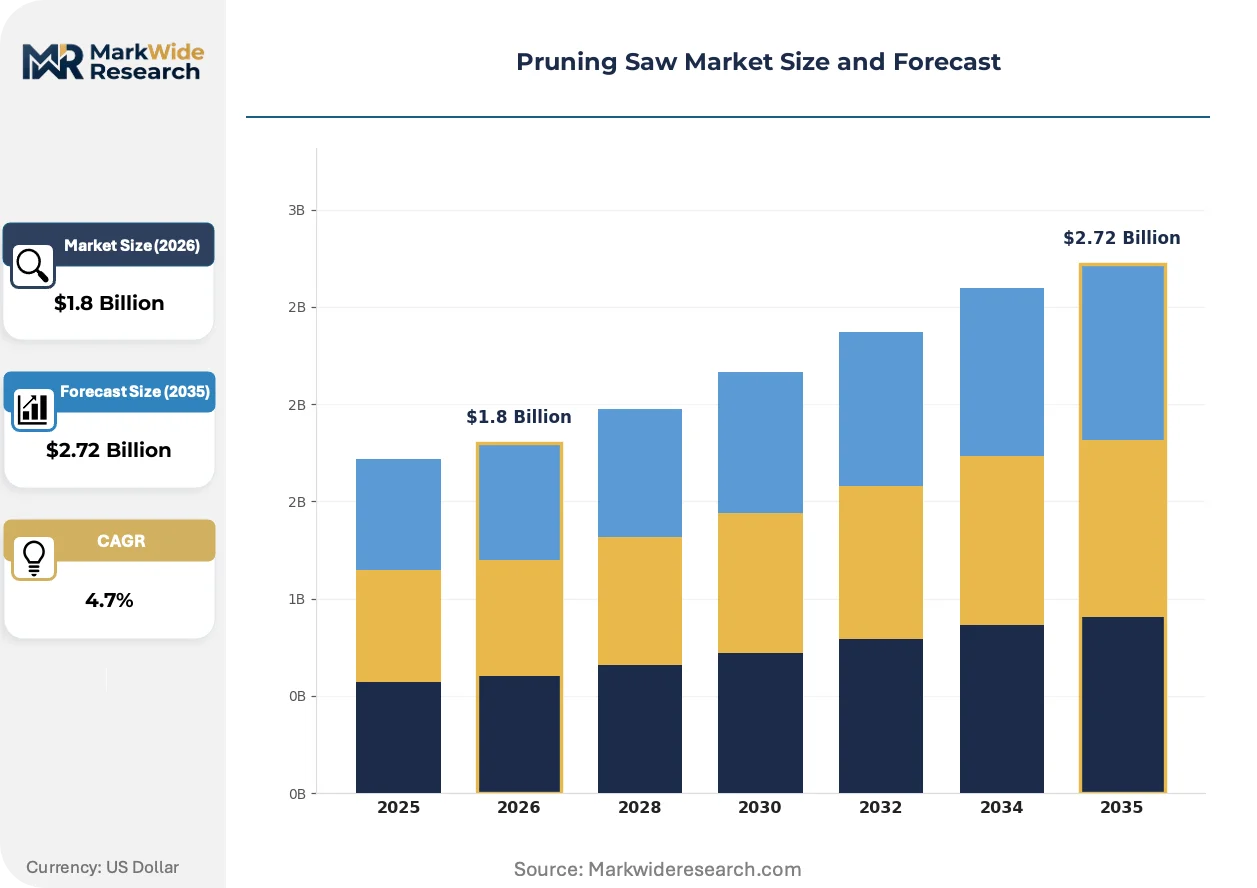
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Saws, Electric Saws, Gas-powered Saws, Pole Saws Application: Residential Gardening, Commercial Landscaping, Orchard Management, Forestry End User: Homeowners, Professional Gardeners, Landscape Contractors, Arborists Material: Steel, Aluminum, Carbon Fiber, Plastic |
| Companies Covered | Husqvarna AB, STIHL Incorporated, Fiskars Group, Stanley Black & Decker, Felco SA, Bahco, Corona Tools, CRAFTSMAN, ARS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pruning Saw Market Evolving Landscape
Electrification architectures and material science advances are compressing traditional equipment lifecycles while regulatory emission thresholds accelerate platform turnover across professional segments.
Brushless DC motor integration with lithium-ion power electronics is unifying battery management and cutting performance optimization in a single control module. Professional arboriculture crews in California and Oregon are adopting these unified platforms at replacement-cycle velocity. The technology is unifying what were previously separate gasoline engine and manual saw procurement decisions into single-vendor battery ecosystem commitments.
The EU F-Gas Regulation and Machinery Directive impose parallel conformity burdens on outdoor power equipment sold across European member states. Manufacturers must now certify battery-electric platforms for electromagnetic compatibility and machinery safety simultaneously, raising fixed compliance costs. Professional pole saw and chainsaw categories face the steepest certification timeline compression as member states accelerate phase-out schedules.
Landscape contractors are consolidating vendor relationships around full-fleet battery interoperability rather than single-tool procurement. Dense dealer-service networks in the United States Midwest and Northeast are capturing this consolidation by bundling maintenance contracts with initial equipment sales. California municipal procurement offices now specify cross-compatible battery platforms in RFP language, forcing non-compliant bidders from contention.
Pruning Saw Market Segmentation
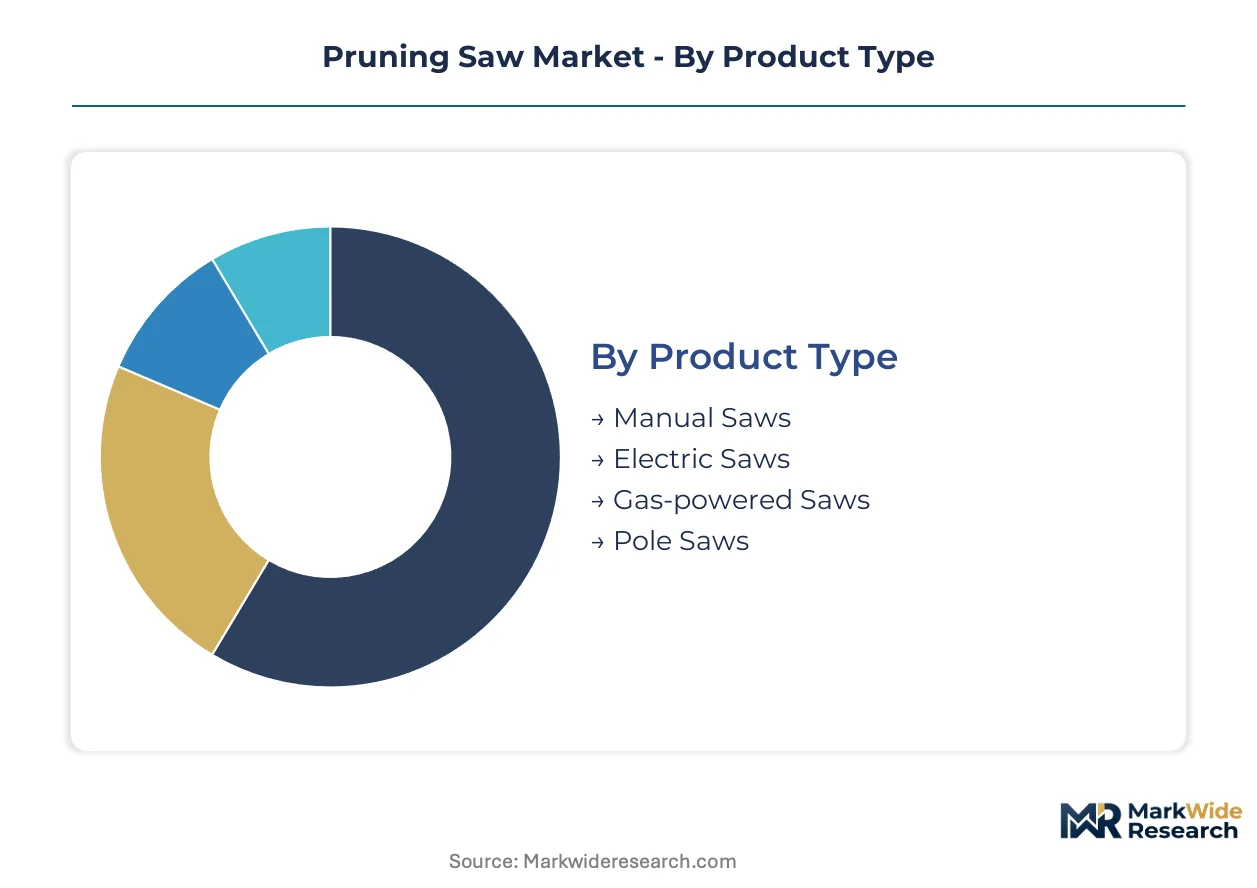
Pruning saw procurement patterns diverge sharply across user sophistication levels and duty-cycle intensity. Segment boundaries increasingly blur as battery platforms unify professional and prosumer tool categories under single-vendor ecosystems.
Product Type:
Supply concentration in battery-cell manufacturing tilts competitive advantage toward integrated electric-platform producers.
- Manual Saws:Precision-hardened steel blades with impulse-toothing patterns dominate arborist preference for fine canopy work. Demand clusters in developing markets where capital constraints and intermittent use patterns suppress powered-tool penetration.
- Electric Saws:Brushless DC motor integration with lithium-ion power electronics unifies battery management and cutting optimization. California municipal procurement offices now specify cross-compatible battery platforms in RFP language.
- Gas-powered Saws:Two-stroke engine architectures face EPA and CARB emission threshold compression. Existing fleet turnover accelerates as compliance windows narrow for professional crews.
- Pole Saws:Carbon fiber-reinforced nylon handles decouple unit economics from aluminum die-cast supply chains. Telescoping configurations command premium positioning in vineyard replanting corridors.
Today's leader: Manual Saws. Tomorrow's challenger: Electric Saws.
Application:
Cost tier stratification separates specification-grade procurement from consumer-grade purchasing cycles.
- Residential Gardening:Intermittent duty cycles favor lightweight manual configurations or entry battery platforms. Big-box retail distribution dominates with seasonal promotional calendars.
- Commercial Landscaping:Fleet standardization around interoperability standards reduces total cost of ownership. Dense dealer-service networks in the US Midwest capture maintenance contract bundling.
- Orchard Management:Precision cutting angles between 12 and 18 degrees minimize bark tearing in fruit-wood renewal. Vineyard replanting on the US Pacific Coast concentrates seasonal demand spikes.
- Forestry:Wildfire-fuel-reduction programs overlap with municipal tree-canopy mandates. Professional-grade specifications align with ANSI Z133 safety standards.
Commercial Landscaping anchors current revenue pools. Orchard Management climbs the fastest as vineyard replanting accelerates.
End User:
Customer type fragmentation forces parallel channel strategies with incompatible margin structures.
- Homeowners:Price-sensitive purchasing favors retail-branded manual saws or entry electric platforms. Online direct-to-consumer channels erode traditional hardware store foot traffic.
- Professional Gardeners:Tool durability specifications prioritize edge retention over initial cost. Swiss-precision blade hardening commands loyalty among repeat purchasers.
- Landscape Contractors:Fleet procurement consolidates around full-battery interoperability rather than single-tool decisions. Dense authorized service coverage limits rural agricultural zone penetration.
- Arborists:ANSI Z133 certification requirements extend sales cycles for non-compliant configurations. Municipal procurement specifications increasingly mandate certified tool configurations.
Landscape Contractors drive volume concentration. Arborists define premium specification trajectories.
Material:
Maturity gradients separate legacy metallurgy from advanced composite adoption curves.
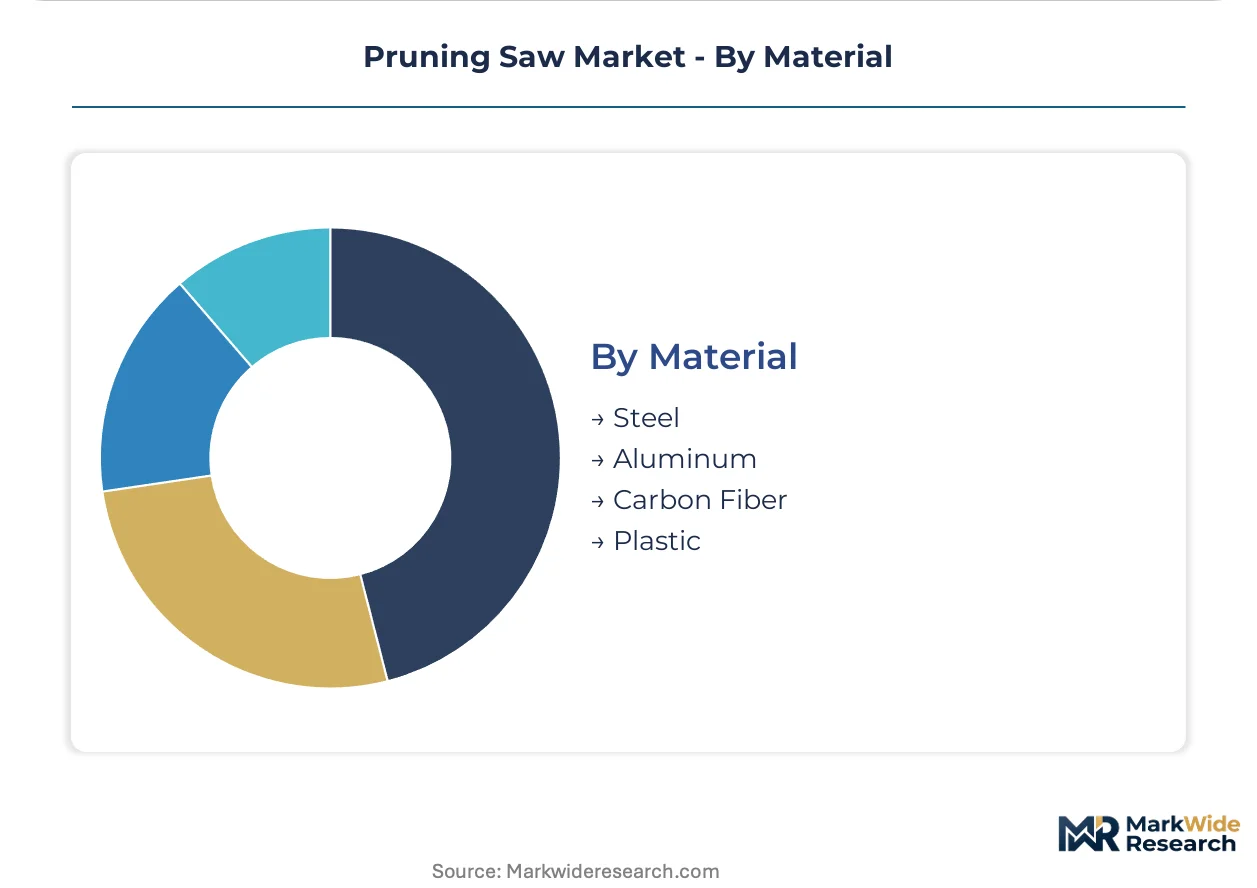
- Steel:Impulse-hardened tooth configurations remain standard for professional blade architectures. Japanese and Swiss proprietary heat-treatment techniques create licensing complexity for non-integrated manufacturers.
- Aluminum:Die-cast handle economics face margin compression from raw material volatility. Mid-tier manufacturers struggle to defend position against composite substitution.
- Carbon Fiber:Reinforced nylon composites trim unit weight by nearly half without torque tolerance sacrifice. Husqvarna's captive composite molding protects margin pools in professional pole saw lines.
- Plastic:Glass-filled polymer handles serve consumer-grade price points with limited durability expectations. Injection molding scale economies favor high-volume producers.
Steel retains specification authority. Carbon Fiber gains share fastest as professional weight-reduction priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Pacific Coast corridor concentrates pruning saw procurement as vineyard replanting and wildfire-fuel-reduction programs overlap. Municipal tree-canopy mandates across California, Oregon, and Washington force landscape contractors into compliance-driven maintenance cycles. Dense dealer-service networks in the Midwest and Northeast capture fleet standardization opportunities.
United States
California's vineyard replanting corridors and municipal fuel-load management programs generate concentrated seasonal demand spikes. The California Air Resources Board enforces escalating emission thresholds that compress two-stroke engine viability and redirect manufacturer R&D toward battery-electric architectures. The Pacific Northwest cluster spanning Oregon and Washington sees professional arborist crews adopting brushless DC motor platforms at replacement-cycle velocity.
Germany
Precision horticulture operations along the Rhine corridor sustain specification-grade manual saw demand for fine canopy work. The EU F-Gas Regulation and Machinery Directive impose parallel conformity burdens that raise fixed compliance costs for battery-electric platform certification. The Baden-Württemberg industrial cluster hosts dense dealer-service networks bundling maintenance contracts with equipment sales.
China
Rapid urban greening initiatives in the Yangtze River Delta and Pearl River Delta expand managed tree inventories requiring professional maintenance tools. The national dual carbon goals accelerate phase-out schedules for gasoline-powered outdoor equipment across municipal procurement. Zhejiang and Jiangsu provinces concentrate carbon fiber-reinforced nylon handle manufacturing for export-oriented producers.
Australia
Wildfire-fuel-reduction programs in New South Wales and Victoria overlap with commercial landscaping expansion in metropolitan Sydney and Melbourne. State-level environmental regulations tighten emission standards for powered outdoor equipment in professional applications. The Queensland agricultural belt sustains manual saw demand where capital constraints and intermittent use patterns suppress battery-platform penetration.
Japan
Precision orchard management in the Chubu and Tohoku regions prioritizes blade hardening specifications that minimize bark tearing in fruit-wood renewal. METI efficiency standards and JIS certification requirements extend sales cycles for non-compliant tool configurations. The Kanto industrial corridor around Tokyo concentrates high-end manual saw distribution through specialized horticultural supply channels.
Pruning Saw Market Competitive Landscape
Global majors compete with regional champions across battery-platform ecosystems and dealer-service network density. The vendor base stratifies into three tiers: integrated electric-platform producers with captive composite molding, precision metallurgy specialists commanding premium positioning, and scale-driven manufacturers serving retail-branded distribution. Consolidation pressures intensify as interoperability standards force ecosystem commitments rather than single-tool procurement. Dominant competitive moves include backward integration into lithium-ion pack assembly and geographic expansion through authorized service network franchising.
Within the integrated electric-platform tier, Husqvarna AB and STIHL Incorporated occupy positions defined by captive supply chain control and dense dealer coverage. Felco SA exemplifies the precision-metallurgy specialist archetype, anchoring premium-tier positioning through Swiss-origin blade hardening expertise. Fiskars Group sits within the diversified tool conglomerate category, leveraging portfolio breadth across consumer and professional horticultural segments.
| Leading Market Players |
|---|
| Husqvarna AB |
| STIHL Incorporated |
| Fiskars Group |
| Stanley Black & Decker |
| Felco SA |
| Bahco |
| Corona Tools |
| CRAFTSMAN |
| ARS Corporation |
| Others |
Value Network & Pricing Analysis
Landscape contractors consolidating around full-fleet battery interoperability exercise concentrated procurement leverage, compressing margin pools for mid-tier manufacturers while rewarding integrated electric-platform producers with captive lithium-ion pack assembly.
Pricing Analysis
Lithium-ion cell cost volatility feeds directly into battery pack assembly economics, forcing manufacturers to absorb margin compression or pass through to professional crews. Three-tier pricing structure across premium, standard, and economy levels separates ANSI Z133-certified professional configurations from municipal procurement grade and retail consumer offerings. Price differentiation centers on blade hardening certification and dealer-service bundling density. Cost compression in the mid-tier is intensifying because raw material concentration in Asian processing facilities creates input price instability.
Supply Chain Analysis
California Air Resources Board domestic-content preferences for municipal procurement are reshaping sourcing patterns toward North American battery pack assembly. Lithium-ion cell manufacturing concentrates in China, South Korea, and Japan, while carbon fiber-reinforced nylon handle production clusters in Zhejiang and Jiangsu provinces. Supply chain risk rests on single-source vulnerability for precision-hardened steel blades from Japanese and Swiss heat-treatment facilities. Distribution runs through dense authorized dealer-service networks in the US Midwest and Northeast capturing maintenance contract bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pruning saw market functions as a stable compounder anchored by urban tree-canopy mandates tightening across municipalities, generating compliance-driven replacement cycles regardless of broader construction cyclicality.
For Market Incumbents: Anticipate two-stroke engine phase-out friction accelerating fleet turnover among contractors with recent gasoline investments. Defend margin pools through backward integration into lithium-ion pack assembly and carbon fiber-reinforced nylon composite molding. Prioritize ANSI Z133 certification alignment to extend sales cycle advantages against non-compliant configurations. For New Entrants and Emerging Players: California Air Resources Board emission thresholds open a window for battery-electric platform specialists to capture stranded demand from gasoline equipment obsolescence. White-space targets include rural agricultural zones with sparse dealer-service coverage and developing markets where capital constraints sustain premium manual saw demand. A direct-to-arborist digital channel bypassing traditional hardware retail offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Outdoor power equipment conglomerates are the most active acquirer in this space, seeking battery-platform interoperability to consolidate fleet procurement relationships. The five-to-ten-year viability window favors precision metallurgy specialists with proprietary blade hardening IP and captive heat-treatment facilities. Monitor municipal RFP language specifying cross-compatible battery platforms as the inflection indicator for ecosystem consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Interoperability commitments from Husqvarna and STIHL force competitor ecosystem responses. |
| Carbon Fiber Handle Integration | Captive composite molding protects margin pools against aluminum die-cast volatility. |
| Dealer-Service Network Franchising | Dense authorized coverage in California and Oregon captures maintenance contract bundling. |
| ANSI Z133 Certification Investment | Municipal procurement specifications increasingly mandate certified tool configurations. |
| Backward Integration into Cells | In-house lithium-ion pack assembly insulates against raw material price volatility. |
Research Methodology
Bottom-up arborist crew and landscape contractor modeling reconciled against top-down battery-platform shipment tracking forms the analytical core of this study. Primary interviews with professional arborists, municipal procurement officers, dealer-service network managers, and composite molding engineers combined with secondary validation from EPA emission filings, California Air Resources Board compliance databases, EU F-Gas Regulation submissions, and outdoor power equipment customs records. Top-down manufacturer shipment data and bottom-up end-use demand estimates triangulate to segment-level outputs.
Input-output matrices map lithium-ion energy density improvements, carbon fiber composite adoption curves, and regulatory phase-out schedules across product type, application, end user, and material segmentation dimensions. CAGRs derive from slope analysis of replacement cycle velocity and fleet turnover patterns. Industry-specific forecast inputs include municipal tree-canopy mandate implementation timelines and vineyard replanting corridor seasonal demand spikes.
Revisions become necessary when battery-platform interoperability standards shift, lithium-ion cell supply disruptions materialize, or emission threshold acceleration compresses compliance windows beyond modeled assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Pneumatic Marking Machines Market
Tools
Hacksaw Blades Market
Tools
Bandsaw Market
Tools
Rotary Knife Cutters Market
Tools
Digital Cutting Machine Market
Tools
Indexable Tool Inserts Market
Tools
Electric Power Tools Market
Tools
Drilling Tools Market
Tools
Crimping Tool Market
Tools
Horizontal Milling Machine Market
Tools
Wood Floor Grinding Machine Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Mallets and Sledgehammers Market
Tools
Power Tool Gears Market
Tools
Global Table Saws Market
Tools
Concrete Saw Market