
 Hand Saw Market | 2026-2036
Hand Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Saw Market Foresight
EU F-Gas Regulation phase-down mandates for fluorinated greenhouse gases are shifting procurement criteria toward low-emission manufacturing processes in European hand saw production. Stanley Black & Decker leverages its vertically integrated supply chain to control raw material costs across blade steel categories. Apex Tool Group anchors its competitive position through specialized distribution to professional construction channels in North America. Robert Bosch GmbH differentiates via precision-ground tooth geometries that reduce kerf waste in hardwood applications.
A hand saw is a manually operated cutting tool consisting of a toothed blade fixed to a handle, engineered with specific tooth pitch and set angles to optimize cutting action across wood, metal, or composite substrates. Blade hardness typically ranges from 45 to 65 HRC depending on material grade, with bi-metal construction bonding high-speed steel teeth to flexible alloy backings for fatigue resistance. Crosscut saws dominate volume shipments due to universal application in construction and renovation workflows. Bi-metal blades represent the fastest-expanding material category as metalworking applications intensify in automotive repair and light industrial fabrication. Professional carpenters command premium pricing tiers, while hobbyist and homeowner segments concentrate in mass retail channels with higher price elasticity.
OSHA workplace safety standards in the United States mandate blade guard specifications and ergonomic handle designs, while REACH compliance in Europe restricts chromium and nickel content in blade coatings. Japan's METI enforces JIS standards for blade dimensional tolerance and tooth geometry precision, creating technical barriers for non-certified imports. Stakeholders must monitor evolving alloy material restrictions and ergonomic compliance thresholds as procurement specifications tighten across major demand centers.
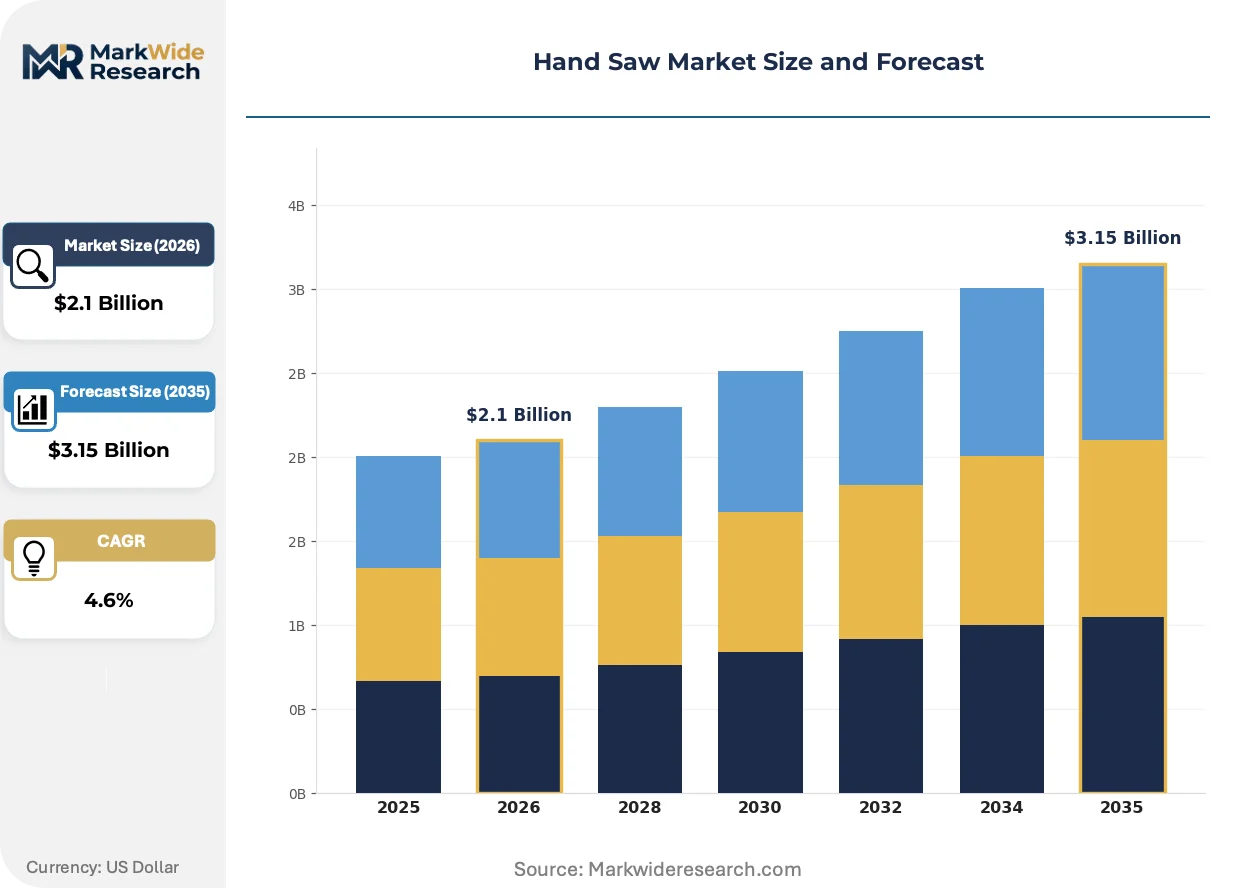
Market Dynamics
Bi-metal blade formulations are compressing the addressable market for conventional high carbon steel saws as metalworking applications intensify, while EU F-Gas Regulation mandates force manufacturing process reinvestment across European production facilities.
Growth Catalysts
- REACH compliance thresholds:Blade coating restrictions in Europe are filtering out low-cost imports and elevating certified domestic manufacturers into premium distribution channels.
- Automotive repair sector expansion:Light industrial fabrication demand for fatigue-resistant bi-metal construction is accelerating replacement cycles in professional metalworking shops.
- Suburban construction corridors:Residential development clusters in the United States are concentrating crosscut saw procurement through specialized contractor supply houses.
Market Restraints
- Alloy steel input volatility:Molybdenum and cobalt price swings in commodity markets compress margin predictability for bi-metal blade producers.
- Japanese certification concentration:METI JIS standards enforcement creates technical barriers that limit import penetration from non-certified Asian suppliers.
- Power tool substitution:Cordless circular saw adoption among renovation contractors threatens manual saw volume in speed-critical applications.
Strategic Opportunities
- German circular economy mandates:Blade refurbishment and re-sharpening service models align with EU Green Deal procurement preferences for durable goods.
- Direct-to-contractor platforms:Digital procurement channels bypass traditional distributor markups and capture professional carpenter segments previously locked into retail networks.
- Hardwood waste reduction:Precision-ground tooth geometries that minimize kerf loss are commanding specification premiums in sustainable construction certification schemes.
Industry Challenges
- Heat treatment skill scarcity:Blade hardness optimization to 45-65 HRC specifications requires specialized metallurgical expertise that is aging out of the workforce in traditional manufacturing regions.
- Ergonomic compliance fragmentation:OSHA handle design mandates diverge from Japan METI grip geometry standards, forcing dual-SKU production complexity for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Saw Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crosscut, Rip, Panel, Coping Material: High Carbon Steel, Stainless Steel, Bi-Metal, Carbide Application: Woodworking, Metalworking, DIY Projects, Home Renovation End User: Professional Carpenter, Hobbyist, Construction Workers, Homeowners |
| Companies Covered | Stanley Black & Decker, Apex Tool Group, Snap-on Incorporated, Techtronic Industries, Klein Tools, Fiskars Oyj Abp, Robert Bosch GmbH, Husqvarna, Irwin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Saw Market Shifts & Advancements
Active material science advances and procurement platform digitization are compressing traditional channel structures while regulatory material restrictions force coating chemistry reinvention.
Bi-metal construction bonding high-speed steel teeth to flexible alloy backings is consolidating market share in professional metalworking segments. Automotive repair shops and light industrial fabricators are specifying bi-metal blades for fatigue resistance in repetitive cutting operations. This material transition is consolidating procurement volumes around suppliers with captive alloy steel sourcing and in-house welding capabilities.
EU F-Gas Regulation phase-down mandates for fluorinated greenhouse gases are redirecting European manufacturing investment toward low-emission heat treatment and coating processes. Blade producers in Germany and adjacent markets are retrofitting production lines to eliminate fluorinated process gases. Professional-grade saw categories face the steepest compliance cost absorption as certification requirements tighten procurement specifications.
Professional carpenters are migrating specification authority from retail procurement officers to jobsite supervisors with direct digital purchasing access. Specialized contractor supply platforms are disintermediating traditional two-step distribution in North American construction corridors. This channel compression is most visible in suburban United States markets where project-based purchasing favors immediate availability over inventory depth.
Hand Saw Market Segmentation
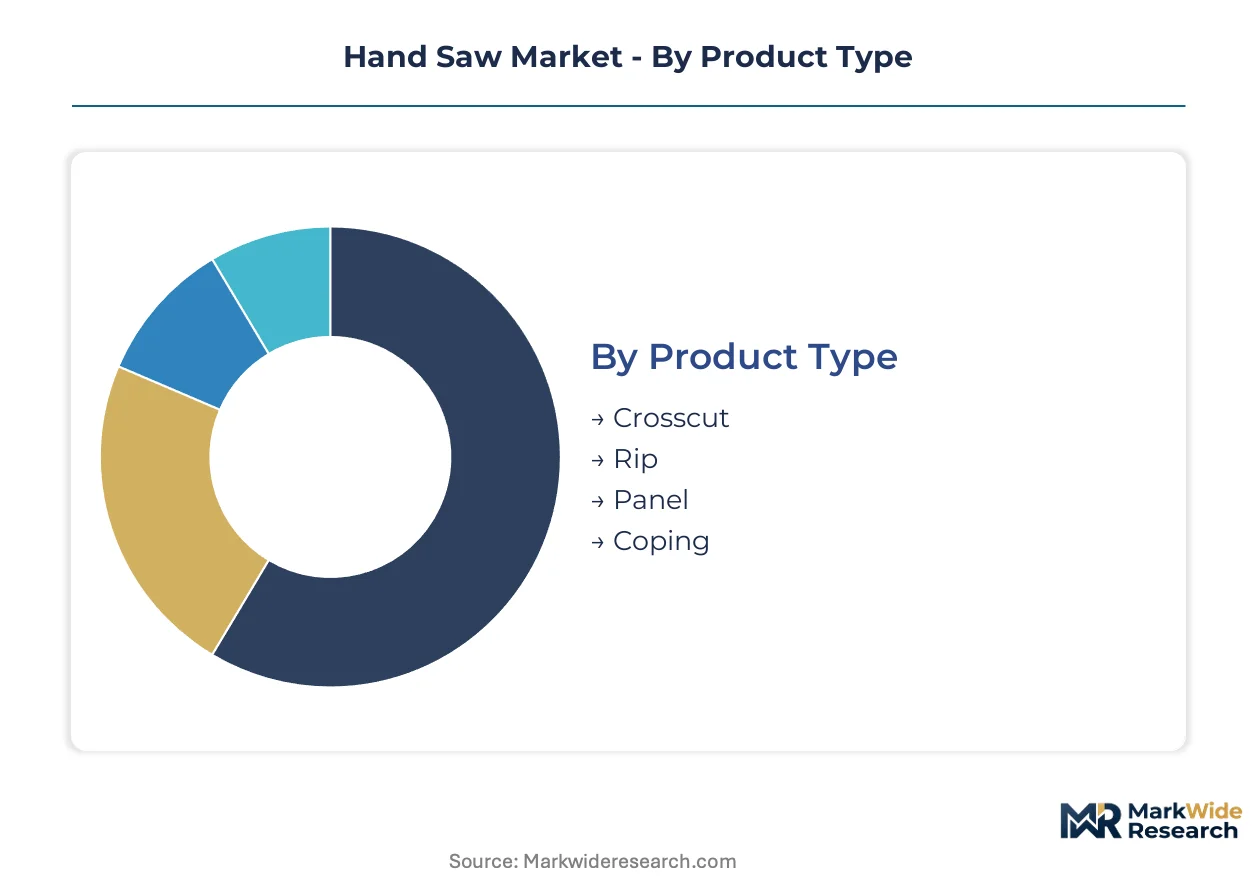
Hand saw procurement patterns diverge sharply between specification-driven professional channels and price-sensitive retail segments. Understanding these divides reveals where margin pools concentrate and which technical attributes command premium positioning.
Product Type:
Customization intensity varies from universal jobsite tools to specialized joinery instruments, with tooth geometry and blade length driving application specificity.
- Crosscut:Teeth angled for severing wood fibers across the grain, typically 8-12 points per inch. Demand clusters with professional carpenters in suburban United States construction corridors where framing and trim work dominate daily workflows.
- Rip:Chisel-like teeth aligned with the grain for longitudinal cuts, fewer teeth per inch than crosscut variants. Woodworking shops in Germany specify rip saws for solid hardwood processing where kerf precision determines material yield.
- Panel:Thin, flexible blades with reinforced backs for controlled cuts in sheet goods. Japanese cabinetry manufacturers source panel saws for veneered plywood applications requiring minimal breakout.
- Coping:Fine-tooth blades with narrow kerfs for intricate curved cuts and decorative joinery. Specialized furniture restoration workshops in Italy represent the primary demand concentration for this precision category.
Most installed capacity flows through Crosscut. Expansion is steepest in Panel.
Material:
Cost tier stratification separates commodity blade grades from engineered metallurgy, with raw material sourcing determining supplier margin durability.
- High Carbon Steel:Traditional blade material with hardness reaching 50-55 HRC through simple heat treatment. Hobbyist retail channels in the United States and mass-market hardware stores in India absorb volume as entry-level pricing sustains replacement-driven purchasing cycles.
- Stainless Steel:Corrosion-resistant formulations for humid environments and food-safe applications. Marine carpentry operations in coastal Australia and commercial kitchen installation contractors specify stainless blades for regulatory compliance and durability.
- Bi-Metal:Electron beam welding bonds high-speed steel cutting edges to flexible alloy backings, achieving 62-65 HRC at the tooth tip. Automotive repair facilities across Japan and light industrial fabricators in Germany drive specification migration toward fatigue-resistant construction.
- Carbide:Tungsten carbide tooth tips brazed to steel bodies for abrasive material cutting. Composite decking installers and fiberglass fabricators in the United States pay substantial premiums for extended edge retention in abrasive substrates.
Bi-Metal captures the steepest expansion trajectory as professional metalworking applications intensify. Carbide remains confined to specialized abrasive-cutting niches.
Application:
Customer sophistication determines whether procurement prioritizes speed, precision, or unit economics, with channel access filtering segment overlap.
- Woodworking:Encompasses rough carpentry through fine joinery, with tooth pitch and set angle calibrated to hardwood species. Professional cabinetmakers in Japan's Aichi Prefecture and custom furniture producers in North Carolina's High Point cluster specify premium tooth geometries.
- Metalworking:Requires hardened teeth and optimized rake angles for ferrous and non-ferrous stock. Machine shops in Germany's Baden-Württemberg region and automotive repair chains across the United States Midwest specify bi-metal construction for repetitive cutting operations.
- DIY Projects:Occasional-use segment prioritizing low acquisition cost over durability. Mass retailers in suburban United States markets and home improvement superstores in the United Kingdom dominate distribution.
- Home Renovation:Project-driven purchasing with mixed material cutting requirements. General contractors in Australia's Queensland and renovation specialists in France's Île-de-France region source versatile crosscut patterns for on-site adaptability.
Woodworking absorbs the greatest installed base volume. Metalworking climbs the fastest as industrial maintenance cycles compress replacement intervals.
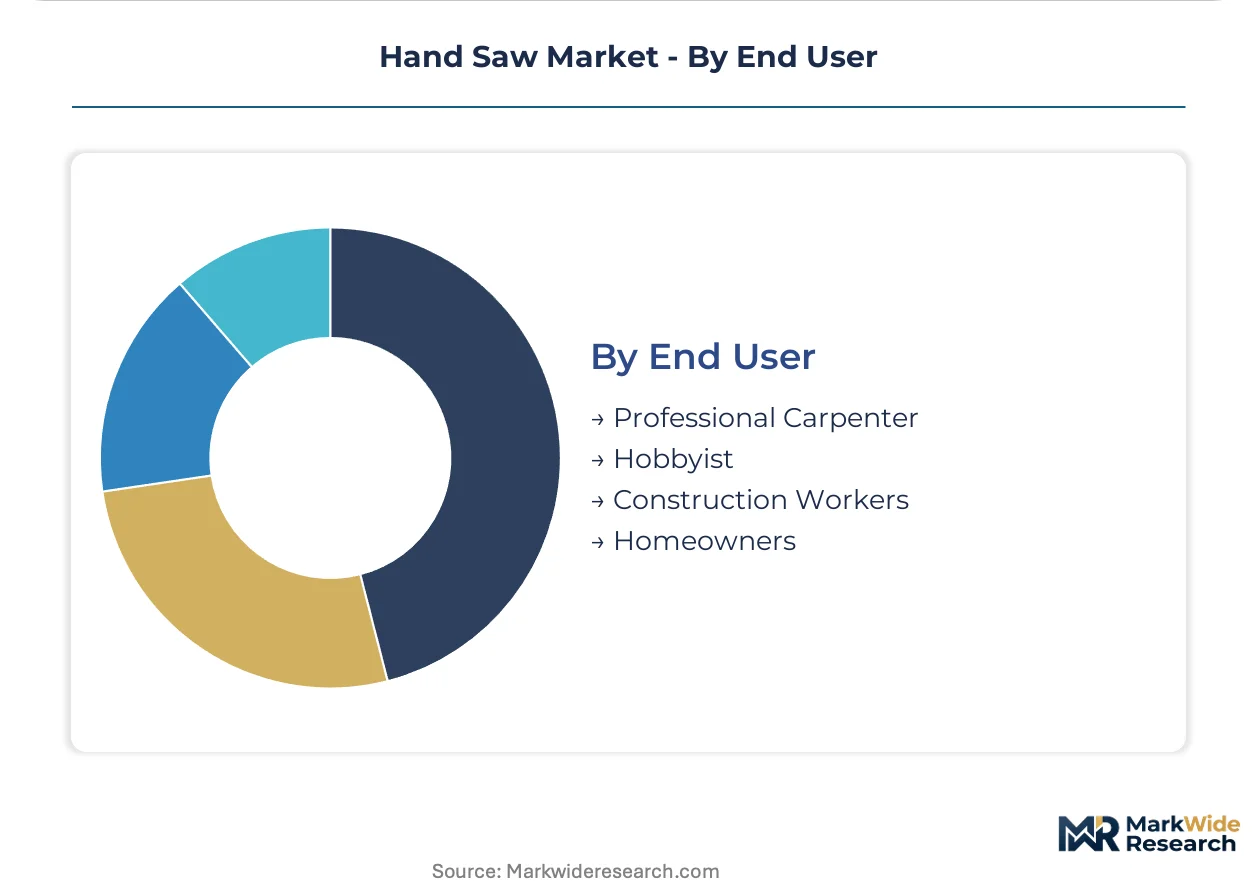
End User:
Volume concentration versus margin extraction potential separates contractor supply channels from consumer retail, with specification authority residing at different organizational levels.
- Professional Carpenter:Skilled tradespeople with direct tool specification authority and brand loyalty. Union carpenters in Chicago and Vancouver construction corridors purchase through specialized contractor supply houses with immediate availability requirements.
- Hobbyist:Enthusiast woodworkers with moderate technical knowledge and willingness to pay for performance differentiation. Membership-based retailers in Japan and boutique tool dealers in Germany's Black Forest region serve this segment.
- Construction Workers:General laborers requiring durable, replaceable tools for demanding site conditions. Large infrastructure contractors in Saudi Arabia and residential developers in Texas specify contractor-grade blades through bulk procurement programs.
- Homeowners:Infrequent users with minimal technical sophistication and high price elasticity. Big-box retailers in the United States and home center chains in the United Kingdom dominate this lowest-margin segment.
Professional Carpenter channels command the deepest margin pools. Construction Workers represent the largest volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hand saw industry traces its modern manufacturing lineage to Sheffield, England, where precision steelworking techniques developed during the Industrial Revolution established quality benchmarks still referenced today. Contemporary production and demand patterns now concentrate across five national markets where certification requirements and construction activity drive procurement specifications.
United States
Suburban construction corridors in Texas and Florida generate concentrated demand for crosscut saws among professional framing crews. OSHA workplace safety standards mandate blade guard specifications and ergonomic handle designs that filter out uncertified imports. Chicago's union carpenter networks purchase through specialized contractor supply houses with immediate availability requirements.
Germany
Baden-Württemberg's machine shops and light industrial fabricators specify bi-metal blades for repetitive metalworking operations. EU F-Gas Regulation phase-down mandates redirect manufacturing investment toward low-emission heat treatment processes. The Black Forest region hosts boutique tool dealers serving precision-oriented hobbyist segments.
Japan
Aichi Prefecture cabinetry manufacturers source panel saws for veneered plywood applications requiring minimal breakout. METI enforces JIS standards for blade dimensional tolerance and tooth geometry precision. Tokyo-area construction markets concentrate procurement through membership-based retailers with technical consultation services.
India
Mass-market hardware stores in Maharashtra and Gujarat absorb high carbon steel volumes as entry-level pricing sustains replacement-driven purchasing cycles. BIS certification requirements for hand tools create compliance thresholds for organized retail channels. Tamil Nadu's emerging industrial clusters show early specification migration toward fatigue-resistant blade constructions.
Australia
Marine carpentry operations along Queensland's coastal corridors specify stainless steel blades for humid environment durability. The country's national workplace safety regulator mandates ergonomic standards that parallel but diverge from European specifications. Sydney and Melbourne renovation specialists source versatile crosscut patterns for mixed-material on-site adaptability.
Hand Saw Market Competitive Landscape
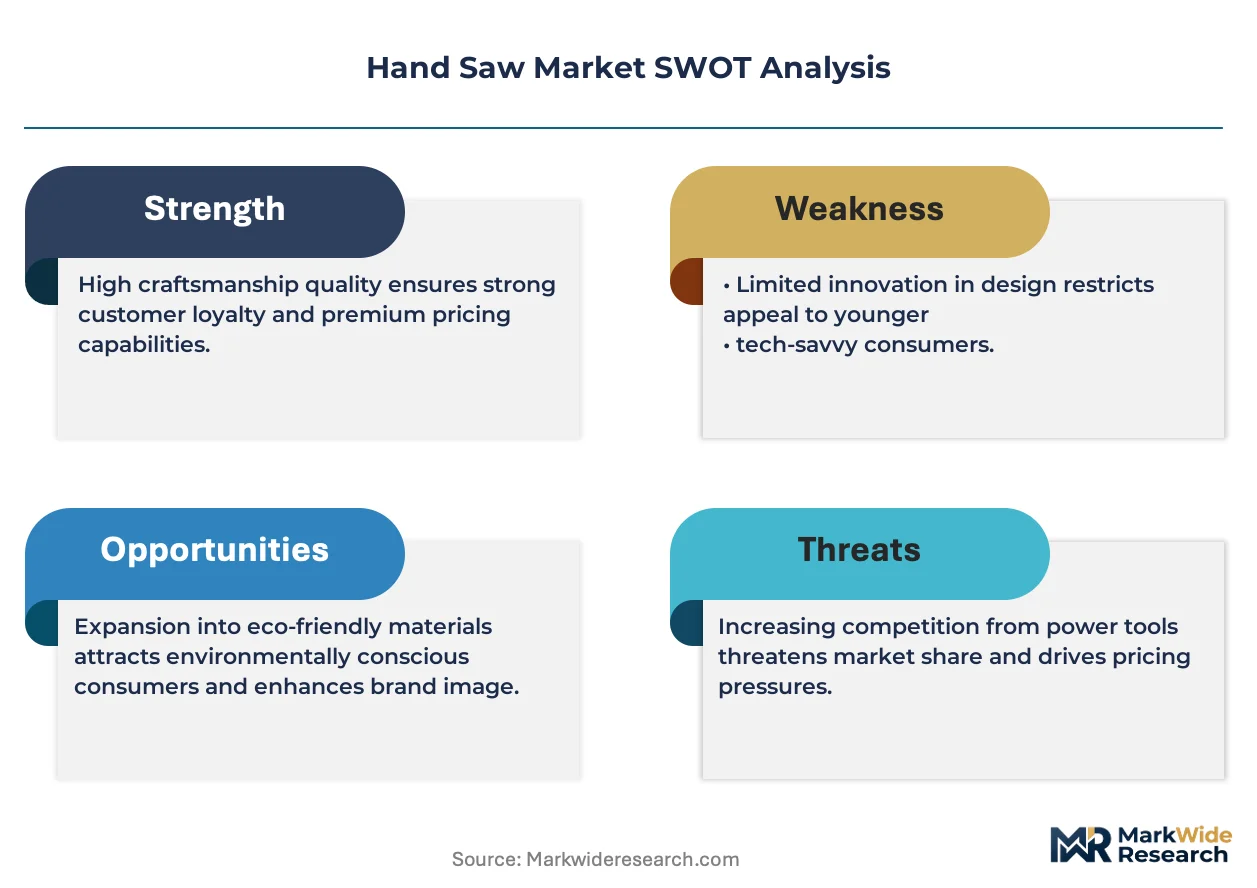
Premium-margin players sit above commodity-margin players across certification tiers, with METI JIS-compliant Japanese suppliers and REACH-certified European fabricators commanding specification premiums over mass-market imports. The vendor base organizes into three strategic archetypes: vertically integrated conglomerates with captive steel sourcing, specialized professional-channel distributors with dense contractor networks, and precision-engineering specialists with proprietary tooth geometry IP. Capacity expansion and portfolio diversification represent the dominant competitive moves, with players extending bi-metal welding capabilities and adding refurbishment service models to capture circular economy procurement preferences.
Within the vertically integrated tier, Stanley Black & Decker and Robert Bosch GmbH exemplify scale-driven positions with upstream control over raw material categories. Apex Tool Group occupies a specialized distribution anchor in North American professional construction channels. These three entities represent contrasting strategic postures: conglomerate breadth, precision engineering heritage, and channel-specific focus respectively.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Apex Tool Group |
| Snap-on Incorporated |
| Techtronic Industries |
| Klein Tools |
| Fiskars Oyj Abp |
| Robert Bosch GmbH |
| Husqvarna |
| Irwin |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between METI JIS-compliant precision manufacturers and uncertified mass-market suppliers shapes both margin capture and procurement channel configuration across the hand saw industry. REACH-certified European fabricators and Japanese precision-engineered products command specification premiums through restricted distribution networks, while high carbon steel commoditization in Indian mass retail channels compresses pricing power and forces volume-dependent supply strategies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates professional-grade bi-metal blades from contractor-grade crosscut saws and hobbyist high carbon steel variants. Price differentiation rests on METI JIS certification status and captive alloy steel sourcing capabilities. Cost compression in economy tiers intensifies because molybdenum and cobalt commodity volatility squeezes bi-metal blade margins. Homeowners exhibit highest price sensitivity through big-box retail channels, while union carpenters in Chicago and Vancouver demonstrate lowest sensitivity due to immediate availability requirements and brand loyalty.
Supply Chain Analysis
Specialized heat treatment expertise scarcity in Sheffield's traditional manufacturing region and Germany's Black Forest area constrains blade hardness optimization to 45-65 HRC specifications. Production gravity centers on Germany, Japan, and the United States for precision-engineered categories, with India absorbing high carbon steel commoditization. Raw material dependencies draw from Swedish alloy steel, Chinese tungsten carbide, and Australian cobalt concentrates. Single-source vulnerability concentrates in electron beam welding equipment for bi-metal construction. Distribution runs through specialized contractor supply houses in North American suburban corridors, membership-based retailers in Japan, and mass-market hardware stores in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hand saw market represents a late-cycle quality story as professional carpenters migrate specification authority toward jobsite supervisors demanding precision-ground tooth geometries and fatigue-resistant bi-metal construction. This demand shift toward premium specifications rewards suppliers with captive metallurgical capabilities and certification compliance infrastructure.
For Market Incumbents: To counter cordless circular saw substitution in speed-critical renovation applications, incumbents should deepen precision-ground tooth geometry IP investment for hardwood waste reduction premiums and establish blade refurbishment service models aligned with German circular economy mandates. Channel control through direct-to-contractor digital platforms captures specification authority migration from retail procurement officers. For New Entrants and Emerging Players: Begin with India's Tamil Nadu industrial clusters showing early specification migration toward fatigue-resistant blade constructions, where BIS certification thresholds filter organized retail access. Target marine carpentry operations in Queensland's coastal corridors requiring stainless steel corrosion resistance. A go-to-market angle emphasizing humid-environment durability specifications bypasses established bi-metal welding capability barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where heat treatment skill scarcity in traditional manufacturing regions meets aging workforce demographics and compliance fragmentation between OSHA ergonomic mandates and Japan METI grip geometry standards. Long-term viability favors vertically integrated positions with captive alloy steel sourcing and in-house electron beam welding capabilities. The signal to watch is procurement platform digitization velocity in North American suburban construction corridors, indicating channel compression maturity and margin pool redistribution timing.| Strategic Initiative | Industry Significance |
|---|---|
| Bi-Metal Welding Capability Expansion | Captures automotive repair sector demand acceleration across Japan and Germany. |
| Blade Refurbishment Service Launch | Aligns with EU Green Deal procurement preferences in German industrial markets. |
| Direct-to-Contractor Platform Development | Bypasses distributor markups in Texas and Florida suburban construction corridors. |
| Precision Tooth Geometry IP Investment | Commands specification premiums in sustainable construction certification schemes. |
| Dual-Certification SKU Rationalization | Reduces production complexity from divergent OSHA and METI ergonomic mandates. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers at blade manufacturing facilities, procurement leads at automotive repair chains, distribution channel partners in contractor supply houses, and aftermarket service heads at industrial fabricators combined with secondary validation from customs/trade data, SEC 10-K filings of publicly traded tool manufacturers, and METI JIS certification registries. This approach triangulates volume estimates against capacity disclosures and shipment tracking.
Historical trendline analysis across blade material substitution patterns and certification compliance trajectories informed projection frameworks. The model segments by product type, material grade, application intensity, and end-user sophistication across the projection horizon. CAGRs derive from regression analysis of replacement cycle compression in metalworking applications and suburban construction corridor demand clustering. Industry-specific forecast inputs include alloy steel commodity price volatility indices and regulatory compliance cost absorption rates.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to EU F-Gas Regulation phase-down timelines and disruptive power tool technology introductions. Forecasts reflect assumptions about continued professional carpenter preference for manual precision in finish carpentry applications. Practitioners should monitor cordless circular saw battery efficiency improvements and Chinese bi-metal blade import penetration rates for early signals of demand elasticity shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Workholding Tools Market
Tools
Global Cordless Power Tools Market
Tools
Metal Cutting Tools Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Welding Guns Market
Tools
Rivet Busters Market
Tools
Cordless Power Drill Market
Tools
Friction Washer Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Rebar Cutter Market
Tools
Automatic Lathe Machines Market
Tools
Water Pump Pliers Market
Tools
Entrenching Tool Market
Tools
Drill Set Market
Tools
Nail Gun Market
Tools
Global Protractor Market