
 Air Conditioning Repair Market | 2026-2036
Air Conditioning Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Air Conditioning Repair Market Insights
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is shifting the cost-of-entry calculus for independent repair contractors across the United States. Carrier leverages its captive distribution network to sustain aftermarket parts availability as refrigerant transitions accelerate. Daikin Industries anchors its North American position through dedicated training infrastructure for next-generation coolant handling. Lennox International competes on predictive maintenance platforms that reduce emergency dispatch frequency for commercial clients.
Air conditioning repair encompasses the diagnostic, corrective, and preventive servicing of mechanical vapor-compression refrigeration systems operating with refrigerants at pressures between 150 and 450 psi, restoring thermal comfort and humidity control in enclosed environments. The service spans compressor replacement, coil cleaning, refrigerant recovery, and electrical troubleshooting across units ranging from 1.5-ton residential splits to 500-ton industrial chillers. Preventive maintenance commands the most stable margin pool as building operators prioritize uptime guarantees over reactive emergency repair, while ductless mini-split technology represents the fastest-growing equipment category requiring specialized technician certification. Residential end users generate the highest call volume but exhibit the greatest price sensitivity, compressing labor rates in saturated urban markets.
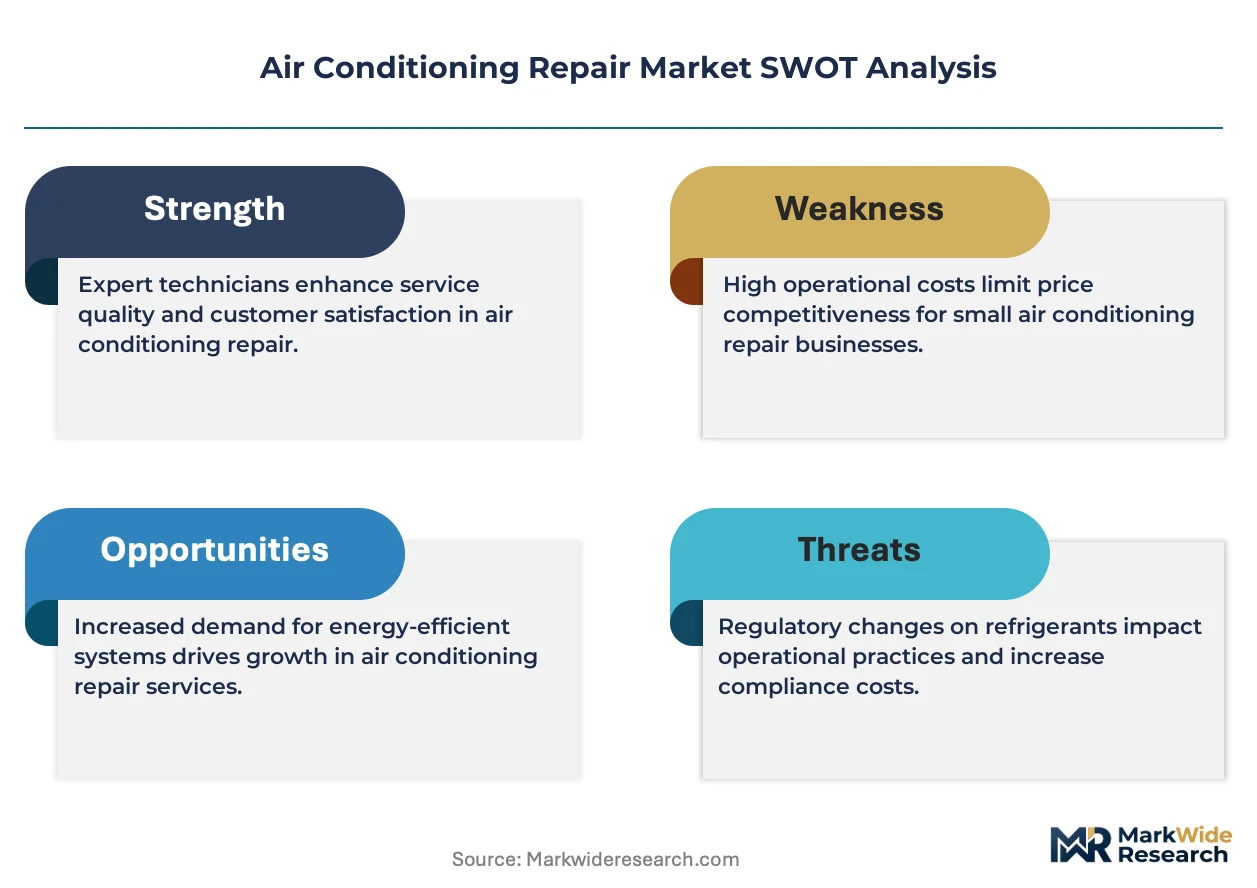
The EPA enforces refrigerant handling certification under Section 608 of the Clean Air Act, mandating technician credentials that limit market participation and elevate labor pricing power for compliant operators. The Department of Energy's minimum efficiency standards for cooling equipment reshape replacement economics, pushing premature retirement of repairable but non-compliant units. OSHA's heat illness prevention directives for outdoor workers indirectly expand commercial cooling infrastructure requirements in southern states. Stakeholders must monitor the trajectory of state-level refrigerant regulations that outpace federal timelines, as California's early HFC prohibitions demonstrate how fragmented compliance obligations fragment service provider operating territories.
Market Dynamics
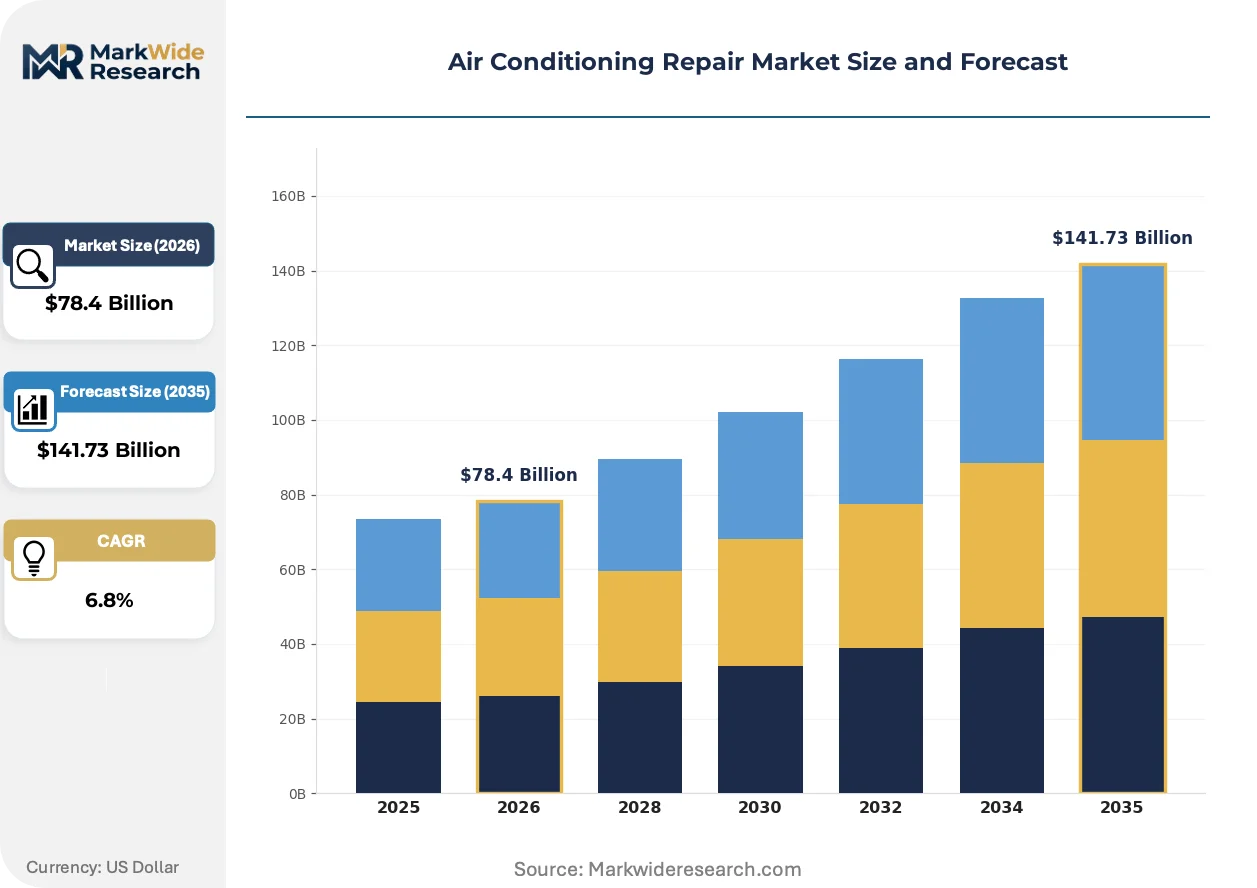
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing equipment replacement cycles and forcing systematic technician retraining across the United States, restructuring how contractors price service calls and manage parts inventory.
Growth Catalysts
- Commercial real estate retrofit mandates:Aging building stock in the United States, Germany, and Japan requires systematic HVAC overhaul as energy efficiency codes tighten.
- Section 608 certification requirements:EPA refrigerant handling credentials limit market participation and elevate labor pricing power for compliant operators.
- Heat illness prevention directives:OSHA outdoor worker protections in southern states expand commercial cooling infrastructure requirements.
Market Restraints
- Refrigerant supply concentration:Dependence on limited domestic producers of next-generation coolants creates price volatility during transition periods.
- Technical skill obsolescence:Rapid refrigerant chemistry shifts render existing technician expertise non-transferable without costly retraining.
- Equipment replacement economics:Department of Energy minimum efficiency standards push premature retirement of repairable but non-compliant units.
Strategic Opportunities
- Predictive maintenance platforms:Sensor-enabled diagnostics reduce emergency dispatch frequency for commercial clients seeking uptime guarantees.
- Ductless mini-split specialization:Fastest-growing equipment category creates white space for certified technicians in residential and light commercial segments.
- State-level regulatory fragmentation:California's early HFC prohibitions demonstrate how accelerated timelines fragment service territories and reward early compliance investment.
Industry Challenges
- Technician certification pipeline:Section 608 credentialing timelines create bottlenecks as refrigerant transitions accelerate and training capacity lags demand.
- Legacy system integration complexity:Retrofitting next-generation refrigerants into existing vapor-compression infrastructure requires custom engineering and voids manufacturer warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Conditioning Repair Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Repair, Preventive Maintenance, Installation, System Upgrade End User: Residential, Commercial, Industrial, Government Technology: Central Air, Ductless Mini-Split, Portable Units, Window Units System Type: AC Units, Heat Pumps, Refrigeration Systems, Chillers |
| Companies Covered | Carrier, Daikin Industries, Lennox International, Trane Technologies, Johnson Controls, Rheem Manufacturing Company, Emcor Group, Comfort Systems USA, American Standard Heating and Air Conditioning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Conditioning Repair Market Trends and Innovations
Refrigerant chemistry transitions and connected diagnostics are compressing traditional service models, forcing contractors to rebuild capabilities around data-driven maintenance and specialized coolant handling.
Variable refrigerant flow systems with integrated inverter compressors are electrifying how commercial buildings manage zonal cooling loads. Large-format office operators in the United States Sun Belt are deploying these systems at accelerated pace to reduce peak demand charges. The technology is electrifying competitive positioning among contractors who can install and service multi-port distribution networks.
The EPA's AIM Act phasedown schedule is forcing wholesale replacement of service equipment and recovery cylinders across the United States. Independent contractors face capital outlays for compliant handling apparatus before existing stocks deplete. Commercial service fleets are responding fastest, consolidating refrigerant inventory management through centralized depot models.
Building operators now unbundle preventive maintenance from emergency repair contracts, soliciting standalone uptime guarantees through multi-year service level agreements. This procurement pattern compresses margins for reactive service providers while rewarding predictive capability. The shift is most visible among United States hospital and data center operators with zero-downtime requirements.
Air Conditioning Repair Market Segmentation
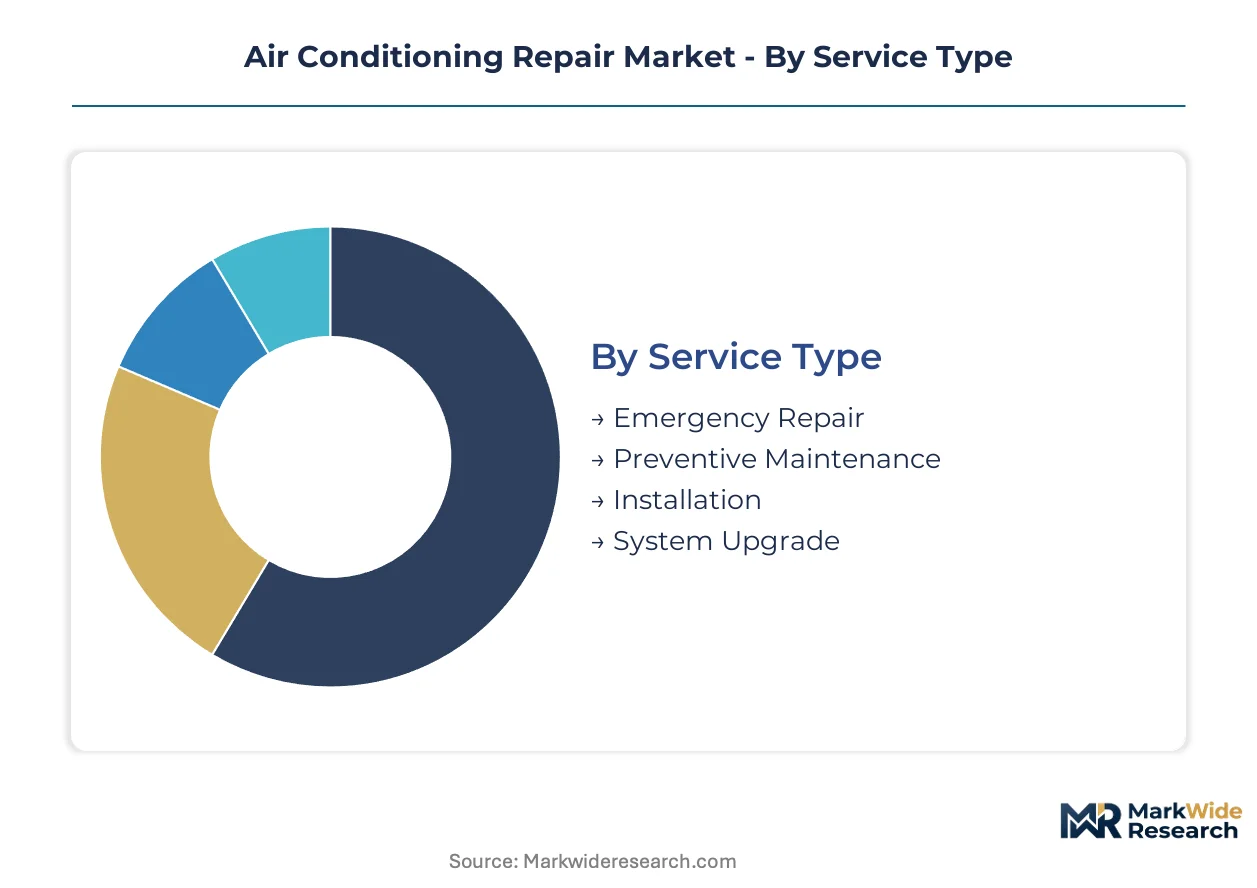
Segmentation in air conditioning repair reveals how certification burdens, equipment complexity, and end-use requirements fragment service provider capabilities and pricing power across distinct operational tiers.
Service Type:
Emergency repair demands EPA Section 608 certification for refrigerant handling, while preventive maintenance contracts increasingly require NATE or manufacturer-specific credentials for warranty preservation.
- Emergency Repair:Reactive dispatch for compressor failure, refrigerant leaks, or electrical faults in systems operating at 150-450 psi. Demand concentrates in the United States Sun Belt during extreme heat events, where commercial density and aging infrastructure sustain highest per-capita incident rates. Labor pricing power elevates during peak seasonal stress when certified technician availability tightens.
- Preventive Maintenance:Scheduled coil cleaning, refrigerant level verification, and electrical connection inspection to sustain thermal output efficiency. Building operators in United States hospital and data center segments unbundle this from emergency contracts, seeking standalone uptime guarantees through multi-year service level agreements. This segment commands the most stable margin pool as procurement shifts toward outcome-based retention.
- Installation:New system deployment requiring load calculation, ductwork modification, and regulatory compliance verification.
- System Upgrade:Retrofit of next-generation refrigerant-compatible components into existing vapor-compression infrastructure.
Preventive maintenance sits at the top of the volume ranking, with system upgrade climbing the fastest as EPA AIM Act timelines accelerate equipment replacement cycles.
End User:
Cost tier differentiation separates price-sensitive residential call volume from commercial operators prioritizing uptime guarantees over per-incident labor rates.
- Residential:Single-family and multi-family dwelling owners generating highest call volume but exhibiting greatest price sensitivity. Service requests concentrate on ductless mini-split and central air systems under 5 tons. Saturated urban markets compress labor rates as independent contractors compete for discretionary repair decisions.
- Commercial:Office buildings, retail spaces, and hospitality operators across the United States, Germany, and Japan. Aging building stock and tightening energy efficiency codes drive systematic HVAC overhaul requirements. Procurement now favors predictive maintenance platforms that reduce emergency dispatch frequency.
- Industrial:Manufacturing facilities and process cooling applications requiring specialized chiller and refrigeration system expertise.
- Government:Municipal buildings, military installations, and public infrastructure subject to procurement regulations and extended equipment lifecycles.
Commercial end users dominate value capture, with residential expanding most quickly in emerging ductless mini-split penetration zones.
Technology:
Application complexity determines whether standard technician training suffices or specialized manufacturer certification becomes mandatory for warranty-valid service.
- Central Air:Traditional ducted vapor-compression systems serving whole-building cooling loads. Mature installed base across United States suburban and commercial construction from 1980-2010 generates steady replacement and repair demand as refrigerant transitions render legacy equipment obsolete.
- Ductless Mini-Split:Zonal cooling with integrated inverter compressors and multi-port distribution networks. Fastest-growing equipment category requiring specialized technician certification for refrigerant circuit management and electronic control diagnostics. United States Sun Belt large-format office operators deploy these at accelerated pace to reduce peak demand charges.
- Portable Units:Self-contained mobile cooling for temporary or supplemental applications.
- Window Units:Fixed-installation residential cooling with limited serviceability and replacement-driven economics.
Central air retains the largest installed base, with ductless mini-split gaining share fastest across commercial retrofit and residential new construction.
System Type:
Supply concentration for replacement parts and refrigerant compatibility creates divergent margin structures across equipment categories.
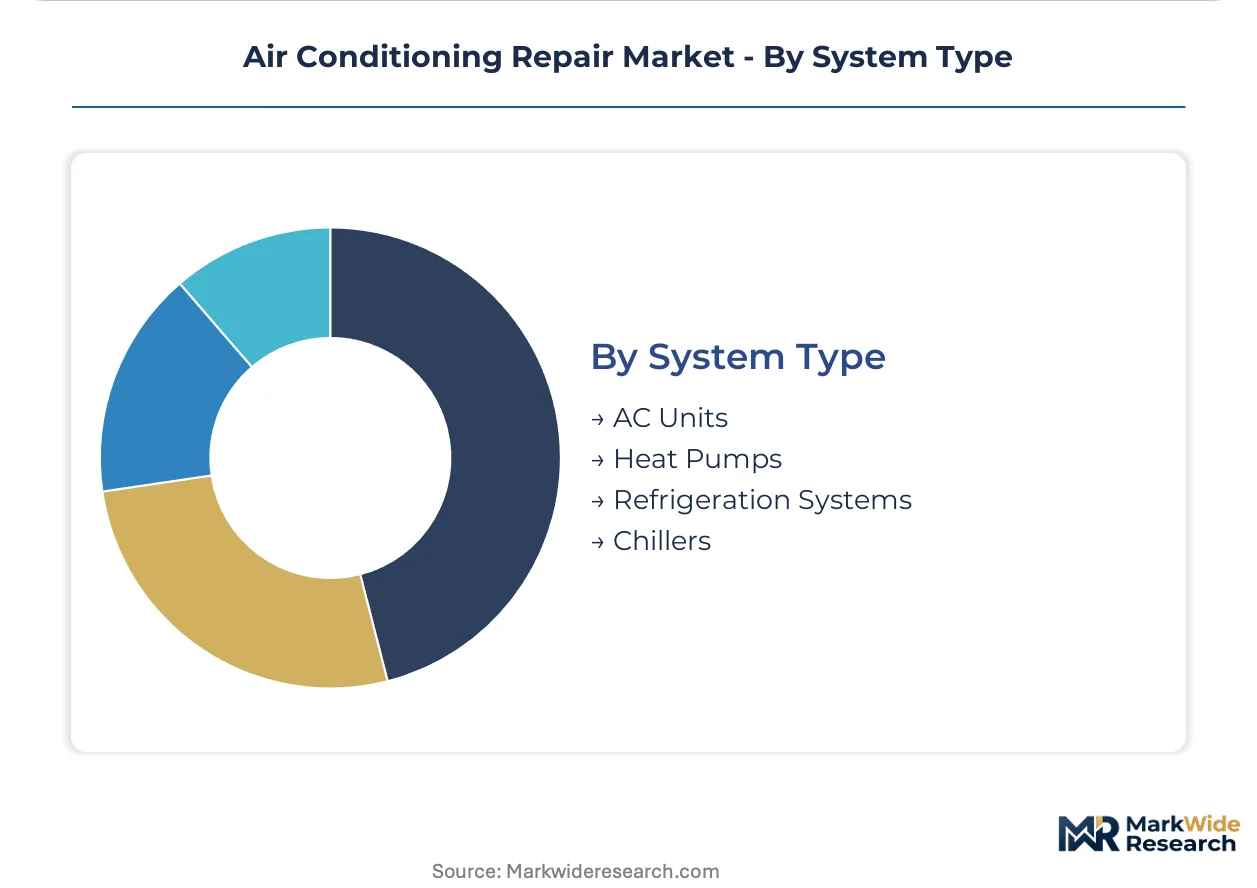
- AC Units:Mechanical vapor-compression systems dedicated to cooling-only operation. Dominant residential and light commercial installed base with established parts distribution networks and broad technician familiarity.
- Heat Pumps:Reversible refrigeration cycles providing both heating and cooling. Department of Energy minimum efficiency standards push premature retirement of repairable but non-compliant units, accelerating replacement timelines in United States northern states where heating load dominates.
- Refrigeration Systems:Commercial food service and cold chain applications with specialized temperature control requirements.
- Chillers:Large-format centrifugal or screw-compressor systems serving industrial and institutional cooling loads above 100 tons.
AC units sit at the top of the volume ranking, with heat pumps climbing the fastest as electrification mandates and efficiency standards reshape replacement economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified technician density concentrates in mature HVAC markets where aging infrastructure and regulatory complexity elevate service specialization requirements.
United States
Commercial real estate operators in the Sun Belt drive emergency repair volume as extreme heat duration sustains highest per-capita incident rates. EPA Section 608 certification mandates limit market participation and elevate labor pricing power for compliant contractors. Phoenix and Houston anchor demand clusters where large-format office operators deploy predictive maintenance platforms to reduce peak demand charges.
Germany
Aging building stock across industrial zones requires systematic HVAC overhaul as energy efficiency codes tighten. The EU F-Gas Regulation accelerates refrigerant transition timelines and forces technician retraining across service networks. The Rhine-Ruhr metropolitan region concentrates retrofit demand as commercial operators seek uptime guarantees through multi-year service agreements.
Japan
Commercial facility managers prioritize preventive maintenance contracts as humidity control requirements intensify in dense urban environments. METI efficiency standards push premature retirement of repairable but non-compliant cooling equipment. Tokyo and Osaka anchor technician training infrastructure as Daikin Industries invests in next-generation coolant handling certification programs.
China
Rapid urbanization and commercial construction expansion generate sustained installation and repair demand across tier-one cities. MEE dual carbon goals reshape equipment replacement economics and elevate efficiency requirements for new cooling systems. The Yangtze River Delta concentrates service provider networks as building operators unbundle preventive maintenance from emergency repair contracts.
India
Ductless mini-split penetration accelerates across residential and light commercial segments as cooling demand intensifies in tropical climates. BIS standards and state-level energy efficiency directives fragment compliance obligations for independent contractors. Maharashtra and Gujarat anchor technician certification pipelines as commercial real estate operators in Mumbai and Ahmedabad prioritize uptime guarantees.
Air Conditioning Repair Market Competitive Landscape
The competitive structure tilts toward diversified HVAC manufacturers with captive distribution networks and aftermarket parts capabilities. Consolidation pressure concentrates among mid-scale independent contractors facing capital outlays for refrigerant transition compliance. Three archetypes dominate: integrated equipment-service conglomerates, specialized commercial service providers, and regional independent contractors. Strategic moves center on predictive maintenance platform development and technician training infrastructure expansion.
Among integrated manufacturers, Carrier, Daikin Industries, and Lennox International exemplify the equipment-to-service archetype. Carrier occupies a position anchored by aftermarket parts availability as refrigerant transitions accelerate. Daikin Industries represents the training-forward model through dedicated infrastructure investment. Lennox International sits within the predictive maintenance tier, reducing emergency dispatch frequency for commercial clients seeking uptime guarantees.
| Leading Market Players |
|---|
| Carrier |
| Daikin Industries |
| Lennox International |
| Trane Technologies |
| Johnson Controls |
| Rheem Manufacturing Company |
| Emcor Group |
| Comfort Systems USA |
| American Standard Heating and Air Conditioning |
| Others |
Pricing and Supply Chain Analysis
R-410A refrigerant spot pricing volatility cascades through contractor cost structures, compressing margins for independent operators while integrated manufacturers absorb shocks through captive supply arrangements. The commodity benchmark drives tiered service pricing as EPA Section 608 certification scarcity elevates labor rates for compliant technicians above uncertified competitors.
Pricing Analysis
Bundled emergency repair contracts command premium rates against unbundled preventive maintenance subscriptions as building operators separate uptime guarantees from reactive dispatch. Three-tier pricing structure across EPA-certified premium, NATE-accredited standard, and uncertified economy levels reflects technician credential scarcity. Pricing pressure stems from refrigerant transition capital outlays forcing contractor consolidation. Residential end users exhibit greatest price sensitivity, while hospital and data center operators prioritize outcome-based retention over per-incident labor costs.
Supply Chain Analysis
Direct-to-commercial-fleet channels handle bulk refrigerant and recovery equipment procurement for multi-location service operators across the United States, Germany, and Japan. Manufacturing concentrates in China for compressor components, Mexico for coil assemblies, and the United States for specialized handling apparatus. Raw material flows draw from aluminum smelters, copper refiners, and fluorochemical producers. Single-source vulnerability in next-generation HFO refrigerant supply creates procurement risk as domestic production capacity lags EPA AIM Act phasedown timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air conditioning repair market compounds steadily as aging building stock and refrigerant transition mandates sustain replacement-driven demand regardless of cyclical construction activity.
For Market Incumbents: Acquire specialized ductless mini-split certification programs to preempt technician training bottlenecks as VRF system penetration accelerates. Consolidate refrigerant inventory management through centralized depot models to offset capital outlay pressures from EPA compliance requirements. Backward integration into aftermarket parts distribution defends margin position against independent contractor price competition. For New Entrants and Emerging Players: Launch via predictive maintenance platform partnerships targeting Sun Belt commercial real estate operators seeking uptime guarantees. White space concentrates in state-level regulatory fragmentation zones where California-style early HFC prohibitions create compliance complexity that national chains navigate poorly. Go-to-market positioning centers on EPA Section 608 certification speed as competitive differentiator. For Investors and Strategic Acquirers: Asymmetric upside sits with regional independent contractors possessing dense technician networks in high-incident geographies. Long-term viability frames around refrigerant transition completion as consolidation pressure peaks and surviving operators capture pricing power. Watch state regulatory acceleration as inflection signal—early HFC prohibition jurisdictions indicate where federal timelines will compress next.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | EPA Section 608 credential scarcity elevates labor pricing power for training-capable operators. |
| Predictive Maintenance Platform Deployment | Sensor-enabled diagnostics reduce emergency dispatch frequency for hospital and data center clients. |
| Refrigerant Inventory Centralization | Depot models consolidate handling equipment costs across commercial service fleets during AIM Act transition. |
| Ductless Mini-Split Specialization | Fastest-growing equipment category creates margin expansion for certified technicians in Sun Belt markets. |
| State-Level Regulatory Compliance Prepositioning | Early HFC prohibition jurisdictions fragment territories and reward advance certification investment. |
Research Methodology
Multiple input streams — primary interviews with HVAC service executives, EPA regulatory affairs specialists, and commercial building operations managers; secondary validation through DOE efficiency standard filings, EPA Section 608 certification databases, and ACC industry statistics; plus customs records for refrigerant and equipment trade flows — were reconciled through bottom-up and top-down triangulation.
Historical growth trajectories were cross-referenced against panel input from contractor associations and equipment manufacturers to anchor projections across the analysis window. Segmentation dimensions modeled include service type, end-user vertical, equipment technology, and system capacity tier. CAGRs were derived from installed base replacement cycles, refrigerant transition timelines, and efficiency standard compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated state-level HFC prohibitions or supply disruptions in next-generation refrigerant production. Periodic stress-testing of base assumptions is recommended as EPA phasedown schedules and DOE efficiency standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mechanical and Electrical Services
Rotary Machinery Market
Mechanical and Electrical Services
US Electrical Services Market
Mechanical and Electrical Services
Diaphragm Coupling in Turbo Machinery Market
Mechanical and Electrical Services
Pneumatic Cylinder Market
Mechanical and Electrical Services
Pressure Pumping Services Market
Mechanical and Electrical Services
Spur Gear Market
Mechanical and Electrical Services
Global Mechanical Electrical and Plumbing (MEP) Services Market
Mechanical and Electrical Services
MEP Services in US Market