
 Multi-Tasking Machine Tools Market | 2026-2036
Multi-Tasking Machine Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Tasking Machine Tools Market Outlook
ISO 9001 and ISO 230 machine-tool qualification cycles are redrawing competitive entry barriers across the supply base. DMG MORI leverages its integrated spindle and control architecture to dominate high-mix, low-volume aerospace workflows. Yamazaki Mazak Corporation anchors Japanese precision manufacturing with extensive five-axis multi-tasking portfolios. Nakamura-Tome differentiates through twin-spindle, twin-turret configurations that compress cycle times for medical device makers.
Multi-tasking machine tools integrate turning, milling, drilling, and grinding operations within a single work envelope, typically achieving positioning accuracies below five micrometers on linear axes. These systems eliminate work-in-process inventory and reduce fixture investment for complex prismatic and rotational components. Turning Centers command the largest installed base among product categories, while Hybrid Systems combining additive and subtractive processes represent the fastest-expanding technology segment. Within end-use verticals, Medical Devices concentrates margin pools due to stringent surface-finish requirements and small batch sizes that reward machine flexibility.
FDA device-quality regulations and EU MDR traceability mandates shape validation protocols for medical-oriented machine builders, while CE marking and Machinery Directive compliance gate European market access. In the United States, OSHA machine-guarding standards influence enclosure and interlock design for domestic installations. Buyers should evaluate supplier certification depth against their target end-use verticals before committing to platform standardization.
Market Dynamics
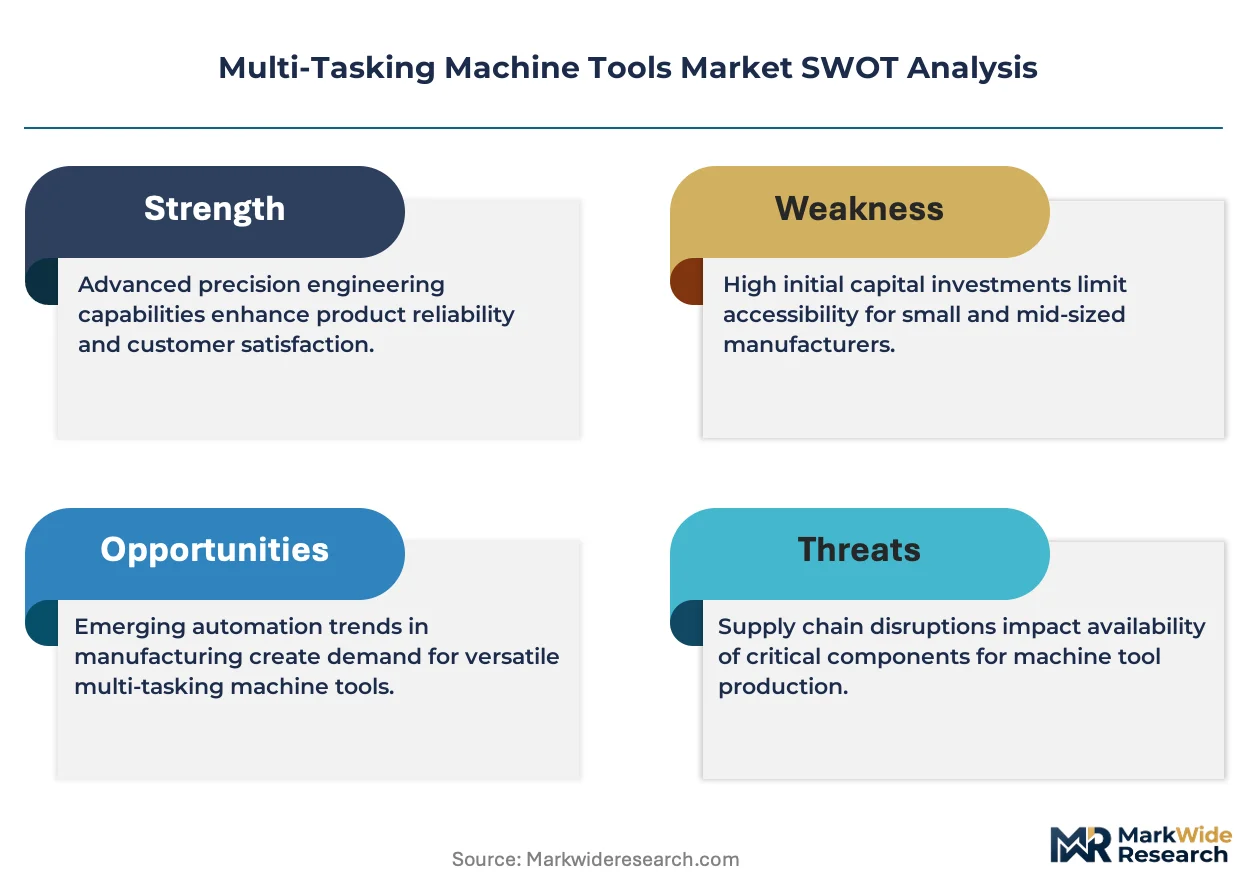
ISO 230 machine-tool qualification cycles and CE marking enforcement are consolidating supplier ecosystems by raising capital barriers for entrants lacking certification depth. Aerospace and medical device manufacturers now demand traceable validation documentation that only vertically integrated builders can provision at scale.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers in Germany and Switzerland require validated multi-tasking platforms with documented surface-finish consistency, compressing supplier qualification timelines for certified builders.
- Aerospace part consolidation:Boeing and Airbus tier-one suppliers in Wichita and Toulouse adopt twin-spindle configurations to machine titanium structural components in single setups, eliminating inter-process queuing.
- Hybrid manufacturing convergence:Directed energy deposition integrated within five-axis turning centers enables repair of Inconel turbine blades without fixture requalification, opening aftermarket service revenue streams.
Market Restraints
- Precision bearing supply concentration:Ceramic hybrid spindle bearings from Japanese and German suppliers face allocation constraints during semiconductor equipment demand surges, extending machine delivery lead times.
- Technical limitation in micro-milling:Thermal drift during simultaneous five-axis interpolation limits achievable surface finishes below Ra 0.2 micrometers on cobalt-chrome medical implants, restricting addressable applications.
- OSHA machine-guarding compliance costs:Interlocked enclosure redesigns for US installations add engineering validation expenses that disproportionately burden mid-volume machine builders.
Strategic Opportunities
- Underpenetrated Indian precision engineering:Bengaluru and Pune aerospace clusters lack domestic multi-tasking capacity, creating import substitution potential for builders establishing local spindle service infrastructure.
- Battery tray machining for electric vehicles:Large-format aluminum extrusions for automotive battery enclosures require simultaneous five-axis contouring and high-torque turning, a specification gap unaddressed by conventional machining centers.
- Japan METI smart factory subsidies:Domestic manufacturers receive tax incentives for equipment integrating real-time tool-wear monitoring and predictive maintenance algorithms, accelerating digital-native platform adoption.
Industry Challenges
- Multi-axis programming skill scarcity:CAM software proficiency for simultaneous five-axis toolpath generation remains concentrated among German and Japanese technical institutes, constraining workforce scalability.
- ISO 230-2 geometric verification timelines:Laser interferometer and ballbar testing protocols extend factory acceptance testing by three to four weeks, compressing revenue recognition cycles.
- Legacy DNC integration complexity:Shop-floor data collection from pre-2015 machine controllers requires proprietary gateway hardware, fragmenting digital thread architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Tasking Machine Tools Market |
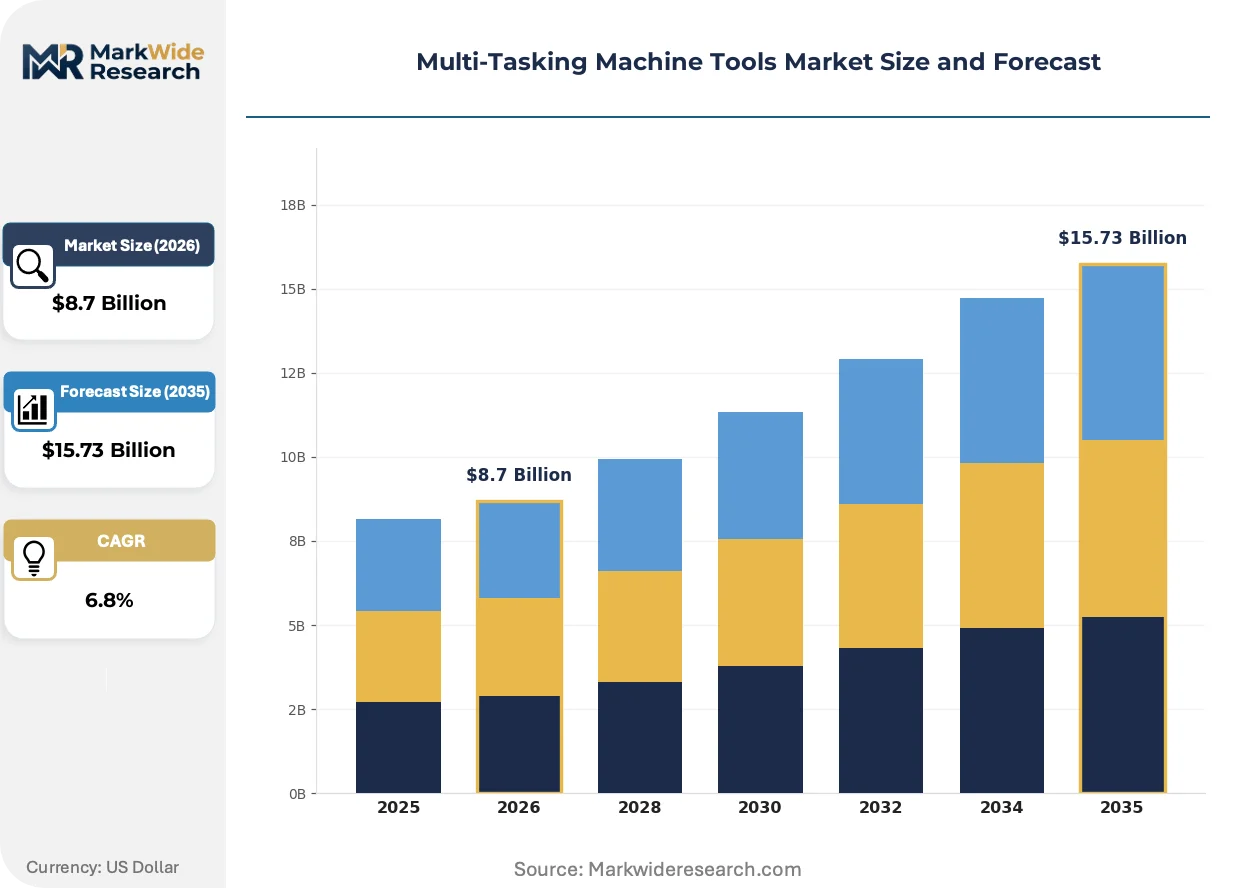
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turning Centers, Machining Centers, Multi-Function Machines, Laser Machines End User: Aerospace, Automotive, Electronics, Medical Devices Technology: CNC, Hybrid Systems, Additive Manufacturing, Automation Application: Precision Machining, Prototyping, Production Machining, Tooling |
| Companies Covered | DN Solutions, Nakamura-Tome, DMG MORI, EMAG, Tsongami Corporation, Yamazaki Mazak Corporation, Haas Automation, Doosan Corporation, Okuma Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Tasking Machine Tools Market Strategic Shifts
Control architecture unification and real-time process monitoring are compressing the boundary between metal-cutting operations and quality assurance, embedding metrology within the machining cycle itself.
Hybrid systems combining directed energy deposition with five-axis milling are decomposing the traditional separation between additive repair and precision finishing. MRO facilities in Singapore and Hamburg adopt these platforms to restore worn aerospace landing gear components without removing them from fixture pallets. The technology is decomposing capital allocation patterns by converting fixed repair infrastructure into flexible, part-agnostic cells.
REACH substance restrictions on cobalt-containing cutting fluids are forcing reformulation of high-performance coolants used in titanium machining. German chemical suppliers now market boron-nitride enhanced alternatives that maintain lubricity while satisfying ECHA registration requirements. Medical device subcontractors in Tuttlingen and Solothurn face the steepest compliance costs due to surface-residue testing protocols.
Buyer consolidation among tier-one automotive suppliers is compressing equipment specification cycles from eighteen months to nine months. Procurement teams at Continental and Bosch demand standardized HMI interfaces across mixed-vendor fleets, pressuring control architecture divergence. This pattern is most visible in Stuttgart and Munich manufacturing corridors, where supplier parks enforce common data exchange formats.
Multi-Tasking Machine Tools Market Segmentation
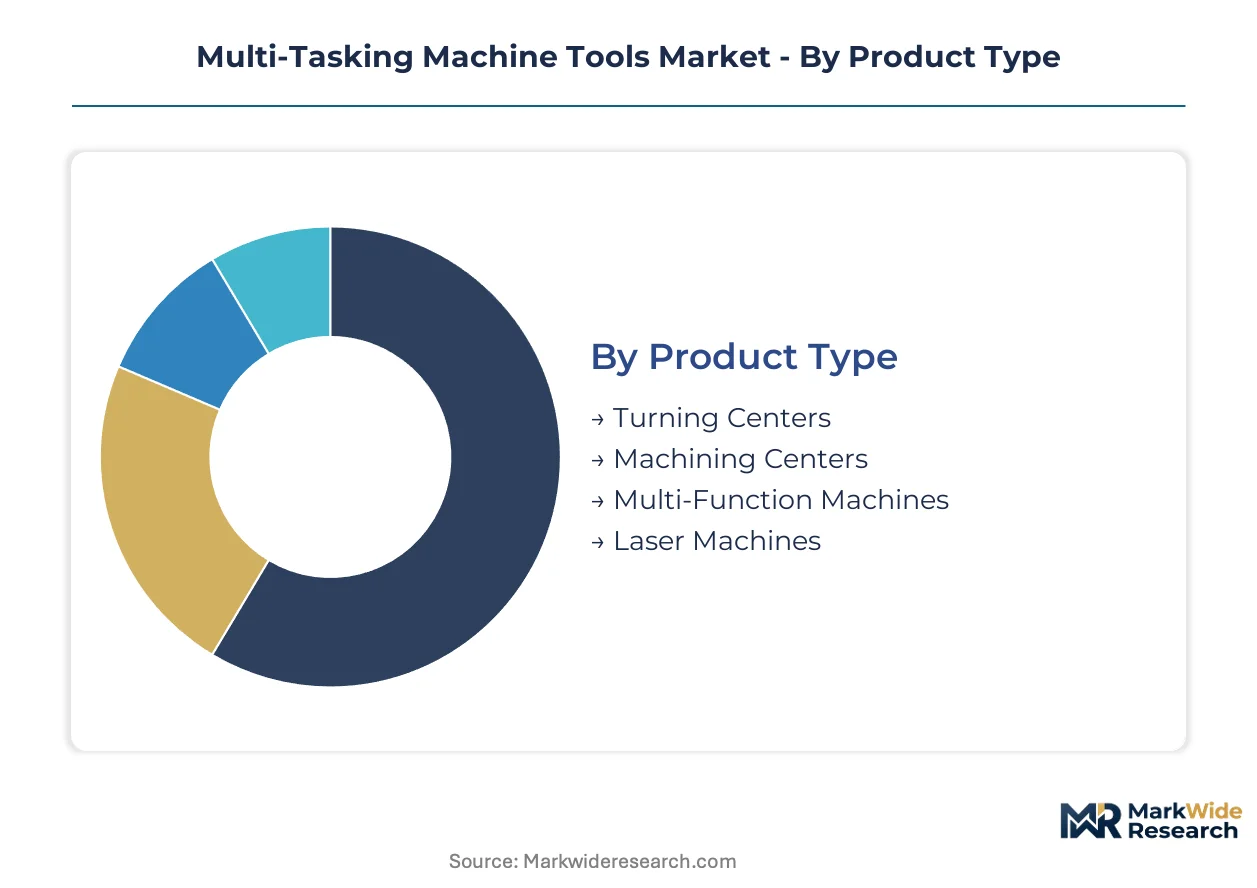
Segmentation in multi-tasking machine tools reveals how capital allocation patterns diverge across precision requirements and production volumes. Buyers in Germany and Japan prioritize certified platforms for aerospace and medical workflows, while emerging manufacturing clusters in India seek import substitutes for automotive battery tray machining.
Product Type:
Turning Centers dominate domestic absorption in precision engineering clusters, while Machining Centers and Laser Machines anchor export-led supply from German and Japanese builders.
- Turning Centers:Integrate milling and drilling spindles on a single horizontal or vertical turret platform, achieving positioning accuracies below five micrometers on linear axes. Demand concentrates in Stuttgart and Solothurn medical device subcontractors, driven by FDA and EU MDR surface-finish validation requirements that reward single-setup processing.
- Machining Centers:Five-axis configurations with rotary tables and integrated turning spindles handle prismatic aerospace structural components. Wichita and Toulouse tier-one suppliers adopt twin-spindle variants to eliminate inter-process queuing for titanium airframe parts.
- Multi-Function Machines:Compact footprints combine turning, milling, and grinding for job-shop flexibility in mid-volume environments.
- Laser Machines:Directed energy deposition heads mounted on five-axis platforms enable Inconel turbine blade repair without fixture requalification.
Turning Centers command the established base. The steepest expansion runs through Laser Machines.
End User:
Cost tier differentiation separates aerospace and medical buyers seeking validated documentation from automotive and electronics purchasers prioritizing throughput economics.
- Aerospace:Boeing and Airbus supply chains demand traceable ISO 230 geometric verification and CE-marked enclosures for titanium structural machining. Wichita and Hamburg MRO facilities drive hybrid system adoption for landing gear component restoration.
- Medical Devices:Tuttlingen and Solothurn subcontractors face REACH coolant reformulation costs and ECHA surface-residue testing protocols. Small batch sizes and cobalt-chrome implant specifications reward twin-spindle, twin-turret flexibility.
- Automotive:Continental and Bosch procurement teams compress specification cycles to nine months, demanding standardized HMI interfaces across mixed-vendor fleets in Stuttgart corridors.
- Electronics:Semiconductor equipment demand surges periodically constrain ceramic hybrid spindle bearing allocation from Japanese suppliers, extending machine delivery timelines.
Aerospace anchors premium platform revenue. Medical Devices capture the highest margin pools per installation.
Technology:
Volume concentration favors mature CNC architectures, while customer type splits between digital-native METI subsidy recipients in Japan and legacy DNC integration projects elsewhere.
- CNC:Control architecture unification around standardized HMI interfaces responds to buyer consolidation at tier-one automotive suppliers. German and Japanese technical institutes concentrate CAM software proficiency for simultaneous five-axis toolpath generation.
- Hybrid Systems:Directed energy deposition integrated with five-axis milling decomposes capital allocation patterns in Singapore and Hamburg MRO facilities. These platforms convert fixed repair infrastructure into flexible, part-agnostic cells.
- Additive Manufacturing:Standalone deposition systems complement subtractive platforms in prototyping workflows.
- Automation:Real-time tool-wear monitoring and predictive maintenance algorithms accelerate under Japan METI smart factory subsidies.
CNC retains the dominant installed footprint. Hybrid Systems are climbing the fastest as repair-service revenue models mature.
Application:
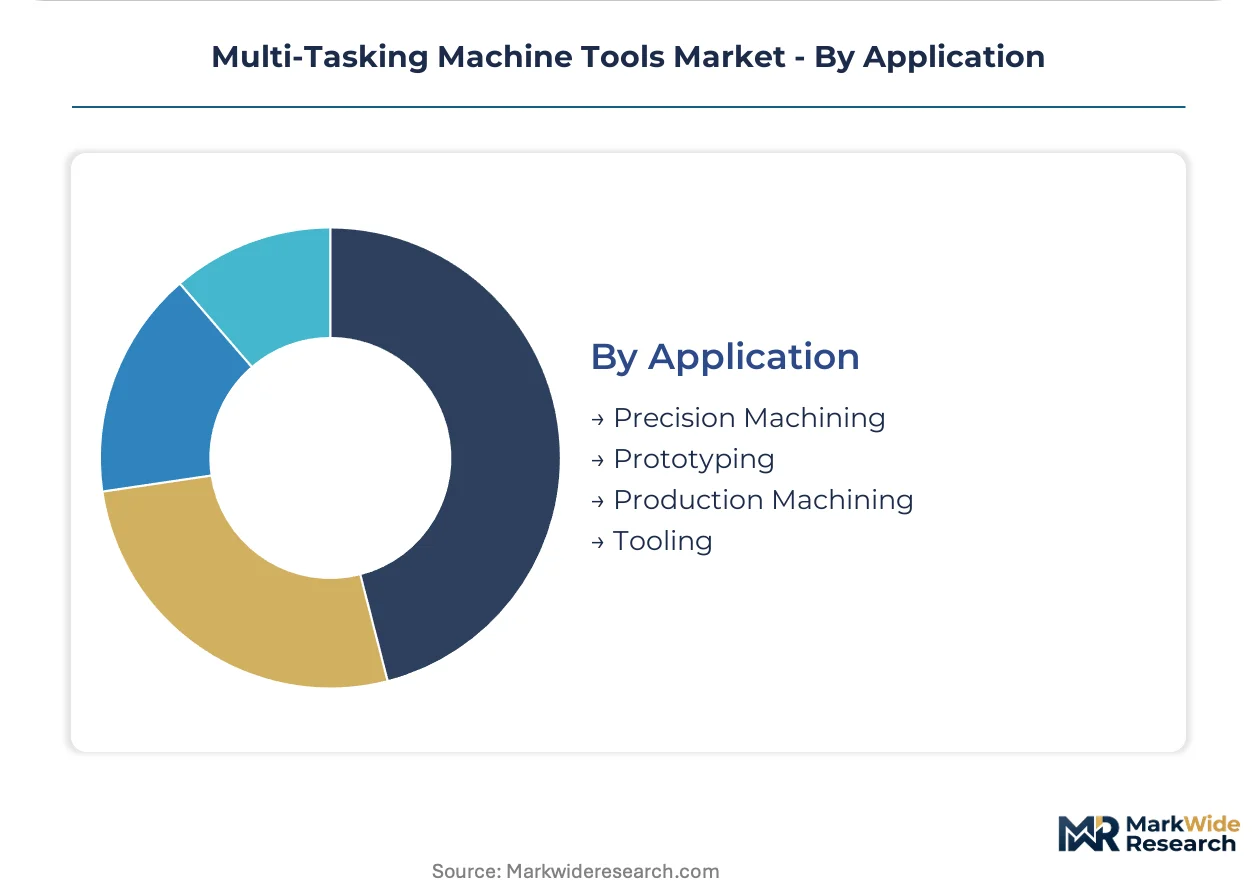
Margin structure separates precision machining validation protocols from high-volume production machining economics.
- Precision Machining:Surface-finish requirements below Ra 0.2 micrometers on cobalt-chrome medical implants constrain addressable applications due to thermal drift during simultaneous five-axis interpolation. FDA and EU MDR traceability mandates enforce documented consistency.
- Production Machining:Large-format aluminum extrusions for electric vehicle battery enclosures require simultaneous five-axis contouring and high-torque turning, a specification gap unaddressed by conventional machining centers.
- Prototyping:Rapid fixture reconfiguration rewards multi-function machine flexibility in low-volume medical device development.
- Tooling:Mold and die production leverages five-axis contouring for complex cavity geometries.
Precision Machining secures the premium pricing tier. Production Machining is gaining share fastest through automotive electrification capex.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration in aerospace and medical device manufacturing drives geographic demand patterns. Precision engineering clusters in Germany and Japan anchor supplier ecosystems, while emerging markets seek import substitution for automotive electrification.
United States
Wichita aerospace suppliers and Boston medical device subcontractors demand twin-spindle configurations for titanium structural components. OSHA machine-guarding standards enforce interlocked enclosure redesigns for domestic installations. Boeing tier-one suppliers in Kansas consolidate production steps to eliminate inter-process queuing.
Germany
Stuttgart automotive corridors and Solothurn medical device clusters prioritize validated platforms with documented surface-finish consistency. REACH substance restrictions force coolant reformulation for titanium machining operations. Tuttlingen subcontractors face ECHA surface-residue testing protocols for cobalt-chrome implants.
Japan
Domestic manufacturers accelerate digital-native platform adoption through METI smart factory subsidies. JIS standards and PMDA traceability requirements shape validation protocols for medical-oriented builders. Nagoya precision engineering clusters concentrate five-axis multi-tasking portfolios.
India
Bengaluru and Pune aerospace clusters lack domestic multi-tasking capacity, creating import substitution potential. BIS certification requirements and PLI scheme incentives attract builders establishing local spindle service infrastructure. Automotive battery tray machining for electric vehicles drives specification gaps unaddressed by conventional centers.
Singapore
MRO facilities adopt hybrid systems combining directed energy deposition with five-axis milling for aerospace landing gear restoration. The country's national aerospace regulator enforces stringent component traceability standards. Seletar aerospace park converts fixed repair infrastructure into flexible, part-agnostic cells.
Multi-Tasking Machine Tools Market Competitive Environment
Player mix skews toward integrated spindle and control architecture specialists with deep certification depth. Three to five vertically integrated builders dominate high-mix, low-volume aerospace workflows, while mid-volume specialists compete on job-shop flexibility. Strategic archetypes include certification-heavy precision platforms, hybrid additive-subtractive systems, and automation-integrated digital-native lines. Competitive moves concentrate on geographic expansion into underpenetrated precision engineering clusters and portfolio diversification toward battery tray machining specifications.
Within the integrated architecture tier, DMG MORI and Yamazaki Mazak Corporation occupy positions as anchors of German and Japanese precision manufacturing respectively. Nakamura-Tome exemplifies the twin-spindle, twin-turret specialization archetype that compresses cycle times for medical device applications. These three entities represent distinct competitive vectors: control unification, five-axis portfolio breadth, and multi-spindle flexibility.
| Leading Market Players |
|---|
| DN Solutions |
| Nakamura-Tome |
| DMG MORI |
| EMAG |
| Tsongami Corporation |
| Yamazaki Mazak Corporation |
| Haas Automation |
| Doosan Corporation |
| Okuma Corporation |
| Others |
Value Chain & Pricing Dynamics
ISO 230 machine-tool qualification cycles gate both supplier entry and price tier separation simultaneously, compressing margin structures for uncertified builders while rewarding vertically integrated incumbents with documented geometric verification protocols. CE marking enforcement and FDA device-quality mandates impose parallel compliance costs that stratify pricing across medical and aerospace buyer segments.
Pricing Analysis
Cost-plus contracts with steel and rare-earth indexation dominate long-term equipment supply agreements between German and Japanese builders and tier-one automotive purchasers. Pricing stratifies across ISO 230-certified premium platforms, CE-marked standard configurations, and economy-tier machines lacking full geometric verification documentation. Price erosion runs through the standard tier as mid-volume builders compete on nine-month specification cycles demanded by Continental and Bosch procurement teams. Medical device subcontractors in Tuttlingen and Solothurn exhibit the lowest price sensitivity due to FDA and EU MDR traceability mandates that prioritize validated surface-finish consistency over capital expenditure minimization.
Supply Chain Analysis
Machine delivery lead times extending sixteen to twenty-four months reflect inventory constraints at Japanese and German precision bearing suppliers rather than final assembly capacity limitations. Ceramic hybrid spindle bearings from NSK, NTN, and Schaeffler draw from semiconductor equipment demand surges that periodically constrain allocation to machine tool builders. Single-source vulnerability concentrates in ultra-precision linear motion guides and direct-drive torque motors sourced predominantly from Japan and Germany. Distribution runs through manufacturer-direct sales engineers for aerospace and medical accounts, with regional distributors handling job-shop and automotive tier-two procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-tasking machine tools are entering a cyclical recovery phase as aerospace production rates normalize and automotive electrification capex accelerates battery tray machining demand. Capital equipment order backlogs at DMG MORI and Yamazaki Mazak signal inventory restocking across precision engineering clusters.
For Market Incumbents: Secure spindle service infrastructure in Bengaluru and Pune before import substitution policies harden, while deepening backward integration into ceramic bearing supply through long-term offtake agreements with Japanese suppliers. Certification depth against ISO 230-2 geometric verification protocols represents the priority defensive lever as mid-volume builders face three-to-four-week factory acceptance testing extensions that compress revenue recognition cycles. For New Entrants and Emerging Players: EU MDR fast-track certification for medical device subcontractors offers the most penetrable entry vector, given Tuttlingen and Solothurn demand for twin-spindle, twin-turret configurations with documented surface-finish consistency. Target Indian automotive battery tray machining specifications unaddressed by conventional five-axis machining centers, leveraging PLI scheme incentives and BIS certification pathways to establish local assembly presence before incumbent spindle service networks mature. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German mid-cap specialists lacking hybrid additive-subtractive portfolios and trapped in legacy DNC architectures. Five-to-ten-year viability hinges on control architecture unification and predictive maintenance algorithm development under Japan METI smart factory subsidy eligibility. The signal to watch is order intake velocity from Wichita and Toulouse aerospace tier-one suppliers adopting twin-spindle configurations for titanium structural consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 230-2 Certification Investment | CE marking and FDA validation protocols gate European and US medical device market access for builders. |
| Hybrid System Portfolio Expansion | Directed energy deposition integration captures MRO revenue streams at Singapore and Hamburg aerospace facilities. |
| Indian Spindle Service Infrastructure | BIS certification and PLI incentives attract builders establishing local presence for battery tray machining demand. |
| Control Architecture Unification | Standardized HMI interfaces respond to Bosch and Continental procurement consolidation across Stuttgart corridors. |
| Predictive Maintenance Algorithm Development | METI smart factory subsidies accelerate digital-native platform adoption among Nagoya precision engineering clusters. |
Study Parameters
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and CAM software specialists and secondary validation through SEC machine tool builder filings, customs import records, and ISO certification registries anchors the qualitative findings. Bottom-up equipment shipment data from German and Japanese trade associations triangulates against top-down aerospace and medical device capital expenditure disclosures. Primary fieldwork concentrated on precision engineering clusters in Stuttgart, Solothurn, Nagoya, and Bengaluru to capture regional specification divergence.
Sensitivity analysis across ceramic bearing allocation scenarios, METI subsidy eligibility windows, and EU MDR traceability mandate compliance timelines frames the projection horizon. Segmentation modeling incorporated product type, end-use vertical, technology architecture, and application precision requirements alongside regional regulatory cluster differentiation. CAGRs derive from equipment replacement cycle analysis and capacity utilization trajectories at Wichita and Toulouse tier-one suppliers, with hybrid system adoption curves calibrated against Singapore and Hamburg MRO facility investment patterns.
Decision-makers should treat outputs as directional under assumptions of sustained aerospace production recovery and automotive electrification capex continuity; material deviation in semiconductor equipment demand cycles or REACH coolant reformulation costs would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hand and Power Tools Market
Tools
Stand Tile Saw Market
Tools
Horizontal Milling Machine Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Industrial Cleaning Equipment Market
Tools
Cold and Hot Tool Steel Market
Tools
Workholding Tools Market
Tools
Collated Screws Market
Tools
Floor Polishing Machine Market
Tools
Drill Presses Market
Tools
Pneumatic Bolting Tools Market
Tools
Digital Levels Market
Tools
Sander Market
Tools
Post Drivers Market
Tools
Welding Guns Market
Tools
Leather Embossing Machine Market