
 Modular Refinery Market | 2026-2036
Modular Refinery Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Refinery Market Foresight
Middle Eastern engineering consortiums is rebalancing capacity deployment toward Africa and Southeast Asia as traditional large-refinery orders slow. Honeywell UOP leverages its catalytic reforming technology leadership to anchor premium licensing contracts across emerging markets. Samsung Engineering competes on integrated EPC delivery, while Axens specializes in process design packages that reduce commissioning timelines for remote installations.
A modular refinery is a prefabricated crude processing system built in standardized sections for transport and rapid assembly, typically handling between 1,000 and 30,000 barrels per day through units that perform atmospheric distillation, hydrotreating, and reforming. These systems serve regions lacking pipeline networks or capital for conventional stick-built facilities, converting stranded or marginal crude into transport fuels and naphtha. Skid-mounted configurations dominate current order books due to faster site mobilization, though floating units command margin pools in offshore West Africa where port infrastructure remains underdeveloped. Distillation technology retains the largest installed base, while hydrocracking segments attract investment from operators seeking diesel yield optimization.
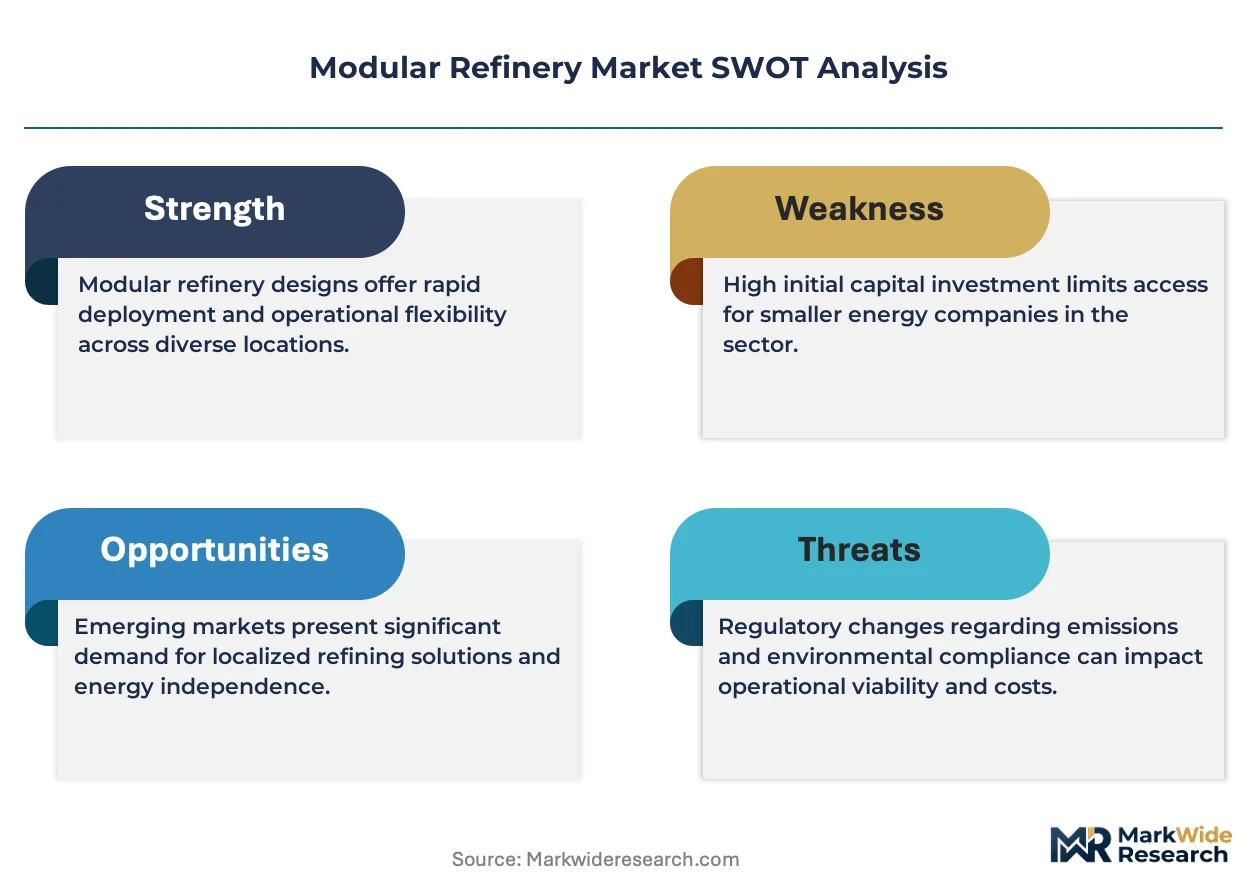
The US EPA enforces Tier 3 gasoline sulfur standards that shape product specifications for any modular unit exporting to North American markets, while Nigeria's Department of Petroleum Resources mandates local content thresholds that alter procurement patterns for equipment and labor. IMO marine fuel regulations and evolving EU Green Deal carbon-border mechanisms are tightening emission benchmarks that modular designs must satisfy to secure offtake agreements. Stakeholders should monitor how carbon intensity accounting rules affect financing terms for smaller-scale refinery investments.
Market Dynamics
Stranded crude fields across West Africa are forcing operators toward localized processing infrastructure that bypasses pipeline-dependent distribution networks entirely. This geographic isolation is compressing commissioning timelines and reshaping supplier relationships around rapid-deployment engineering capabilities.
Growth Catalysts
- IMO 2020 Sulfur Caps:Marine fuel regulations mandate sub-0.5% sulfur content, pushing smaller producers toward hydrotreating-equipped modular units that can upgrade high-sulfur residual streams without billion-dollar conventional refinery investments.
- Offshore West Africa:Nigerian and Angolan marginal field operators require floating processing capacity where port infrastructure remains undeveloped, creating captive demand for barge-mounted distillation and reforming systems.
- Skid-Mounted Configurations:Standardized prefabrication techniques cut site mobilization from years to months, enabling independent producers to capture price arbitrage before pipeline construction becomes economically viable.
Market Restraints
- Specialized Alloy Supply:Corrosion-resistant metallurgy for sour crude service concentrates among a limited supplier base, exposing project timelines to nickel and molybdenum price volatility.
- Feedstock Specification Rigidity:Modular units lack the crude flexibility of large complex refineries, locking operators into stranded medium-gravity crudes that face demand erosion from light tight oil displacement.
- Local Content Mandates:Nigeria's Department of Petroleum Resources thresholds force equipment sourcing patterns that extend procurement cycles and inflate fabrication costs for international engineering firms.
Strategic Opportunities
- Remote Indonesian Archipelago Fields:Island-based producers lack inter-island pipeline connectivity, creating white space for barge-mounted units serving Java Sea and Makassar Strait developments.
- EU Green Deal Carbon Border Adjustments:Emerging carbon intensity accounting rules favor smaller-scale refineries with lower embedded construction emissions, potentially unlocking preferential offtake terms for European fuel buyers.
- Waste Plastic Pyrolysis Integration:Modular chemical recycling units converging with conventional refinery process trains enable circular feedstock processing for polymer producers seeking Scope 3 reductions.
Industry Challenges
- Commissioning Engineer Scarcity:Remote site startups require specialized hydrocracker and reformer specialists whose availability constrains concurrent project execution across multiple African deployments.
- Legacy Terminal Integration:Brownfield product offtake agreements with existing storage and vessel loading infrastructure demand complex interface engineering that extends mechanical completion schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Refinery Market |
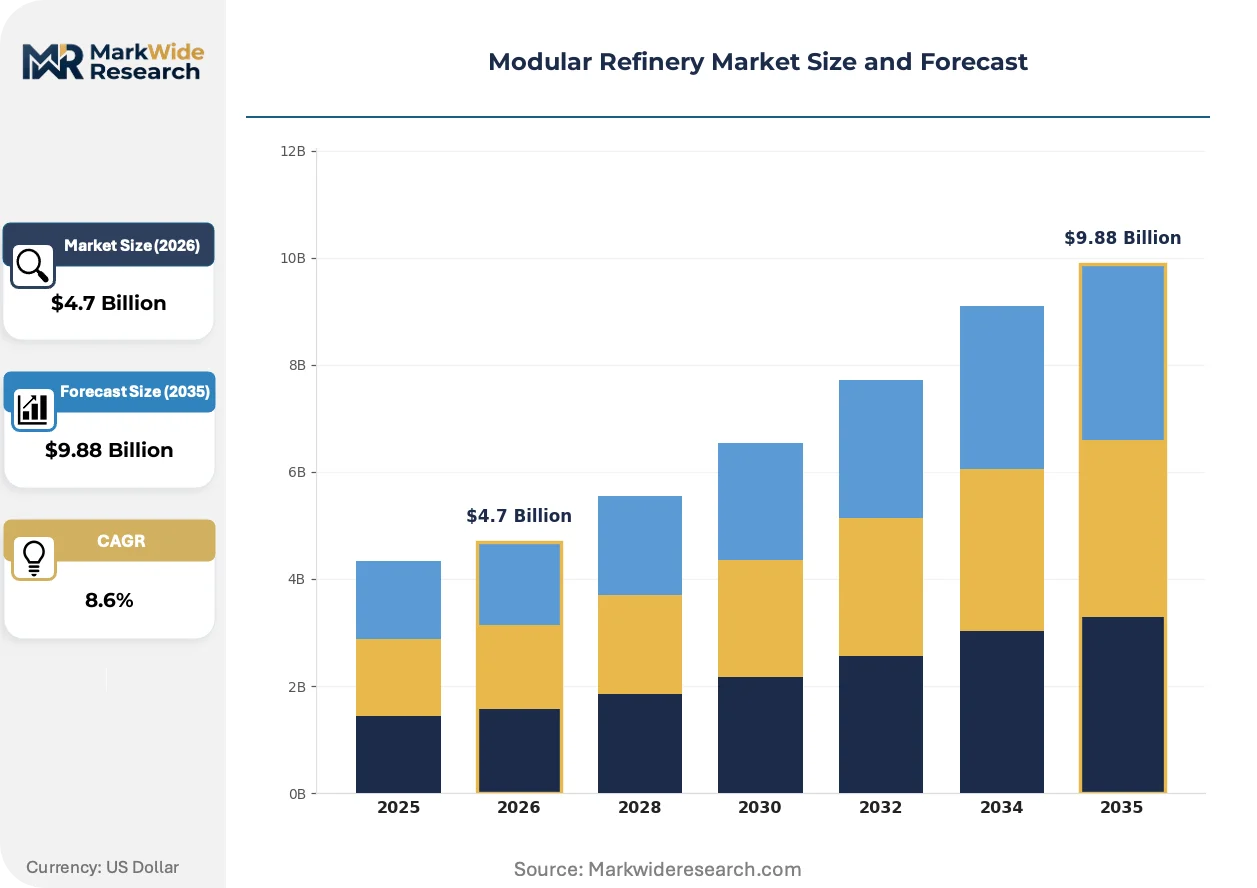
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating, Skid-mounted, Containerized, Mobile Technology: Hydrocracking, Catalytic Reforming, Distillation, Thermal Cracking Service Type: Installation, Training, Maintenance, Consulting End User: Oil & Gas Producers, Industrial Consumers, Power Generation, Governments |
| Companies Covered | Peiyang Chemical Equipment Co. Ltd., Apache Refinery Services, Honeywell UOP, Plant Process Group, LLC, Refinery Equipment of Texas, LLC, Samsung Engineering, Costello, Propak Systems Ltd., Axens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Refinery Market Shifts & Advancements
Process intensification and digital twin deployment are compressing the gap between modular design standardization and field-specific customization requirements. These advances are enabling supplier ecosystems to serve smaller batch orders profitably while maintaining configuration flexibility.
Advanced process control systems with embedded machine learning algorithms are rewriting how remote modular units optimize yield patterns without on-site chemical engineering presence. Nigerian independent operators are piloting these platforms across Niger Delta installations, enabling real-time cutpoint adjustments that maximize diesel output from variable crude assays. This capability is compressing the operational expertise gap that previously favored large integrated refinery operators.
The US EPA maintains Tier 3 gasoline sulfur standards at 10 parts per million maximum, forcing any modular unit targeting North American export markets to incorporate deep hydrotreating capability in base configurations. This specification is elevating capital intensity for suppliers seeking US offtake agreements. West African project developers are responding by bifurcating product slates toward European diesel and Asian naphtha markets with less stringent sulfur protocols.
Integrated service contracts covering catalyst supply, unit operation, and product offtake are displacing traditional equipment-only procurement across emerging market independents. These arrangements transfer operational risk to technology licensors while guaranteeing feedstock access for capital-constrained field operators. The model is most visible in Nigerian marginal field developments where equity partners lack downstream expertise.
Modular Refinery Market Segmentation
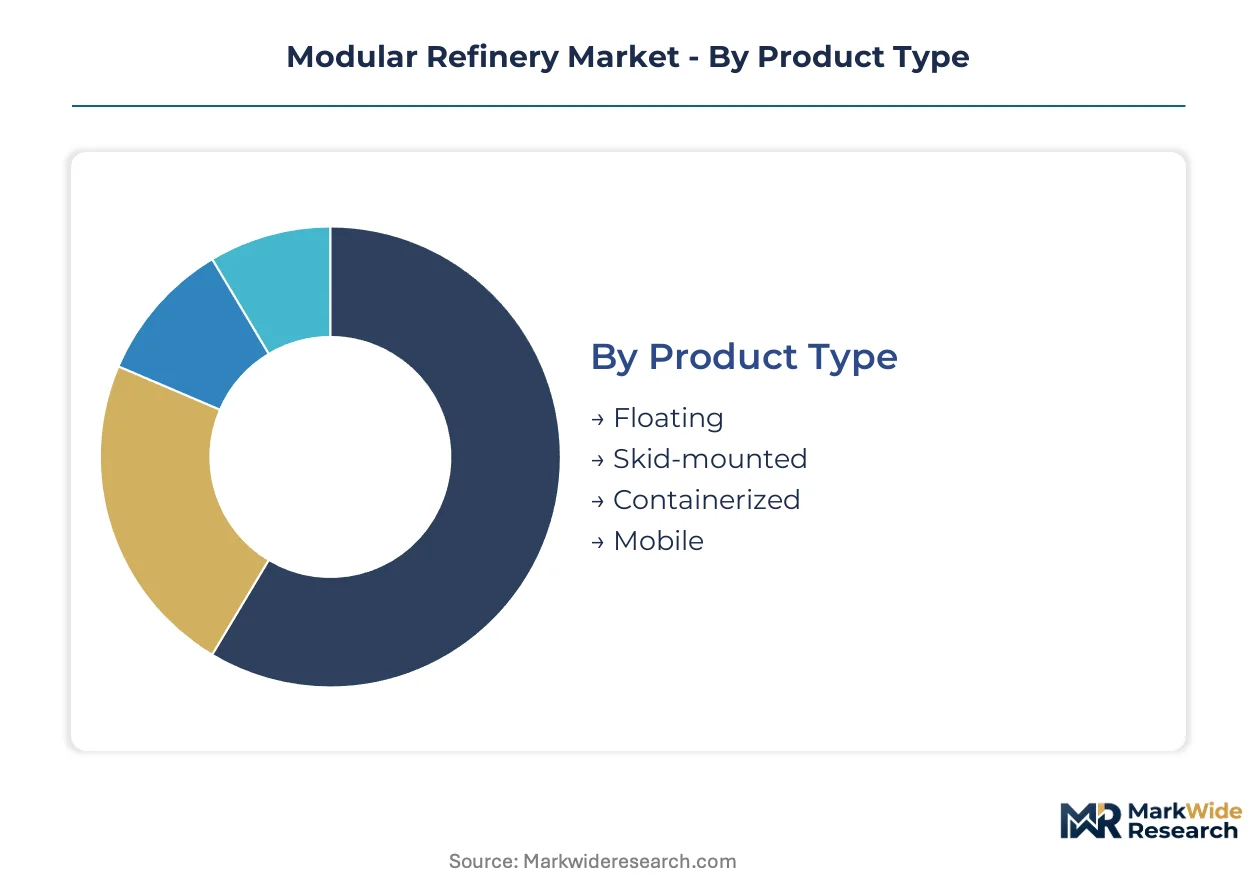
Modular refinery procurement patterns diverge sharply across configuration types and service models, with certification requirements from the US EPA, Nigeria's Department of Petroleum Resources, and the IMO sulfur protocols reshaping supplier priorities. Understanding these segment boundaries reveals where capital concentrates and which technology packages capture premium pricing.
Product Type:
US EPA Tier 3 gasoline sulfur standards and Nigeria's local content mandates impose divergent fabrication burdens across configuration categories, with offshore installations facing additional ABS and DNV marine classification requirements.
- Floating:Barge-mounted processing trains integrate atmospheric distillation, hydrotreating, and reforming units on stabilized hulls designed for West African offshore fields. Nigerian and Angolan marginal field operators dominate current order books, driven by undeveloped port infrastructure that prevents land-based alternatives.
- Skid-mounted:Standardized steel frames accommodate prefabricated process modules that truck or rail to remote sites, cutting mobilization timelines from years to months. Independent producers across Indonesia's Java Sea developments favor this format for capturing price arbitrage before pipeline economics materialize.
- Containerized:ISO-dimensioned process units fit standard shipping containers for rapid global redeployment. These configurations serve temporary processing needs and pilot-scale demonstrations where permanent infrastructure investment remains unviable.
- Mobile:Trailer-transportable mini-refineries target emergency fuel supply and military applications requiring swift relocation. Defense procurement programs and humanitarian response agencies constitute the primary demand pool.
Leading the category by volume: Skid-mounted. Growing fastest: Floating.
Technology:
Process selection determines crude flexibility, product slate, and compliance headroom against evolving marine fuel and automotive emission specifications across target export markets.
- Hydrocracking:High-pressure hydrogen addition cracks heavy vacuum gas oil into diesel and naphtha with superior cetane and low aromatic content. Operators seeking IMO 2020-compliant marine diesel and EU diesel pool access are concentrating procurement here, despite elevated capital intensity from specialized alloy reactor vessels.
- Catalytic Reforming:Platinum-rhenium catalyst systems convert naphtha range material into high-octane reformate and aromatics feedstock. Honeywell UOP licensing dominance anchors premium contract structures across emerging market independents lacking in-house process engineering.
- Distillation:Atmospheric and vacuum fractionation separates crude into straight-run products without chemical transformation. This mature technology retains the largest installed base due to lower capital thresholds and simpler operational requirements.
- Thermal Cracking:Visbreaking and delayed coking units thermally decompose residual fractions into lighter transport fuels. These processes serve heavy sour crude producers facing disposal constraints for vacuum residuum.
Dominating installed capacity: Distillation. Expanding most quickly: Hydrocracking.
Service Type:
Contract scope evolution transfers operational risk from capital-constrained field operators to technology licensors, with integrated service packages displacing equipment-only procurement across Nigerian marginal field developments.
- Installation:Heavy lift coordination, mechanical completion, and pre-commissioning verification for modular process trains. Remote site logistics and specialized welding procedures for sour service metallurgy concentrate execution risk here.
- Training:Operator certification programs covering process control, catalyst handling, and emergency response protocols. Nigerian local content mandates require demonstrated knowledge transfer to indigenous personnel.
- Maintenance:Turnaround planning, catalyst changeout services, and corrosion monitoring for continuous operations. Long-term service agreements lock in recurring revenue streams for technology providers.
- Consulting:Feasibility studies, feedstock assay interpretation, and product slate optimization for greenfield project development. Early-stage engineering consults shape downstream equipment specifications and licensing decisions.
Highest contract value concentration: Installation. Steepest expansion trajectory: Maintenance.
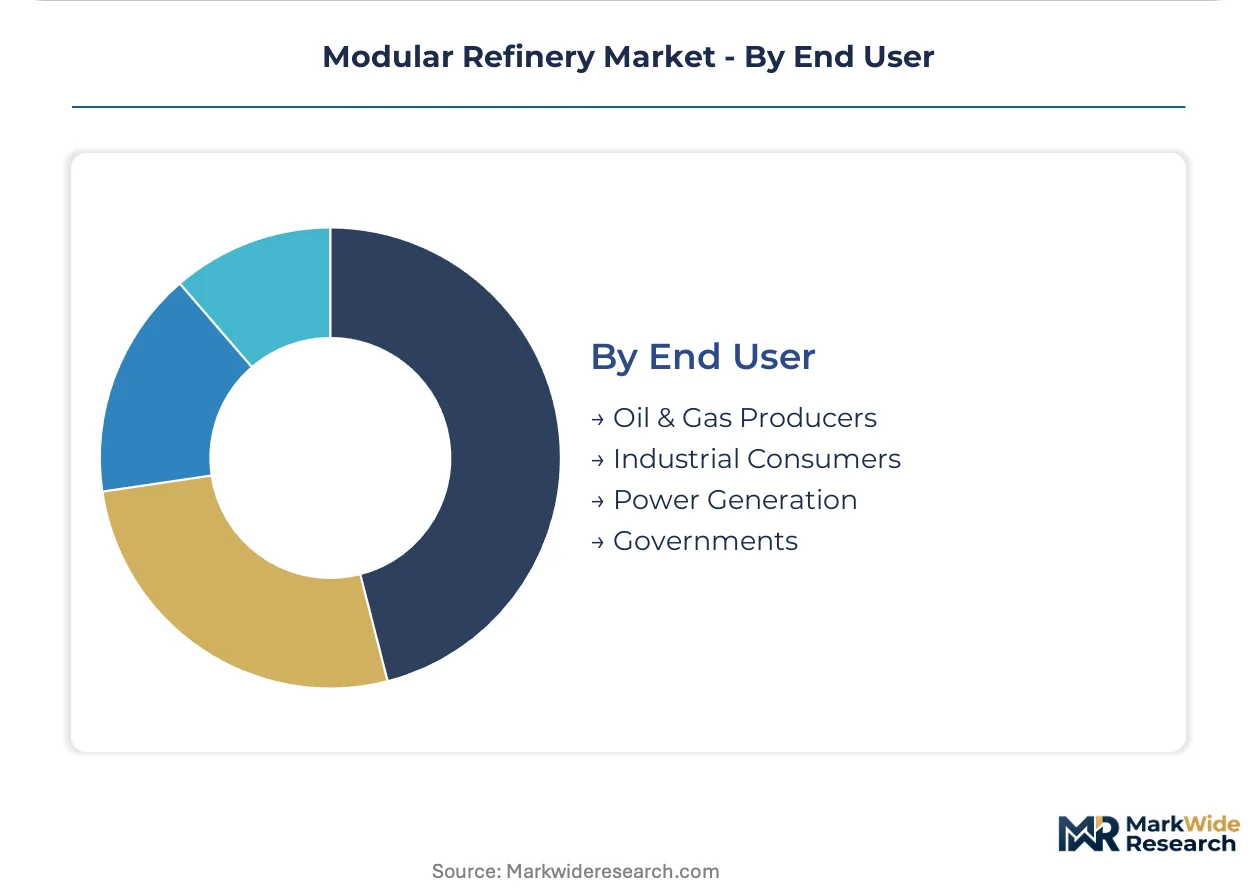
End User:
Customer archetypes exhibit divergent risk tolerances, with equity-backed independents favoring operational outsourcing while state entities prioritize local content compliance and employment generation.
- Oil & Gas Producers:Upstream operators with stranded or marginal crude fields requiring localized processing to bypass pipeline-dependent distribution networks. Nigerian independents and West African national oil companies anchor this segment.
- Industrial Consumers:Mining, cement, and manufacturing operations seeking captive fuel supply security in regions with unreliable commercial product availability. Remote Indonesian nickel processing facilities exemplify this demand profile.
- Power Generation:Diesel and fuel oil consumers for off-grid and backup generation infrastructure. Island nations and remote industrial parks drive procurement of dedicated modular supply.
- Governments:Strategic petroleum reserve programs, military fuel security initiatives, and rural electrification schemes. Defense procurement channels and development finance institutions shape contracting modalities.
Commanding largest procurement volume: Oil & Gas Producers. Gaining share fastest: Industrial Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stranded crude deposits in Nigeria's Niger Delta anchor procurement demand for floating modular units. West African marginal field operators bypass pipeline networks entirely through barge-mounted processing capacity.
Nigeria
Nigerian independents dominate floating modular procurement for offshore marginal fields where port infrastructure remains undeveloped. The Department of Petroleum Resources enforces local content thresholds that reshape equipment sourcing patterns and extend fabrication timelines. Lagos-based engineering clusters coordinate heavy-lift mobilization for Niger Delta deployments.
Angola
Angolan national oil companies accelerate procurement of barge-mounted distillation systems for presalt and marginal field developments. The country's petroleum regulator mandates environmental compliance protocols that elevate metallurgical specifications for sour crude service. Cabinda province installations concentrate demand for rapid-deployment hydrocracking packages.
Indonesia
Island-based producers across the Java Sea and Makassar Strait favor skid-mounted configurations to capture price arbitrage before pipeline economics materialize. The country's energy ministry prioritizes downstream self-sufficiency programs that subsidize modular refinery development. East Kalimantan industrial zones host fabrication yards serving remote nickel processing facilities.
United States
Permian Basin operators evaluate containerized pilot units for stranded lease condensate processing. The EPA enforces Tier 3 gasoline sulfur standards at 10 parts per million maximum for any unit targeting domestic fuel markets. Houston-Gulf Coast engineering clusters dominate technology licensing and catalyst supply relationships.
Saudi Arabia
Saudi Aramco examines modular solutions for remote shale and tight gas liquids processing in the Jafurah basin. The Ministry of Energy's downstream localization initiatives incentivize domestic fabrication partnerships with international licensors. Jubail industrial city hosts specialized alloy supply chains for high-pressure reactor vessels.
Modular Refinery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated service contracts and remote deployment specialization. The vendor base separates between technology licensors anchoring premium positions and fabrication specialists competing on mobilization speed. Three archetypes dominate: integrated EPC providers, process design specialists, and regional equipment fabricators. Capacity expansion and strategic technology licensing constitute the dominant competitive moves across all tiers.
Among Asia-Pacific engineering conglomerates, Samsung Engineering exemplifies the integrated EPC archetype, while Honeywell UOP anchors the technology licensing tier for catalytic reforming systems. Axens occupies a position within the process design specialist category, anchoring premium contract structures through configuration flexibility. These three entities represent the competitive spectrum from fabrication-heavy delivery to knowledge-intensive licensing models.
| Leading Market Players |
|---|
| Peiyang Chemical Equipment Co. Ltd. |
| Apache Refinery Services |
| Honeywell UOP |
| Plant Process Group, LLC |
| Refinery Equipment of Texas, LLC |
| Samsung Engineering |
| Costello |
| Propak Systems Ltd. |
| Axens |
| Others |
Supply & Pricing Matrix
Nickel and molybdenum alloy costs cascade through reactor vessel fabrication into three distinct pricing tiers that separate integrated service contracts from bare-equipment procurement across Nigerian and Angolan project developments.
Pricing Analysis
Warranty and catalyst supply bundling separates premium licensing arrangements from unbundled equipment-only sales across West African deployments. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and local content compliance thresholds mandated by Nigeria's Department of Petroleum Resources. Pricing pressure stems from Indonesian nickel processor demand for rapid-deployment skid units with compressed commissioning windows. Independent oil and gas producers exhibit highest price sensitivity, while national oil companies prioritize compliance assurance over unit economics.
Supply Chain Analysis
Welding specialist availability in South Korean and Chinese fabrication yards constrains throughput for sour service metallurgy required by West African crudes. Reactor vessel fabrication concentrates in South Korea, China, and Jubail industrial city in Saudi Arabia. Supply chains draw from nickel alloy feedstock, platinum-rhenium catalyst systems, and specialized pressure vessel forgings. Single-source vulnerability in corrosion-resistant alloy supply exposes timelines to commodity price swings. Distribution runs through heavy-lift marine logistics coordinated from Lagos and Singapore engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process intensification technologies are displacing conventional stick-built refinery economics, with digital twin deployment and machine learning process control rewriting operational requirements for remote installations.
For Market Incumbents: Anchor licensing dominance through catalytic reforming technology leadership against emerging integrated EPC competitors. Deepen backward integration into specialized alloy supply chains to secure reactor vessel delivery schedules against nickel price volatility. Prioritize certification investment for IMO 2020 marine fuel compliance to defend premium positioning.
For New Entrants and Emerging Players: Begin with remote Indonesian archipelago fields where pipeline infrastructure gaps create captive demand for barge-mounted units. Target industrial consumers in East Kalimantan nickel processing zones with captive fuel supply contracts. Pursue integrated service models transferring operational risk from capital-constrained field operators.
For Investors and Strategic Acquirers: Nigerian local content mandate enforcement acceleration is the leading indicator that fabrication partnership structures will consolidate around compliant domestic engineering clusters. Long-term viability favors technology licensors with recurring catalyst revenue streams over fabrication-heavy EPC providers. Monitor Department of Petroleum Resources procurement pattern shifts as the inflection signal for contract flow concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Expansion | Transfers operational risk to Honeywell UOP and Axens while guaranteeing Nigerian independents feedstock access. |
| Backward Integration into Alloy Supply | Secures nickel and molybdenum reactor vessel capacity against price volatility and single-source exposure. |
| Digital Twin Platform Deployment | Enables real-time yield optimization across Niger Delta installations without on-site chemical engineering presence. |
| Floating Unit Certification Investment | Unlocks ABS and DNV marine classification premiums for barge-mounted West African offshore developments. |
| Remote Indonesian Market Entry | Captures Java Sea and Makassar Strait demand before pipeline economics eliminate modular arbitrage windows. |
Research Methodology
Independent corroboration across technology licensing executives, EPC project directors, and Nigerian procurement officers underwrites the qualitative findings presented in this study. Primary interviews with catalyst supply specialists, marine classification surveyors, and Department of Petroleum Resources compliance officers combined with secondary validation from IMO marine fuel regulation filings, US EPA Tier 3 enforcement data, and Nigerian local content audit reports. Bottom-up project pipeline assessment and top-down capacity deployment tracking triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from unit value evolution across configuration type, process technology, and service model dimensions throughout the forecast period. Segmentation modeling incorporates product type, technology package, contract scope, and end-user archetype. CAGRs derive from deployment timeline aggregation and capacity utilization assumptions. Industry-specific inputs include crude assay variability patterns and marine fuel sulfur specification evolution.
Underlying measurement precision varies by segment; skid-mounted configuration demand carries tighter precision than emerging floating unit categories where order book visibility remains limited. Forecasts reflect assumptions regarding Nigerian marginal field development pace and Indonesian downstream subsidy continuity. Material deviation in nickel alloy pricing or local content enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Libya Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
APAC Oil and Gas Automation Market