
 Asia-Pacific Oil Country Tubular Goods Market | 2026-2036
Asia-Pacific Oil Country Tubular Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oil Country Tubular Goods Market Outlook
Direct procurement channels between steel mills and national oil companies are reshaping traditional distributor networks across the Asia-Pacific OCTG landscape. Nippon Steel Corporation leverages integrated blast furnace-to-pipe production to command premium positioning in Japanese offshore contracts. TPCO Enterprise anchors Chinese supply through captive seamless rolling capacity serving Sinopec and CNOOC drilling programs. Vallourec differentiates via proprietary threading technology for premium connections in sour gas environments.
Oil Country Tubular Goods comprise seamless and welded steel pipes manufactured to API 5CT specifications, with wall thicknesses engineered to withstand formation pressures exceeding 20,000 psi during hydrocarbon extraction. These tubulars function as structural casing strings and production tubing that isolate wellbore zones and convey reservoir fluids to surface facilities. Seamless tubes dominate premium applications where burst resistance and fatigue life prove critical, while welded tubes compete aggressively in standard onshore casing markets across Asia-Pacific basins. Alloy steel grades are gaining traction as operators push into deeper, hotter reservoirs requiring chromium-molybdenum metallurgy.
China's SAMR enforces GB/T 19830 compliance for domestic casing and tubing, while Australia's NOPSEMA mandates well integrity standards that elevate premium connection adoption in offshore permits. Japan's METI coordinates JIS standard alignment with API protocols to preserve export competitiveness for domestic mills. Buyers must weigh localized certification requirements against total cost of ownership when qualifying tubular suppliers across fragmented Asia-Pacific regulatory regimes.
Market Dynamics
Deepwater exploration economics are compressing procurement cycles across Asia-Pacific basins, forcing tubular suppliers to pre-certify premium connections before drilling contracts award. Operators now bundle casing specifications with well integrity guarantees, transferring metallurgical risk from NOCs to mill balance sheets.
Growth Catalysts
- GB/T 19830 alloy tightening:China's SAMR mandates higher chromium-molybdenum content in casing grades, pushing domestic mills toward premium production tiers and displacing standard API grades in Sinopec drilling programs.
- Offshore well integrity mandates:Australia's NOPSEMA requires premium threaded connections in all high-pressure high-temperature permits, locking in specialized tubular demand for Northwest Shelf developments.
- KG-D6 block expansion:India's Reliance-led consortium is drilling deeper subsea wells requiring corrosion-resistant alloy tubing, creating dedicated procurement lanes for sour-service metallurgy.
Market Restraints
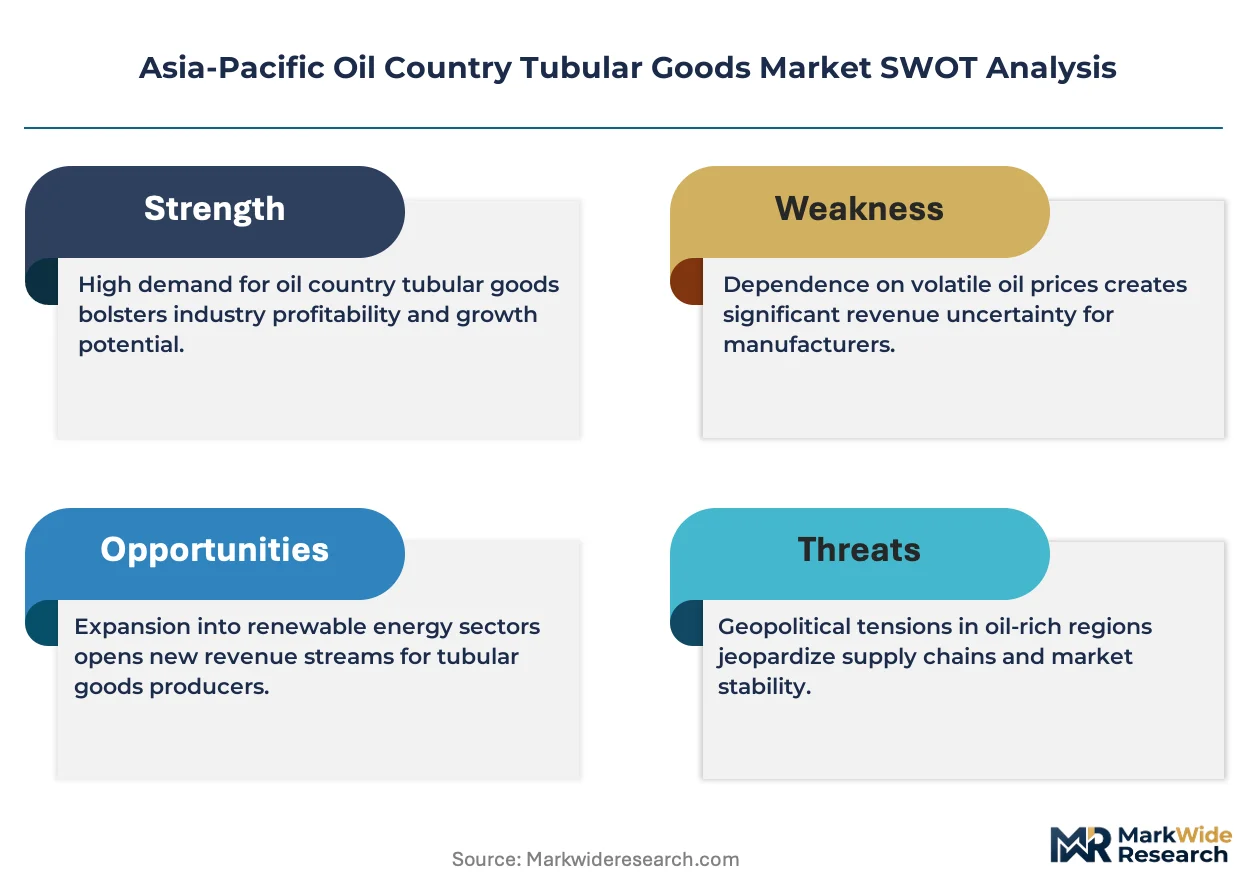
- Scrap-fed electric arc furnace concentration:Chinese OCTG production relies on volatile ferrous scrap inputs, exposing margins to commodity swings that seamless rolling cannot pass through contract pricing.
- Seamless mill geographic clustering:Over 60 percent of Asia-Pacific premium casing capacity sits within 300 kilometers of Tianjin, creating single-point vulnerability to port congestion or regional power rationing.
- API 5CT grade ceiling:Standard specification limits burst ratings for ultra-deep reservoirs exceeding 25,000 psi, forcing operators toward proprietary mill grades with unproven field histories.
Strategic Opportunities
- Indonesia's frontier basins:The country's regulator is relaxing local content rules for deepwater blocks, opening direct mill-to-operator contracting outside traditional distributor networks.
- Digital thread inspection:Ultrasonic phased-array testing converges with blockchain traceability, enabling real-time quality verification that reduces insurance premiums for offshore deployments.
- Japan's METI hydrogen storage alignment:JIS standard revisions for high-pressure gas containment create crossover demand from oilfield tubulars to subsurface hydrogen reservoir applications.
Industry Challenges
- Premium connection field engineering scarcity:Make-and-break technicians for proprietary threaded designs remain concentrated in Houston and Aberdeen, creating mobilization bottlenecks for Australian offshore campaigns.
- Dual certification timeline compression:Mills must simultaneously qualify to GB/T 19830 and API 5CT for Chinese NOC export tenders, extending qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oil Country Tubular Goods Market |
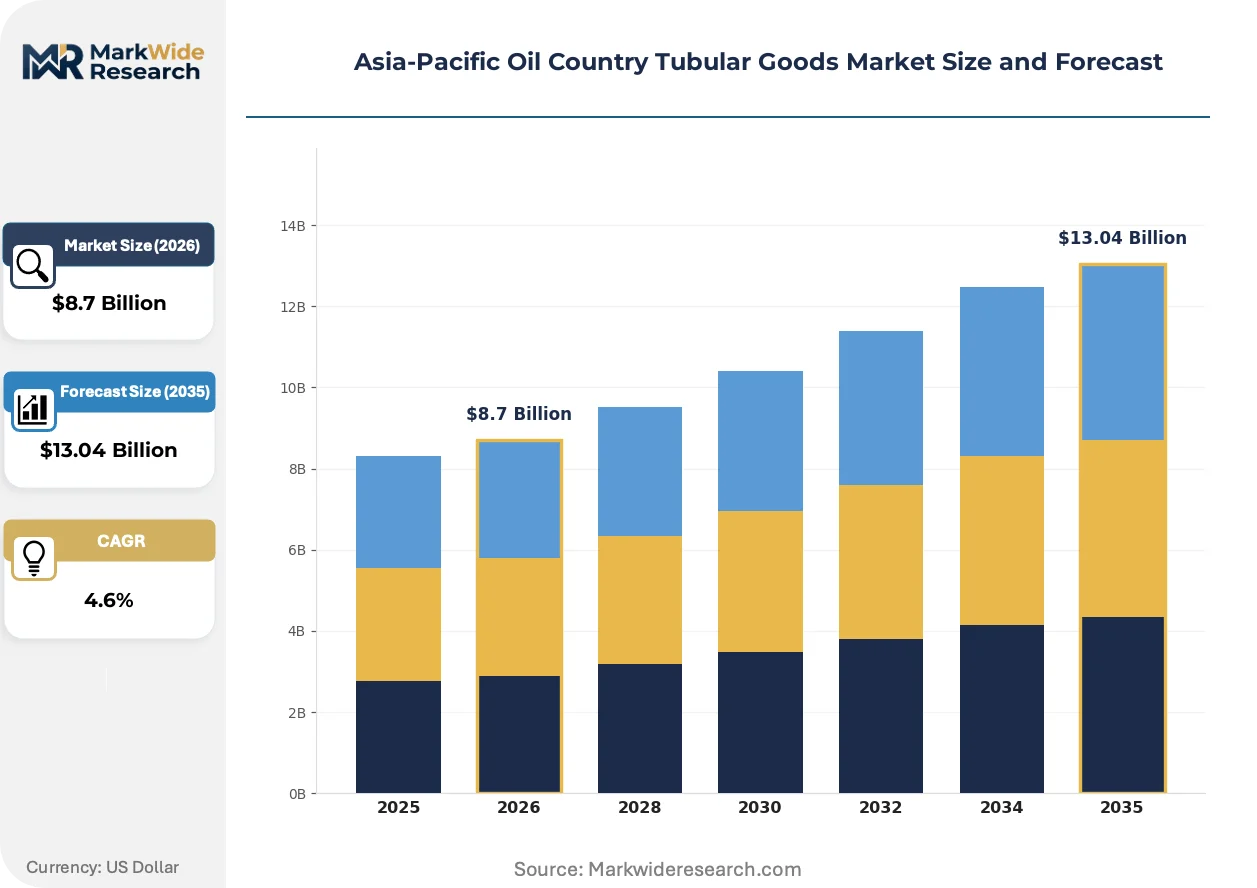
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Tubes, Welded Tubes, Casing Pipes, Tubing Pipes Material: Carbon Steel, Alloy Steel, Stainless Steel, Others End User: Oil Exploration, Gas Extraction, Offshore Drilling, Onshore Drilling Application: Drilling, Construction, Maintenance, Repair |
| Companies Covered | Nippon Steel Corporation, ILJIN Steel, TPCO Enterprise, JFE Steel Corporation, Tenaris, ArcelorMittal, Vallourec, TMK, Jindal Saw, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oil Country Tubular Goods Market Strategic Shifts
Metallurgical differentiation is overtaking scale economies as the primary competitive axis across Asia-Pacific OCTG supply. Threaded connection technology and alloy specification now determine contract awards more than unit pipe pricing.
Chromium-molybdenum alloy grades are migrating from niche sour-gas applications into standard offshore casing specifications. Japanese drilling contractors now specify P110-13Cr minimums for wells previously designed around carbon steel. This migration from commodity metallurgy to corrosion-resistant alloys is compressing the addressable market for welded pipe producers lacking seamless rolling capacity.
Australia's NOPSEMA is tightening well barrier documentation requirements for all offshore drilling permits. Operators must now demonstrate traceable metallurgical provenance for every casing joint from melt to spud. This regulatory pressure is disqualifying traders and spot-market distributors from premium offshore procurement, concentrating supply relationships with integrated mills holding in-house testing laboratories.
Direct mill contracting is displacing traditional stock-and-distribute models for premium casing strings. National oil companies in China and India now negotiate frame agreements covering 18-24 month drilling programs, bypassing regional inventory holders. This channel consolidation is most visible in Australia's Northwest Shelf, where Woodside Energy maintains dedicated supply lines with Japanese seamless producers rather than maintaining domestic tubular inventories.
Asia-Pacific Oil Country Tubular Goods Market Segmentation
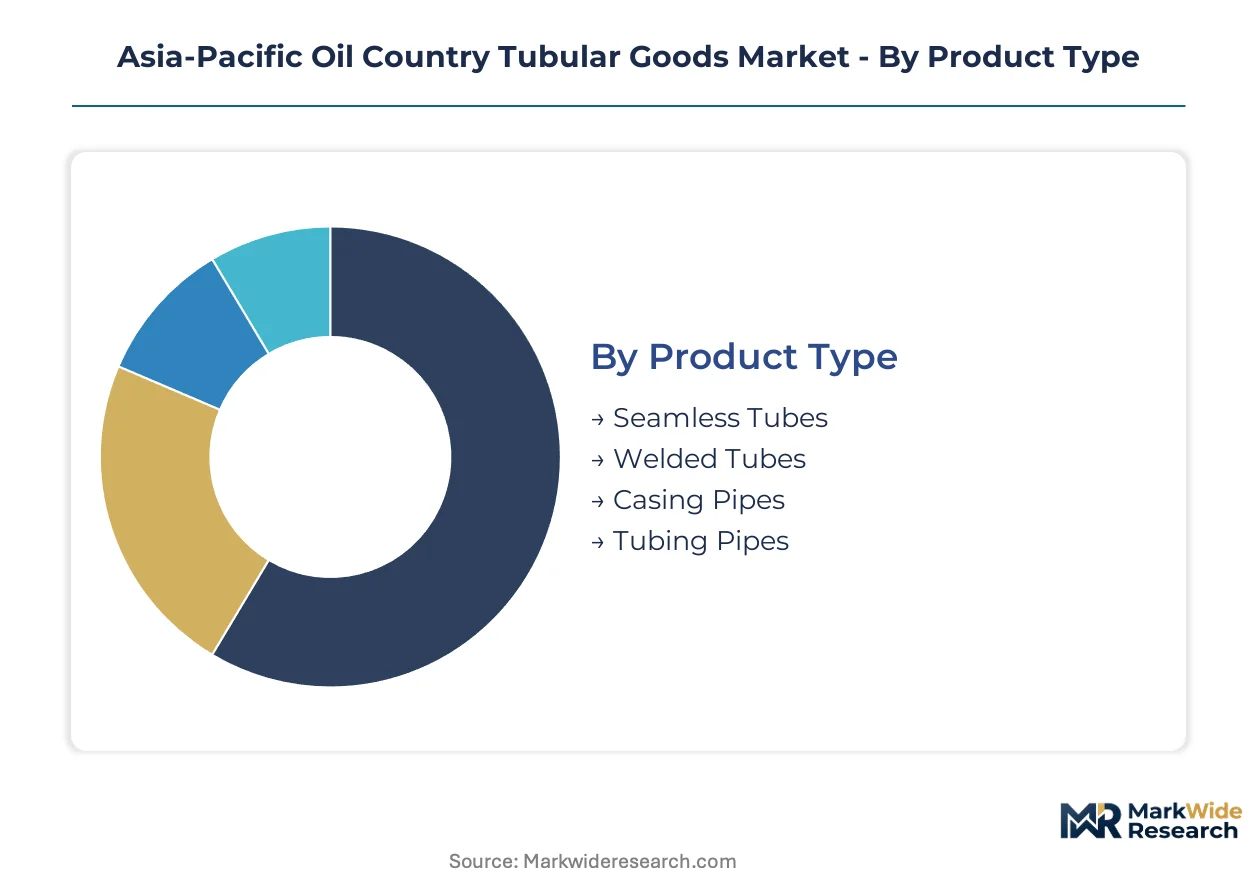
OCTG procurement in Asia-Pacific stratifies sharply across metallurgical grades and manufacturing methods. Operators select tubular categories based on reservoir pressure regimes, corrosive gas content, and regulatory well integrity mandates rather than unit cost alone.
Product Type:
Mature seamless rolling capacity dominates premium offshore contracts, while welded tube producers compete aggressively onshore where pressure ratings permit.
- Seamless Tubes:Hot-rolled from solid billets without longitudinal weld seams, delivering uniform circumferential strength for burst-critical HPHT wells. Australian Northwest Shelf developments specify seamless exclusively for production casing below 3,000 meters. GB/T 19830 alloy tightening is pushing Chinese mills toward seamless-heavy output for Sinopec deep gas programs.
- Welded Tubes:Formed from skelp with electric resistance welding, cost-advantaged for standard onshore conductor casing. India's KG-D6 block uses welded strings for upper hole sections where formation pressures stay below 5,000 psi. Margins compress when scrap volatility hits electric arc furnace feedstock costs.
- Casing Pipes:Structural wellbore liners isolating formations from surface to total depth.
- Tubing Pipes:Conduit strings conveying reservoir fluids through production casing interiors.
Seamless tubes handle the majority of throughput; welded tubes are expanding most quickly in marginal onshore basins where operators accept lower safety factors.
Material:
Cost tier separation runs from commodity carbon grades through corrosion-resistant alloys commanding 3-4x unit premiums.
- Alloy Steel:Chromium-molybdenum metallurgy resists sulfide stress cracking in sour gas reservoirs. Japan's METI-coordinated JIS standards now align alloy specifications with API protocols for export competitiveness. Reliance's KG-D6 drilling mandates 13Cr minimums for all subsea completions.
- Carbon Steel:Standard API 5CT grades dominate shallow onshore drilling across China and Indonesia where CO2 partial pressures stay below threshold limits. Sinopec maintains carbon-heavy inventory for conventional Daqing field workovers.
- Stainless Steel:Duplex and super-duplex grades for ultra-corrosive offshore environments.
- Others:Titanium-clad and nickel-alloy specialty tubulars for extreme chemistries.
Alloy steel commands the steepest expansion trajectory as operators push into deeper, hotter reservoirs; carbon steel retains volume leadership in mature onshore provinces.
End User:
Application concentration splits between reservoir pressure regimes and water depth classifications.
- Offshore Drilling:Australia's NOPSEMA mandates premium threaded connections and full metallurgical traceability for all high-pressure permits. Woodside Energy bypasses distributors entirely, contracting direct with Japanese seamless mills for Northwest Shelf campaigns. Well integrity guarantees now transfer from NOCs to mill balance sheets.
- Oil Exploration:Wildcat drilling in Indonesia's frontier basins drives spot procurement of standard casing grades. Local content rule relaxation opens direct mill-to-operator contracting outside traditional networks.
- Gas Extraction:Sour gas developments requiring corrosion-resistant alloy specifications.
- Onshore Drilling:Conventional drilling programs in China's Sichuan and Tarim basins.
Offshore drilling concentrates premium procurement value; oil exploration is gaining share fastest as Indonesia relaxes local content barriers.
Application:
Customer type stratification separates exploration-phase tubular consumption from recurring production maintenance demand.
- Drilling:Initial well construction consumes 60-70% of OCTG tonnage per well, with casing programs stacked from conductor to production strings. China's national oil companies negotiate 18-24 month frame agreements covering multi-well programs, displacing spot distributor purchases.
- Maintenance:Workover tubing replacement and casing repair in mature fields. Australia's Cooper Basin operators schedule predictive tubing pulls based on corrosion monitoring rather than failure-driven replacement.
- Construction:Pipeline and facility fabrication using surplus OCTG specifications.
- Repair:Casing patch and squeeze operations extending well life.
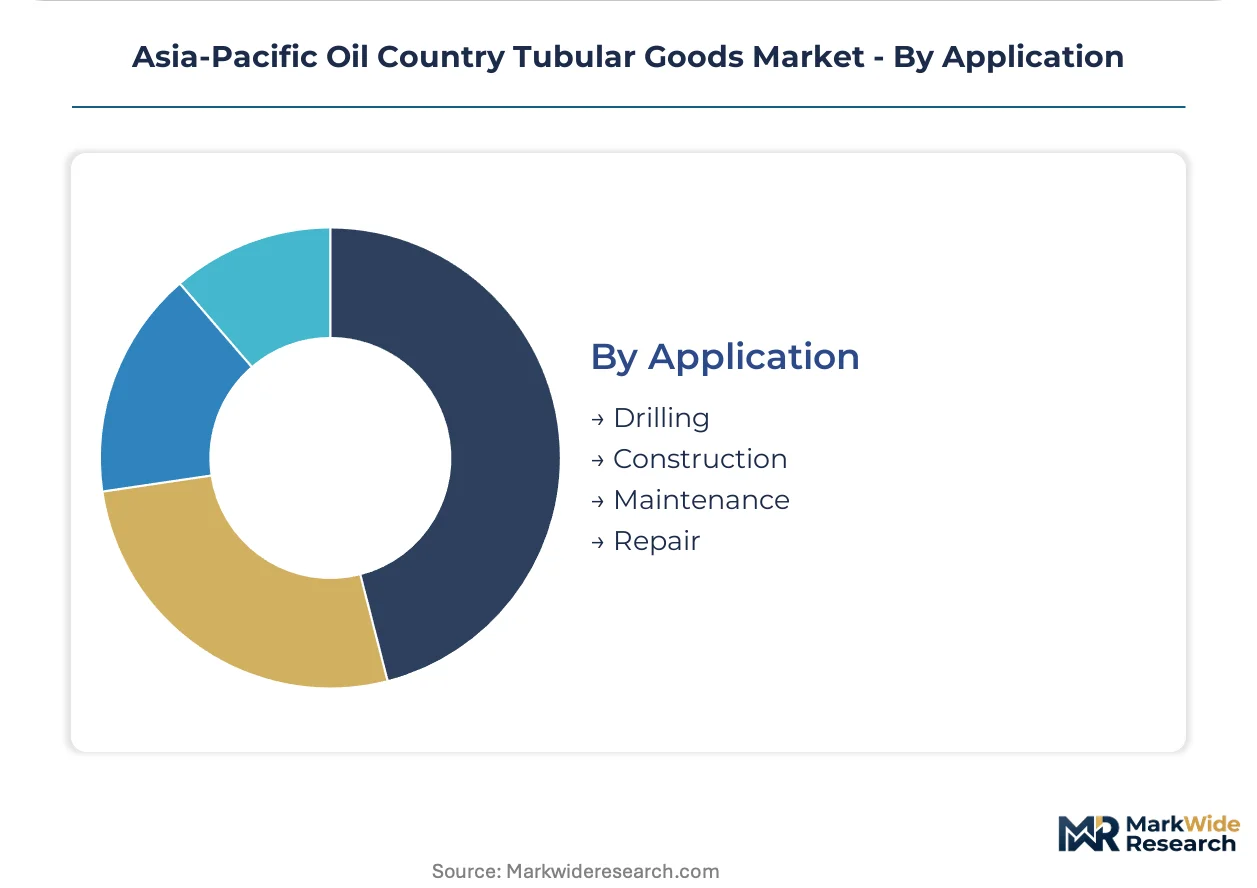
Drilling absorbs the dominant share of mill output; maintenance is climbing the fastest as Asia-Pacific's installed base ages into workover-intensive maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power across the Asia-Pacific OCTG landscape tilts sharply toward Japanese seamless mills commanding premium positioning in Australian offshore contracts, while Chinese producers compete on alloy-grade compliance for domestic NOC programs.
China
Sinopec and CNOOC drilling programs are absorbing higher-grade seamless output as SAMR tightens GB/T 19830 alloy specifications. The Tianjin port cluster concentrates over 60 percent of regional premium casing capacity, exposing supply chains to congestion risks. Mills near Tangshan are upgrading electric arc furnace feedstock handling to reduce scrap volatility exposure.
Australia
NOPSEMA well integrity mandates lock in premium threaded connections for all Northwest Shelf HPHT permits. Woodside Energy contracts directly with Japanese seamless producers rather than maintaining domestic tubular inventories. Perth serves as the procurement coordination hub for subsea developments off the northwest coast.
Japan
METI-coordinated JIS standard alignment with API protocols preserves export competitiveness for domestic mills. Kanto-based integrated steel producers leverage blast furnace-to-pipe production for regional offshore contracts. Nagoya-area threading facilities specialize in sour-service metallurgy for Australian gas developments.
India
Reliance-led KG-D6 block expansions are drilling deeper subsea wells requiring 13Cr minimum corrosion-resistant alloy tubing. Mumbai anchors procurement coordination for west coast deepwater programs. Gujarat-based distributors are losing share as NOCs negotiate direct mill frame agreements.
Indonesia
Frontier basin wildcatting in eastern provinces is driving spot procurement as the national regulator relaxes local content rules for deepwater blocks. Jakarta-based procurement offices are establishing direct mill-to-operator contracting lanes outside traditional distributor networks. Surabaya clusters welded pipe fabricators serving mature onshore fields.
Asia-Pacific Oil Country Tubular Goods Market Competitive Environment
Integrated blast furnace operators and electric arc furnace specialists split the market between premium offshore contracts and volume onshore supply. Japanese and South Korean mills anchor the premium tier through captive seamless rolling and proprietary threading technology. Chinese producers dominate standard-grade volume through clustered Tianjin-area capacity. Competitive moves concentrate on metallurgical certification stacking and direct NOC frame agreement negotiation.
Among Japanese integrated steel producers, Nippon Steel Corporation and JFE Steel Corporation exemplify the blast furnace-to-pipe archetype with positioning in Australian offshore contracts. TPCO Enterprise occupies a central position within Chinese supply, representing the domestic seamless-heavy capacity serving Sinopec and CNOOC programs. Vallourec and Tenaris sit within the multinational premium-connection tier, anchoring sour-service metallurgy offerings for HPHT developments.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| ILJIN Steel |
| TPCO Enterprise |
| JFE Steel Corporation |
| Tenaris |
| ArcelorMittal |
| Vallourec |
| TMK |
| Jindal Saw |
| Others |
Value Chain & Pricing Dynamics
Tianjin's seamless mill cluster concentrates over sixty percent of Asia-Pacific premium casing capacity, translating geographic supply density into asymmetric pricing power for Japanese and South Korean producers serving Australian offshore contracts. Chinese electric arc furnace operators compete on alloy-grade compliance for domestic NOC programs, but scrap-fed volatility compresses margin stability against integrated blast furnace rivals.
Pricing Analysis
The customization-premium spread separates configured-to-order seamless strings from standard welded commodity grades by factors of three to four. Pricing stratifies across premium threaded connections for HPHT wells, standard API 5CT certified grades for conventional drilling, and economy welded conductor casing for shallow onshore programs. Price differentiation hinges on metallurgical certification tier and after-sales field engineering bundling. Cost compression in the standard welded tier is intensifying because scrap volatility hits electric arc furnace feedstock costs that seamless rolling cannot fully pass through contract pricing. National oil companies exhibit lowest price sensitivity for premium offshore strings, while marginal onshore operators in Indonesia's frontier basins drive spot-market discounting.
Supply Chain Analysis
Ferrous scrap, chromium-molybdenum alloying elements, and proprietary threading technology constitute the upstream feedstock dependencies shaping Asia-Pacific OCTG economics. Supply concentrates in China, Japan, and South Korea, with Tianjin anchoring seamless rolling and Nagoya-area facilities specializing in sour-service metallurgy. Raw material sourcing draws from Australian iron ore, Indonesian nickel for stainless grades, and volatile global scrap markets. Single-source vulnerability to port congestion at Tianjin exposes procurement timelines for Sinopec and CNOOC drilling programs. Distribution runs through direct mill-to-operator frame agreements that displace traditional stock-and-distribute networks, particularly visible in Woodside Energy's dedicated supply lines with Japanese seamless producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific OCTG markets face high-growth disruption as GB/T 19830 alloy tightening and Australia's NOPSEMA well integrity mandates simultaneously elevate technical barriers and consolidate procurement around integrated mills. This regulatory-technological inflection favors metallurgical differentiation over scale economies.
For Market Incumbents: Build proprietary threading technology moats through captive R&D in sour-service metallurgy and premium connection field engineering. Defensive moves center on securing dual GB/T 19830 and API 5CT certification ahead of Chinese NOC export tender timelines, while adding seamless rolling capacity in low-power-cost geographies to offset Tianjin clustering risk. The threat of electric arc furnace margin compression from scrap volatility makes blast furnace integration the critical lever for premium positioning.
For New Entrants and Emerging Players: Indonesia's frontier basins offer the most penetrable white-space as local content rule relaxation opens direct mill-to-operator contracting lanes outside established distributor networks. Target welded pipe fabrication for upper-hole conductor sections where pressure ratings permit commodity metallurgy, leveraging Surabaya's existing cluster for regional logistics. The go-to-market angle centers on digital thread inspection bundling with blockchain traceability to reduce insurance premiums for independent operators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated mills with captive seamless rolling and in-house testing laboratories over trader-distributor models disqualified by NOPSEMA traceability mandates. Long-term viability across the analysis window hinges on alloy-grade migration from carbon steel to chromium-molybdenum specifications. The acquisition target archetype combines Japanese or South Korean threading technology with Chinese scale capacity. The signal to watch is frame agreement duration extension beyond eighteen months, indicating procurement consolidation momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Rolling Capacity Expansion | Captures premium HPHT demand as GB/T 19830 tightens alloy specifications for Sinopec programs. |
| Dual Certification Investment | Qualifies mills for Chinese NOC export tenders requiring simultaneous GB/T 19830 and API 5CT compliance. |
| Proprietary Threading Technology Development | Locks in Australian offshore contracts through NOPSEMA-mandated premium connection performance guarantees. |
| Direct Mill-to-Operator Frame Agreements | Bypasses distributor networks as Woodside Energy and Reliance consolidate procurement around dedicated supply lines. |
| Digital Traceability Platform Deployment | Enables real-time metallurgical provenance verification that reduces insurance premiums for offshore deployments. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with OCTG procurement officers at national oil companies, drilling contractors, and seamless mill technical directors, combined with secondary validation through API certification databases, SAMR regulatory filings, and customs trade records for alloy steel pipe movements. Stakeholder conversations spanned Sinopec material planners, Woodside Energy supply chain leads, JFE Steel export managers, and Reliance drilling engineers. Secondary sources included NOPSEMA well integrity guidance documents, METI JIS standard revision notices, and Indian Directorate General of Hydrocarbons production statistics. Bottom-up tubular demand modeling triangulated against top-down steel consumption forecasts.
Forecast inputs considered seamless versus welded manufacturing method splits, carbon versus alloy steel grade migration patterns, and offshore versus onshore application concentration across the projection horizon. Segmentation dimensions modeled encompassed product type, material specification, end-user industry, and geographic regulatory cluster. CAGRs derived from regression analysis of historical drilling activity against tubular consumption intensity, incorporating HPHT well count trajectories and sour gas development timelines as industry-specific demand drivers.
Practitioners should monitor SAMR regulatory enforcement intensity, Australian offshore permit award velocity, and ferrous scrap price volatility for early signals of forecast revision. Cross-checking against IEA oil and gas investment outlooks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Shale Shakers Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Oilfield Market
Oil & Gas
Liquefied Natural Gas Market