
 Exploration and Drilling Security Market | 2026-2036
Exploration and Drilling Security Market Size, Share, and Industry Trends Forecast 2026-2036
Exploration and Drilling Security Market Foresight
API-standard cybersecurity certification is reorganizing vendor qualification protocols across offshore drilling contracts. Schlumberger leverages its integrated digital platform to anchor cybersecurity services within broader drilling packages. Baker Hughes competes through specialized threat-detection hardware purpose-built for subsea communication networks. Honeywell controls a dominant position in process safety systems that now merge with physical access management at rig sites.
Exploration and drilling security encompasses protective systems, monitoring infrastructure, and risk mitigation protocols designed to safeguard personnel, equipment, and data across upstream energy operations. These installations typically integrate intrusion detection sensors, video analytics with low-light performance specifications, and encrypted communication backbones capable of operating in explosive atmospheres certified to IECEx standards. Physical security services command the largest revenue share among service types due to persistent manned-guarding requirements at remote onshore and offshore facilities. Cybersecurity represents the fastest-expanding technology segment as drilling automation and remote operations expose previously isolated control systems to network-borne threats.
The US Coast Guard enforces maritime security regulations under the Maritime Transportation Security Act that mandate vessel and facility security plans for offshore drilling units. BSEE administers safety and environmental management system rules that incorporate security incident reporting as a compliance element for Outer Continental Shelf operators. The EU's NIS2 Directive extends critical infrastructure cybersecurity obligations to offshore oil and gas installations in European waters. Stakeholders must evaluate how converging physical-cyber regulatory frameworks reshape capital allocation between traditional guarding budgets and integrated security technology platforms.
Market Dynamics
Converging cyber-physical threat vectors at remote drilling sites are forcing capital reallocation from standalone guarding contracts toward integrated security technology platforms that unify physical access, process safety, and network defense.
Growth Catalysts
- Maritime Transportation Security Act mandates:US Coast Guard vessel and facility security plans for offshore drilling units create baseline compliance spending that vendors can upsell into comprehensive solutions.
- Deepwater exploration intensity:US Gulf Coast cluster operators generate the highest security service procurement intensity globally due to concentrated ultra-deepwater activity and hurricane-season operational continuity requirements.
- Drilling automation proliferation:Remote operations and automated rig controls expose previously isolated industrial control systems to network-borne threats, expanding addressable market for cybersecurity overlays.
Market Restraints
- Specialized labor scarcity:Certified security technicians qualified for explosive atmosphere work under IECEx standards command premium wages that compress vendor margins.
- Subsea communication hardware concentration:Purpose-built threat-detection equipment for subsea networks relies on limited qualified suppliers, creating procurement bottlenecks.
- Dual compliance burden:BSEE safety and environmental management system rules layered with Coast Guard maritime security mandates generate redundant reporting overhead for Outer Continental Shelf operators.
Strategic Opportunities
- European NIS2 Directive extension:Critical infrastructure cybersecurity obligations now cover offshore oil and gas installations in European waters, opening new compliance-driven demand.
- AI-powered video analytics:Low-light performance specifications for intrusion detection sensors at remote facilities enable technology convergence between physical surveillance and automated threat classification.
- Integrated platform bundling:Vendors anchoring cybersecurity services within broader drilling service packages can capture recurring revenue streams beyond equipment sales.
Industry Challenges
- Legacy control system integration:Decades-old SCADA infrastructure at mature offshore platforms requires complex retrofitting to achieve encrypted communication backbones without operational disruption.
- API-standard certification timelines:Vendor qualification protocol reorganization under new cybersecurity certification frameworks extends sales cycles and strains technical documentation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exploration and Drilling Security Market |
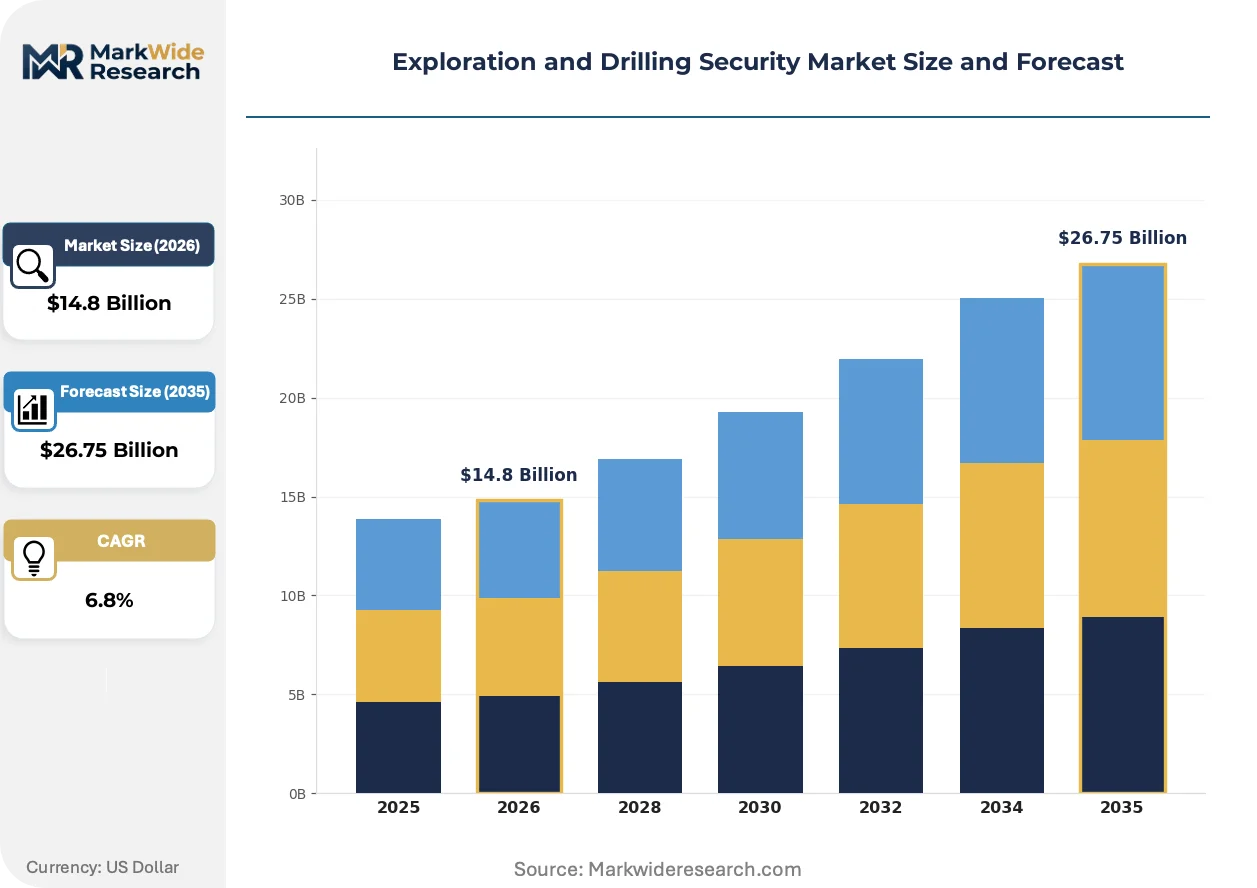
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.75 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
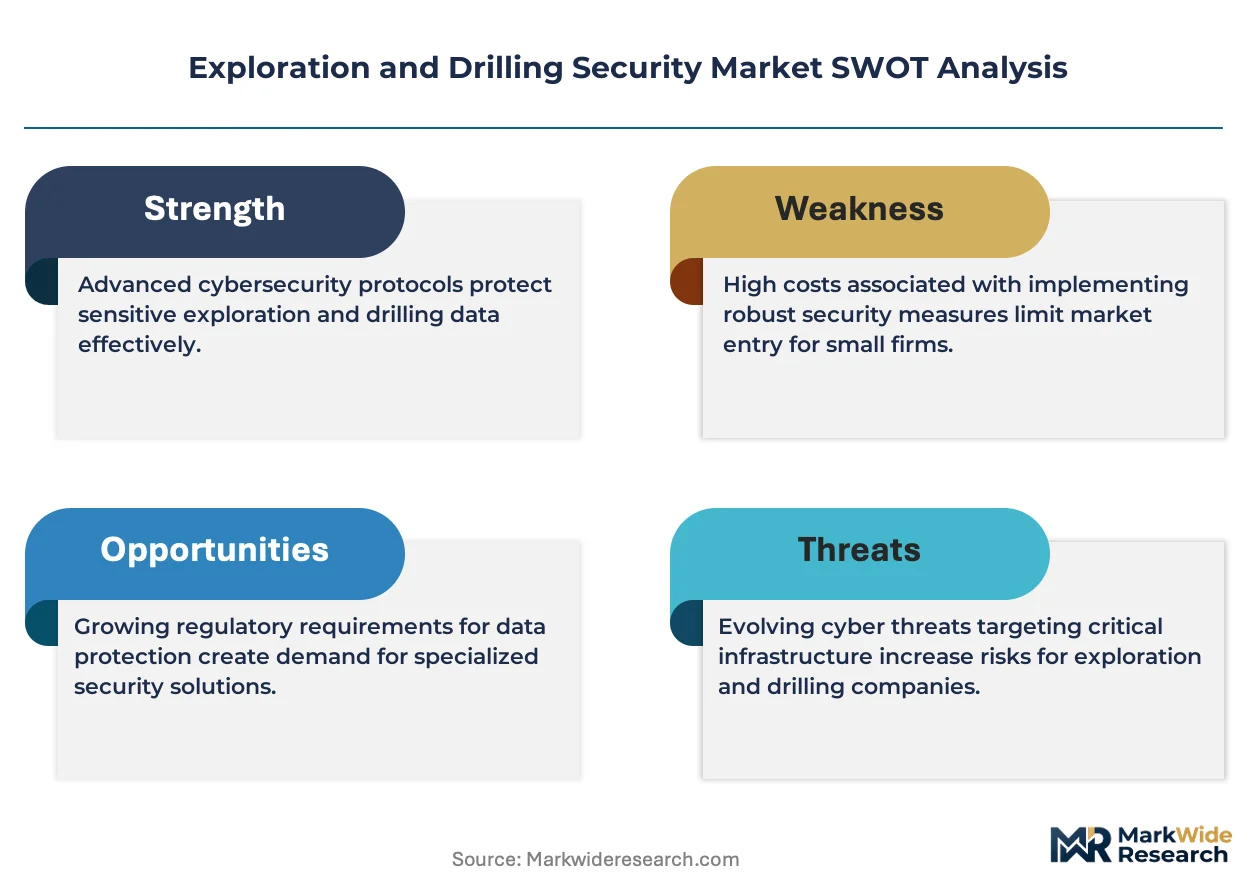
| Segmentation | Service Type: Physical Security, Cybersecurity, Surveillance, Consultancy Technology: Access Control, Intrusion Detection, Video Monitoring, Threat Intelligence End User: Oil & Gas Companies, Mining Firms, Government Agencies, Contractors Application: Site Security, Asset Protection, Emergency Response, Risk Management |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, TechnipFMC, Saipem, Honeywell, Fugro, Weatherford International, Veritas Geophysical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exploration and Drilling Security Market Shifts & Advancements
Security architecture at drilling facilities is splitting into two parallel evolution tracks: hardened perimeter defense for legacy assets and software-defined protection for digitally native operations.
Edge computing nodes with localized threat processing are bifurcating security system design philosophies across the offshore fleet. Deepwater operators in the US Gulf are deploying these devices at production pace to reduce satellite bandwidth dependency for real-time anomaly detection. This technology compression is enabling autonomous response protocols that bypass human-in-the-loop delays for critical infrastructure protection.
EU NIS2 Directive enforcement is extending critical infrastructure cybersecurity obligations to offshore installations in European waters. Operators must now document security incident reporting as a compliance element alongside existing environmental management commitments. North Sea drilling contractors are responding by consolidating fragmented physical and cyber security budgets under single vendor relationships.
Buyer contracting preferences are rotating from capital-intensive equipment purchases toward subscription-based monitoring services. Offshore operators in the Gulf of Mexico increasingly specify performance-guaranteed security outcomes rather than hardware specifications in tender documents. This unbundling of after-sales service from initial system deployment compresses vendor cash conversion cycles while locking in multi-year recurring relationships.
Exploration and Drilling Security Market Segmentation
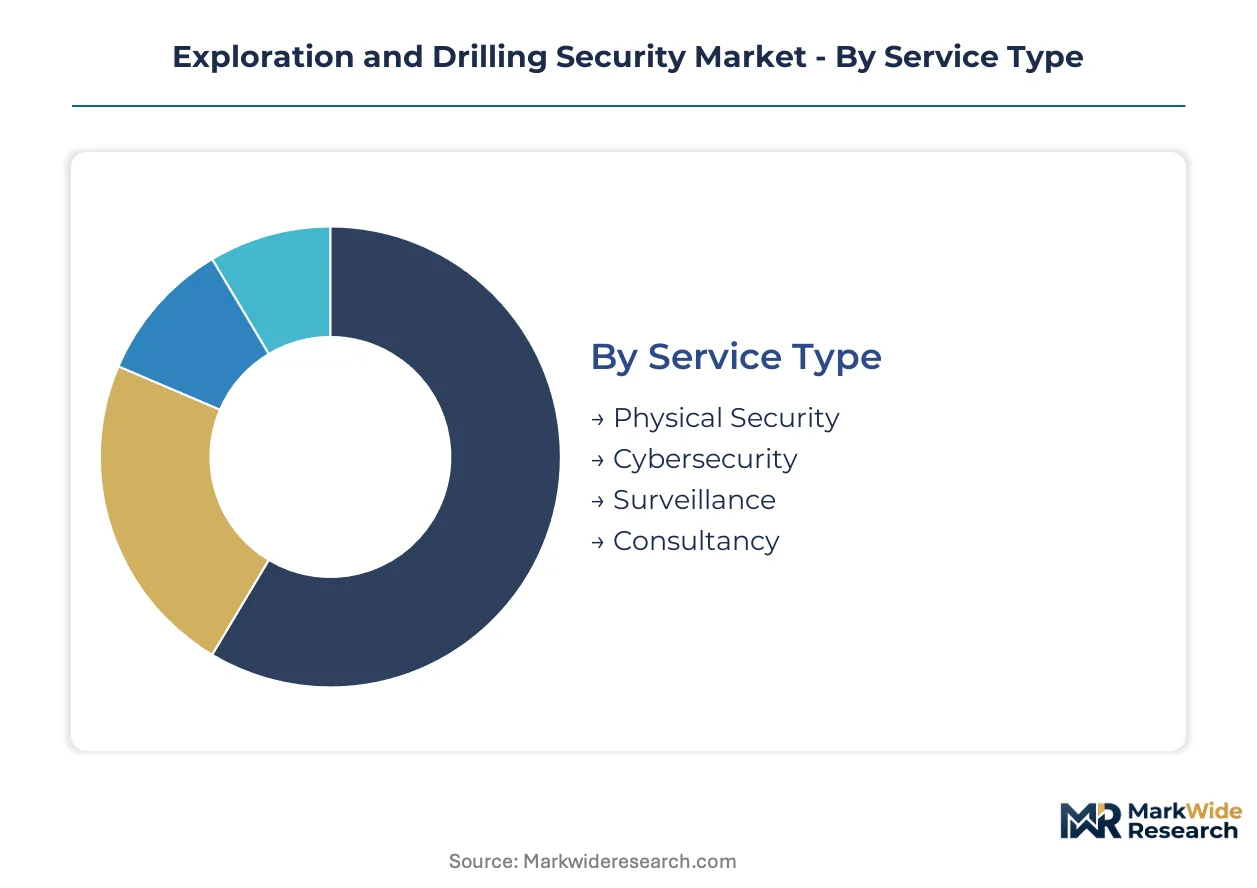
Security procurement patterns across exploration and drilling operations diverge sharply between capital-intensive physical infrastructure and recurring cybersecurity services. Understanding where operators concentrate spending reveals which vendor capabilities determine contract awards.
Service Type:
Margin pools concentrate in recurring service relationships rather than one-time equipment sales, with manned guarding and managed security operations generating sustained revenue streams.
- Physical Security:Manned guarding deployments at remote onshore and offshore facilities require personnel certified for explosive atmosphere work under IECEx standards. US Gulf Coast cluster operators generate the highest procurement intensity globally due to concentrated ultra-deepwater activity and hurricane-season operational continuity mandates. This segment commands the largest revenue share among service types.
- Cybersecurity:Network defense overlays for drilling automation and remote operations expose previously isolated industrial control systems to new threat vectors. European operators under NIS2 Directive obligations are consolidating fragmented physical and cyber budgets under single vendor relationships. This segment is expanding most quickly as digital infrastructure proliferates.
- Surveillance:Integrated sensor networks with low-light video analytics for perimeter monitoring at unmanned facilities.
- Consultancy:Risk assessment and compliance advisory services for BSEE and Coast Guard dual reporting requirements.
The dominant share belongs to Physical Security, while Cybersecurity is closing the gap fastest.
Technology:
Technology selection tracks the operational maturity of drilling assets, with legacy platforms requiring hardware retrofits and new builds accepting software-defined architectures.
- Access Control:Biometric and credential-based entry systems merging with process safety management at rig sites. Honeywell dominates this intersection through integrated platform offerings that bundle physical access with industrial control systems.
- Intrusion Detection:Sensor arrays with edge computing nodes for localized threat processing reduce satellite bandwidth dependency. Deepwater operators in the US Gulf deploy these at production pace for autonomous response protocols.
- Video Monitoring:AI-powered analytics with low-light performance specifications enabling automated threat classification.
- Threat Intelligence:Subscription-based monitoring services replacing capital-intensive hardware purchases in Gulf of Mexico tender documents.
Access Control captures the largest installed base, though Intrusion Detection is gaining share fastest through edge computing adoption.
End User:
End user procurement authority determines contract structure, with integrated oil companies favoring bundled drilling packages and specialized contractors seeking point solutions.
- Oil & Gas Companies:Majors and independents operating offshore facilities under BSEE and Coast Guard jurisdiction. These buyers increasingly specify performance-guaranteed outcomes rather than hardware specifications, compressing vendor cash conversion cycles while locking in multi-year recurring relationships.
- Mining Firms:Hard rock and mineral extraction operators with similar remote site security requirements but distinct regulatory frameworks.
- Government Agencies:National oil companies and energy ministries with procurement governed by public sector compliance protocols.
- Contractors:Drilling service providers leasing rigs to operators and assuming security responsibility under charter agreements.
Oil & Gas Companies dominate procurement volume, while Contractors are expanding their security decision authority fastest through rig leasing structures.
Application:
Application prioritization reflects whether operators treat security as operational expense or integrated risk management function.
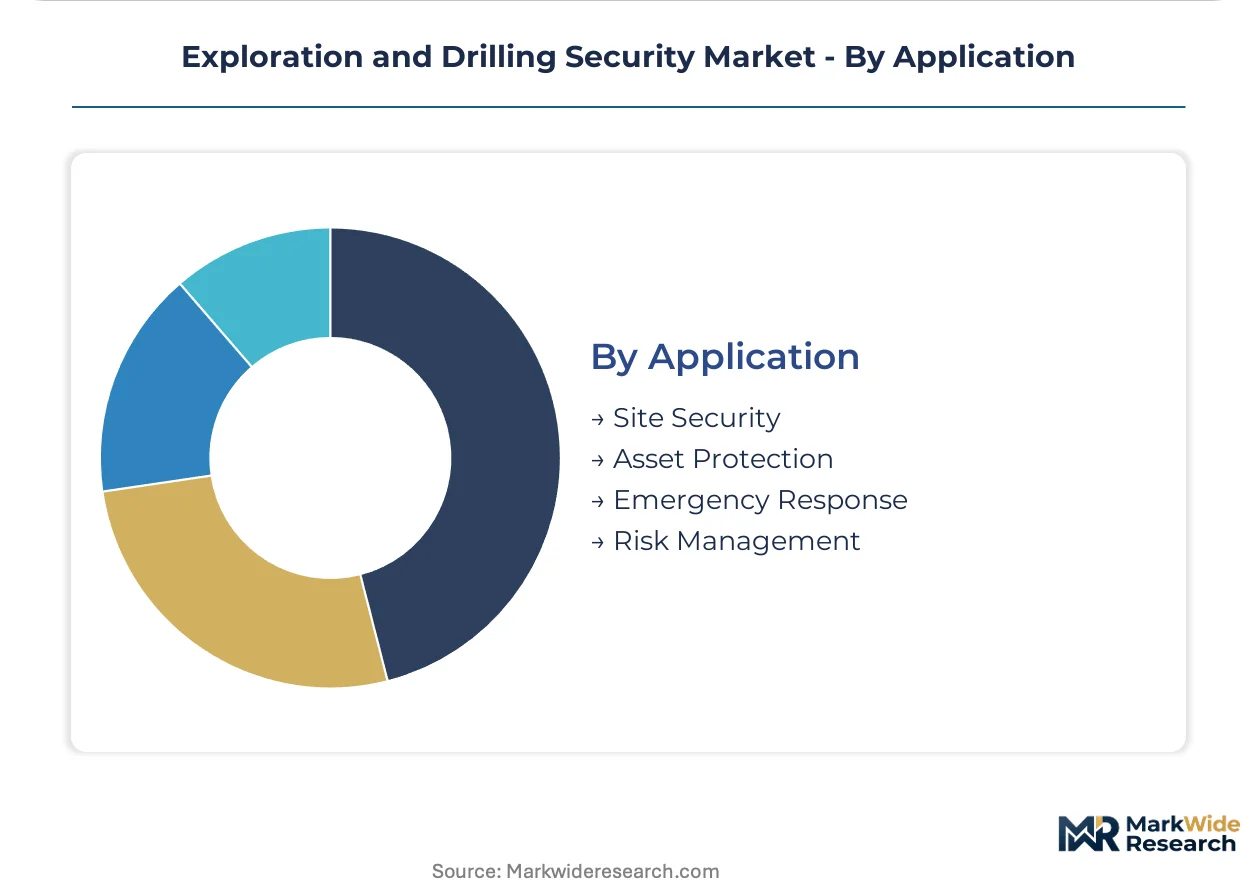
- Site Security:Perimeter defense and access management for onshore drilling pads and offshore platforms. Mature assets in the US Gulf require complex retrofitting of decades-old SCADA infrastructure to achieve encrypted communication backbones without operational disruption.
- Asset Protection:Equipment safeguarding and anti-theft measures for high-value drilling machinery and subsea hardware.
- Emergency Response:Coordinated evacuation and incident management protocols tied to BSEE safety and environmental management system rules.
- Risk Management:Enterprise-level threat assessment and insurance alignment across geographically dispersed operations.
Site Security holds the dominant position, yet Risk Management is ascending fastest as converged cyber-physical frameworks reshape capital allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Security equipment and services flow from US Gulf Coast engineering hubs to offshore installations across the Atlantic and Middle East, with Norwegian North Sea operators and Brazilian pre-salt developers emerging as the largest export destinations for integrated drilling protection systems.
United States
Deepwater exploration intensity in the Gulf of Mexico drives the highest security procurement intensity globally, with operators mandating hurricane-season operational continuity systems. The US Coast Guard enforces Maritime Transportation Security Act vessel and facility security plans that create baseline compliance spending. Ultra-deepwater clusters off Louisiana and Texas generate concentrated demand for manned guarding certified to IECEx explosive atmosphere standards.
Norway
North Sea drilling contractors face consolidated physical-cyber security obligations under the EU NIS2 Directive extension to offshore installations. The Norwegian Petroleum Safety Authority integrates security incident reporting into existing safety management frameworks. Stavanger and Bergen engineering centers host specialized vendors bundling threat-detection hardware with subsea communication network protection.
Brazil
Pre-salt deepwater development off the Santos Basin requires autonomous security response protocols for geographically isolated platforms. The country's national petroleum regulator mandates facility security plans aligned with International Maritime Organization guidelines. Rio de Janeiro serves as the procurement hub where integrated oil companies consolidate fragmented guarding and cybersecurity budgets.
United Kingdom
Mature North Sea assets require complex retrofitting of legacy SCADA infrastructure to achieve encrypted communication backbones without production disruption. The Health and Safety Executive layers security requirements atop existing environmental management commitments. Aberdeen maintains its position as the primary service coordination point for North Atlantic offshore security contracts.
Saudi Arabia
Offshore expansion in the Arabian Gulf generates demand for integrated platforms merging physical access control with process safety management. The national oil company procurement protocols favor bundled drilling service packages that embed cybersecurity overlays. Dhahran-based engineering centers anchor vendor relationships for Red Sea and Gulf development projects.
Exploration and Drilling Security Market Competitive Landscape
Listed energy technology conglomerates compete with private specialists across certification-heavy procurement channels, creating a tiered structure where scale advantages in API-standard documentation collide with niche expertise in explosive atmosphere work. Three archetypes dominate: integrated drilling service providers bundling security into broader contracts, industrial automation specialists merging physical access with process control systems, and dedicated maritime security firms focused on subsea threat detection. Competitive moves concentrate on vertical integration of cybersecurity capabilities and geographic expansion through rig-leasing structures that transfer security responsibility.
Within the integrated services tier, Schlumberger, Baker Hughes, and Honeywell occupy positions that exemplify divergent strategic anchors. Schlumberger represents the digital platform approach, Baker Hughes exemplifies specialized hardware development, and Honeywell sits within the industrial control convergence archetype. These three entities collectively illustrate how vendor qualification protocols under evolving cybersecurity certification frameworks reshape contract award dynamics across offshore drilling markets.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| TechnipFMC |
| Saipem |
| Honeywell |
| Fugro |
| Weatherford International |
| Veritas Geophysical |
| Others |
Supply & Pricing Matrix
Explosive atmosphere certification capacity at Houston and Stavanger engineering centers concentrates vendor bargaining power and establishes price floors for IECEx-qualified security technicians. This scale dynamic compresses margins for mid-tier suppliers while anchoring premium tiers for integrated platform providers that bundle physical access with cybersecurity overlays.
Pricing Analysis
Next-generation edge computing nodes for localized threat processing command 40-60% premiums over prior-generation satellite-dependent sensor arrays, while legacy SCADA retrofit services face persistent cost compression. Three-tier pricing structure across premium, standard, and economy levels separates API-standard certified platforms from basic compliance packages and unbundled hardware sales. Pricing pressure stems from buyer rotation toward subscription-based monitoring services in Gulf of Mexico tender documents. National oil companies exhibit lowest price sensitivity due to bundled procurement protocols, while independent drilling contractors face acute margin pressure from dual BSEE and Coast Guard compliance burdens.
Supply Chain Analysis
Extended lead times for subsea communication hardware from Norwegian and UK suppliers create inventory buffers that strain working capital for deepwater project timelines. Component sourcing draws from semiconductor fabrication in Taiwan, specialized sensor manufacturing in Germany, and explosive atmosphere enclosure production in the United States. Single-source vulnerability concentrates in IECEx-certified edge computing modules from limited qualified vendors. Distribution runs through Houston, Stavanger, and Rio de Janeiro engineering hubs that anchor vendor relationships for Atlantic basin offshore developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Exploration and drilling security sits in early-cycle expansion as converged cyber-physical threats force capital reallocation from standalone guarding toward integrated technology platforms. The NIS2 Directive extension to European offshore installations accelerates this penetration trajectory.
For Market Incumbents: Consolidate fragmented physical and cybersecurity budgets under single vendor relationships to defend against specialized maritime security firms capturing subsea threat detection share. Prioritize backward integration into edge computing module production to reduce single-source procurement bottlenecks. Lock in multi-year recurring service contracts before buyer preferences fully rotate toward performance-guaranteed outcomes.
For New Entrants and Emerging Players: Lead with AI-powered video analytics offerings targeting mature North Sea assets requiring complex SCADA retrofit without operational disruption. Penetrate the contractor segment fastest through rig-leasing structures that transfer security decision authority from operators. Establish beachheads in Brazil pre-salt developments where autonomous response protocols for geographically isolated platforms face limited incumbent saturation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors anchoring cybersecurity services within broader drilling service packages rather than standalone hardware specialists. Five-to-ten year viability hinges on recurring revenue share exceeding equipment sales. Watch API-standard certification timeline extensions as the inflection signal for vendor qualification protocol consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Platform Bundling | Captures recurring revenue streams beyond equipment sales through Schlumberger-style digital anchoring. |
| Backward Integration into Edge Computing | Reduces satellite bandwidth dependency and procurement bottlenecks for Gulf of Mexico deepwater operators. |
| NIS2 Directive Compliance Certification | Opens European North Sea demand as security incident reporting merges with existing safety frameworks. |
| AI-Powered Video Analytics Development | Enables autonomous response protocols that bypass human-in-the-loop delays for critical infrastructure protection. |
| Rig-Leasing Security Responsibility Transfer | Expands addressable market through contractor segment decision authority in Brazil and US Gulf charter structures. |
Research Methodology
Cross-validation between primary interviews with offshore security directors and secondary regulatory filings anchors the qualitative findings in documented compliance patterns. Security operations managers at US Gulf Coast operators, BSEE incident reporting officers, Norwegian Petroleum Safety Authority framework specialists, and subsea communication network engineers provided operational ground-truth. Bottom-up triangulation against Coast Guard Maritime Transportation Security Act enforcement records, BSEE safety management system audits, EU NIS2 Directive implementation guidance, and API cybersecurity certification documentation validated segment-level assumptions.
Sensitivity analysis across deployment model, asset maturity tier, regulatory framework cluster, and service integration depth shaped the analytical framework over the projection horizon. Modeled dimensions span physical security, cybersecurity, surveillance, and consultancy services crossed with access control, intrusion detection, video monitoring, and threat intelligence technologies. CAGRs derived from penetration rate trajectories for drilling automation and remote operations adoption, hurricane-season operational continuity mandates, and IECEx certification capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained deepwater exploration intensity or accelerated regulatory convergence would require recalibration. Forecasts reflect assumptions about cyber-physical threat vector evolution and certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Sidetracking Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Africa Natural Gas Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
Well Cementing Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market