
 Ice Thermal Storage Systems Market | 2026-2036
Ice Thermal Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Thermal Storage Systems Market Insights
Aftermarket service revenue is rewriting competitive economics for ice thermal storage systems, pulling margin pools away from one-time equipment sales toward long-term maintenance contracts and performance guarantees. Trane Technologies leverages its extensive service network to capture recurring revenue streams across installed base expansion. Johnson Controls anchors its position through building automation integration that ties thermal storage into broader energy management platforms. CALMAC Manufacturing Corporation specializes in ice tank technology leadership, sustaining differentiation through proprietary coil designs and decades of field-proven installations.
Ice thermal storage systems utilize phase-change materials—typically water frozen into ice around heat exchange coils—to store cooling capacity during off-peak hours for discharge during periods of peak demand, with storage temperatures generally ranging from 22°F to 34°F depending on application requirements. These systems serve primary commercial and industrial purposes including demand charge reduction, chiller downsizing, and backup cooling redundancy for critical facilities. Ice tanks dominate installed capacity across mature district energy networks where centralized plants distribute chilled water to multiple buildings, while ice slurry represents the fastest-growing product category due to its superior heat transfer coefficients and compact storage footprint that appeals to space-constrained urban installations. Load shifting applications command the most attractive margins as utilities expand demand response programs that directly compensate facility operators for peak-period curtailment.
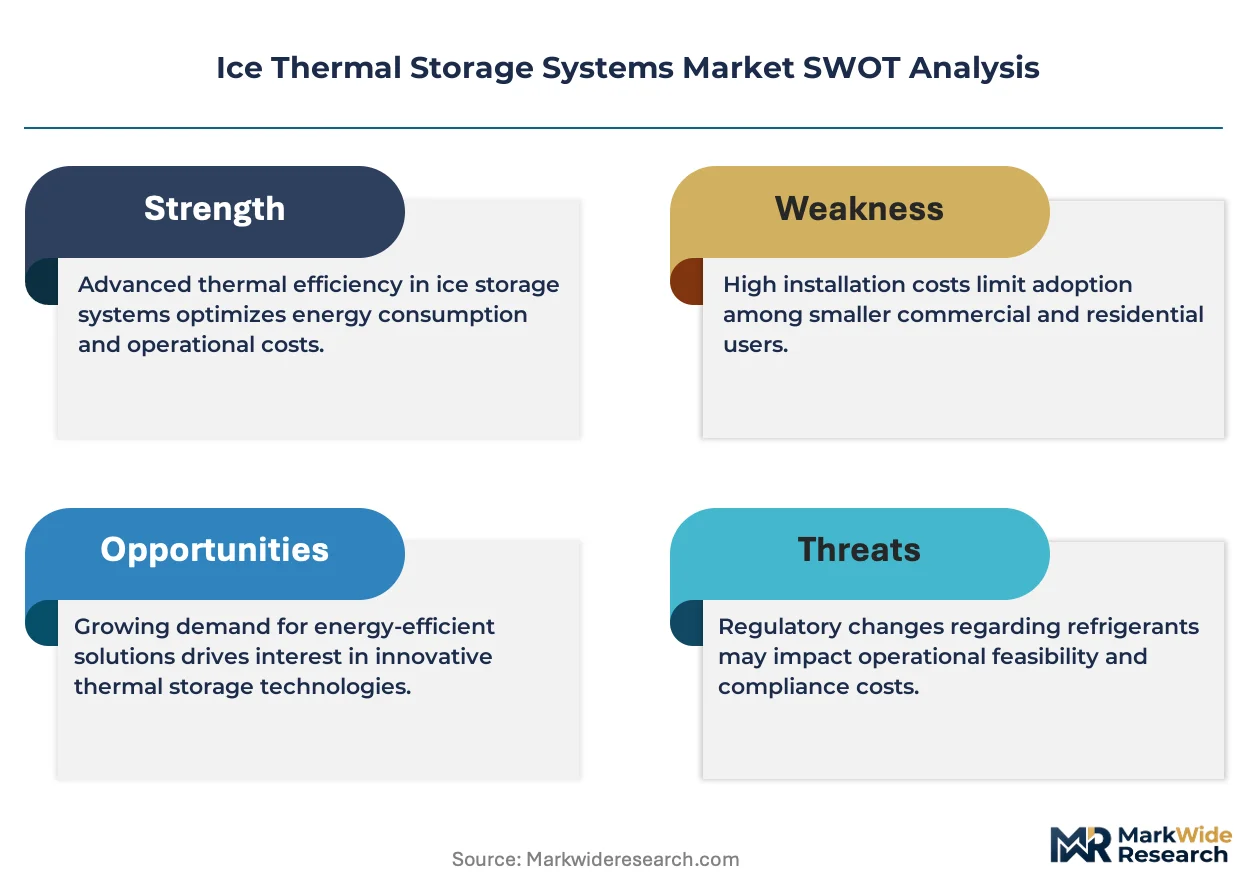
The U.S. Department of Energy's appliance and equipment standards program shapes product efficiency benchmarks, while ASHRAE Standard 90.1 influences building code adoption across municipalities and drives specification requirements for thermal storage integration. EPA regulations on refrigerant phase-down under the AIM Act are indirectly accelerating ice storage interest as facilities seek alternatives to conventional vapor-compression cooling expansion. Stakeholders must monitor evolving utility rate structures and carbon disclosure mandates to determine optimal timing for thermal storage investments against direct electrification alternatives.
Market Dynamics
Data center operators in the United States are accelerating ice thermal storage adoption to manage power density surges from AI-driven server loads, while utility time-of-use rate structures in California and Texas create direct economic incentives for load-shifting infrastructure.
Growth Catalysts
- FERC Order 2222:Grid operators must enable distributed energy resources including thermal storage to participate in wholesale markets, opening revenue streams for commercial building owners.
- Data center cooling:Hyperscale facilities deploy ice storage to downsize chiller plants and ride through utility peak pricing windows without operational interruption.
- Phase-change material advances:Eutectic salt formulations extend discharge durations beyond conventional ice systems, enabling longer load-shifting cycles for industrial process cooling.
Market Restraints
- Copper coil pricing volatility:Heat exchange component costs fluctuate with commodity markets, compressing margins on fixed-price installation contracts.
- Refrigerant phase-down timelines:EPA AIM Act restrictions on HFC production constrain conventional chiller expansion, yet ice storage uptake remains contingent on chiller plant retrofits that face permitting delays.
- Space constraints in dense urban cores:Ice tank footprints compete with rentable floor area in Class A office buildings, limiting retrofit viability in Manhattan and downtown San Francisco.
Strategic Opportunities
- Texas ERCOT grid volatility:Real-time pricing spikes exceeding $5,000 per MWh create payback periods under three years for thermal storage in Houston and Dallas commercial properties.
- Building automation convergence:Integration with digital twin platforms enables predictive ice discharge scheduling based on occupancy forecasting and weather data.
- District cooling networks:Campus-style deployments at universities and medical centers aggregate thermal loads across multiple buildings, improving storage utilization rates.
Industry Challenges
- Thermal engineering specialization:System design requires expertise in both HVAC and utility rate structures, creating hiring bottlenecks for regional contractors.
- Utility interconnection timelines:Behind-the-meter storage participation in demand response programs faces approval processes stretching 12-18 months in some ISO territories.
- Commissioning complexity:Ice storage performance guarantees depend on precise control sequencing with existing chiller plants, requiring extended startup periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Thermal Storage Systems Market |
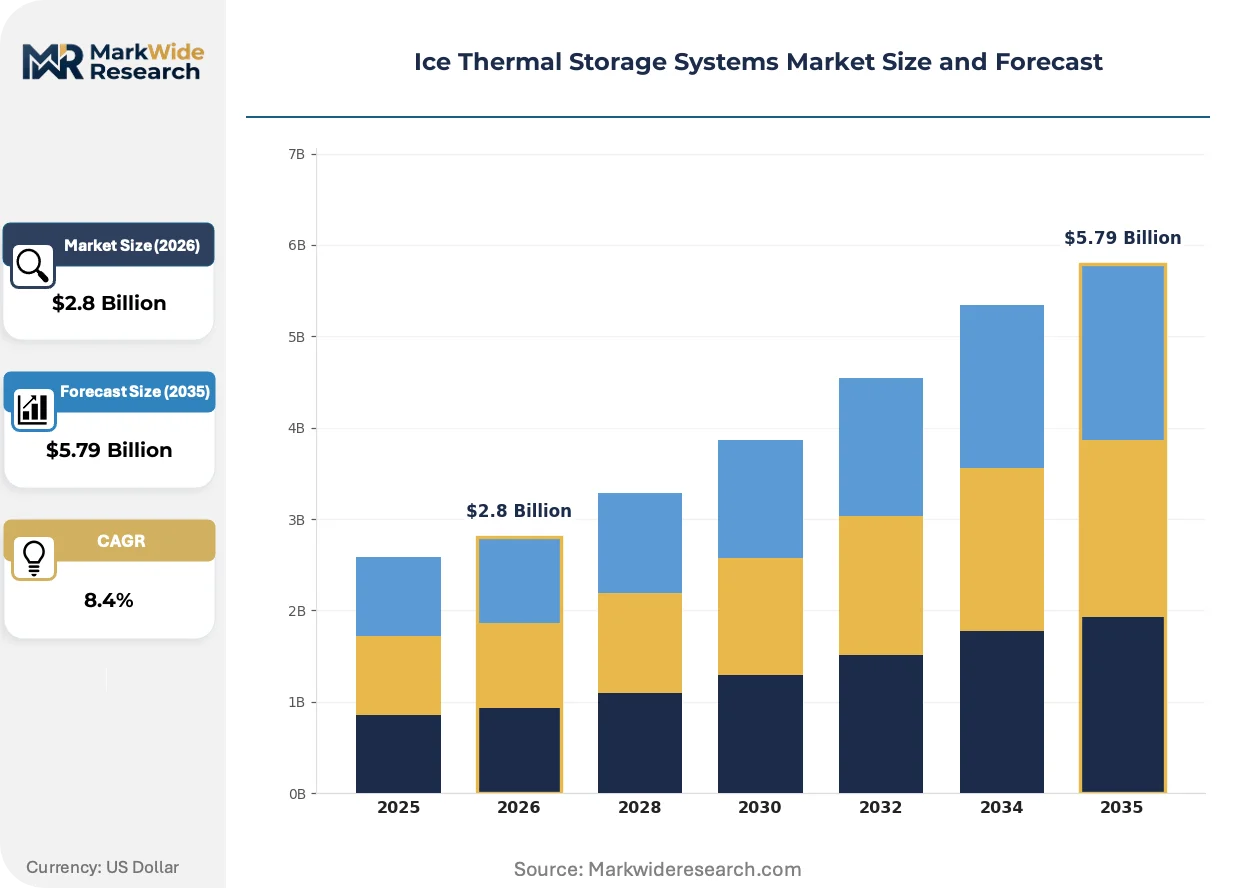
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Tanks, Ice Harvester, Ice Slurry, Ice Brick Application: Commercial Cooling, District Energy, Refrigeration, Load Shifting End User: Hospitality, Industrial, Educational Institutions, Retail Stores Installation: Indoor, Outdoor, Retrofit, New Construction |
| Companies Covered | CALMAC Manufacturing Corporation, Ice Energy, Trane Technologies, Johnson Controls, Carrier Corporation, Honeywell, EVAPCO, Baltimore Aircoil Company, Trojan Energy Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Thermal Storage Systems Market Trends and Innovations
Ice thermal storage technology is converging with building electrification mandates and grid-interactive controls, shifting competitive advantage from equipment efficiency toward software-enabled energy arbitrage.
Encapsulated ice ball systems are migrating from niche industrial applications toward mainstream commercial deployment. These spherical phase-change modules pack into vertical tanks rather than horizontal concrete vessels, reducing mechanical room footprints by 40 percent. Multi-tenant office developers in Boston and Seattle specify encapsulated systems to preserve leasable basement space while meeting local electrification ordinances.
California Title 24 building energy codes now mandate thermal energy storage readiness for new commercial construction above 100,000 square feet. This regulatory pressure forces mechanical engineers to size electrical service capacity for future ice storage integration even when initial installation is deferred. Developers respond by pre-plumbing chiller plants and reserving tank pad locations to avoid costly electrical upgrades later.
Facility managers increasingly bundle ice storage procurement with performance-based energy service contracts rather than capital purchases. Third-party thermal storage providers install and operate systems, capturing utility incentives and demand charge savings through shared savings agreements. This financing structure dominates the Arizona and Nevada markets where property owners prioritize balance sheet preservation over asset ownership.
Ice Thermal Storage Systems Market Segmentation
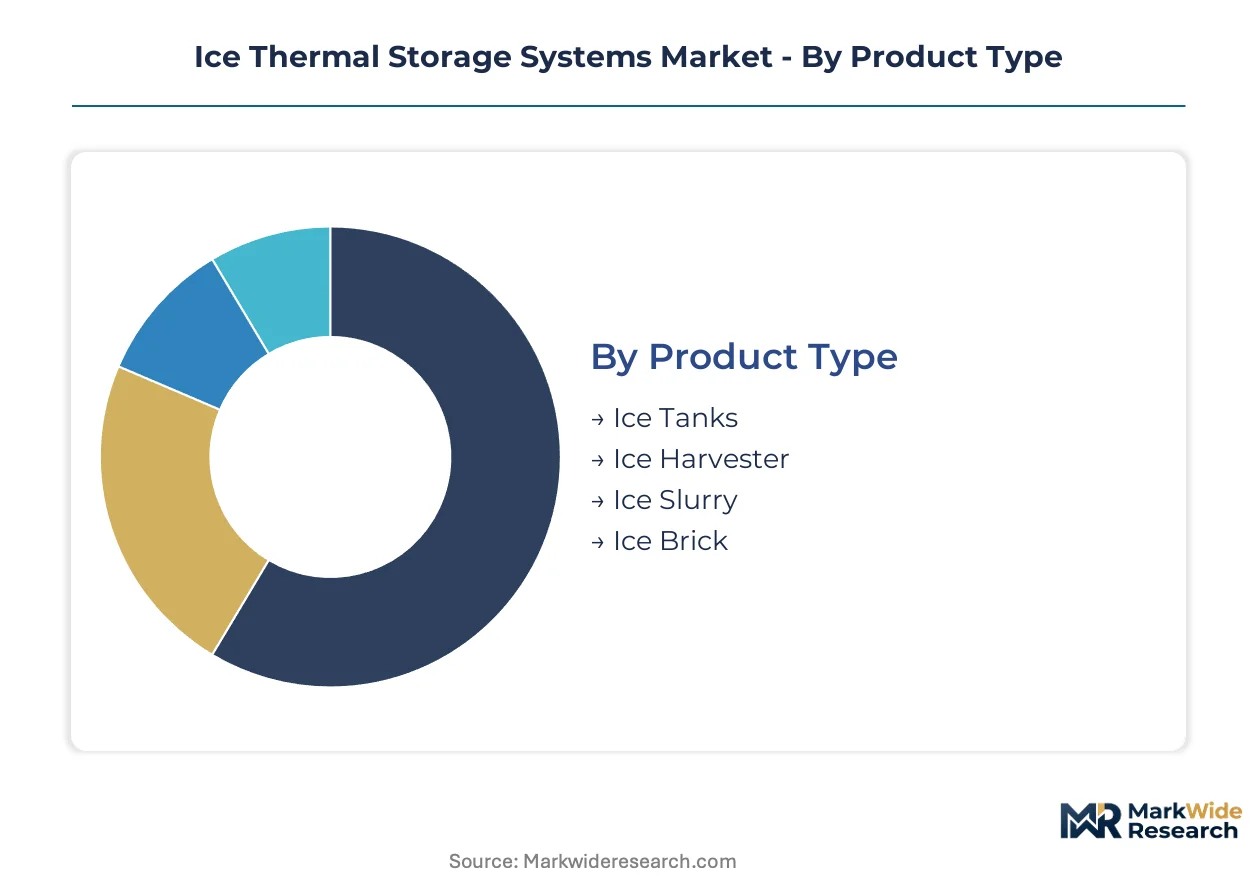
Product architecture, application intensity, and installation constraints fragment the ice thermal storage landscape into distinct commercial battlegrounds. Each segment carries unique margin profiles and capital cycle timing that reshape vendor positioning.
Product Type:
Ice tanks turn over on 15-20 year replacement cycles while ice slurry systems refresh every 8-12 years as heat exchange technology advances.
- Ice Tanks:Horizontal or vertical concrete or steel vessels containing submerged heat exchange coils that freeze water during off-peak hours. Demand concentrates in California district energy networks where utility time-of-use rates reward overnight charging cycles.
- Ice Slurry:Pumpable ice-water mixtures with superior heat transfer coefficients enable compact storage footprints. Texas data centers deploy these systems to ride through ERCOT real-time pricing spikes exceeding $5,000 per MWh.
- Ice Harvester:Mechanical systems that build ice on evaporator surfaces before harvesting into storage tanks. Industrial process cooling in Arizona favors this technology for extended discharge durations.
- Ice Brick:Modular encapsulated phase-change units that pack into vertical configurations. Boston developers specify these for basement-constrained Class A office retrofits.
Ice tanks anchor the volume base while ice slurry gains share at the steepest rate.
Application:
Margin tiers separate mission-critical cooling from discretionary efficiency plays, with district energy commanding the highest service contract attachment rates.
- Commercial Cooling:Office buildings and mixed-use developments deploy thermal storage to downsize chiller plants and capture utility demand response payments. California Title 24 mandates now require thermal storage readiness for new construction above 100,000 square feet.
- Load Shifting:Facilities discharge stored cooling during peak pricing windows to avoid demand charges. Texas and Arizona utilities compensate operators directly for peak-period curtailment, creating payback periods under three years.
- District Energy:Centralized plants distribute chilled water across campus or urban networks. University and medical center deployments in Houston and Dallas aggregate thermal loads to improve storage utilization.
- Refrigeration:Cold storage warehouses and food processing facilities maintain temperature stability during utility interruptions. EPA refrigerant phase-down timelines accelerate interest as operators seek alternatives to conventional vapor-compression expansion.
Commercial cooling carries the broadest installed base while load shifting delivers the steepest margin expansion.
End User:
Capital availability and technical sophistication create distinct procurement patterns across facility types.
- Industrial:Manufacturing and process cooling operations with predictable load profiles justify large-capital thermal storage investments. Eutectic salt formulations extend discharge durations for extended production cycles.
- Hospitality:Hotels and resorts prioritize guest comfort over energy arbitrage, limiting adoption to properties with sustainability mandates or utility incentive programs.
- Educational Institutions:Universities leverage district cooling networks to aggregate classroom, laboratory, and residential loads. Campus-style deployments improve storage utilization across seasonal demand variations.
- Retail Stores:Big-box and grocery chains face space constraints that favor compact ice slurry or encapsulated ice brick configurations over conventional tank systems.
Industrial facilities anchor the volume base while educational institutions gain share at the steepest rate.
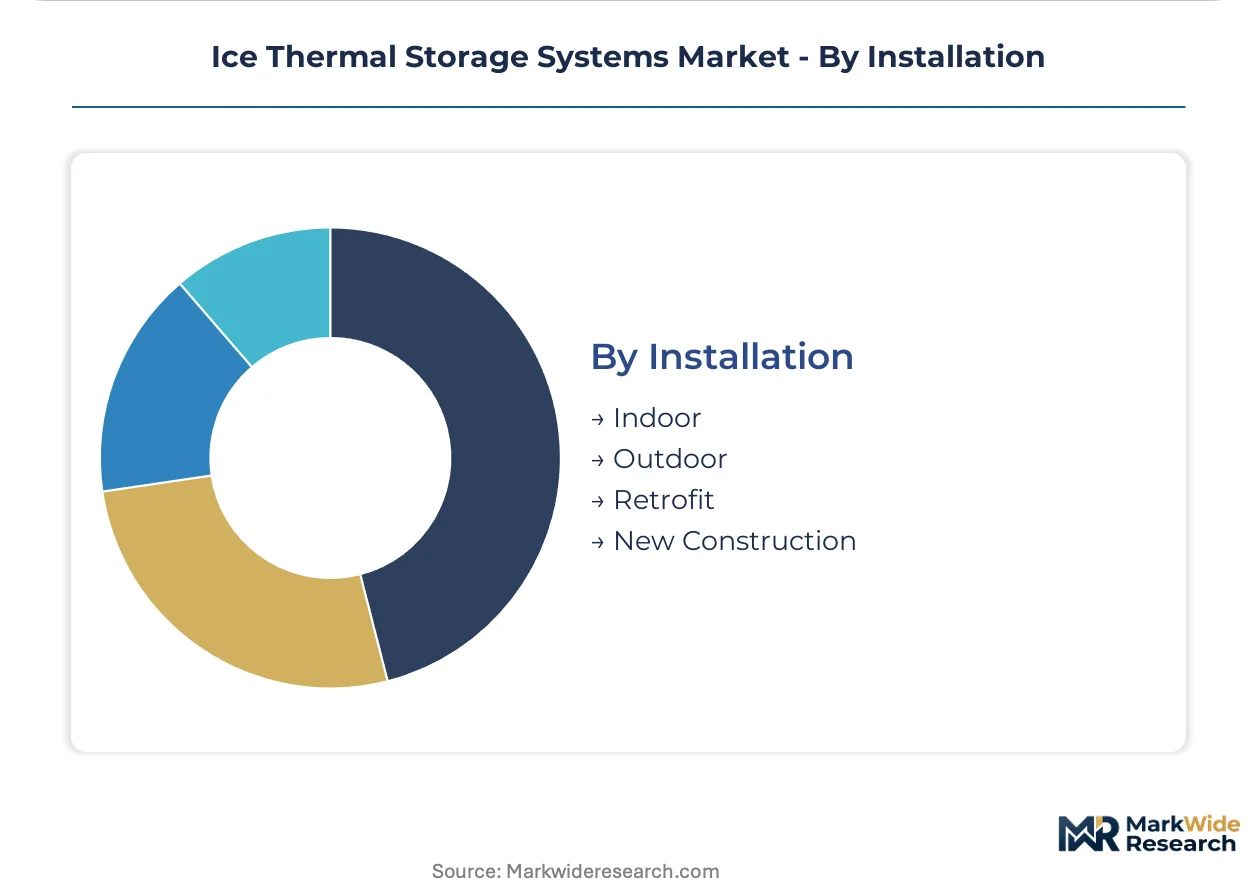
Installation:
Project risk profiles and margin structures diverge sharply between greenfield and retrofit contexts.
- New Construction:Developers pre-plumb chiller plants and reserve tank pad locations to avoid costly electrical upgrades later. California Title 24 mandates force mechanical engineers to size electrical service capacity for future ice storage integration.
- Retrofit:Existing buildings face space constraints and permitting delays that compress contractor margins. Manhattan and downtown San Francisco Class A office buildings struggle to sacrifice rentable floor area for ice tank footprints.
- Indoor:Mechanical room installations require vertical tank configurations or encapsulated ice ball systems to preserve leasable basement space. Boston and Seattle developers specify these for electrification ordinance compliance.
- Outdoor:Above-ground or buried tank installations suit properties with available land area. Industrial campuses and suburban office parks favor this lower-cost configuration.
New construction anchors the volume base while retrofit gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Texas and California exhibit the lowest price elasticity, absorbing premium equipment costs to capture ERCOT volatility and Title 24 compliance value. Facility operators in the Northeast and Midwest remain more price-sensitive, deferring investments absent utility incentive programs or electrification mandates.
United States
Data center operators in Northern Virginia and Phoenix deploy ice storage to manage AI-driven thermal loads while downsizing chiller plants. The U.S. Department of Energy's efficiency mandates for commercial buildings accelerate system upgrades in jurisdictions adopting ASHRAE Standard 90.1. California's Title 24 codes now require thermal storage readiness for new commercial construction above 100,000 square feet, forcing developers in Los Angeles and San Francisco to pre-plumb mechanical rooms.
Canada
District energy networks in Toronto and Vancouver aggregate campus cooling loads across universities and medical centers. Natural Resources Canada's energy efficiency regulations influence provincial building code adoption, particularly in Ontario and British Columbia. Montreal's district cooling system serves as the country's largest thermal storage installation, distributing chilled water across the downtown core.
Germany
Industrial process cooling operations in Bavaria and North Rhine-Westphalia justify thermal storage investments through extended discharge cycles. The EU F-Gas Regulation accelerates interest in alternatives to conventional vapor-compression expansion. Munich's district energy network integrates ice storage at centralized plants serving multiple commercial properties.
China
Peak-shaving requirements in the Yangtze River Delta and Pearl River Delta drive utility-scale thermal storage procurement. MIIT energy efficiency standards shape product specifications for commercial building applications. Shanghai's district cooling infrastructure serves as the primary deployment cluster, with ice tanks integrated into centralized plants across the Pudong financial district.
Japan
Space-constrained commercial developments in Tokyo and Osaka favor compact ice slurry and encapsulated ice brick configurations. METI building energy codes incentivize load-shifting infrastructure through time-of-use rate structures. The Tokyo Metropolitan Government mandates thermal storage readiness for large-scale new construction in the central business district.
Ice Thermal Storage Systems Market Competitive Landscape
Capability concentration sits with specialized thermal engineering firms; scale advantage sits with diversified HVAC conglomerates. The market structures around three tiers: full-system integrators with building automation platforms, component specialists with proprietary coil or tank designs, and regional contractors with local installation expertise. Dominant competitive moves include vertical integration into controls software and strategic partnerships with utility demand response programs.
Within the full-system integrator tier, Trane Technologies and Johnson Controls occupy positions that tie thermal storage into broader energy management platforms. CALMAC Manufacturing Corporation anchors the component specialist segment with decades of field-proven ice tank installations. These three companies exemplify the strategic archetypes reshaping competitive economics: recurring service revenue capture, building automation convergence, and proprietary hardware differentiation.
| Leading Market Players |
|---|
| CALMAC Manufacturing Corporation |
| Ice Energy |
| Trane Technologies |
| Johnson Controls |
| Carrier Corporation |
| Honeywell |
| EVAPCO |
| Baltimore Aircoil Company |
| Trojan Energy Systems |
| Others |
Pricing and Supply Chain Analysis
Copper coil commodity volatility determines both tiered pricing spreads and supply chain configuration across ice thermal storage system manufacturing. Equipment vendors absorbing spot-price swings on fixed installation contracts compress margins at the standard tier while premium-tier providers bundle long-term service agreements to insulate revenue from raw material cycles.
Pricing Analysis
Performance-based service contracts now drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates Trane Technologies' automation-integrated bundles from regional contractors' bare-metal installations. Cost compression in the economy tier intensifies because copper and steel commodity exposure concentrates in fixed-price retrofit projects. Data center operators in Northern Virginia exhibit the lowest price sensitivity, while Midwest commercial developers defer investments absent utility incentive programs.
Supply Chain Analysis
Extended payment terms from 90 to 120 days have become standard for heat exchange coil procurement from Chinese and South Korean metal fabricators. Domestic tank vessel manufacturing draws from U.S. steel mills and Mexican component assembly, with refrigeration-grade copper tubing sourced from Chilean smelters. Single-source vulnerability concentrates in specialized phase-change material formulations from German chemical suppliers. Distribution runs through regional HVAC wholesalers and direct EPC contractor relationships for hyperscale data center projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue layers expand faster than hardware sales as facility managers outsource thermal storage operations to third-party providers under shared-savings agreements.
For Market Incumbents: Pre-empt margin erosion from copper price volatility by captive supply of heat exchange coils through backward integration into metal fabrication. Consolidate regional service networks before emerging controls-software entrants capture building automation integration contracts. Lock in multi-year performance guarantees with California data center operators facing Title 24 compliance deadlines. For New Entrants and Emerging Players: Texas ERCOT grid volatility creates white-space opportunity for ice slurry specialists targeting Houston and Dallas commercial properties with sub-three-year payback propositions. Arizona and Nevada markets favor third-party thermal storage providers offering balance-sheet-friendly service contracts over capital purchases. Lead with utility incentive capture expertise rather than equipment efficiency claims. For Investors and Strategic Acquirers: EPA AIM Act refrigerant phase-down timelines reshape the acquisition landscape toward thermal storage assets displacing conventional chiller expansion. Long-term viability centers on software-enabled energy arbitrage capabilities rather than hardware manufacturing scale. Monitor FERC Order 2222 implementation velocity across ISO territories as the signal for distributed energy resource market participation maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Expansion | Third-party thermal storage operators capture recurring revenue through shared-savings agreements with Arizona and Nevada property owners. |
| Controls Software Integration | Building automation convergence enables predictive ice discharge scheduling based on occupancy forecasting and ERCOT real-time pricing data. |
| Phase-Change Material R&D | Eutectic salt formulations extend discharge durations beyond conventional ice systems for industrial process cooling applications. |
| Geographic Market Entry | Texas and California utility rate structures create payback periods under three years for load-shifting infrastructure deployment. |
| Utility Partnership Programs | Demand response program integration with FERC Order 2222 compliance opens wholesale market revenue streams for commercial building owners. |
Research Methodology
The analysis maps ice tank, ice slurry, ice harvester, and ice brick product architectures, each validated through facility managers, HVAC contractors, utility demand response program administrators, and district energy plant engineers. Primary interview insights triangulate against ASHRAE Standard 90.1 adoption tracking, FERC Order 2222 implementation filings, EPA AIM Act regulatory timelines, and utility time-of-use rate structure databases. Bottom-up installation project pipelines and top-down energy efficiency mandate penetration rates converge to establish market sizing boundaries.
Fixed assumptions across the analysis window include continued copper and steel commodity volatility within observed ranges, steady-state Title 24 compliance enforcement in California, and ERCOT real-time pricing event frequency at historical levels. Segmentation modeling spans product type, application intensity, end-user capital availability, and installation context. CAGRs derive from project backlog analysis and regulatory mandate adoption curves, with inputs from data center power density trajectories and building electrification ordinance expansion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified HVAC conglomerates would shift competitive economics. Macroeconomic deviation in construction activity, regulatory acceleration of refrigerant phase-down timelines, or breakthrough battery thermal storage cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market