
 North America Perforating Gun Market | 2026-2036
North America Perforating Gun Market Size, Share, and Industry Trends Forecast 2026-2036
North America Perforating Gun Market Analytics
Buyer concentration among supermajors and large independents is restructuring procurement dynamics across the North America Perforating Gun Market. Baker Hughes Company leverages integrated well-construction portfolios to bundle perforating services with logging and completion hardware. Schlumberger Limited anchors its position through proprietary shaped-charge design centers in Texas and Oklahoma. Halliburton Company competes via extensive rental fleets and field engineering density across the Permian and Eagle Ford.
North America perforating guns are explosive charge assemblies engineered to penetrate steel casing, cement sheaths, and formation rock at controlled depths using shaped charges with precise cone angles and liner metallurgy. These tools establish controlled flow paths between reservoir rock and wellbore, enabling hydrocarbon production from otherwise isolated zones. Cased hole systems dominate current revenue owing to their compatibility with horizontal completions in unconventional plays, while composite gun bodies represent the fastest-expanding product category as operators seek reduced debris and improved mill-out efficiency. Electrical firing technology leads deployment volumes, though hybrid ignition architectures are gaining traction in high-temperature downhole environments where mechanical backup prevents misfire risk.
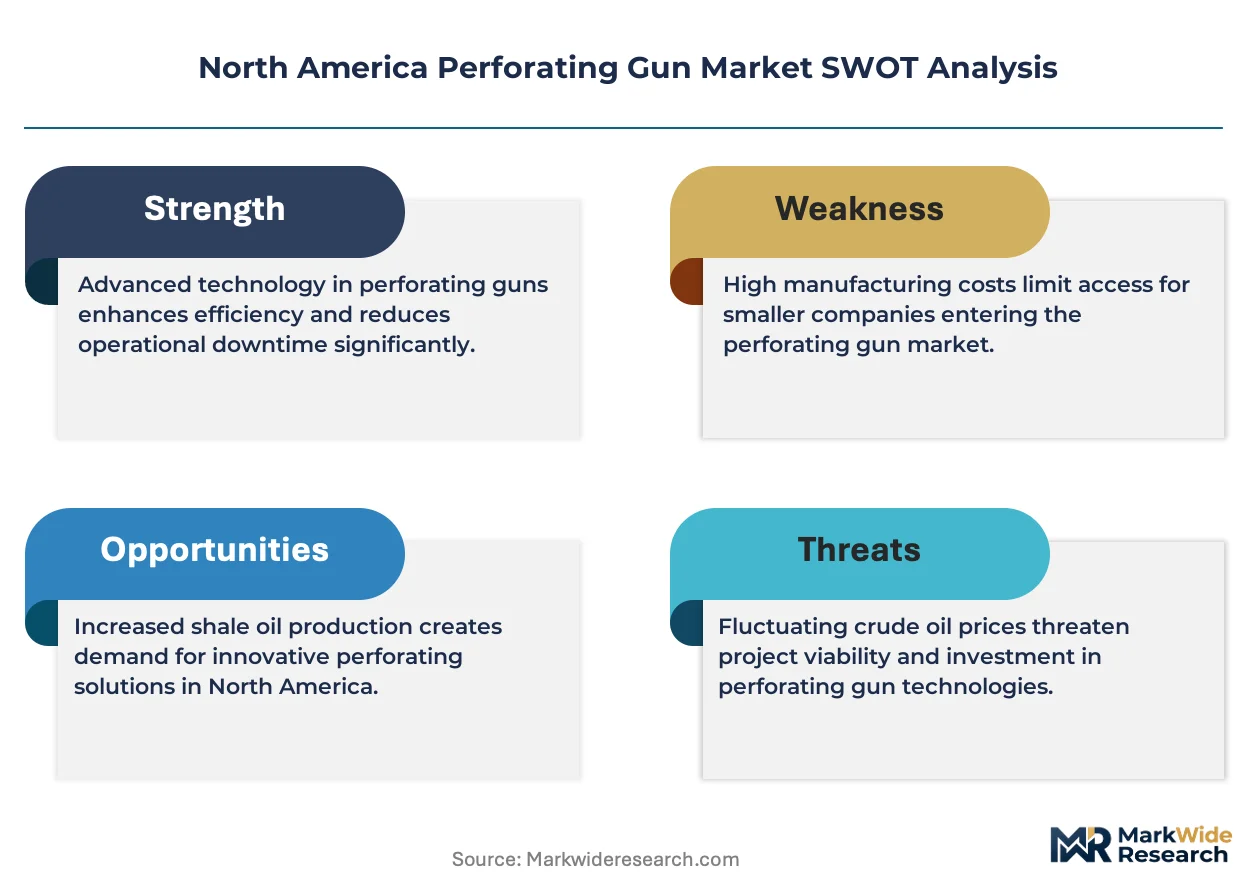
The US Bureau of Alcohol, Tobacco, Firearms and Explosives regulates explosive transport and storage, while API RP 19B governs perforator performance testing and reporting standards that determine product qualification for operator approval lists. Canada's Natural Resources Canada and provincial regulators enforce parallel certification pathways that vendors must navigate for cross-border market access. Stakeholders must monitor evolving state-level setback rules and flaring restrictions that directly alter well-spacing designs and perforation cluster counts.
Market Dynamics
Longer lateral completions in unconventional shale plays are restructuring procurement volumes and perforation cluster densities across the North America Perforating Gun Market. Operators now demand gun systems capable of 60-plus stage sequences in single runs, forcing suppliers to redesign charge carriers and ignition architectures.
Growth Catalysts
- API RP 19B Testing Mandates:Stricter perforation performance verification requirements are elevating demand for certified high-shot-density systems that demonstrate consistent penetration depth across variable formation hardness.
- Permian Basin Drilling Intensity:Delaware and Midland sub-basin operators are expanding horizontal well programs, directly lifting consumption of cased-hole perforating assemblies engineered for extended-reach laterals.
- Composite Gun Body Adoption:Lightweight non-metallic carriers are reducing post-perforation mill-out time, cutting completion costs for operators running plug-and-perf sequences in multi-well pads.
Market Restraints
- Explosive Raw Material Volatility:RDX and HMX precursor costs fluctuate with defense sector demand cycles, compressing margins for shaped-charge manufacturers without long-term chemical supply agreements.
- ATF Transport Licensing Bottlenecks:Interstate movement of classified explosive devices faces seasonal permit delays, constraining just-in-time delivery to remote Permian and Bakken drilling sites.
- High-Temperature Electronics Limitations:Conventional detonator circuits degrade above 400°F, excluding standard electrical firing systems from deep Gulf of Mexico and Haynesville high-pressure zones.
Strategic Opportunities
- New Mexico Delaware Sub-Basin Expansion:Lease consolidation and infrastructure buildout in Eddy and Lea counties are creating fresh demand nodes for perforating service providers beyond established Texas supply corridors.
- Hybrid Ignition Architecture Deployment:Dual-mode electrical-mechanical firing systems are opening penetration into high-temperature formations previously served by costlier wireline-conveyed perforating methods.
- Canadian Montney Shale Underpenetration:British Columbia and Alberta operators lag US peers in perforation intensity per lateral foot, representing latent demand for advanced charge configurations as LNG export capacity expands.
Industry Challenges
- Shaped-Charge Metallurgy Talent Scarcity:Precision liner fabrication requires specialized expertise in powder metallurgy and electroformed copper alloys that the aging workforce has not replenished at sufficient rates.
- Cross-Border Certification Complexity:Vendors seeking Canadian market access must duplicate testing protocols under Natural Resources Canada guidelines that diverge from US API standards, extending product qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Perforating Gun Market |
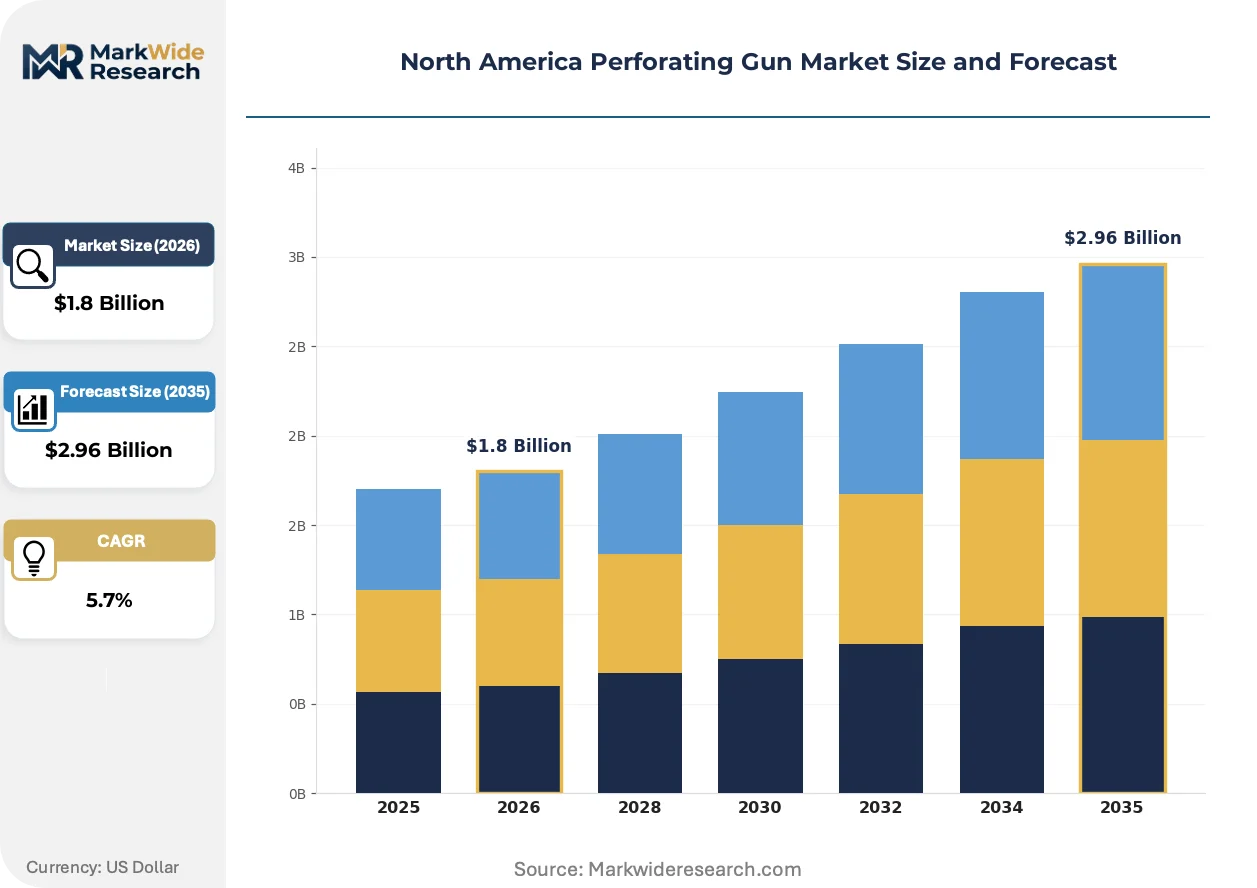
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cased Hole, Open Hole, Composite, Others Technology: Electrical, Mechanical, Hybrid, Chemical Delivery Mode: Land-based, Offshore, Subsea, Mobile End User: Oil & Gas Companies, Service Providers, Operators, Contractors |
| Companies Covered | Baker Hughes Company, Schlumberger Limited, Weatherford International plc, NOV Inc., Halliburton Company, DynaEnergetics, Hunting PLC, DMC Global Inc., Core Laboratories NV, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Perforating Gun Market Evolving Landscape
Perforating gun engineering is converging with downhole sensing and real-time diagnostics, transforming standalone explosive tools into intelligent completion system components. This integration is compressing operational uncertainty and enabling predictive maintenance models across unconventional drilling programs.
Automated perforation design software is automating charge placement optimization based on microseismic data and geomechanical models. E&P operators in the Permian and Eagle Ford are deploying these platforms to reduce engineering hours per well. The technology is automating what previously required manual cluster spacing adjustments, compressing pre-drill planning cycles from weeks to days.
The US EPA's methane emissions rules are tightening venting and flaring restrictions that directly alter well-spacing designs and perforation cluster counts. Operators must now demonstrate minimized fugitive emissions through optimized completion techniques. Cased-hole perforating systems with improved seal integrity are gaining preference in Texas and New Mexico as compliance documentation requirements expand.
Supermajor procurement departments are consolidating supplier rosters and demanding integrated perforating-to-completion service bundles. Large independents in the Delaware Basin are shifting from single-product tenders to multi-year framework agreements covering gun systems, wireline services, and charge replenishment. This concentration is most visible among Permian operators seeking simplified vendor management and volume-based pricing leverage.
North America Perforating Gun Market Segmentation
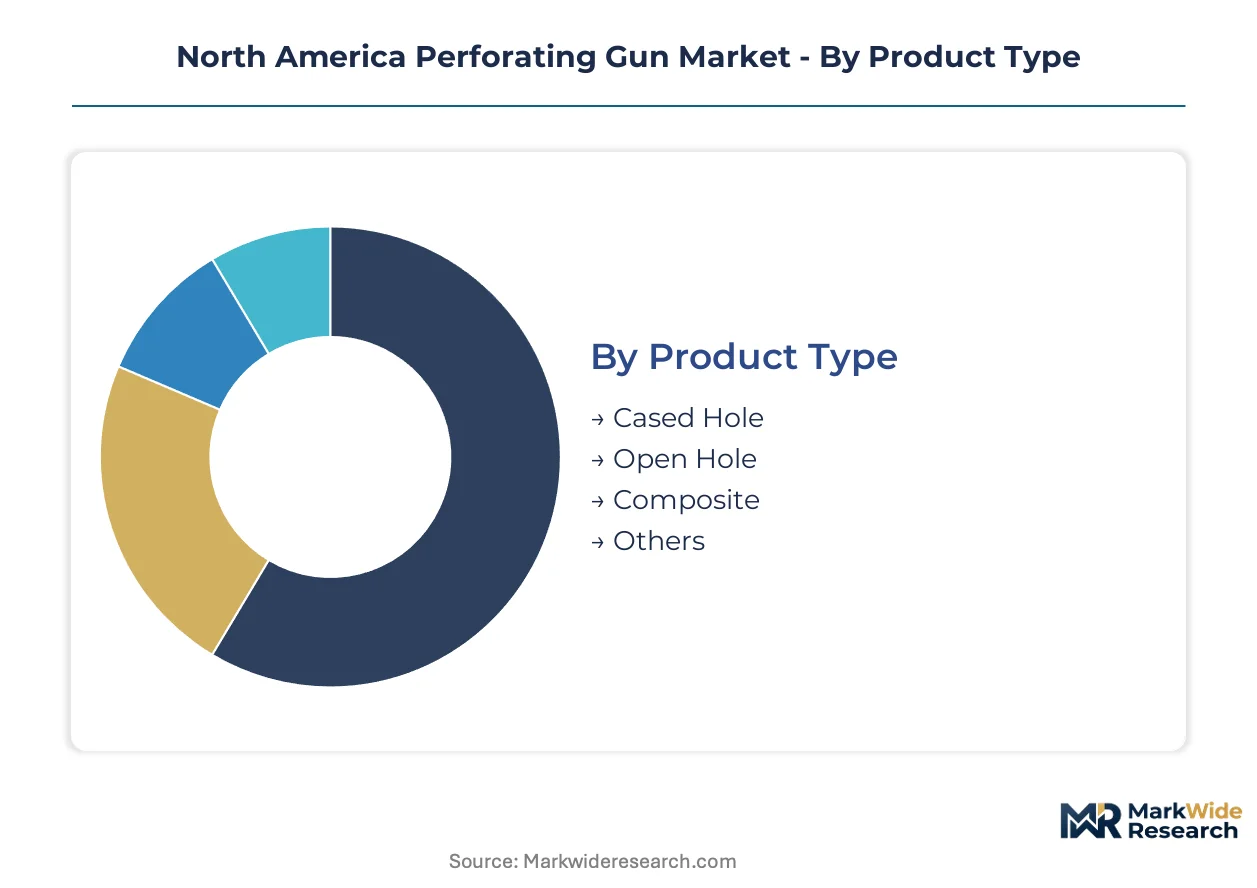
Perforating gun procurement decisions in North America hinge on well architecture, formation temperature, and completion economics. Each segmentation dimension captures distinct trade-offs between penetration performance, operational speed, and regulatory compliance across Permian, Eagle Ford, and Bakken drilling programs.
Product Type:
Buyers prioritize debris reduction and mill-out efficiency when selecting gun body materials for extended-reach laterals.
- Cased Hole:Steel-carrier assemblies designed for cemented casing penetration dominate unconventional shale completions. Delaware Basin operators specify these systems for 60-plus stage plug-and-perf sequences where seal integrity matters for methane compliance.
- Composite:Non-metallic gun bodies from fiberglass-reinforced polymers reduce post-perforation milling time by eliminating metallic debris. Permian multi-well pad operators are shifting procurement toward these systems to compress completion cycles.
- Open Hole:Bare-rock perforating configurations serve specific carbonate and sandstone completions where casing is absent. Applications concentrate in older Gulf of Mexico shelf wells and select Canadian conventional fields.
- Others:Specialty configurations including retrievable gun systems and modular charge carriers address niche through-tubing interventions.
Volume sits with Cased Hole; growth tilts toward Composite.
Technology:
Downhole temperature tolerance and misfire risk tolerance shape ignition system selection across formation depths.
- Electrical:Electronic detonator circuits provide precise timing control for multi-shot sequences. These systems dominate Permian and Eagle Ford land operations where bottom-hole temperatures stay below 350°F.
- Hybrid:Dual-mode electrical-mechanical architectures deploy mechanical backup firing when electronics risk thermal degradation. Haynesville and deep Gulf of Mexico operators specify these for high-pressure zones exceeding 400°F.
- Mechanical:Pressure-activated firing heads eliminate electrical components entirely. Applications persist in subsea completions where battery reliability concerns override precision timing needs.
- Chemical:Reactive pyrotechnic delays enable time-based firing without surface control lines. Limited deployment occurs in remote Alaska North Slope wells where wireline access is seasonal.
Electrical commands current procurement volumes; Hybrid is climbing the fastest as operators push into deeper, hotter formations.
Delivery Mode:
Logistics infrastructure density and water depth determine how gun systems reach the wellsite.
- Land-based:Truck-conveyed gun systems from regional supply yards serve Texas, New Mexico, and North Dakota drilling pads. ATF transport licensing bottlenecks constrain just-in-time delivery to remote Bakken locations.
- Offshore:Platform-stored perforating assemblies support Gulf of Mexico shelf operations. Helicopter-limited weight restrictions shape gun length and charge density specifications.
- Subsea:Riser-conveyed and horizontal tree-deployed systems address deepwater completions. Technical complexity limits this segment to supermajor-operated projects in US federal waters.
- Mobile:Self-contained offshore units mounted on dynamically positioned vessels serve exploratory drilling without permanent infrastructure. Atlantic Canada and Pacific Mexico frontier drilling drives sporadic demand.
Land-based absorbs the dominant share; Subsea offers the steepest expansion trajectory as deepwater sanctioning accelerates.
End User:
Procurement centralization versus decentralized field autonomy splits buying behavior across the value chain.
- Oil & Gas Companies:Supermajors and large independents negotiate multi-year framework agreements covering gun systems, wireline services, and charge replenishment. Permian operators particularly favor this consolidated vendor management approach.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes maintain captive perforating gun manufacturing and rental fleets. Their procurement of raw shaped charges and carrier components represents substantial upstream demand.
- Operators:Mid-size E&P firms with internal completion engineering teams purchase guns directly for self-executed plug-and-perf programs. This pattern concentrates in the Midland sub-basin among private equity-backed drillers.
- Contractors:Specialized wireline and perforating contractors serving marginal wells and workover markets rent guns on single-well terms. Fragmented demand across thousands of stripper wells characterizes this tier.
Service Providers hold the volume anchor; Operators are gaining share fastest as E&P firms internalize completion execution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Permian Basin's Delaware and Midland sub-basins, where operators deploy 60-plus stage perforating sequences in extended-reach laterals. Texas and New Mexico absorb the dominant procurement volumes, while Canadian shale plays and Mexican frontier drilling represent secondary expansion nodes.
United States
Permian Basin operators in Texas and New Mexico drive 70% of regional perforating gun consumption through multi-well pad development. The US EPA's methane emissions rules tighten venting restrictions, elevating demand for cased-hole systems with improved seal integrity. Midland and Eddy counties anchor manufacturing and service density, with supply yards clustered along Interstate 20 corridors.
Canada
Montney and Duvernay shale operators in British Columbia and Alberta lag US peers in perforation intensity per lateral foot. Natural Resources Canada enforces certification pathways that diverge from API standards, extending product qualification timelines for cross-border vendors. Calgary-based procurement offices coordinate field deployment across the Western Canadian Sedimentary Basin.
Mexico
Deepwater exploration in the Gulf of Mexico and onshore unconventional pilot programs in Burgos Basin create sporadic demand for subsea and land-based perforating systems. The National Hydrocarbons Commission regulates upstream contracting terms that shape service company market access. Ciudad del Carmen serves as the logistics hub for offshore supply chains.
Texas
Delaware and Midland sub-basin drilling intensity sustains the highest perforating gun utilization rates in North America. The Railroad Commission of Texas enforces well-spacing rules that directly alter perforation cluster counts and stage densities. Odessa and Midland host the densest concentrations of shaped-charge manufacturing and wireline service operations.
New Mexico
Lease consolidation in Eddy and Lea counties expands demand beyond established Texas supply corridors. The New Mexico Environment Department implements methane capture requirements that favor certified high-shot-density systems. Carlsbad and Hobbs anchor regional distribution networks serving multi-well pad completions.
North America Perforating Gun Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite gun body specialization and hybrid ignition architectures. The vendor base consolidates around three to four integrated service companies with captive manufacturing, while mid-size specialists compete on charge metallurgy and regional logistics density. Two archetypes dominate: full-service conglomerates bundling perforating with logging and completion hardware, and technology-focused independents advancing liner design and non-metallic carriers. Competitive moves center on multi-year framework agreements with supermajors and backward integration into explosive precursor supply.
Among Houston-based integrated service providers, Baker Hughes Company, Schlumberger Limited, and Halliburton Company exemplify the conglomerate archetype through captive perforating gun manufacturing and rental fleet operations. These entities anchor procurement relationships with Permian operators seeking bundled well-construction services. DynaEnergetics and Hunting PLC represent the specialized tier, with company names indicating focused explosive technology and precision manufacturing origins respectively.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Schlumberger Limited |
| Weatherford International plc |
| NOV Inc. |
| Halliburton Company |
| DynaEnergetics |
| Hunting PLC |
| DMC Global Inc. |
| Core Laboratories NV |
| Others |
Value Network & Pricing Analysis
RDX and HMX precursor costs flow from defense sector demand cycles through shaped-charge manufacturing tiers, compressing margins for vendors lacking long-term chemical supply agreements while elevating procurement premiums for certified high-shot-density systems.
Pricing Analysis
Volume concentrates in standard-tier cased-hole systems while margins accrue to composite gun bodies and hybrid ignition architectures. Price differentiation rests on API RP 19B certification status and perforation cluster density specifications. Cost compression in standard electrical firing systems is intensifying because raw explosive volatility and ATF transport licensing bottlenecks constrain just-in-time delivery. Supermajors and large independents exhibit lowest price sensitivity due to multi-year framework agreements, while specialized wireline contractors face acute margin pressure from single-well rental terms.
Supply Chain Analysis
Direct-to-operator channels handle supermajor and large independent demand, while regional distribution yards feed mid-size E&P and contractor tiers. Manufacturing concentrates in Texas, Oklahoma, and Alberta, drawing from copper alloy liner foundries and explosive precursor suppliers in the United States and Canada. Raw material dependencies include electroformed copper alloys, RDX/HMX energetic materials, and fiberglass-reinforced polymer composites. Single-source vulnerability in precision liner fabrication creates supply chain risk, as aging powder metallurgy expertise has not replenished at sufficient rates. Distribution runs through Interstate 20 corridors in Texas and rail networks serving Bakken and Montney drilling pads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Perforating Gun Market functions as a cost-of-compliance arena where US EPA methane emissions rules and API RP 19B testing mandates erect barrier-to-entry moats favoring vendors with established certification pathways and captive manufacturing infrastructure.
For Market Incumbents: Deploy backward integration into explosive precursor supply to defend against RDX and HMX cost volatility eroding shaped-charge margins. Expand hybrid ignition architecture R&D capacity in Oklahoma and Texas to capture high-temperature formation demand escaping standard electrical firing systems. Consolidate regional logistics density around Delaware Basin lease consolidation in Eddy and Lea counties before mid-size specialists establish distribution footholds. For New Entrants and Emerging Players: Enter via composite gun body specialization targeting Permian multi-well pad operators seeking reduced mill-out time and debris elimination. Target the Canadian Montney and Duvernay shale plays where perforation intensity per lateral foot lags US benchmarks and Natural Resources Canada certification complexity has delayed incumbent product qualification timelines. Pursue direct sales to private equity-backed Midland sub-basin drillers with internal completion engineering teams and fragmented incumbent relationships. For Investors and Strategic Acquirers: Multi-year framework agreement announcements between supermajors and integrated service providers is the leading indicator that procurement consolidation is accelerating and captive manufacturing assets are appreciating in strategic value. The five-to-ten-year viability window favors vendors with API RP 19B certification infrastructure and shaped-charge metallurgy expertise that cannot be replicated through capital deployment alone. Acquisition target archetype: mid-size specialists with proprietary liner design capabilities and established cross-border Canadian market access.| Strategic Initiative | Industry Significance |
|---|---|
| API RP 19B Certification Investment | EPA methane compliance requirements elevate certified system premiums in Texas and New Mexico procurement. |
| Composite Gun Body Manufacturing Scale-Up | Permian pad drilling economics reward debris-reduction technology with faster completion cycle times. |
| Hybrid Ignition Architecture Development | Haynesville and deep Gulf of Mexico high-pressure zones exclude conventional electrical firing systems. |
| Explosive Precursor Supply Agreement | Defense sector demand cycles for RDX and HMX compress margins without long-term chemical supply contracts. |
| Canadian Market Access Expansion | Natural Resources Canada certification divergence creates 8-14 month qualification delays for unprepared vendors. |
Research Methodology
Independent corroboration across API RP 19B test facility operators, shaped-charge manufacturing technical directors, and Permian Basin completion engineering teams underwrites the qualitative findings. Primary interviews with supermajor procurement officers, large independent drilling managers, wireline service company executives, and ATF-licensed explosive transport logistics coordinators combined with secondary validation from US EPA regulatory filings, Railroad Commission of Texas drilling permit databases, and Natural Resources Canada certification records. Bottom-up rig-count and stage-density data triangulated against top-down vendor revenue segmentation across the analysis window.
Rate-of-change decomposition separates volume growth from price realization across gun body material tiers, ignition technology generations, and delivery mode categories. Segmentation dimensions modeled include well architecture type, formation temperature tolerance, logistics infrastructure density, and buyer procurement centralization level. CAGRs derived from rig-count trajectories, lateral length extension curves, and stage density intensification patterns in Delaware and Midland sub-basins. Industry-specific forecast inputs incorporate ATF transport licensing approval timelines and state-level methane capture requirement implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under defense sector RDX/HMX demand spikes or accelerated EPA methane rule enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Sand Control Screens Market
Oil & Gas
Oilfield Services Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Dissolvable Frac Plug Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Turkmenistan Oil and Gas Market