
 North Sea Oilfield Equipment Market | 2026-2036
North Sea Oilfield Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North Sea Oilfield Equipment Market Analytics
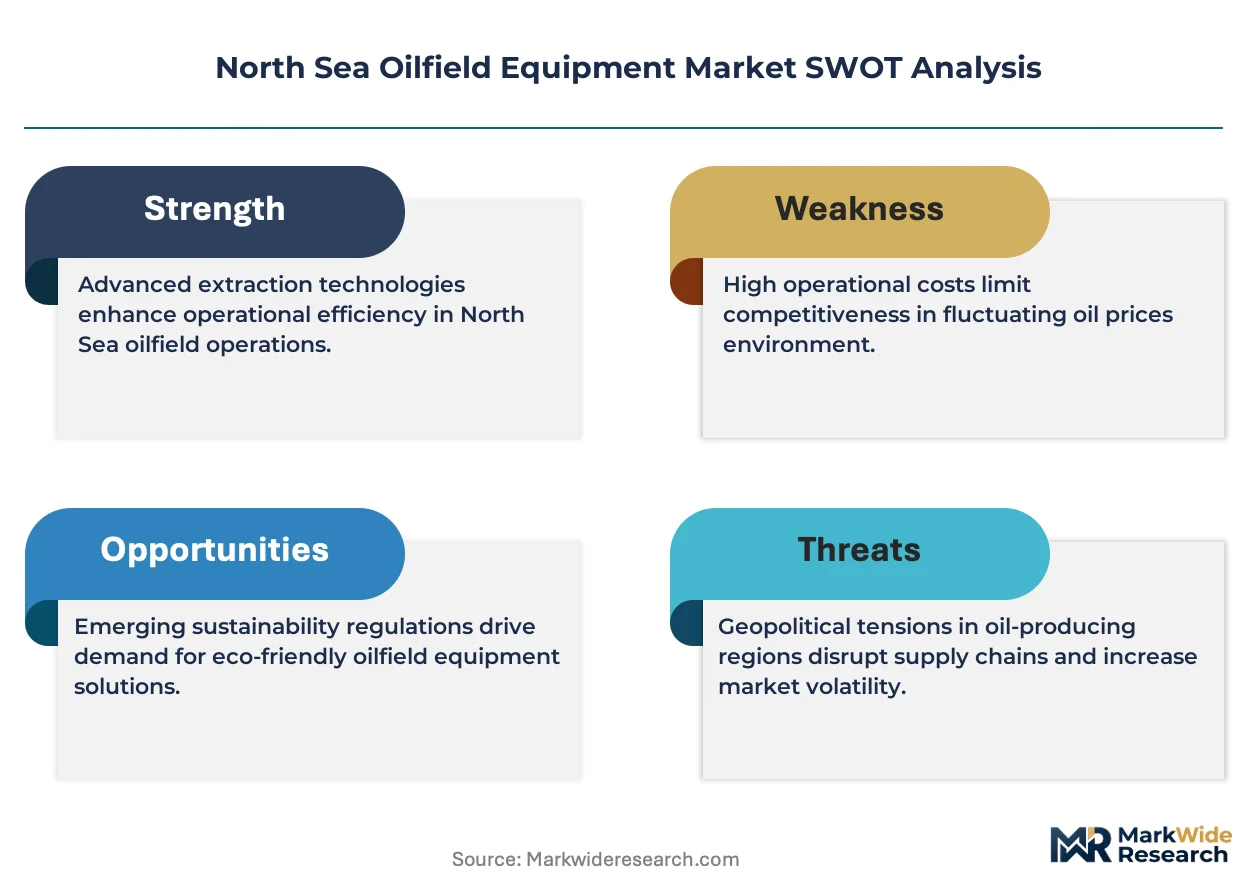
Buyer concentration among North Sea operators is decoupling from historical patterns as national oil companies and private equity-backed independents fragment procurement across more vendors. Schlumberger Ltd anchors its position through integrated drilling and evaluation portfolios tailored to high-pressure formations. Baker Hughes Company differentiates via turbomachinery and digital monitoring systems deployed across Norwegian and UK assets.
North Sea oilfield equipment comprises engineered systems designed to extract, process, and transport hydrocarbons from offshore reservoirs operating at water depths exceeding 100 meters and pressures above 10,000 psi. Subsea Systems command the deepest technical barriers and longest replacement cycles among Equipment Type categories, while Blowout Preventers face accelerated upgrade schedules driven by post-Macondo safety protocols. Enhanced Oil Recovery technology within the Technology dimension captures expanding capital allocation as operators target recovery factors above 50 percent in maturing UK and Norwegian fields.
The Norwegian Petroleum Safety Authority and the UK Health and Safety Executive enforce equipment certification regimes that directly shape supplier qualification timelines and product design standards. EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing compressor and refrigeration system redesigns across the Norwegian Continental Shelf. Stakeholders must monitor how UK decommissioning cost estimates and Norwegian tax depreciation rules reshape replacement-versus-repair economics for aging platform infrastructure.
Market Dynamics
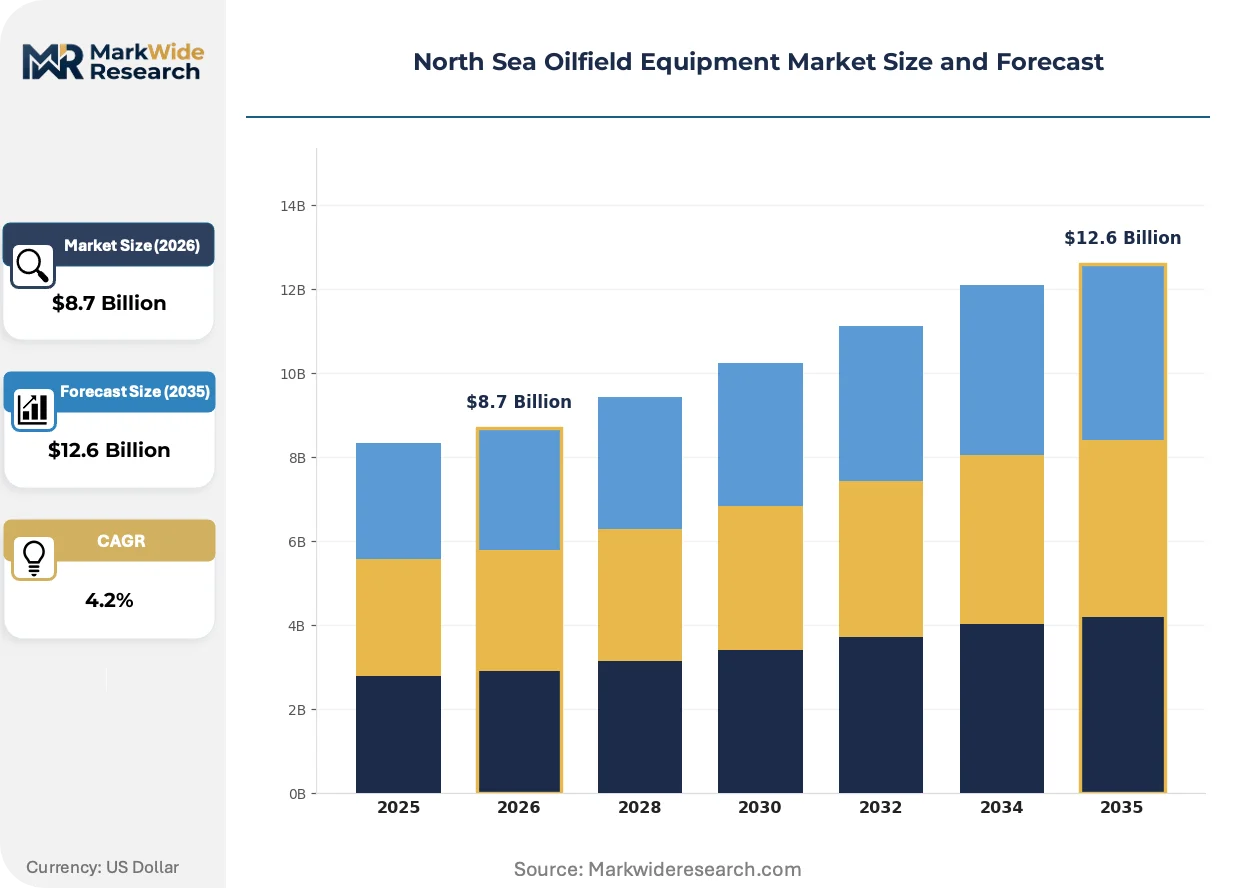
The North Sea oilfield equipment market is compressing replacement cycles as maturing reservoirs force operators to choose between decommissioning commitments and enhanced recovery investments. The EU F-Gas Regulation and Norwegian tax depreciation rules are rewriting capital allocation timelines across the UK and Norwegian Continental Shelves.
Growth Catalysts
- Subsea tieback proliferation:Exploration and production companies in mature basins are expanding procurement of subsea tieback systems to connect satellite fields to existing infrastructure, bypassing the capital intensity of new platform construction.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases are forcing compressor and refrigeration system redesigns, accelerating equipment replacement schedules across the Norwegian Continental Shelf.
- Johan Sverdrup cluster concentration:Norway's largest producing field complex is driving concentrated demand for high-pressure drilling and evaluation equipment, anchoring supplier qualification investments.
Market Restraints
- Specialized steel alloy volatility:Input cost fluctuations for chromium-molybdenum steels used in blowout preventer manufacturing compress margin predictability for forged component suppliers.
- Supplier concentration in Aberdeen:Subsea umbilical and riser fabrication capacity clusters disproportionately in northeast Scotland, creating geographic vulnerability to North Sea weather disruptions and labor actions.
- Post-Macondo certification drag:UK Health and Safety Executive and Norwegian Petroleum Safety Authority equipment recertification timelines extend procurement cycles for safety-critical systems beyond operational planning horizons.
Strategic Opportunities
- UK Central Graben brownfield expansion:Underpenetrated reservoir compartments in the UK sector offer white space for enhanced oil recovery technology deployment targeting recovery factors above 50 percent.
- Electrification infrastructure convergence:Integration of subsea power distribution with digital monitoring systems creates bundled offering potential for suppliers with turbomachinery and automation capabilities.
- Decommissioning mandate tailwinds:UK and Norwegian national decommissioning mandates are generating demand for plug and abandonment equipment, cutting tools, and platform removal services as operators face legal deadlines.
Industry Challenges
- Subsea robotics technician scarcity:The specialized skill set required for remotely operated vehicle operations and autonomous underwater system maintenance outpaces vocational training pipeline output in Aberdeen and Stavanger.
- Legacy platform integration complexity:New digital monitoring systems face protocol incompatibility with 1980s-era supervisory control and data acquisition architectures on aging UK Central North Sea installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Sea Oilfield Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Drilling Rigs, Blowout Preventers, Production Platforms, Subsea Systems Component: Pipes, Valves, Pumps, Compressors Technology: Exploration Technology, Enhanced Oil Recovery, Automation Solutions, Monitoring Systems End User: Oil Producers, Service Companies, Contractors, Government Agencies |
| Companies Covered | Schlumberger Ltd, Halliburton Company, Baker Hughes Company, Weatherford International plc, Tenaris S.A., TechnipFMC plc, Aker Solutions ASA, Subsea 7 S.A., NOV Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Sea Oilfield Equipment Market Evolving Landscape
Digitalization and electrification are converging to compress the technical boundaries between subsea production systems and surface facility automation. Equipment suppliers are repositioning around integrated lifecycle service models that bundle hardware with predictive analytics.
All-electric subsea actuation systems are rewriting the technical economics of deepwater field development. Norwegian operators at Johan Sverdrup and nearby clusters are adopting these systems to eliminate hydraulic fluid infrastructure and reduce topside footprint. The technology is compressing subsea facility capital intensity while extending operational depth ratings beyond 3,000 meters.
The EU F-Gas Regulation is mandating refrigerant transitions in offshore compression trains. Equipment manufacturers serving the Norwegian Continental Shelf are redesigning turbomachinery sealing systems to accommodate lower-global-warming-potential working fluids. Subsea compression projects in the Ormen Lange area are piloting these reconfigured systems under accelerated regulatory timelines.
Buyer concentration patterns are fragmenting as private equity-backed independents and national oil companies decouple from historical integrated procurement relationships. National oil companies in Norway and UK independents are unbundling drilling, evaluation, and production equipment contracts, creating entry points for specialized vendors. This pattern is most visible in the UK Central Graben, where operator portfolio turnover has disrupted legacy supplier lock-in.
North Sea Oilfield Equipment Market Segmentation
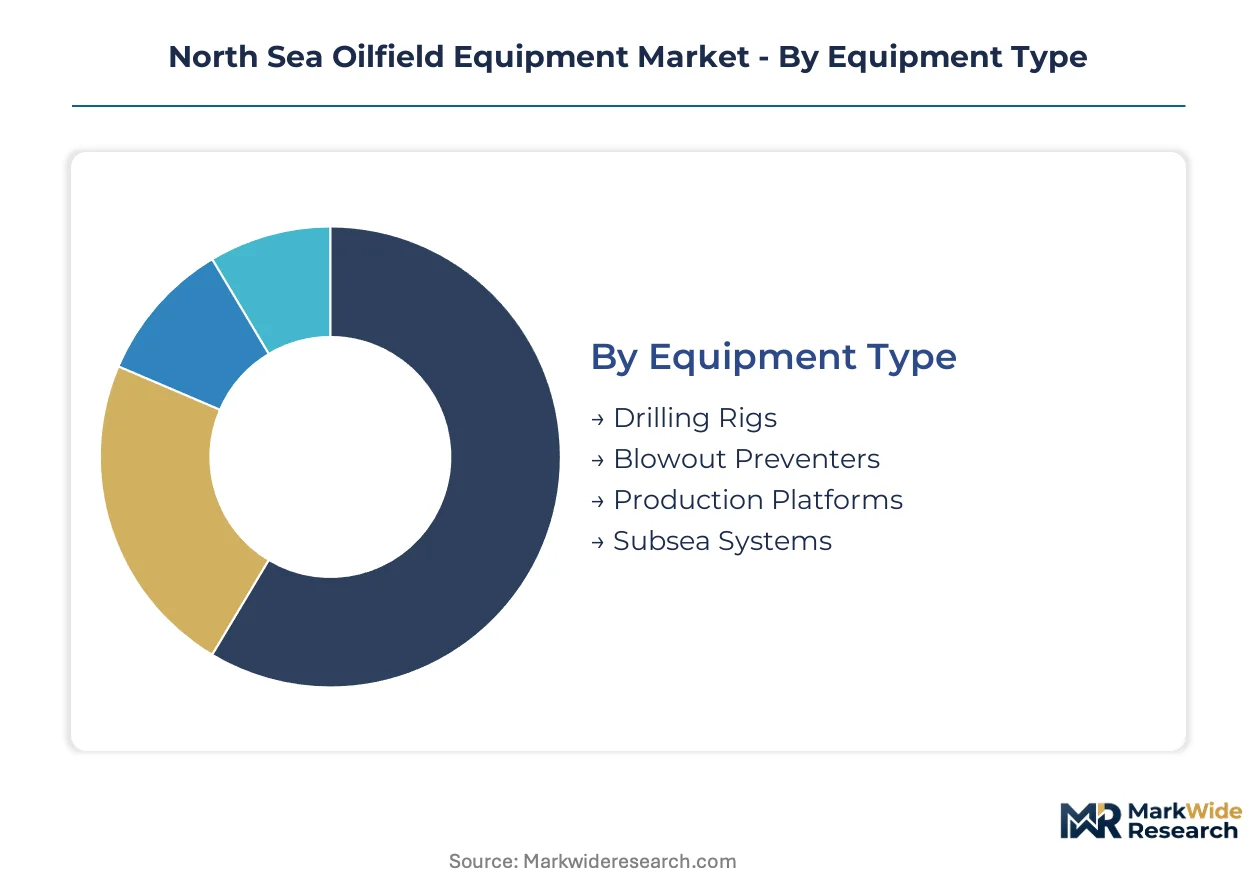
North Sea oilfield equipment procurement splits across technical, commercial, and regulatory dimensions. Each segmentation layer carries distinct certification burdens from the Norwegian Petroleum Safety Authority and UK Health and Safety Executive.
Equipment Type:
Equipment certification timelines vary sharply across this category. Subsea Systems face the longest qualification cycles due to pressure-rating requirements, while Blowout Preventers operate under accelerated recertification mandates post-Macondo.
- Subsea Systems:Engineered for water depths exceeding 100 meters and pressures above 10,000 psi. Demand concentrates in Norway's Johan Sverdrup cluster as operators deploy tieback architectures to avoid new platform construction. The Norwegian Petroleum Safety Authority enforces extended factory acceptance testing for these systems.
- Blowout Preventers:Forged chromium-molybdenum steel assemblies rated for high-pressure containment. UK Central Graben operators are replacing legacy stacks under tightened UK Health and Safety Executive protocols. Specialized alloy input costs compress margin predictability for component suppliers.
- Drilling Rigs:Jack-up and semi-submersible units adapted to North Sea weather windows.
- Production Platforms:Fixed and floating facilities facing decommissioning mandate deadlines in UK and Norwegian waters.
Leading the category by volume: Subsea Systems. Growing fastest: Blowout Preventers.
Component:
Component procurement patterns track field maturity curves. Pipes and Valves dominate replacement spending in aging UK Central North Sea infrastructure, while Compressors absorb capital under EU F-Gas refrigerant transition mandates.
- Compressors:Turbomachinery systems undergoing redesign for lower-global-warming-potential working fluids. Norwegian Continental Shelf projects in the Ormen Lange area pilot reconfigured sealing systems under accelerated regulatory timelines.
- Pipes:Subsea umbilical and riser fabrication capacity clusters disproportionately in northeast Scotland. Aberdeen-based suppliers face geographic vulnerability to North Sea weather disruptions and labor actions.
- Valves:High-pressure isolation and control equipment for subsea manifolds.
- Pumps:Artificial lift and injection systems for enhanced recovery applications.
Compressors command the steepest expansion trajectory as refrigerant transitions force replacement cycles. Pipes anchor current procurement volumes.
Technology:
Technology adoption splits between reservoir characterization and operational efficiency plays. Enhanced Oil Recovery captures capital as operators target recovery factors above 50 percent, while Automation Solutions face integration barriers against 1980s-era platform architectures.
- Enhanced Oil Recovery:Thermal, chemical, and gas injection methods for maturing reservoirs. UK Central Graben brownfield compartments offer white space for deployment targeting stranded hydrocarbon volumes. National decommissioning mandates create tension between recovery investment and abandonment timelines.
- Automation Solutions:Digital monitoring and control systems bundled with turbomachinery offerings. Legacy platform integration complexity limits retrofit penetration on aging UK installations with incompatible supervisory control architectures.
- Exploration Technology:Seismic imaging and reservoir characterization for new prospect evaluation.
- Monitoring Systems:Predictive analytics platforms repositioning suppliers around lifecycle service models.
Enhanced Oil Recovery leads technology investment by value. Automation Solutions are climbing the fastest as electrification converges with subsea power distribution.
End User:
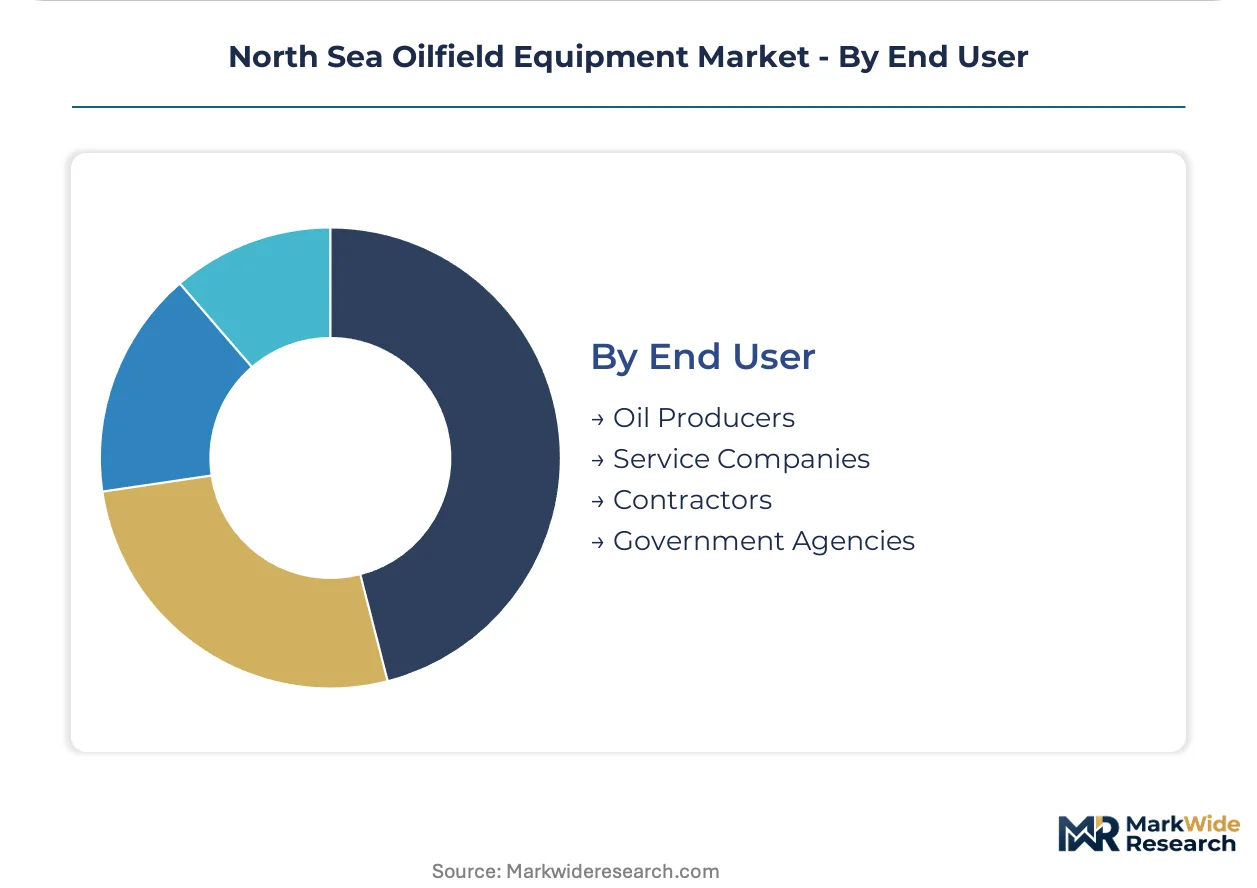
End user procurement authority is fragmenting as national oil companies and private equity-backed independents unbundle historical integrated contracts. Oil Producers retain largest capital allocation discretion, while Government Agencies shape economics through tax depreciation and decommissioning liability frameworks.
- Oil Producers:Exploration and production companies operating UK and Norwegian Continental Shelf assets. Johan Sverdrup cluster operators anchor concentrated demand for high-pressure drilling and evaluation equipment. Private equity portfolio turnover in the UK Central Graben disrupts legacy supplier relationships.
- Government Agencies:Norwegian tax depreciation rules and UK decommissioning cost estimates reshape replacement-versus-repair economics. The Norwegian Petroleum Safety Authority and UK Health and Safety Executive enforcement actions directly shape supplier qualification timelines.
- Service Companies:Drilling, completion, and intervention contractors managing equipment logistics.
- Contractors:Construction and installation firms executing platform and subsea infrastructure projects.
Oil Producers dominate procurement volume. Government Agencies are gaining influence fastest through regulatory and fiscal mechanism redesign.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromium-molybdenum steel foundries in Sheffield and Stavanger anchor fabrication capacity for pressure-rated subsea components. Norwegian Continental Shelf operators source forged alloys through North Sea supply chains. Aberdeen-based umbilical manufacturers face weather-driven logistics constraints.
Norway
Johan Sverdrup cluster operators anchor concentrated demand for high-pressure drilling systems. The Norwegian Petroleum Safety Authority enforces extended factory acceptance testing for subsea tieback architectures. Stavanger hosts fabrication yards supplying electrified subsea actuation systems to Ormen Lange compression projects.
United Kingdom
UK Central Graben brownfield compartments drive enhanced oil recovery equipment procurement. The UK Health and Safety Executive mandates accelerated blowout preventer recertification under post-Macondo protocols. Aberdeen concentrates subsea umbilical and riser fabrication capacity vulnerable to North Sea weather disruptions.
Germany
Ruhr Valley steel producers supply specialized chromium-molybdenum alloys for forged blowout preventer components. EU F-Gas Regulation restrictions force compressor redesigns for lower-global-warming-potential refrigerants. Hamburg-based turbomachinery specialists serve Norwegian Continental Shelf electrification projects.
Netherlands
Rotterdam port infrastructure handles heavy subsea module logistics for North Sea field developments. REACH chemical regulations shape polymer compound specifications for subsea insulation systems. Eindhoven-region automation specialists integrate digital monitoring with legacy platform architectures.
North Sea Oilfield Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and digital monitoring adjacencies. The supplier base fragments across integrated service portfolios and specialized component fabricators. Three archetypes dominate: full-service contractors bundling drilling and subsea systems, turbomachinery specialists pivoting toward electrification, and forged-component suppliers managing alloy cost volatility. Competitive moves center on qualification investments for high-pressure certifications and backward integration into specialized steel supply.
Among US-based integrated service providers, Schlumberger Ltd and Halliburton Company exemplify full-service archetypes spanning drilling evaluation and production systems. Baker Hughes Company represents the turbomachinery-digital convergence vector. These three occupy positions shaped by Norwegian Petroleum Safety Authority qualification timelines and UK Health and Safety Executive certification requirements rather than scale advantages alone.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| Tenaris S.A. |
| TechnipFMC plc |
| Aker Solutions ASA |
| Subsea 7 S.A. |
| NOV Inc. |
| Others |
Value Network & Pricing Analysis
Captive forging operations at Sheffield and Stavanger foundries anchor supply positions for pressure-rated subsea components while simultaneously determining pricing power through alloy cost pass-through mechanisms. Norwegian Continental Shelf operators source chromium-molybdenum steels through these vertically integrated channels, compressing margin flexibility for independent fabricators lacking upstream metal control.
Pricing Analysis
Extended warranty and lifecycle service bundling separate premium-tier suppliers from unbundled equipment vendors in this market. Project-based contracting dominates, with price differentiation tracking certification grade from the Norwegian Petroleum Safety Authority and customization depth for high-pressure formations. Cost compression in standard-grade blowout preventers is intensifying because of specialized steel alloy volatility. Private equity-backed independents in the UK Central Graben exhibit highest price sensitivity, while Johan Sverdrup cluster operators prioritize qualification reliability over unit cost.
Supply Chain Analysis
Subsea robotics technician scarcity in Aberdeen and Stavanger constrains fabrication throughput for umbilical and riser systems. Manufacturing gravity centers on the United Kingdom, Norway, and Germany, with Sheffield foundries and Ruhr Valley steel mills feeding component production. The supply chain draws from chromium-molybdenum alloys, high-pressure sealing polymers, and electrical actuation systems. Single-source vulnerability clusters in northeast Scotland, where weather disruptions interrupt logistics. Distribution runs through Rotterdam port infrastructure and specialized heavy-lift vessel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance costs and post-Macondo certification burdens are forcing subscale fabricators toward exit or acquisition, consolidating viable supplier positions around qualified integrated service providers.
For Market Incumbents: Lock in Norwegian Petroleum Safety Authority qualification timelines for subsea tieback systems before competitor recertification investments mature. Backward integration into Sheffield or Stavanger forging capacity secures alloy cost control against spot market volatility. Digital monitoring bundling with turbomachinery creates switching costs that defend margin position against emerging electrification specialists. For New Entrants and Emerging Players: Enter via UK Central Graben brownfield compartments where private equity portfolio turnover has disrupted legacy supplier relationships. Electrification infrastructure convergence between subsea power distribution and automation systems offers the most penetrable white space. Target qualification-light monitoring retrofits for 1980s-era platforms as the initial go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap turbomachinery specialists with Norwegian Continental Shelf certification credentials and digital monitoring IP. Long-term viability favors suppliers with captive alloy supply and bundled lifecycle service models. Watch Johan Sverdrup cluster capital allocation shifts as the inflection signal for subsea systems demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Sheffield and Stavanger alloy control neutralizes chromium-molybdenum price volatility for blowout preventer margins. |
| EU F-Gas Refrigerant Transition | Ormen Lange compression pilots validate lower-global-warming-potential sealing systems for Norwegian Continental Shelf deployment. |
| All-Electric Subsea Actuation | Johan Sverdrup cluster adoption eliminates hydraulic infrastructure and extends depth ratings beyond 3,000 meters. |
| Lifecycle Service Model Bundling | Predictive analytics integration with turbomachinery creates recurring revenue streams and platform switching costs. |
| UK Central Graben Brownfield Expansion | Enhanced oil recovery targeting recovery factors above 50 percent captures stranded hydrocarbons before decommissioning deadlines. |
Research Methodology
Trade flow databases, EU regulatory filings, and Norwegian Petroleum Directorate production reports formed the secondary backbone for market sizing. Primary interviews with subsea project engineers, procurement leads at UK and Norwegian operators, turbomachinery R&D directors, and Health and Safety Executive certification officers validated equipment replacement timelines and qualification burdens. Bottom-up equipment unit economics and top-down field development capex triangulation anchored volume estimates.
Historical field sanctioning patterns and equipment procurement cycles established baseline trendlines across the projection horizon. Segmentation modeling captured equipment type, component category, technology adoption stage, and end-user procurement authority dimensions. CAGRs were derived from regression analysis against reservoir depletion curves and regulatory mandate implementation schedules. Forecast inputs incorporated Johan Sverdrup cluster development phasing and UK decommissioning liability timelines.
Revisions become necessary when Norwegian tax depreciation rules shift replacement-versus-repair economics, UK Health and Safety Executive mandates accelerate blowout preventer recertification, or EU F-Gas Regulation timelines compress compressor redesign windows. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Smart Well Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
South and Central America Oil Field Services Market