
 Energy Storage Sodium Ion Battery Market | 2026-2036
Energy Storage Sodium Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Storage Sodium Ion Battery Market Insights
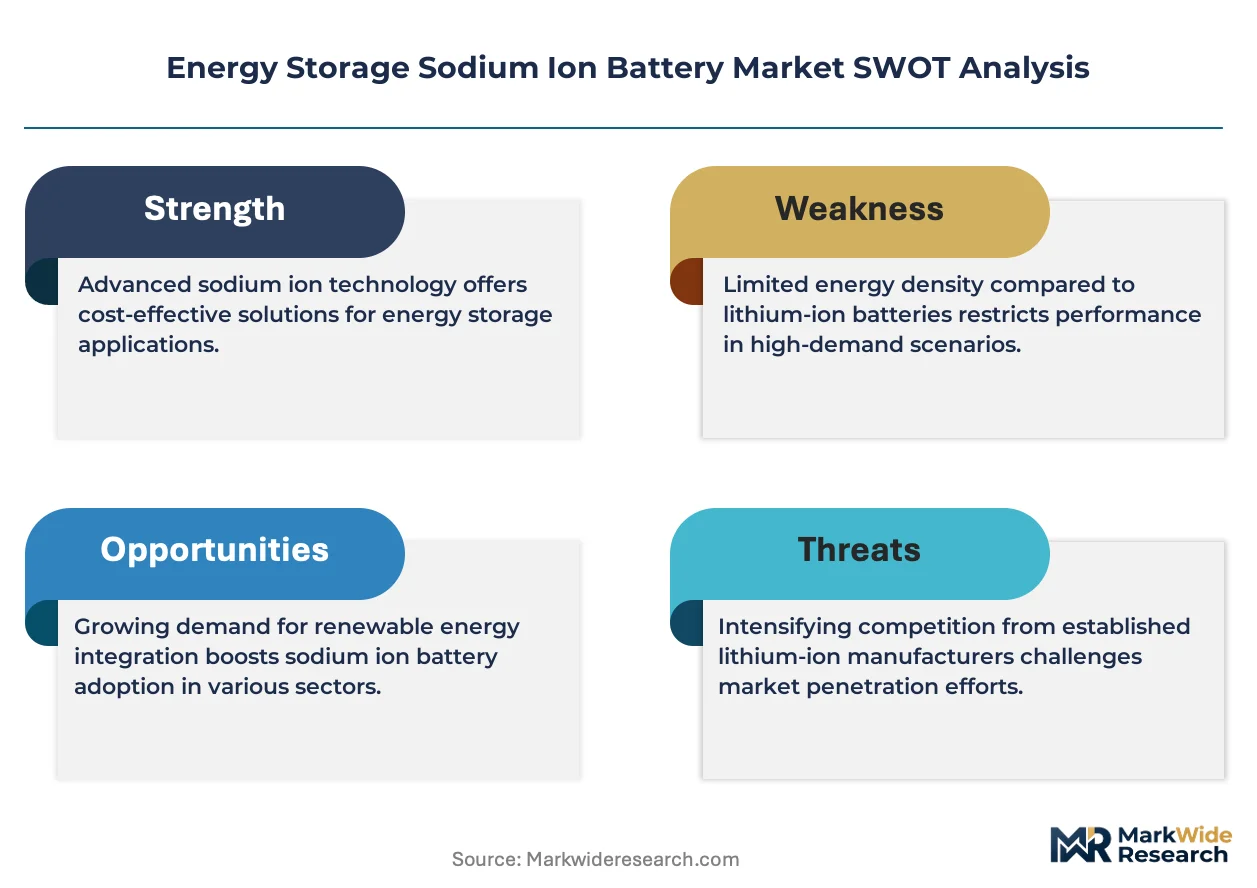
Electrochemical engineering talent is collapsing across European and North American battery corridors as sodium-ion chemistry diverges from established lithium-ion expertise. Contemporary Amperex Technology dominates prismatic cell manufacturing at scale in Ningde, leveraging proprietary layered oxide cathode formulations. HiNa Battery Technology anchors China's aqueous electrolyte segment through partnerships with state grid operators. Faradion competes in UK-India technology licensing, sustaining R&D intensity through joint ventures with NGK Insulators.
Energy storage sodium ion batteries employ sodium ions as charge carriers between hard carbon anodes and transition metal oxide cathodes, achieving energy densities of 100-160 Wh/kg with operating temperatures spanning -20°C to 60°C. Prismatic formats lead utility-scale deployments due to superior thermal management and pack-level energy density, while cylindrical designs occupy telecom infrastructure applications where mechanical robustness matters. Aqueous electrolyte technology differentiates through intrinsic fire safety, positioning it for data center backup power where thermal runaway tolerance shapes procurement criteria. Solid-state variants remain pre-commercial but attract venture funding from Peak Energy and Natron Energy.
China's MIIT governs sodium-ion battery GB standards development, while the EU Green Deal's critical raw materials taxonomy shapes import preferences for chemistries reducing lithium dependency. India's PLI scheme for advanced chemistry cells now explicitly includes sodium-ion eligibility, redirecting capacity investments from Jiangsu Zhongna Energy Technology toward Gujarat manufacturing zones. Stakeholders must monitor cathode material patent thickets between Faradion and Altris, as intellectual property positioning will determine technology licensing economics before mass commercialization.
Market Dynamics
Lithium supply constraints and China's MIIT sodium-ion GB standards are accelerating chemistry diversification across utility-scale storage procurement, redirecting engineering talent and capital toward abundant sodium feedstocks.
Growth Catalysts
- EU Green Deal critical raw materials taxonomy:Import preferences now explicitly favor chemistries reducing lithium dependency, reshaping European utility procurement criteria toward sodium-ion eligibility.
- Grid-scale renewable integration:China's state grid operators are accelerating sodium-ion system deployment to buffer intermittency from wind and solar assets in Jiangsu and Anhui provinces.
- Aqueous electrolyte fire safety:Data center operators are specifying intrinsic thermal runaway tolerance for backup power, bypassing lithium-ion cooling infrastructure requirements.
Market Restraints
- Hard carbon anode supply concentration:Biomass precursor sourcing clusters in Southeast Asia, creating feedstock bottleneck risk for scaled manufacturing.
- Energy density ceiling:Sodium-ion systems top out at 160 Wh/kg versus lithium iron phosphate, limiting premium automotive and aerospace applications.
- Patent thickets:Faradion and Altris layered oxide cathode IP disputes are complicating technology licensing economics before mass commercialization.
Strategic Opportunities
- India PLI scheme expansion:Advanced chemistry cell eligibility now includes sodium-ion, redirecting Jiangsu Zhongna Energy Technology capacity investments toward Gujarat manufacturing zones.
- Solid-state electrolyte convergence:Pre-commercial variants attracting venture funding from Peak Energy and Natron Energy for next-generation safety performance.
- Telecom infrastructure cylindrical formats:Mechanical robustness requirements in remote base station deployments favor sodium-ion over lithium-ion thermal management complexity.
Industry Challenges
- Electrochemical engineering talent collapse:European and North American battery corridors face expertise gaps as sodium-ion chemistry diverges from established lithium-ion manufacturing protocols.
- Certification timeline compression:China's GB standards development lags pilot production scale, creating regulatory uncertainty for export-bound manufacturers.
- Pack-level integration complexity:Battery management system redesign requirements for sodium-ion voltage profiles delay retrofit compatibility with existing lithium-ion infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Storage Sodium Ion Battery Market |
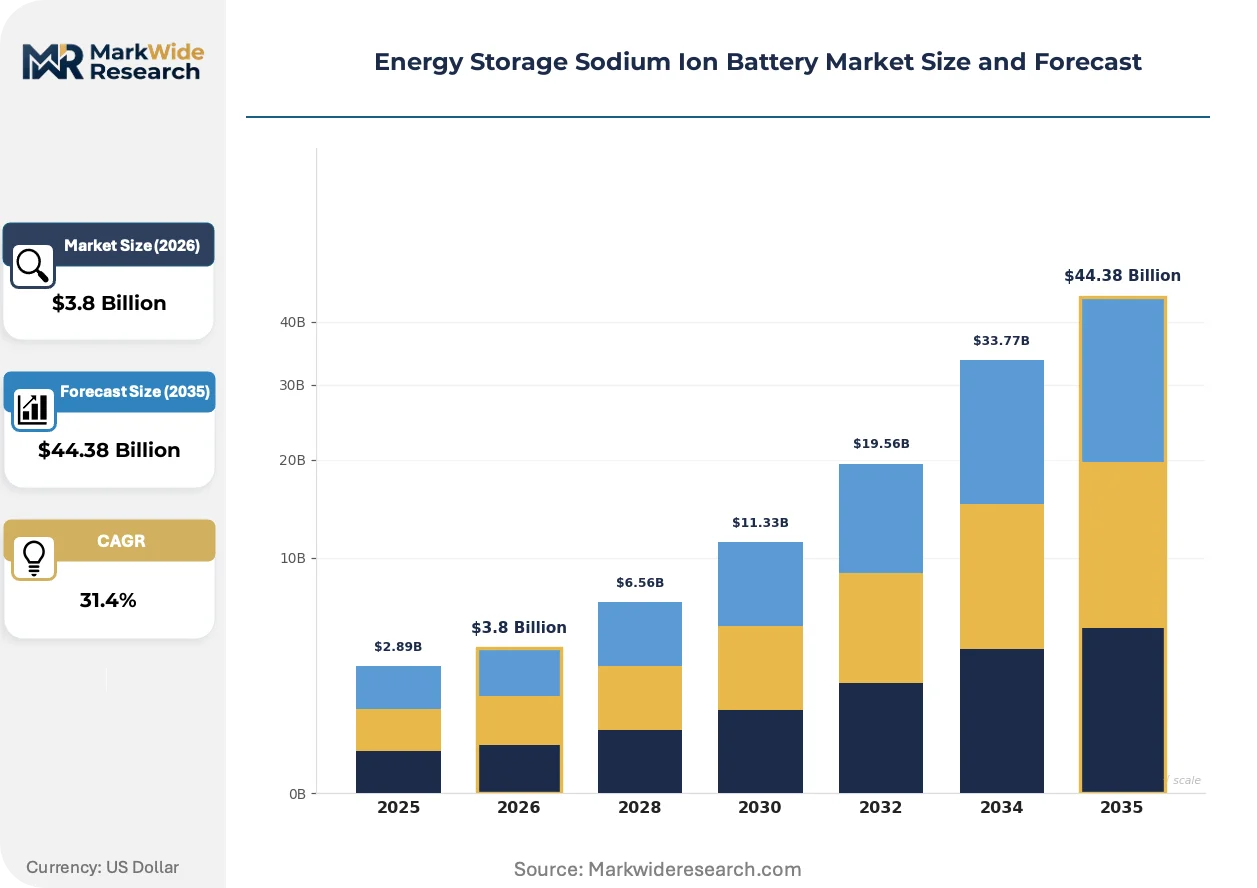
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $44.38 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Prismatic, Cylindrical, Pouch, Sheet Application: Grid Stabilization, Renewable Integration, Backup Power, Electric Mobility, Telecom Infrastructure Technology: Solid-State, Aqueous Electrolyte, Polymer Electrolyte, Glass Electrolyte End User: Utility Operators, Data Centers, Public Transport Providers, Residential Complexes |
| Companies Covered | Contemporary Amperex Technology, HiNa Battery Technology, Faradion, Natron Energy, TIAMAT Energy, Altris, Jiangsu Zhongna Energy Technology, NGK Insulators, Peak Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Storage Sodium Ion Battery Market Trends and Innovations
Layered oxide cathode formulations and aqueous electrolyte architectures are actively reshaping competitive positioning, while regulatory frameworks accelerate chemistry-specific procurement mandates across major storage markets.
Hard carbon anodes derived from biomass precursors are supplanting synthetic graphite in utility-scale sodium-ion cell production. State grid operators in China are adopting prismatic formats at commercial scale for superior thermal management. This chemistry transition is compressing lithium carbonate demand elasticity in stationary storage applications.
REACH and EU Green Deal critical raw materials taxonomy are mandating supply chain due diligence for battery chemistries. Industrial consequence includes explicit import preference shifts toward sodium-based systems in European utility tenders. Grid-scale developers in Germany and Spain are restructuring supplier qualification criteria to satisfy compliance thresholds.
Buyer preference is rotating toward chemistry-agnostic performance contracting in long-duration storage procurement. Traditional equipment sales models face displacement from availability-guaranteed service agreements. This pattern concentrates in Nordic markets where wind asset operators prioritize operational risk transfer over capital ownership.
Energy Storage Sodium Ion Battery Market Segmentation
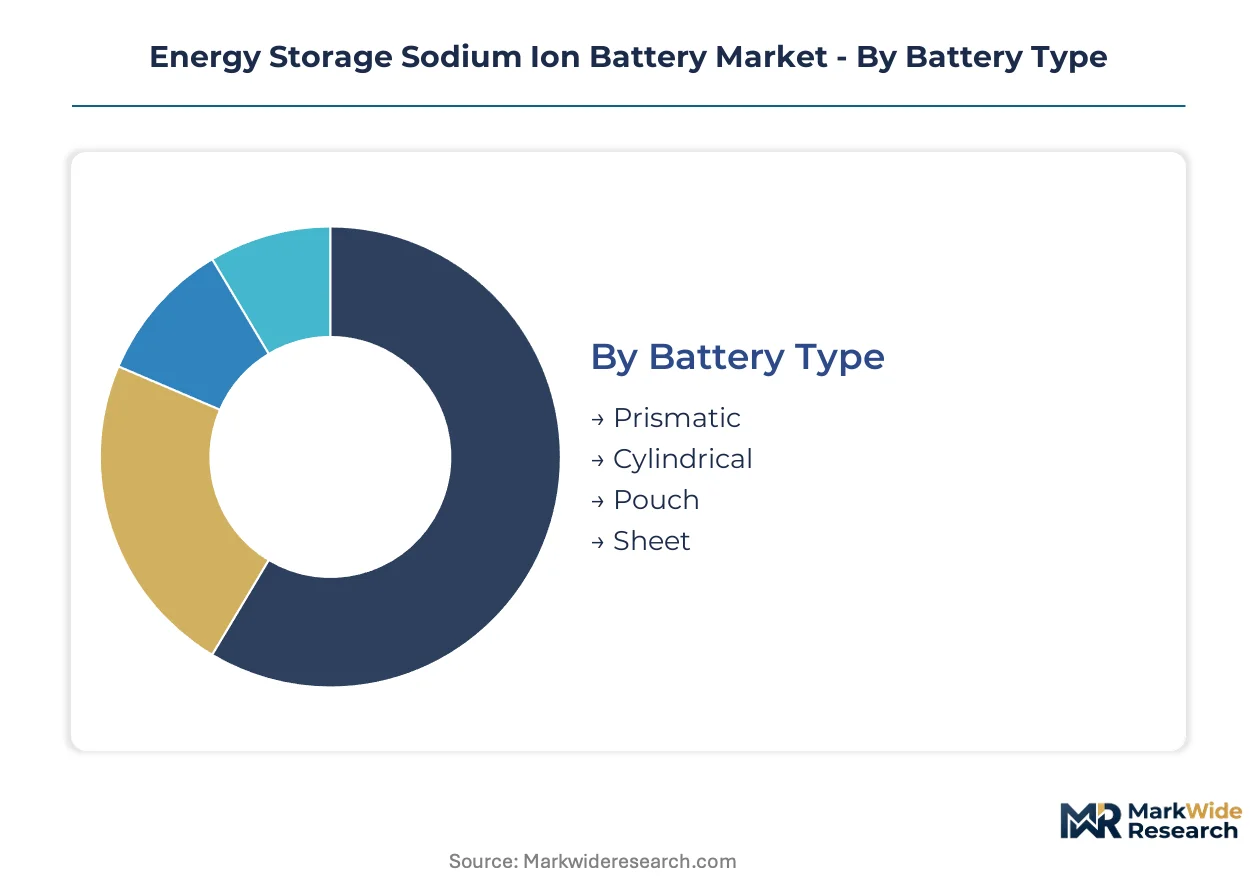
Sodium-ion battery procurement channels diverge sharply by segment, with utility-scale tenders favoring prismatic formats while data center operators specify aqueous electrolyte systems through direct manufacturer contracts. Understanding these channel dynamics reveals where margin pools concentrate and which technology configurations command pricing power.
Battery Type:
Prismatic cells flow predominantly through state procurement channels in China, while cylindrical formats reach telecom operators via distributor networks. Pouch and sheet variants occupy niche direct-sales relationships with specialized integrators.
- Prismatic:Layered oxide cathode formulations packaged in rigid aluminum housings achieve superior thermal management for utility-scale deployments. Demand clusters in Jiangsu province grid stabilization projects where CATL and HiNa Battery Technology anchor manufacturing capacity. State grid operators specify these formats for 100+ MWh installations due to pack-level energy density advantages and standardized module integration.
- Cylindrical:Rolled electrode architectures deliver mechanical robustness for remote infrastructure applications. Telecom base station operators across India and Southeast Asia favor this format for vibration tolerance and simplified thermal management in uncontrolled environments. Faradion licenses cylindrical production protocols to NGK Insulators for Japanese market penetration.
- Pouch:Flexible laminate enclosures enable custom form factors for space-constrained residential installations. Limited production runs serve European home energy storage integrators.
- Sheet:Ultra-thin electrode configurations target building-integrated photovoltaic applications. Emerging segment with pre-commercial shipments to German distributed energy developers.
Prismatic formats dominate installed base. Cylindrical is where expansion concentrates.
Application:
Cost tier stratification separates premium grid-scale contracts from economy backup power segments, with renewable integration occupying the mid-tier procurement band.
- Grid Stabilization:Frequency regulation and peak shaving services require 4-8 hour discharge duration with 10,000+ cycle life. Procurement concentrates through China's State Grid and Southern Power Grid tender processes where sodium-ion systems displace lithium iron phosphate in 100 MW-class installations. MIIT GB standards compliance is mandatory for vendor qualification.
- Renewable Integration:Wind and solar buffering applications prioritize capital cost minimization over energy density. Developers in Anhui province pair sodium-ion storage with photovoltaic assets to satisfy dual carbon goals while circumventing lithium supply volatility.
- Backup Power:Uninterruptible power supply for critical infrastructure favors aqueous electrolyte fire safety. Data center operators in Frankfurt and Amsterdam specify sodium-ion for EU Green Deal compliance.
- Electric Mobility:Limited to low-speed vehicles and stationary charging buffers due to 160 Wh/kg energy density ceiling. Indian PLI scheme eligibility redirects some capacity toward two-wheeler applications.
- Telecom Infrastructure:Remote base station power demands mechanical durability and wide temperature operation. Southeast Asian operators specify cylindrical sodium-ion for tropical climate resilience.
Grid stabilization commands premium pricing. Renewable integration is expanding most quickly.
Technology:
Volume concentration favors aqueous electrolyte manufacturing at scale, while polymer and glass variants remain pre-commercial with venture-funded pilot lines.
- Aqueous Electrolyte:Water-based sodium salt solutions deliver intrinsic thermal runaway immunity without flammable organic solvents. HiNa Battery Technology anchors production in China through partnerships with state grid operators. Data center procurement in Singapore and Frankfurt explicitly specifies this chemistry for fire code compliance.
- Solid-State:Ceramic or glass-ceramic electrolyte architectures promise enhanced safety and wider temperature operation. Peak Energy and Natron Energy fund pre-commercial development with target applications in aerospace and extreme environment deployment.
- Polymer Electrolyte:Gel-type sodium ion conductors enable flexible form factors for wearable and portable applications. Limited production by Korean specialty chemical manufacturers.
- Glass Electrolyte:Borate or phosphate glass matrices achieve high ionic conductivity at elevated temperatures. Laboratory-scale production with Japanese materials science partnerships.
Aqueous electrolyte dominates installed base. Solid-state is where expansion concentrates.
End User:
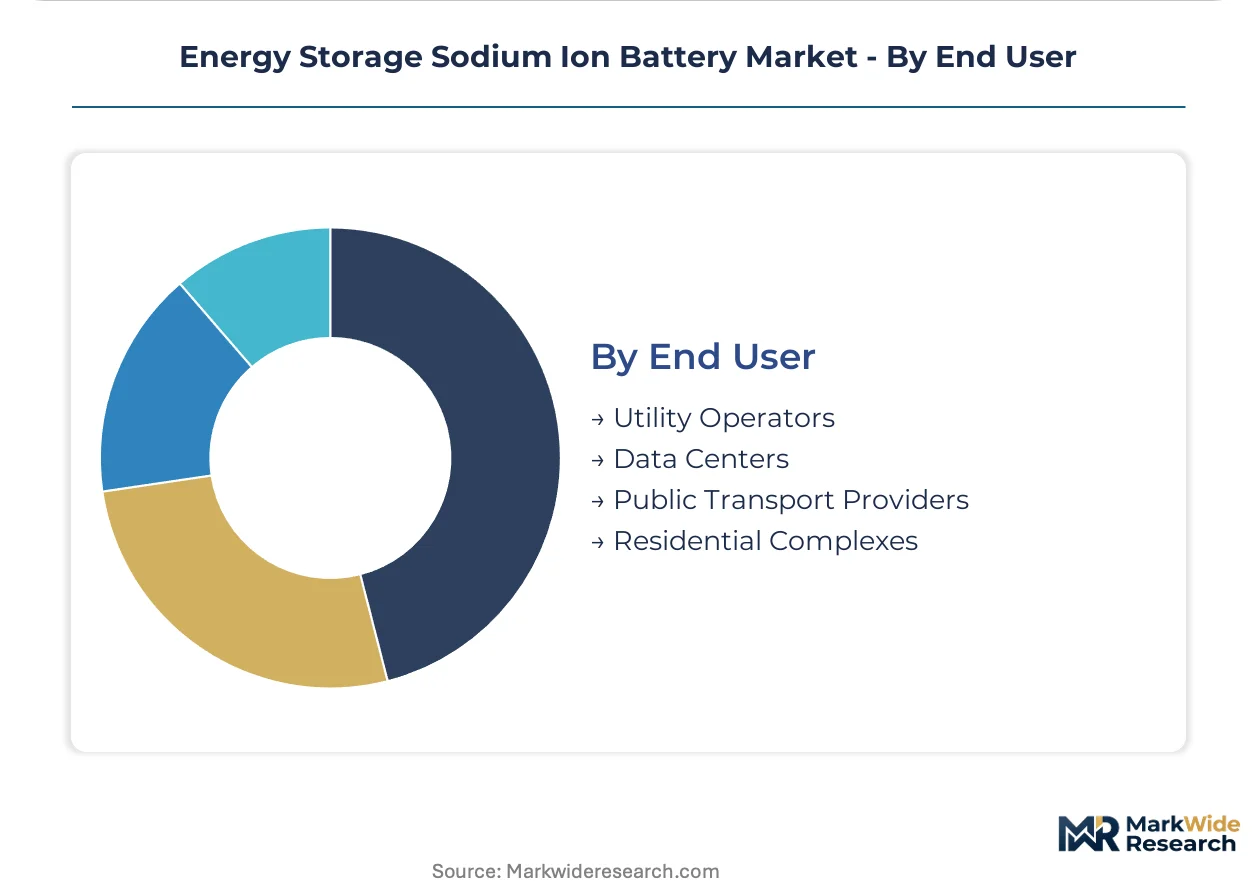
Customer type determines contract structure, with utility operators demanding availability guarantees and data centers prioritizing chemistry certification.
- Utility Operators:State-owned grid companies in China procure through centralized tender processes with 10-15 year service agreements. Jiangsu and Anhui provinces lead deployment volume. Contracts specify degradation limits and replacement obligations that favor established manufacturers with balance sheet capacity.
- Data Centers:Hyperscale operators and colocation providers specify fire-safe chemistry for backup power. EU Green Deal critical raw materials taxonomy shapes European procurement toward sodium-based systems. Frankfurt and Amsterdam clusters actively qualify sodium-ion suppliers.
- Public Transport Providers:Municipal bus and rail operators evaluate sodium-ion for depot charging buffers and stationary storage. Indian state transport utilities pilot systems under PLI scheme incentives.
- Residential Complexes:Home energy storage and apartment building microgrids represent emerging demand. German and Australian distributed energy markets show early adoption for solar self-consumption optimization.
Utility operators dominate installed base. Data centers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT governs sodium-ion battery GB standards development in China, while the EU Green Deal and India's PLI scheme reshape procurement incentives across three continents. Each geography is deploying distinct regulatory levers to accelerate chemistry diversification.
China
State grid operators in Jiangsu and Anhui provinces are procuring prismatic sodium-ion systems for 100+ MWh renewable integration projects. MIIT GB standards compliance is mandatory for vendor qualification in centralized tenders. Ningde anchors manufacturing capacity where CATL leverages proprietary layered oxide cathode formulations at commercial scale.
Germany
Grid-scale developers in Frankfurt and Bavaria are restructuring supplier qualification criteria to satisfy EU Green Deal critical raw materials taxonomy thresholds. REACH mandates supply chain due diligence for battery chemistries reducing lithium dependency. Industrial clusters in Baden-Württemberg actively qualify sodium-ion suppliers for utility-scale storage tenders.
India
State transport utilities in Gujarat and Maharashtra are piloting sodium-ion systems under PLI scheme incentives for advanced chemistry cells. The national program explicitly includes sodium-ion eligibility, redirecting capacity investments toward western manufacturing zones. Indian Railways evaluates depot charging buffers for electrified corridors.
United States
Data center operators in Northern Virginia and Dallas-Fort Worth are specifying aqueous electrolyte fire safety for backup power procurement. State-level clean energy standards in California and New York create procurement preference for thermal runaway-tolerant chemistries. Venture funding from Peak Energy and Natron Energy supports solid-state pre-commercial development.
United Kingdom
Technology licensing activity concentrates in Oxford and Cambridge corridors where Faradion sustains R&D intensity through joint ventures. The UK-India technology transfer pipeline positions British IP holders for Gujarat manufacturing partnerships. BEIS funding programs support hard carbon anode feedstock development from domestic biomass sources.
Energy Storage Sodium Ion Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sodium-ion battery landscape. The market structure consolidates around vertically integrated cell manufacturers and specialized electrolyte technology developers, with limited pure-play component suppliers achieving scale. Three archetypes dominate: state-backed Chinese conglomerates with captive raw material access, European IP licensing specialists, and venture-funded solid-state innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with technology licensing agreements proliferating ahead of mass commercialization.
Among the integrated manufacturing tier, Contemporary Amperex Technology Co., Ltd. exemplifies scale-driven production archetypes, while Faradion Limited occupies a position within the European IP licensing specialist tier. HiNa Battery Technology Co., Ltd. represents the aqueous electrolyte technology anchor, sitting within the state-partnership dependent archetype alongside grid operator procurement relationships.
| Leading Market Players |
|---|
| Contemporary Amperex Technology |
| HiNa Battery Technology |
| Faradion |
| Natron Energy |
| TIAMAT Energy |
| Altris |
| Jiangsu Zhongna Energy Technology |
| NGK Insulators |
| Peak Energy |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day hard carbon anode procurement cycles concentrate pricing power with Southeast Asian biomass precursor suppliers, compressing margin buffers for cell manufacturers while amplifying cost pass-through elasticity in utility-scale contracts.
Pricing Analysis
Price spreads between Chinese state-tender prismatic cells and European direct-contract aqueous electrolyte systems reflect divergent certification burdens. Three-tier pricing structure across premium MIIT-certified, standard commercial-grade, and economy pilot-production tiers separates grid-scale utility procurement from data center backup specifications. Cost compression in economy tiers intensifies because Jiangsu province manufacturing overcapacity feeds spot-market discounting. Data center operators exhibit least price sensitivity due to EU Green Deal compliance mandates, while renewable integration developers in Anhui province drive hardest bargain on capital cost per MWh.
Supply Chain Analysis
Inventory buffers for hard carbon anodes rarely exceed forty-five days, exposing manufacturers to Southeast Asian coconut shell and rice husk feedstock volatility. Cell production draws from China, India, and Japan, with cathode active materials resting on layered oxide precursors from domestic Chinese chemical processors. Single-source vulnerability concentrates in biomass carbonization facilities across Indonesia and Malaysia. Distribution runs through state grid procurement channels in China, direct manufacturer contracts for European data centers, and licensed distributor networks for Southeast Asian telecom infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in sodium-ion storage rests on chemistry-specific procurement mandates from China's MIIT and the EU Green Deal, accelerating penetration ahead of lithium supply constraint resolution.
For Market Incumbents: Compound manufacturing scale advantages in Ningde and Jiangsu through captive hard carbon anode sourcing from Indonesian biomass partnerships. Defend position against aqueous electrolyte specialists by accelerating MIIT GB certification timelines. Prioritize backward integration into cathode precursor synthesis to offset layered oxide material cost volatility.
For New Entrants and Emerging Players: Anchor in solid-state electrolyte pre-commercial development where Peak Energy and Natron Energy have validated venture funding appetite. Target data center backup power in Frankfurt and Amsterdam clusters where EU Green Deal compliance creates procurement preference void of incumbent lock-in. Pursue technology licensing rather than capital-intensive manufacturing to bypass scale disadvantages.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate battery divisions seeking to monetize sodium-ion IP ahead of mass commercialization. Five-to-ten-year viability hinges on cathode material patent thickets resolving in favor of licensable architectures. Monitor Faradion-Altris litigation outcomes as inflection indicator for technology licensing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Patent Licensing | Faradion's UK-India IP positioning determines technology transfer economics before mass manufacturing scale. |
| Hard Carbon Anode Backward Integration | Indonesian biomass precursor sourcing secures feedstock autonomy against Southeast Asian supply concentration. |
| Aqueous Electrolyte Scale-Up | HiNa Battery Technology's state grid partnerships validate fire-safe chemistry for data center procurement. |
| MIIT GB Standards Certification | Compliance unlocks centralized tender participation in Jiangsu and Anhui province renewable integration projects. |
| Solid-State Pre-Commercial Development | Peak Energy and Natron Energy funding signals venture appetite for next-generation safety performance. |
Research Methodology
A standing panel of utility planning officers, battery cell manufacturing executives, EPC contractors, and grid procurement specialists provided ongoing calibration against secondary validation from MIIT GB standard drafts, EU Green Deal implementation guidance, India PLI scheme eligibility criteria, and customs trade data for hard carbon anode feedstocks. Primary fieldwork combined structured interviews with bottom-up installation tracking and top-down regulatory impact assessment.
Consistency checks against IEA stationary storage outlooks and EIA battery deployment databases validated volume and value outputs across the projection horizon. Segmentation modeled battery type, application, technology, and end user dimensions alongside regional regulatory framework clusters. CAGRs derived from unit economics trajectories for prismatic cell manufacturing and aqueous electrolyte system integration.
Material uncertainties — patent litigation outcomes, biomass feedstock harvest variability, and MIIT certification timeline compression — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding lithium supply constraint persistence and sodium-ion chemistry performance maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
Energy Storage Software Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
Hydrogen Storage Cylinders Market