
 Solar Microgrid Market | 2026-2036
Solar Microgrid Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Microgrid Market Insights
The certified microgrid engineering workforce is collapsing across North America and Europe, creating project execution bottlenecks that delay commissioning timelines. Schneider Electric leverages its integrated hardware-software platform to capture utility-scale and community-based deployment contracts. Siemens sustains competitive positioning through deep domain expertise in grid-tied and hybrid system architecture. Tesla anchors its presence through proprietary energy storage integration and virtual power plant software layers.
A solar microgrid constitutes a localized energy network combining photovoltaic generation, battery storage, power conversion equipment, and intelligent control systems capable of islanded or grid-connected operation, typically ranging from kilowatt-scale residential installations to multi-megawatt industrial complexes. These systems serve primary commercial and industrial purposes including energy cost reduction, resilience assurance, and carbon footprint compliance through dispatchable renewable output. Off-grid and hybrid product types command premium margins where transmission infrastructure remains absent or unreliable, while grid-tied configurations dominate cumulative installed capacity in markets with stable utility interconnection standards. Community-based deployment models are gaining structural momentum as aggregators pool distributed assets into virtual microgrids that participate in wholesale electricity markets.
The Federal Energy Regulatory Commission and state-level public utility commissions in the United States shape interconnection standards and compensation mechanisms that determine project bankability, while the European Union's Renewable Energy Directive and CE marking requirements for electrical equipment govern product compliance and market access across member states. India's Central Electricity Authority and Bureau of Indian Standards enforce technical standards for distributed generation that directly influence component procurement specifications for domestic installations. Stakeholders must monitor evolving cybersecurity mandates for distributed energy resources and assess how carbon border adjustment mechanisms will alter component sourcing economics for storage and power electronics.
Market Dynamics
The collapse of certified microgrid engineering capacity across North America and Europe is compressing project execution timelines and forcing procurement officers toward pre-integrated hardware-software platforms that reduce commissioning complexity.
Growth Catalysts
- Feed-in tariff frameworks:India's Central Electricity Authority and Germany's Bundesnetzagentur have established guaranteed remuneration structures for distributed solar exports that improve project bankability and attract institutional capital.
- Lithium-ion cost compression:Battery pack price declines of the past decade are enabling longer-duration storage configurations that extend microgrid operational hours beyond daylight periods.
- Sub-Saharan electrification mandates:Rural electrification programs in Kenya, Nigeria, and Tanzania are accelerating tender volumes for off-grid solar microgrid systems in healthcare and agricultural processing facilities.
Market Restraints
- Power electronics supply concentration:Inverter and converter manufacturing clusters in China create single-source dependencies that expose project developers to tariff and logistics volatility.
- Interconnection standard fragmentation:Divergent grid codes across US state-level public utility commissions force component redesigns that inflate engineering costs and delay permitting.
- Diesel generator substitution economics:Backup fossil-fuel systems retain cost advantages in markets with subsidized fuel pricing, particularly in Middle Eastern industrial zones.
Strategic Opportunities
- Virtual power plant aggregation:Software platforms that pool distributed microgrid assets into wholesale market participants are creating new revenue streams beyond energy sales.
- Caribbean resilience procurement:Island nations including Jamaica, Barbados, and the Dominican Republic are prioritizing hurricane-hardened microgrids for critical infrastructure.
- CE marking alignment:The European Union's harmonized electrical equipment standards are reducing certification burdens for manufacturers targeting multiple member state markets simultaneously.
Industry Challenges
- Commissioning engineer scarcity:The specialized workforce for microgrid integration and control system commissioning is contracting faster than training pipeline expansion in both North America and Western Europe.
- Cybersecurity compliance timelines:Evolving distributed energy resource security mandates from the Federal Energy Regulatory Commission are extending pre-operational testing phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Microgrid Market |
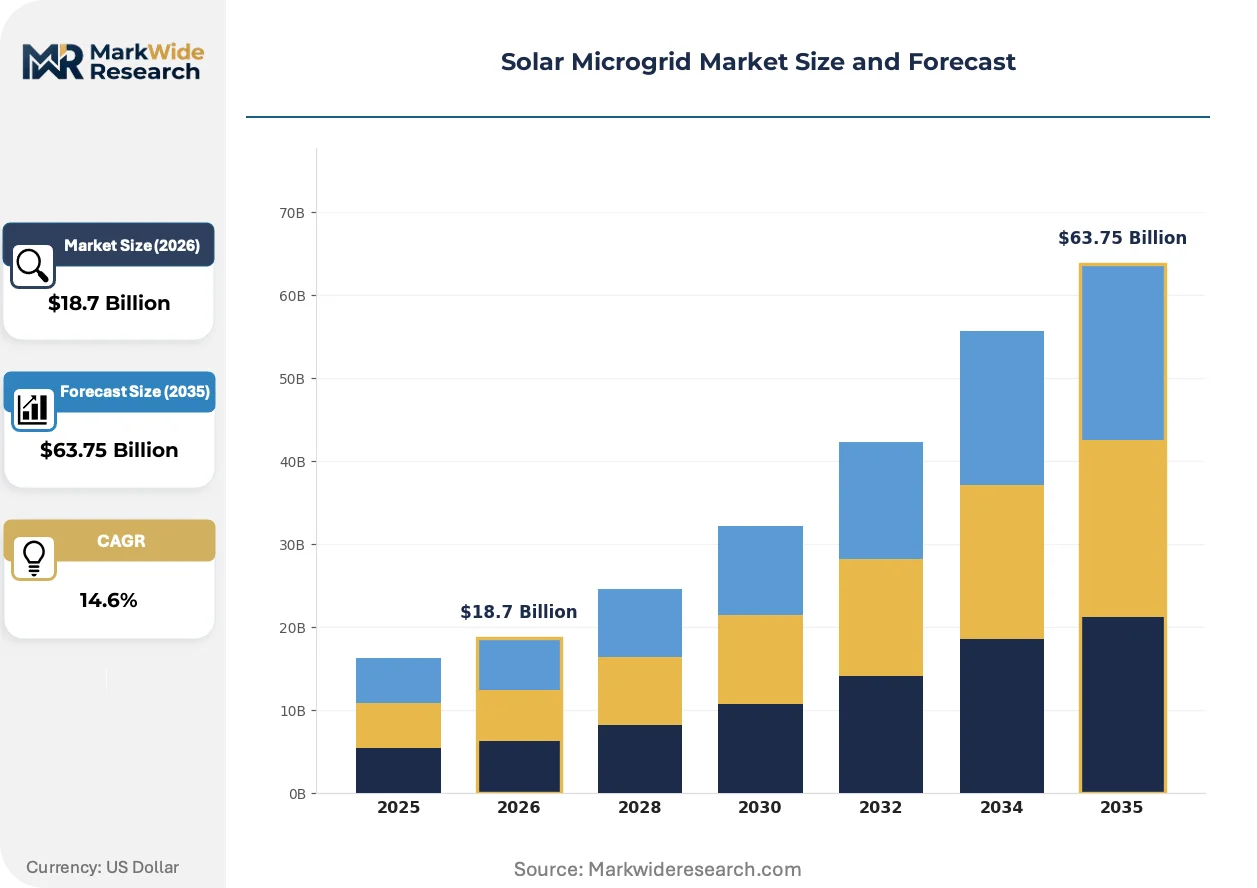
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid-Tied, Off-Grid, Hybrid, Virtual Microgrid Component: Solar Panels, Inverters, Energy Storage Systems, Controllers End User: Residential, Commercial, Industrial, Institutions Deployment: Utility-Scale, Community-Based, Remote Island, Disaster Relief |
| Companies Covered | Schneider Electric, Siemens, General Electric, ABB, Eaton, Tesla, Honeywell International, GE Vernova, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Microgrid Market Trends and Innovations
Intelligent control architectures and modular battery systems are restructuring how developers configure and scale microgrid deployments across residential, commercial, and industrial segments.
Solid-state battery chemistry is bifurcating the stationary storage landscape. These systems deliver higher energy density and improved thermal stability compared to conventional lithium-ion configurations. Remote industrial sites in Southeast Asia and mining operations in Western Australia are piloting solid-state integration for extended autonomy periods. The technology is bifurcating procurement patterns between premium long-duration applications and cost-optimized shorter-cycle deployments.
The European Union's Cybersecurity Act and accompanying CE marking requirements for critical infrastructure are mandating formal security certification for microgrid control systems. Manufacturers must now demonstrate compliance with IEC 62443 industrial cybersecurity standards before market entry. Grid-tied commercial installations across Germany, France, and the Netherlands are experiencing the longest certification delays as notified bodies build testing capacity.
Industrial energy buyers are consolidating procurement authority into centralized sustainability offices that negotiate multi-site microgrid service agreements. Traditional equipment vendors are responding with performance-guaranteed contracting models that transfer operational risk from facility managers to technology providers. This concentration of buying power is most visible across automotive manufacturing campuses in the US Southeast and chemical processing complexes along Germany's Rhine corridor.
Solar Microgrid Market Segmentation
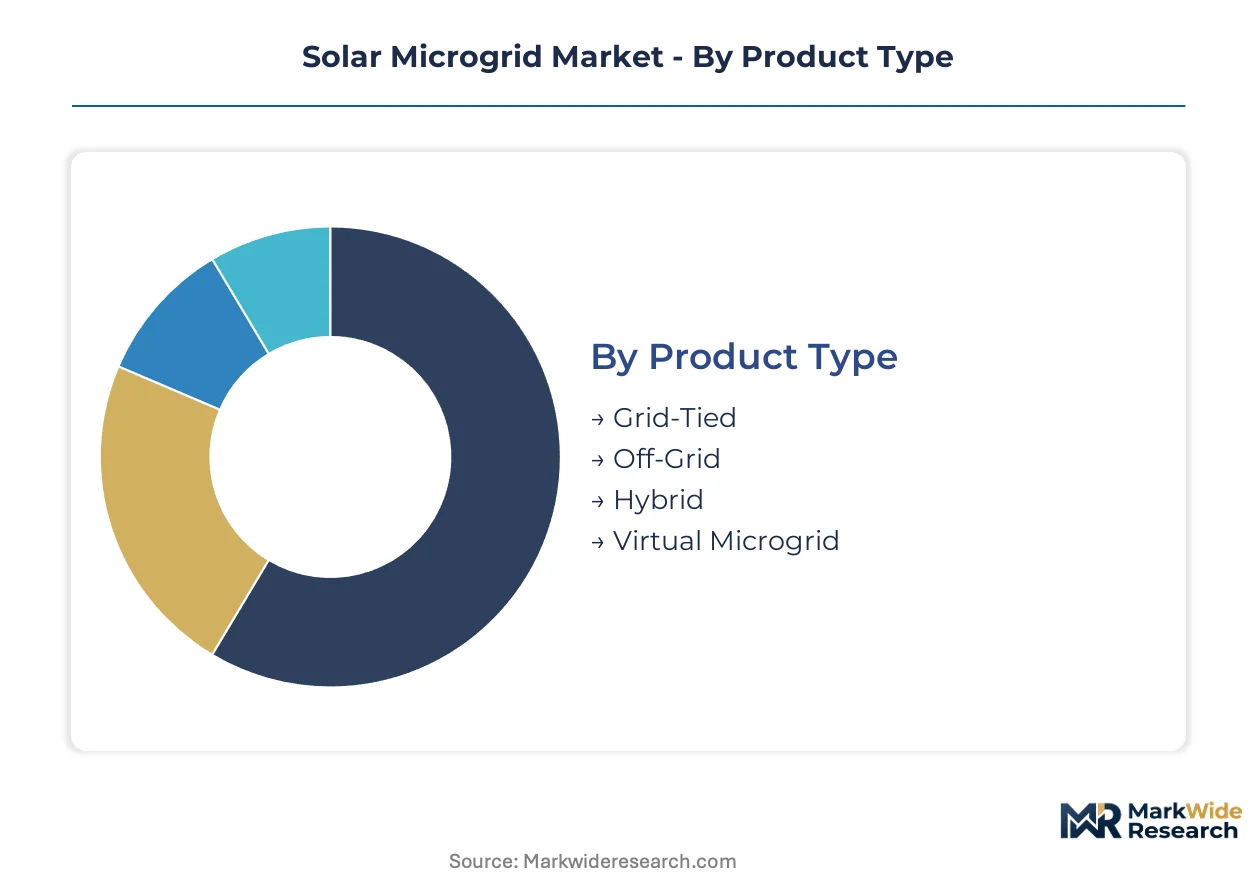
Solar microgrids serve radically different economic and technical requirements across electrification contexts. Segment boundaries determine component specifications, financing structures, and regulatory compliance pathways for project developers.
Product Type:
Grid-tied configurations dominate procurement in Germany and India where interconnection standards are mature, while off-grid and hybrid systems concentrate in sub-Saharan Africa and island nations lacking transmission infrastructure.
- Grid-Tied:These systems synchronize with utility networks through bidirectional inverters that export surplus generation and import during deficits. Demand concentrates across commercial campuses in India and industrial parks in Germany where feed-in tariffs improve project returns. Developers favor pre-certified power conversion equipment to accelerate permitting timelines.
- Off-Grid:Fully autonomous systems combine oversized PV arrays with lithium-ion storage to guarantee 24-hour supply without utility backup. Healthcare facilities in Kenya and agricultural processing cooperatives in Tanzania drive procurement volumes through rural electrification programs. Battery cost compression is extending operational autonomy beyond daylight hours.
- Hybrid:Dual-fuel architectures integrate solar generation with diesel or gas generators for seamless backup during extended cloud cover. Mining operations in Western Australia and remote industrial sites in Indonesia specify these configurations where fuel logistics remain challenging.
- Virtual Microgrid:Software-aggregated distributed assets pool generation and storage across multiple physical sites to participate in wholesale electricity markets. Aggregators in California and Texas are deploying these platforms to capture capacity market revenues.
Grid-tied holds the largest share; momentum sits with virtual microgrids as software platforms mature.
Component:
Cost tiers separate premium-certified equipment for European and North American markets from cost-optimized specifications serving developing economies.
- Solar Panels:Crystalline silicon modules dominate utility-scale procurement while bifacial designs gain share in high-albedo desert environments. Tier-1 manufacturers in Southeast Asia supply the majority of global volume.
- Inverters:Power conversion equipment transforms DC generation to AC grid-compliant output with reactive power control and fault ride-through capabilities. String inverters serve commercial installations in Germany while central inverters anchor utility-scale projects in India.
- Energy Storage Systems:Lithium-ion battery packs with integrated thermal management and battery management systems enable dispatchable renewable output. Containerized systems from Chinese manufacturers are displacing European alternatives in price-sensitive markets.
- Controllers:Intelligent control hardware orchestrates generation dispatch, load prioritization, and grid interconnection through IEC 62443-compliant cybersecurity architectures. Certification delays at European notified bodies are extending procurement timelines.
Storage systems command the steepest expansion trajectory as duration requirements extend beyond four hours.
End User:
Customer sophistication determines service model complexity, from standardized residential packages to performance-guaranteed industrial contracts.
- Residential:Kilowatt-scale rooftop systems serve single-family homes and small multi-unit buildings through lease or power purchase agreement structures. Installations cluster in suburban California and Australian states with favorable net metering policies.
- Commercial:Megawatt-scale systems reduce energy costs and ensure resilience for retail chains, data centers, and logistics facilities. Automotive manufacturing campuses in the US Southeast are consolidating procurement through centralized sustainability offices.
- Industrial:Multi-megawatt complexes power continuous-process manufacturing where grid outages incur catastrophic losses. Chemical processing complexes along Germany's Rhine corridor negotiate performance-guaranteed service agreements.
- Institutions:Hospitals, universities, and military installations prioritize resilience and carbon compliance over cost optimization. Hurricane-hardened microgrids are gaining priority across Caribbean healthcare infrastructure.
Industrial deployments generate the highest revenue per project; institutions are gaining share fastest through resilience procurement mandates.
Deployment:
Application maturity separates established utility-scale procurement from emerging community-based aggregation models.
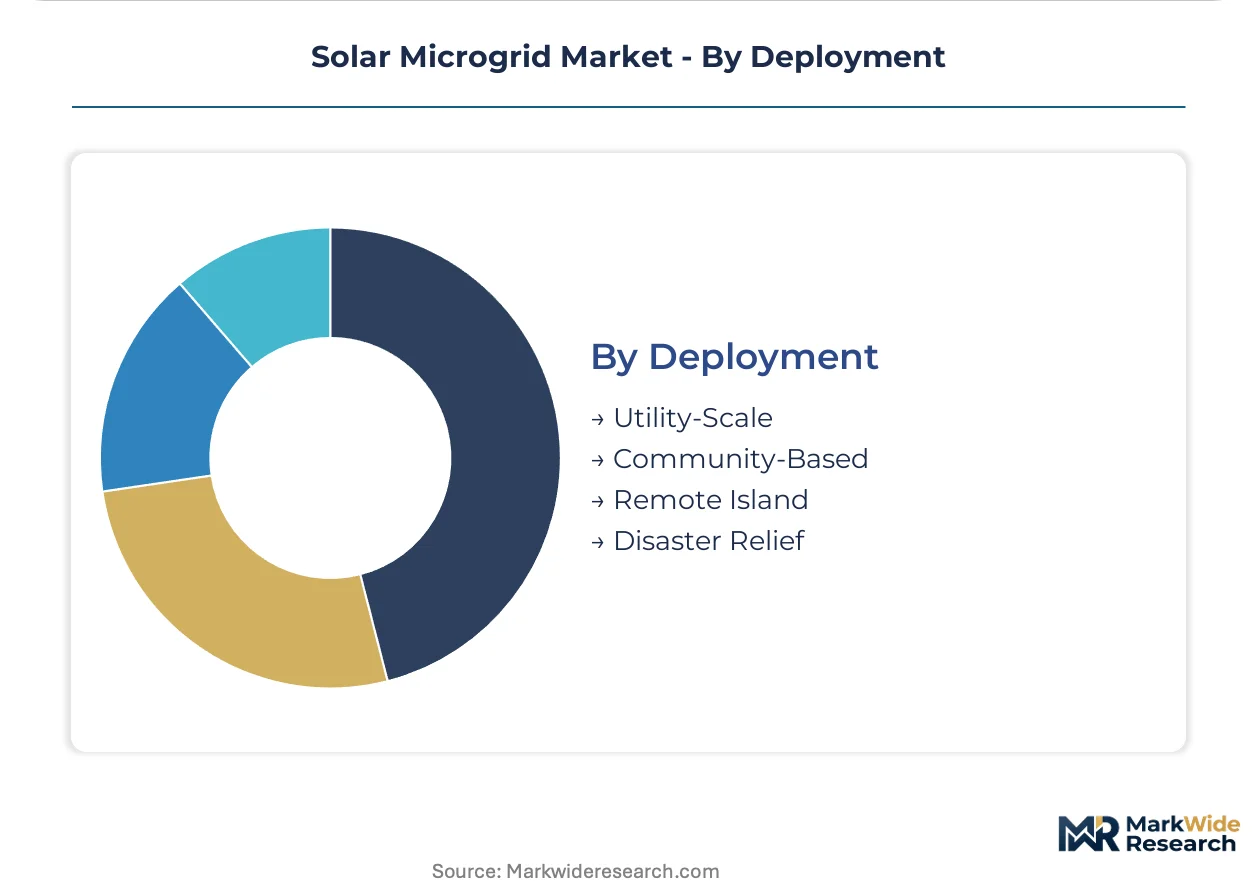
- Utility-Scale:Centralized solar-plus-storage plants ranging from 10 to 100+ megawatts serve as grid assets with wholesale market participation. Developers in India and the southwestern United States dominate installed capacity.
- Community-Based:Shared solar resources enable multiple subscribers to access renewable generation without individual rooftop installation. Virtual aggregation platforms in Germany and the Netherlands are pooling residential assets into wholesale market participants.
- Remote Island:Isolated systems replace diesel dependence for island nations where fuel logistics inflate electricity costs. Jamaica, Barbados, and the Dominican Republic are prioritizing hurricane-hardened designs.
- Disaster Relief:Rapidly deployable containerized systems restore critical power within hours of grid failure. International development agencies are pre-positioning equipment across Southeast Asian cyclone corridors.
Utility-scale retains volume leadership; community-based models are climbing the fastest as aggregation software matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys solar microgrids primarily for rural electrification and industrial cost reduction, whereas Germany emphasizes grid-tied commercial systems and virtual aggregation platforms. Island nations across the Caribbean prioritize hurricane-hardened resilience configurations. Sub-Saharan Africa concentrates procurement in healthcare and agricultural processing facilities.
United States
Data center operators and automotive manufacturing campuses in the Southeast are consolidating procurement through centralized sustainability offices. The Federal Energy Regulatory Commission shapes interconnection standards and compensation mechanisms that determine project bankability. Hurricane-hardened microgrids are gaining priority across critical infrastructure in Florida and Texas.
Germany
Commercial campuses and industrial parks along the Rhine corridor specify grid-tied configurations where feed-in tariffs improve project returns. The Bundesnetzagentur establishes guaranteed remuneration structures for distributed solar exports that attract institutional capital. Grid-tied commercial installations across Germany, France, and the Netherlands are experiencing the longest certification delays as notified bodies build testing capacity.
India
Rural electrification programs and healthcare facilities in Kenya, Nigeria, and Tanzania are accelerating tender volumes for off-grid solar microgrid systems. The Central Electricity Authority and Bureau of Indian Standards enforce technical standards for distributed generation that directly influence component procurement specifications. Utility-scale solar-plus-storage plants ranging from 10 to 100+ megawatts serve as grid assets with wholesale market participation.
Kenya
Healthcare facilities and agricultural processing cooperatives drive procurement volumes through rural electrification programs. The country's national energy regulator shapes tariff structures that improve project bankability for off-grid installations. Off-grid systems combine oversized PV arrays with lithium-ion storage to guarantee 24-hour supply without utility backup across rural health infrastructure.
Jamaica
Island nations including Jamaica, Barbados, and the Dominican Republic are prioritizing hurricane-hardened microgrids for critical infrastructure. The regional utility commission shapes resilience procurement mandates that accelerate tender volumes. Remote island systems replace diesel dependence where fuel logistics inflate electricity costs across Caribbean healthcare and tourism facilities.
Solar Microgrid Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding utility-scale and community-based deployment contracts through pre-integrated hardware-software platforms. The middle tier fragments across component specialists and regional system integrators. Three archetypes dominate: integrated industrial conglomerates with deep domain expertise in grid-tied architecture, energy storage specialists with proprietary software layers, and power electronics manufacturers with captive supply chains. Competitive moves concentrate on strategic partnerships for virtual power plant aggregation and backward integration into battery management systems.
Within the integrated industrial tier, Schneider Electric and Siemens exemplify archetypes of hardware-software platform providers and grid architecture specialists respectively. Tesla occupies a distinct position anchoring the energy storage integration vector through proprietary virtual power plant software layers. These three companies represent the dominant competitive anchors shaping procurement officer preferences toward pre-integrated solutions that reduce commissioning complexity.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| General Electric |
| ABB |
| Eaton |
| Tesla |
| Honeywell International |
| GE Vernova |
| Hitachi Energy |
| Others |
Pricing and Supply Chain Analysis
Sixteen-week lead times for IEC 62443-certified controllers are compressing margins for European project developers while amplifying pricing power for pre-integrated platform vendors. This inventory tightness concentrates procurement authority with manufacturers who can guarantee delivery certainty.
Pricing Analysis
Long-term offtake contracts dominate utility-scale deployments in India and Germany, locking in equipment costs and shielding developers from lithium-ion volatility. Three-tier pricing structure across premium-certified, standard-compliant, and economy-optimized levels separates European notified-body approvals from cost-optimized Asian alternatives. Pricing pressure stems from battery pack cost compression and inverter commoditization. Commercial campuses exhibit highest price sensitivity; hurricane-hardened Caribbean institutions show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites containerized battery shipments from Chinese manufacturers to Southeast Asian and African markets. Manufacturing clusters in China, South Korea, and Vietnam supply crystalline silicon modules, power conversion equipment, and lithium-ion storage systems. Raw material dependencies span polysilicon feedstock, electrolyte chemicals, and rare-earth magnets. Single-source vulnerability concentrates in inverter controller semiconductors. Distribution runs through EPC contractors with captive installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapsing certified microgrid engineering workforce is constraining execution capacity faster than training pipelines can replenish, creating acute scarcity premiums for integration expertise.
For Market Incumbents: Fortify commissioning capabilities through backward integration into battery management systems and captive certification programs. Pre-integrated hardware-software platforms reduce deployment risk as diesel generator substitution economics threaten margin compression in Middle Eastern industrial zones. Deepen control system cybersecurity credentials ahead of FERC mandate expansion. For New Entrants and Emerging Players: Anchor in Caribbean resilience procurement and sub-Saharan healthcare electrification where incumbent presence remains thin. Virtual power plant aggregation software presents the most penetrable white-space, with California and Texas regulatory frameworks enabling wholesale market participation. Pursue performance-guaranteed service contracts that transfer operational risk from facility managers. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because grid-edge intelligence layers capture recurring revenue beyond hardware depreciation. Target acquisition archetypes combine distributed energy resource control platforms with established EPC relationships. Watch FERC cybersecurity compliance timelines as inflection indicator for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Aggregation | Software platforms pool distributed assets into wholesale market participants across Texas and California. |
| Backward Integration into Storage | Captive battery management systems reduce commissioning complexity and supplier dependency. |
| Cybersecurity Certification Investment | IEC 62443 compliance accelerates European market entry amid notified body capacity constraints. |
| Caribbean Resilience Procurement | Hurricane-hardened designs capture premium pricing across Jamaica and Dominican Republic infrastructure. |
| Performance-Guaranteed Contracting | Risk transfer models align vendor incentives with industrial buyer uptime requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA project databases, IEA renewable energy reports, FERC interconnection filings, and component manufacturer technical specifications. Interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators informed demand-side assumptions. Bottom-up installation forecasts triangulate against top-down regulatory mandate analysis.
Segmentation dimensions modeled include product type, component category, end-user archetype, and deployment scale across the projection horizon. CAGRs derive from capacity addition trajectories, technology cost curves, and regulatory incentive evolution. Forecast inputs incorporate lithium-ion price elasticity and interconnection queue depth by regional grid operator.
Material uncertainties — tariff exposure on Chinese power electronics, FERC cybersecurity rule finalization, and sub-Saharan electrification funding continuity — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as battery chemistry transitions and carbon border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
United Kingdom Distributed Solar Power Generation Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Solar Fuel Market