
 Solar Storage System Market | 2026-2036
Solar Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Storage System Market Insights
Utility-grade cycle-life specifications above 6,000 cycles at 80% depth of discharge is unwinding the cost-per-kWh calculus for front-of-meter projects. Tesla leverages its integrated power electronics and software stack to sustain margin capture across utility and residential deployments. LG Energy Solution anchors its position through cathode material verticality and automotive-derived cell architectures. BYD Company dominates in China through captive lithium iron phosphate cell supply and aggressive utility-scale EPC bundling.
A solar storage system combines electrochemical or mechanical energy storage with photovoltaic generation to time-shift solar output, regulate grid frequency, or provide backup power, typically incorporating inverters, battery management systems, and thermal controls to maintain cell temperatures between 15°C and 35°C for optimal longevity. Lithium-ion configurations lead installed capacity owing to declining cell costs and proven cycle stability, while flow batteries occupy a niche in long-duration utility applications where daily cycling exceeds eight hours. Residential end-user demand clusters in markets with time-of-use rate structures and net metering revisions, whereas utility applications command the largest absolute capacity additions as grid operators replace peaker plants with battery-stored solar.
The US IRA and FERC Order 2222 are enabling distributed storage aggregation and standalone project finance, while China's National Energy Administration sets provincial installation quotas that directly shape annual procurement volumes. The EU Green Deal and Battery Regulation mandate carbon footprint disclosure and recycled content thresholds, forcing supply chain reconfiguration for exporters serving European utility and commercial segments. Stakeholders must track how evolving interconnection standards and capacity market rules in each jurisdiction determine merchant revenue streams versus contracted offtake structures.
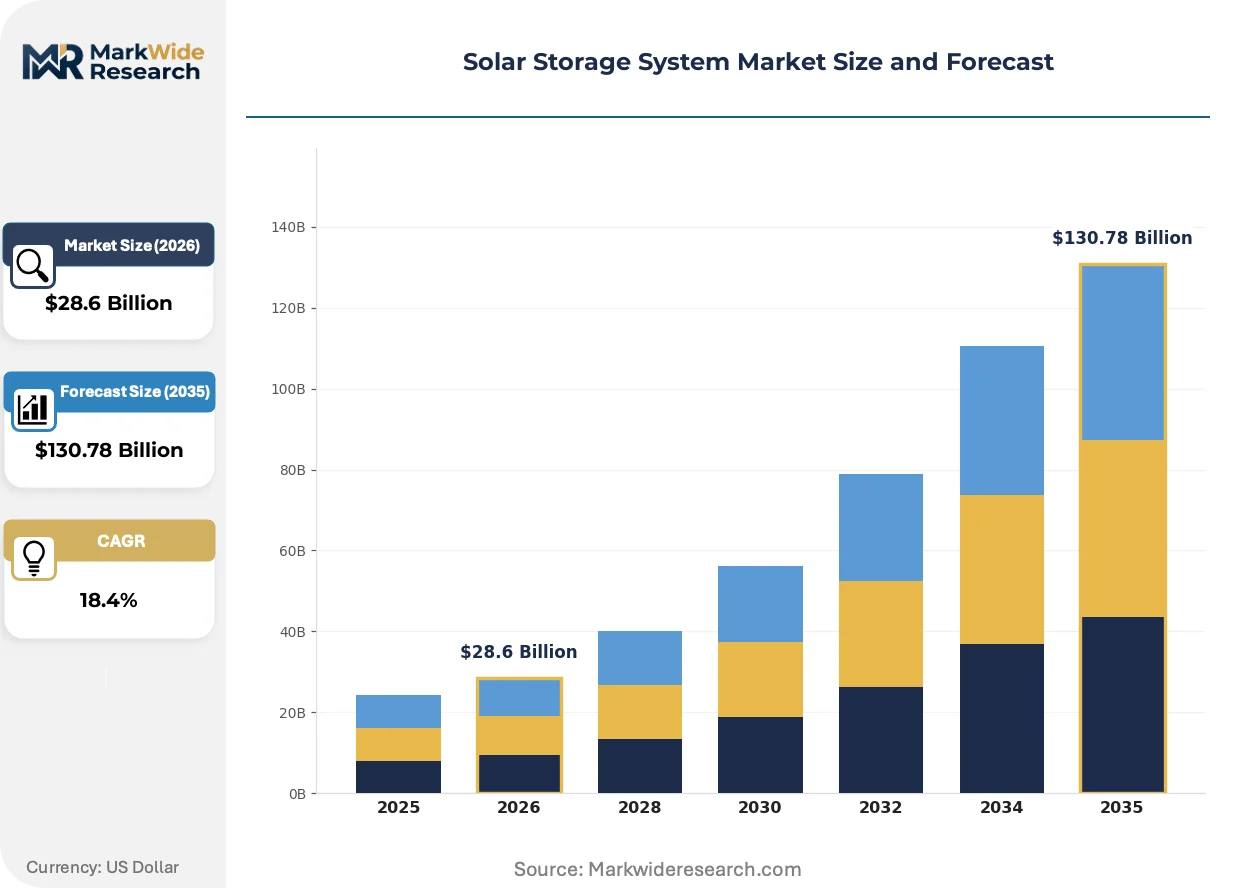
Market Dynamics
The solar storage system market is being fundamentally restructured by the US Inflation Reduction Act's standalone storage investment tax credit, which decouples battery economics from solar co-location and unlocks merchant revenue streams for grid-scale developers.
Growth Catalysts
- Grid operator procurement mandates:US utilities under FERC Order 2222 are aggregating distributed storage into virtual power plants, creating standardized offtake contracts that reduce developer risk.
- Cell chemistry maturation:Lithium iron phosphate architectures are achieving 6,000+ cycle ratings at 80% depth of discharge, collapsing levelized cost of storage for daily cycling applications.
- China's provincial quota system:The National Energy Administration's installation targets for Shandong, Jiangsu and Inner Mongolia are compressing EPC timelines and driving manufacturing scale.
Market Restraints
- Lithium carbonate price volatility:Raw material swings between 2022 peaks and 2024 troughs have destabilized project finance assumptions for long-duration contracts.
- Interconnection queue congestion:US regional transmission organizations face 3-5 year backlogs for grid-tied storage, freezing capital deployment regardless of technology readiness.
- Flow battery capital intensity:Vanadium redox systems require 40% higher upfront investment than lithium-ion, limiting penetration despite superior 8+ hour duration economics.
Strategic Opportunities
- India's renewable purchase obligations:State-level storage mandates under CEA guidelines are opening procurement windows for foreign integrators willing to localize assembly.
- Behind-the-meter commercial aggregation:Software platforms that stack frequency regulation, demand charge management and backup power are capturing margin previously retained by utilities.
- EU Battery Regulation compliance services:Carbon footprint disclosure and recycled content thresholds are creating advisory and certification revenue streams for supply chain auditors.
Industry Challenges
- Battery management system firmware integration:Multi-vendor DC-coupled architectures suffer communication protocol incompatibilities that delay commissioning and void warranties.
- Thermal runaway mitigation engineering:NFPA 855 fire code compliance requires gas detection, suppression and ventilation systems that add 8-12% to balance-of-plant costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Storage System Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Saltwater, Flow Batteries End User: Residential, Commercial, Industrial, Utility Application: Grid Storage, Off-grid, Backup Power, Peak Shaving Technology: Hybrid Systems, Smart Inverters, Battery Management Systems, Integrated Solutions |
| Companies Covered | Tesla, BYD Company, LG Energy Solution, Samsung SDI, ABB, Siemens Energy, Panasonic Holdings Corporation, Fluence Energy, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Storage System Market Trends and Innovations
Electrochemical storage architectures are bifurcating between lithium-ion dominance in 2-4 hour markets and emerging chemistries targeting multi-day duration, while software-defined control layers are commoditizing hardware differentiation.
Solid-state battery prototypes are supplanting conventional liquid electrolyte designs in pilot utility deployments. Korean and Japanese developers are testing sulfide-based cells for 10,000-cycle lifespans. This chemistry is compressing degradation risk premiums in project finance models.
Europe's Battery Regulation mandates passport-grade supply chain traceability from 2027. Manufacturers must document carbon intensity per kWh and recycled content percentages. Exporters to Germany, France and the Netherlands are reconfiguring cathode sourcing to meet disclosure thresholds.
Merchant developers are underwriting projects on arbitrage revenue rather than contracted offtake. Texas ERCOT and California CAISO markets reward rapid response to price spikes. This behavior concentrates deployment in nodal pricing zones with high volatility, displacing traditional capacity payment reliance.
Solar Storage System Market Segmentation
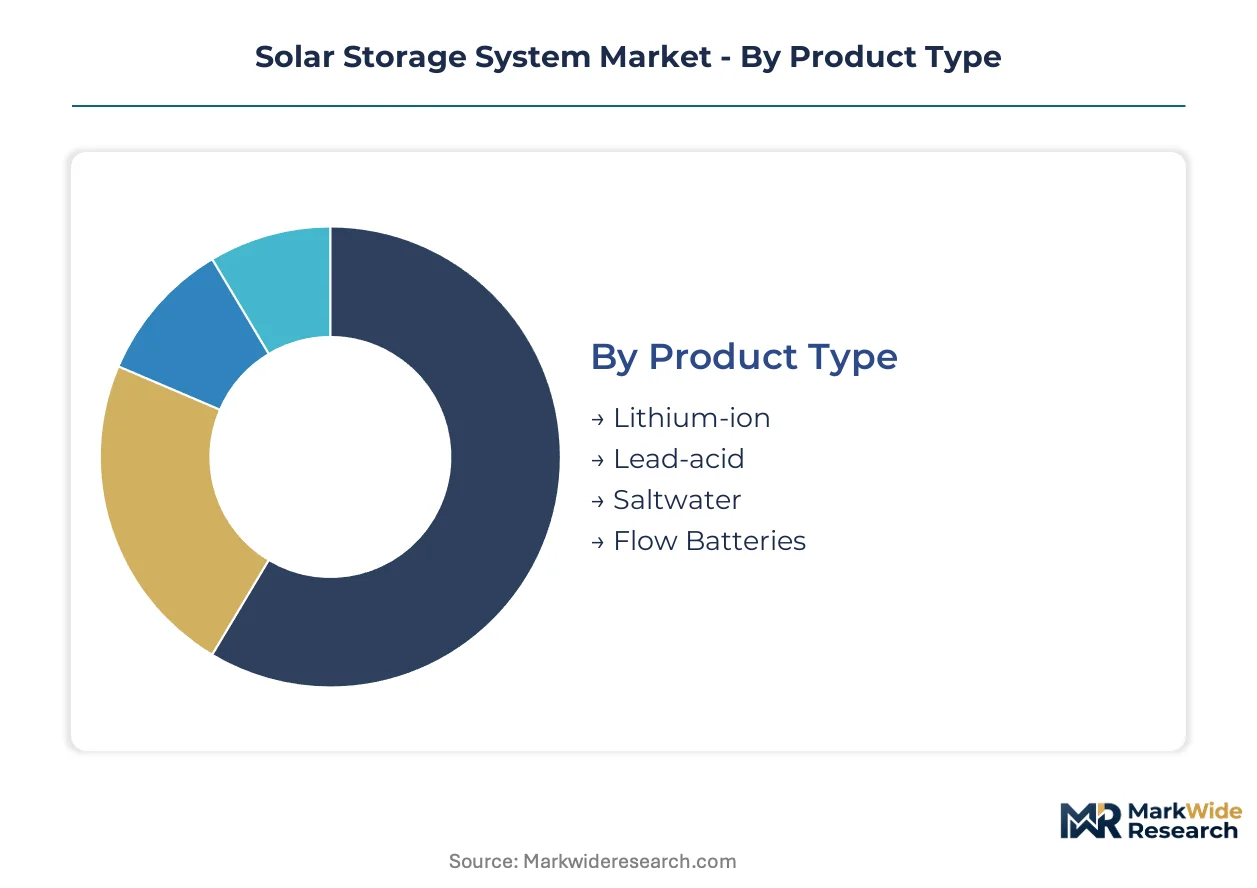
Solar storage system procurement splits across electrochemical chemistries, end-use scales, functional applications, and control architectures. Each dimension carries distinct margin profiles, warranty obligations, and integration complexity that shape vendor strategy and project finance assumptions.
Product Type:
Flow batteries and saltwater architectures pose the strongest substitution threat to incumbent lithium-ion systems in long-duration procurement, though capital cost gaps limit near-term displacement.
- Lithium-ion:Dominant electrochemical architecture utilizing lithium iron phosphate or nickel manganese cobalt cathodes, achieving 6,000+ cycle ratings at 80% depth of discharge. Demand concentrates in utility-scale deployments across Texas ERCOT and California CAISO markets, where rapid response to price spikes rewards high round-trip efficiency. IRA standalone storage tax credits compress project economics for front-of-meter developers.
- Lead-acid:Mature flooded or valve-regulated designs with lower energy density and shorter cycle life. Residential backup installations in hurricane-prone US Gulf Coast states sustain procurement volumes where upfront cost sensitivity outweighs longevity requirements.
- Saltwater:Aqueous sodium-ion chemistry eliminating thermal runaway risks and critical mineral dependencies. Pilot deployments in Germany and Netherlands utility tenders test carbon footprint advantages under EU Battery Regulation disclosure mandates.
- Flow Batteries:Vanadium redox or zinc-bromide systems decoupling power and energy scaling for 8+ hour duration applications. Shandong and Jiangsu provincial quotas in China drive manufacturing scale trials for daily cycling beyond lithium-ion economic thresholds.
Lithium-ion retains volume leadership; flow batteries hold the steepest expansion curve for multi-hour utility contracts.
End User:
Cost tier stratification separates premium integrated solutions from standard modular configurations across customer scales.
- Residential:Behind-the-meter systems from 5-20 kWh paired with rooftop solar, clustering in California, Arizona, and Hawaii where net metering revisions and time-of-use rate structures improve payback periods. Tesla and LG Energy Solution dominate through installer network density and financing partnerships.
- Commercial:100 kWh to 2 MWh installations serving demand charge management and backup power for data centers, retail chains, and manufacturing facilities. Software platforms stacking frequency regulation revenue with utility bill optimization capture margin previously retained by load-serving entities.
- Industrial:Microgrids and process-critical backup for semiconductor fabrication, cold storage, and chemical processing. Texas and Arizona industrial parks deploy solar-plus-storage to isolate from grid volatility and secure power purchase agreement price certainty.
- Utility:Front-of-meter projects from 10 MWh to giga-scale replacing peaker plants and providing ancillary services. FERC Order 2222 aggregation standards and standalone IRA tax credits reshape procurement toward merchant revenue underwriting in nodal pricing zones.
Utility commands absolute capacity additions; residential climbs fastest as financing products mature and installer competition intensifies.
Application:
Volume concentration tracks geography-specific grid reliability needs and regulatory compensation structures.
- Grid Storage:Bulk energy shifting and ancillary service provision at transmission-connected substations. California, Texas, and Australian NEM markets reward rapid frequency response and arbitrage capture, concentrating deployments where nodal price volatility exceeds contracted capacity payment returns.
- Off-grid:Remote industrial sites, rural electrification, and islanded communities lacking transmission infrastructure. Mining operations in Western Australia and agricultural processing in Sub-Saharan Africa sustain demand for solar-diesel-battery hybrids.
- Backup Power:Resilience provisioning for critical facilities during grid outages. US Gulf Coast hurricane corridors and California wildfire-prone regions drive procurement where reliability premiums outweigh pure economic optimization.
- Peak Shaving:Demand charge reduction for commercial and industrial ratepayers facing volumetric pricing spikes. Northeast US utility territories with high demand ratchets and Southeast commercial zones with summer peak pricing sustain deployment.
Grid storage leads installed megawatt-hours; backup power gains share fastest as climate-driven outage frequency rises.
Technology:
Supply concentration in power electronics and software layers determines margin capture versus hardware commoditization.
- Hybrid Systems:DC-coupled architectures integrating PV inverters with battery charge controllers, reducing conversion losses and balance-of-plant costs. Utility-scale procurement in China and US Southwest favors single-vendor integration to streamline commissioning and warranty coverage.
- Smart Inverters:Grid-forming and grid-following power electronics with reactive power support, frequency-watt control, and remote dispatch capability. IEEE 1547-2018 compliance requirements in US interconnection standards mandate advanced functionality for new installations.
- Battery Management Systems:Cell-level monitoring, thermal regulation, and state-of-charge estimation firmware maintaining 15-35°C operating windows. Multi-vendor DC-coupled projects suffer protocol incompatibilities that delay commissioning and complicate warranty enforcement.
- Integrated Solutions:Factory-assembled containerized units with pre-tested power conversion, thermal management, and safety systems. EPC timeline compression in China's provincial quota system and US interconnection queue congestion reward plug-and-play deployment models.
Integrated solutions capture expanding share; smart inverters face steepest functional escalation as grid codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are rebalancing as domestic cell manufacturing expands in major demand centers, reducing reliance on cross-border lithium supply chains while creating new trade flows in power electronics and software layers.
United States
Standalone storage procurement accelerates under IRA tax credits as Texas ERCOT and California CAISO markets reward merchant arbitrage strategies. FERC Order 2222 aggregation standards reshape interconnection queues across regional transmission organizations. Arizona and Nevada industrial corridors concentrate utility-scale deployments where solar irradiance supports DC-coupled economics.
China
Provincial installation quotas in Shandong, Jiangsu and Inner Mongolia compress EPC timelines for state-backed procurement. The National Energy Administration's dual carbon targets mandate storage co-location with renewable tenders. Yangtze River Delta manufacturing clusters dominate lithium iron phosphate cell output for domestic and export markets.
Germany
EU Battery Regulation carbon disclosure mandates force supply chain reconfiguration for utility and commercial segments. The country's national energy regulator prioritizes grid-forming inverter standards for frequency stability. Bavaria and North Rhine-Westphalia host pilot saltwater battery deployments testing aqueous chemistry advantages.
Australia
NEM market price volatility drives merchant storage underwriting in Queensland and Victoria transmission zones. The country's renewable energy agency funds long-duration flow battery trials for multi-day shifting. Western Australian mining operations sustain off-grid solar-diesel-battery hybrid demand.
India
Central Electricity Authority storage mandates under state renewable purchase obligations open procurement windows for foreign integrators. The country's Bureau of Indian Standards drafts safety protocols for lithium-ion grid installations. Gujarat and Tamil Nadu industrial zones localize assembly to meet domestic content requirements.
Solar Storage System Market Competitive Landscape
Concentration sits with integrated technology conglomerates and specialized energy storage developers, creating a tiered structure where captive cell supply and software control layers determine margin capture. The vendor base splits between automotive-derived battery manufacturers, power electronics specialists, and turnkey EPC providers. Dominant competitive moves include backward integration into cathode material refining and strategic partnerships with grid operators for virtual power plant aggregation.
Among automotive-rooted cell suppliers, Tesla, BYD Company and LG Energy Solution exemplify divergent strategic archetypes. Tesla leverages integrated power electronics and software stacks across utility and residential deployments. BYD Company anchors its position through captive lithium iron phosphate supply and aggressive utility-scale bundling. LG Energy Solution occupies a position emphasizing cathode material verticality and automotive-derived architectures.
| Leading Market Players |
|---|
| Tesla |
| BYD Company |
| LG Energy Solution |
| Samsung SDI |
| ABB |
| Siemens Energy |
| Panasonic Holdings Corporation |
| Fluence Energy |
| General Electric Company |
| Others |
Pricing and Supply Chain Analysis
EU Battery Regulation carbon disclosure mandates gate both supplier qualification and price differentiation simultaneously, forcing exporters to reconfigure cathode sourcing to meet recycled content thresholds while compressing margins for non-compliant producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across utility-scale procurement, with premium-mid-economy pricing differentiation driven by certification grade and volume scale. Cost compression in standard-tier lithium-ion systems is intensifying because Yangtze River Delta manufacturing clusters achieve manufacturing scale. Residential end-users exhibit highest price sensitivity due to upfront capital constraints, while utility developers with IRA tax credit access show lowest sensitivity to per-kWh pricing.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and cathode precursors dominates over just-in-time preferences, reflecting raw material price volatility exposure. Manufacturing concentrates in China, South Korea, and Japan, drawing from Chilean lithium brine, Australian spodumene, and Indonesian nickel processing. Single-source vulnerability in refined cathode active material creates structural risk. Distribution runs through EPC contractors and turnkey integrators for utility deployments, with direct-to-installer channels serving residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Profitable participation in this market hinges on scarce capabilities in grid-forming inverter firmware and multi-vendor battery management system integration, assets concentrated among automotive-rooted cell suppliers and power electronics specialists.
For Market Incumbents: Fortify margin capture through backward integration into cathode material refining and captive lithium iron phosphate cell production. Emerging solid-state chemistry from Korean and Japanese developers threatens cycle-life superiority. Certification investment in EU Battery Regulation compliance services creates defensive moats against reconfigured supply chain entrants.
For New Entrants and Emerging Players: UL 9540A fire safety certification fast-tracks market access for residential and commercial segments where incumbent installer networks remain underpenetrated. India's state-level storage mandates under CEA guidelines offer the most penetrable geography. Software platforms stacking frequency regulation with demand charge management provide differentiated go-to-market positioning against hardware-centric competitors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across integrated containerized solutions as factory-assembly models displace field-built architectures. Long-term viability favors acquirers targeting power electronics specialists with IEEE 1547-2018 compliant inverter platforms. The signal to watch is FERC interconnection queue clearance rates as inflection indicator for deployable capital velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Refining | Captive lithium iron phosphate supply secures margin capture against raw material volatility in China procurement. |
| Grid-Forming Inverter Certification | IEEE 1547-2018 compliance unlocks California CAISO and Texas ERCOT interconnection approvals for utility developers. |
| Virtual Power Plant Aggregation Platform | FERC Order 2222 standards enable software-layer revenue stacking beyond hardware sales for residential integrators. |
| EU Battery Regulation Compliance Service | Carbon footprint disclosure mandates create advisory revenue streams for supply chain auditors serving German utility tenders. |
| Factory-Assembled Containerized Units | Plug-and-play deployment models compress EPC timelines in China's provincial quota system and congested US interconnection queues. |
Research Methodology
The analysis maps lithium-ion, flow battery, and saltwater electrochemical architectures, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary interviews combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases support bottom-up and top-down triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across chemistry type, end-use scale, application function, and control architecture segmentation. CAGRs derived from installed capacity buildout trajectories and system cost decline curves incorporate lithium carbonate price assumptions and IRA tax credit eligibility modeling throughout the forecast period.
Decision-makers should treat outputs as directional under continued IRA standalone storage incentive continuity and FERC Order 2222 aggregation standard adoption; material deviation would warrant model refresh. Revision becomes warranted when interconnection queue clearance durations or lithium raw material contract structures cross thresholds that alter project finance assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
South America Energy Storage Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market