
 Mexico Rooftop Solar Market | 2026-2036
Mexico Rooftop Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Rooftop Solar Market Foresight
Tier-one module certification is redrawing procurement standards across the Mexico Rooftop Solar Market. Bright Mexico leverages its installer network to dominate residential net metering deployments in Jalisco and Nuevo León. Canadian Solar anchors utility-scale module supply while extending distribution partnerships into rooftop channels. Enphase Energy specializes in microinverter architecture that differentiates its offering for shaded or complex roof geometries common in dense urban zones.
Mexico rooftop solar denotes photovoltaic arrays mounted on building structures, typically comprising silicon cells encased in tempered glass with aluminum framing, converting solar irradiance into alternating current through inverters for on-site consumption or grid export. Grid-tied systems lead installation volume due to favorable interconnection rules, though hybrid configurations incorporating battery storage represent the fastest-expanding segment as lithium-ion prices compress payback periods. Residential applications sustain the broadest addressable base, while commercial and industrial rooftops concentrate margin pools through larger project scales and direct power purchase structures.
CRE's net metering framework and CFE's interconnection standards shape system sizing and export compensation, while NOM-001-SEDE electrical safety codes govern installation quality and inverter specifications. BIS-aligned module testing requirements, administered through Mexico's national standards body, filter import quality and protect domestic channel integrity. Stakeholders must monitor regulatory stability around distributed generation credits and local content rules that could restructure supplier economics.
Market Dynamics
CRE's net metering reforms have compressed payback periods for distributed generation assets, triggering a wave of capital reallocation from commercial property portfolios toward behind-the-meter solar installations.
Growth Catalysts
- Net Metering Reforms:CRE's updated distributed generation framework allows surplus export at retail rates, improving project economics for industrial facilities in Querétaro and Guanajuato.
- Lithium-Ion Cost Compression:Battery pack price declines enable hybrid system configurations that hedge against CFE's time-of-use tariff volatility.
- Industrial Corridor Demand:Automotive and electronics manufacturers across central Mexico prioritize energy cost predictability through captive generation.
Market Restraints
- Import Duty Exposure:DGFT-aligned customs classifications create uncertainty for module shipments entering through Lázaro Cárdenas and Manzanillo ports.
- Grid Interconnection Queues:CFE's distribution utility backlog extends commissioning timelines for commercial projects beyond contracted completion dates.
- Financing Currency Mismatch:Dollar-denominated equipment costs against peso revenue streams elevate hedging requirements for non-exporting offtakers.
Strategic Opportunities
- Yucatán Peninsula Expansion:Merida's commercial real estate stock remains underpenetrated relative to irradiance levels, offering first-mover positioning for installer networks.
- Agrivoltaic Pilots:Dual-use arrays combining strawberry and berry cultivation with generation are attracting SADER-linked rural development financing.
- Digital Platform Distribution:Online marketplace channels for system design and installer matching are reducing customer acquisition costs in tertiary cities.
Industry Challenges
- Certification Bottlenecks:BIS-aligned NOM testing protocols for inverters create 8-12 week approval delays that compress construction windows.
- Electrical Workforce Scarcity:Qualified low-voltage technicians familiar with NOM-001-SEDE grounding requirements remain concentrated in Mexico City and Monterrey.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Rooftop Solar Market |
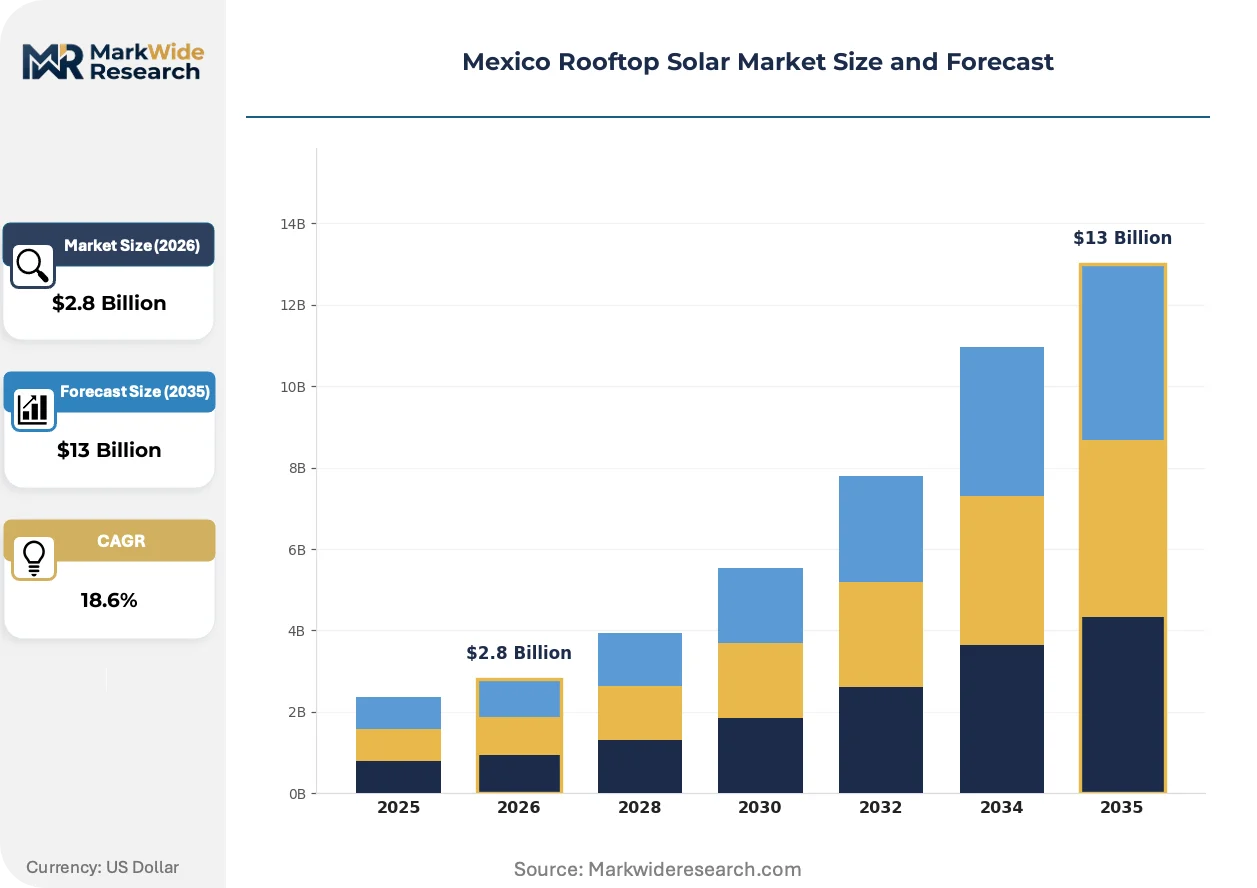
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Grid-Tied, Off-Grid, Hybrid, Battery Storage Installation Segment: Residential, Commercial, Industrial, Agricultural Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Self-Consumption, Feed-In Tariff, Net Metering, Energy Savings |
| Companies Covered | Bright Mexico, 3Tek SOLAR, SunPower Corporation, Canadian Solar, Enphase Energy, Tesla Inc., Positive Energy Solar, Hanwha Q Cells, Enlight Mexico, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Rooftop Solar Market Shifts & Advancements
Module-level power electronics and digital twin modeling are compressing design-to-commissioning cycles while improving performance forecasting accuracy for complex roof geometries.
Microinverter architectures are displacing string inverter dominance in shaded urban installations. Commercial property managers in Mexico City's Roma and Condesa districts favor module-level monitoring for granular fault detection. This granularity is displacing traditional O&M contracts that relied on annual physical inspections rather than real-time alerts.
CRE's distributed generation registry modernization mandates digital interconnection applications with standardized single-line diagrams. Industrial developers in Nuevo León report 40% faster permitting through the new portal. The policy shift most acutely affects mid-scale commercial projects that previously navigated paper-based submissions through regional CFE offices.
Buyer preference is migrating from equipment ownership toward energy-as-a-service structures. Textile manufacturers in Puebla and Tlaxcala increasingly sign 10-15 year power purchase agreements with third-party asset owners. This shift is most visible in the Bajío region where foreign direct investment facilities face parent-company capital rationing for non-core infrastructure.
Mexico Rooftop Solar Market Segmentation
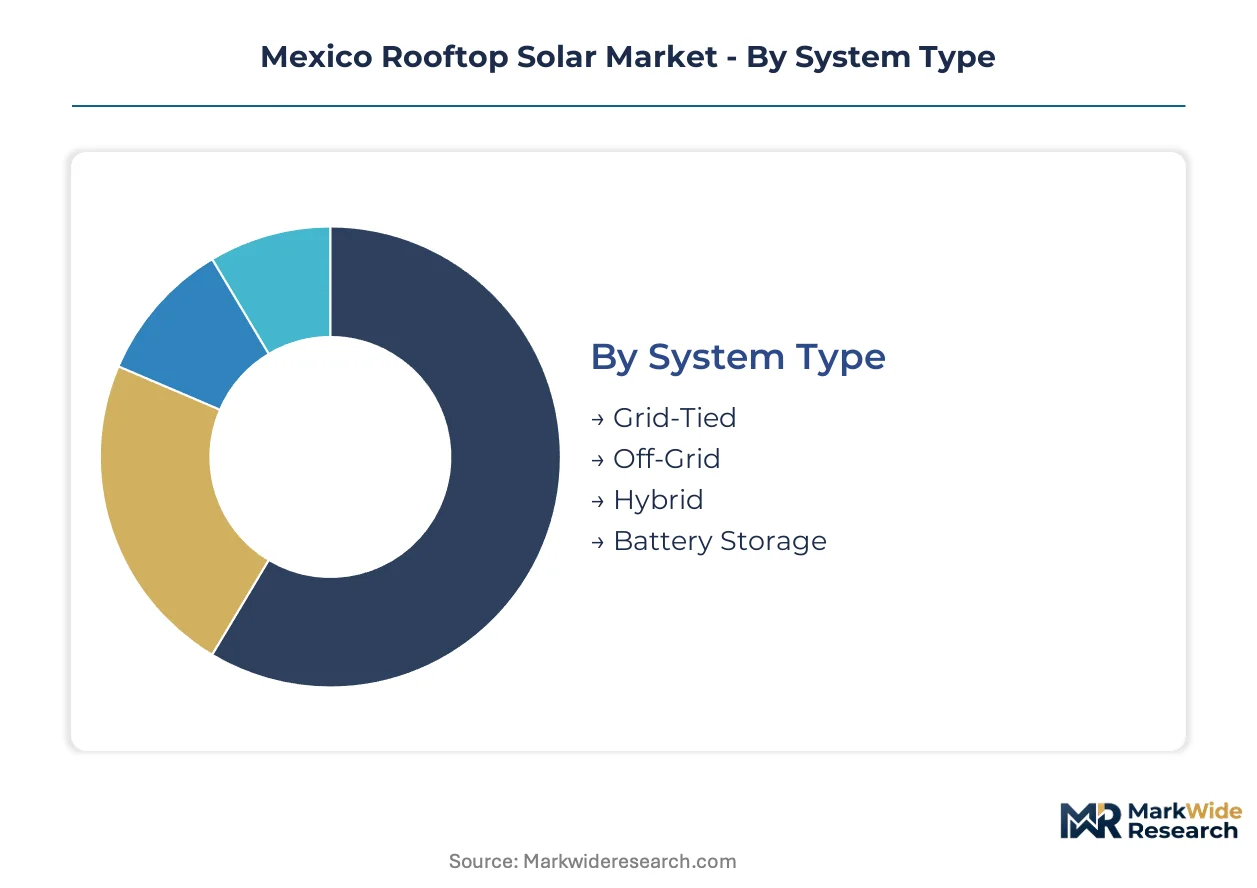
Segmentation in the Mexico Rooftop Solar Market reveals how regulatory frameworks, irradiance patterns, and tariff structures create divergent value pools across system configurations and customer types. Understanding these divisions illuminates where capital deployment concentrates and where technology transitions accelerate.
System Type:
Domestic demand centers on grid-connected architectures, while export-oriented manufacturing facilities in Baja California and border maquiladoras increasingly specify hybrid configurations to ensure production continuity.
- Grid-Tied:Direct interconnection to CFE distribution infrastructure dominates installation volume across Mexico City and Guadalajara metropolitan zones. CRE's net metering reforms allow surplus export at retail rates, compressing payback periods for commercial property owners in Querétaro's industrial parks.
- Hybrid:Battery-coupled systems combine photovoltaic generation with lithium-ion storage to hedge against CFE's time-of-use tariff volatility. Automotive suppliers in Guanajuato's Silao cluster prioritize these configurations to maintain energy cost predictability under parent-company capital rationing.
- Off-Grid:Standalone arrays serve rural telecommunications towers and isolated agricultural operations across Oaxaca and Chiapas where grid extension remains uneconomical.
- Battery Storage:Retrofit installations on existing rooftop arrays accelerate in Baja California Sur where diesel generator dependence previously dominated commercial backup strategies.
Grid-tied configurations hold the largest share; momentum sits with hybrid systems.
Installation Segment:
Cost tier differentiation separates premium engineering for industrial scale from standardized residential packages, with commercial applications commanding the widest margin spreads through direct power purchase structures.
- Industrial:Megawatt-scale rooftop arrays on manufacturing facilities require structural engineering certification for load-bearing capacity and NOM-001-SEDE electrical compliance. Electronics assemblers in Tijuana and Ciudad Juárez specify these systems under long-term energy-as-a-service contracts to bypass capital expenditure constraints.
- Commercial:Mid-scale deployments on retail and office properties concentrate in Mexico City's Roma, Condesa, and Polanco districts. Property managers favor module-level monitoring architectures that reduce operations and maintenance costs through real-time fault detection rather than annual physical inspections.
- Residential:Distributed generation registries in Jalisco and Nuevo León track rapid deployment growth among net metering participants. Bright Mexico's installer network captures volume through standardized permitting packages that navigate CRE's digital interconnection portal.
- Agricultural:Dual-use agrivoltaic pilots combining strawberry cultivation with generation attract SADER-linked rural development financing in Michoacán's berry-growing regions.
Industrial installations generate the highest revenue per project; residential applications expand the addressable base most quickly.
Technology:
Module efficiency ratings and temperature coefficients determine technology selection across Mexico's altitude-varying irradiance zones, from coastal humidity to highland clarity.
- Monocrystalline:Single-crystal silicon cells deliver superior conversion efficiency in space-constrained urban rooftops. Dense installations in Monterrey's San Pedro Garza García commercial district specify these modules to maximize generation per square meter of available roof area.
- Bifacial:Dual-sided cell architectures capture reflected irradiance from white membrane roofing common in industrial facilities. Bajío region automotive plants specify bifacial glass-glass modules for enhanced durability against hail and thermal cycling.
- Polycrystalline:Multi-crystal silicon offers cost-advantaged entry points for price-sensitive residential segments in tertiary cities where module efficiency premiums do not justify expenditure.
- Thin-Film:Cadmium telluride and copper indium gallium selenide technologies perform in high-temperature environments where crystalline silicon efficiency degrades. Limited deployment concentrates in Yucatán Peninsula commercial applications.
Monocrystalline technology dominates current procurement; bifacial modules are climbing the fastest.
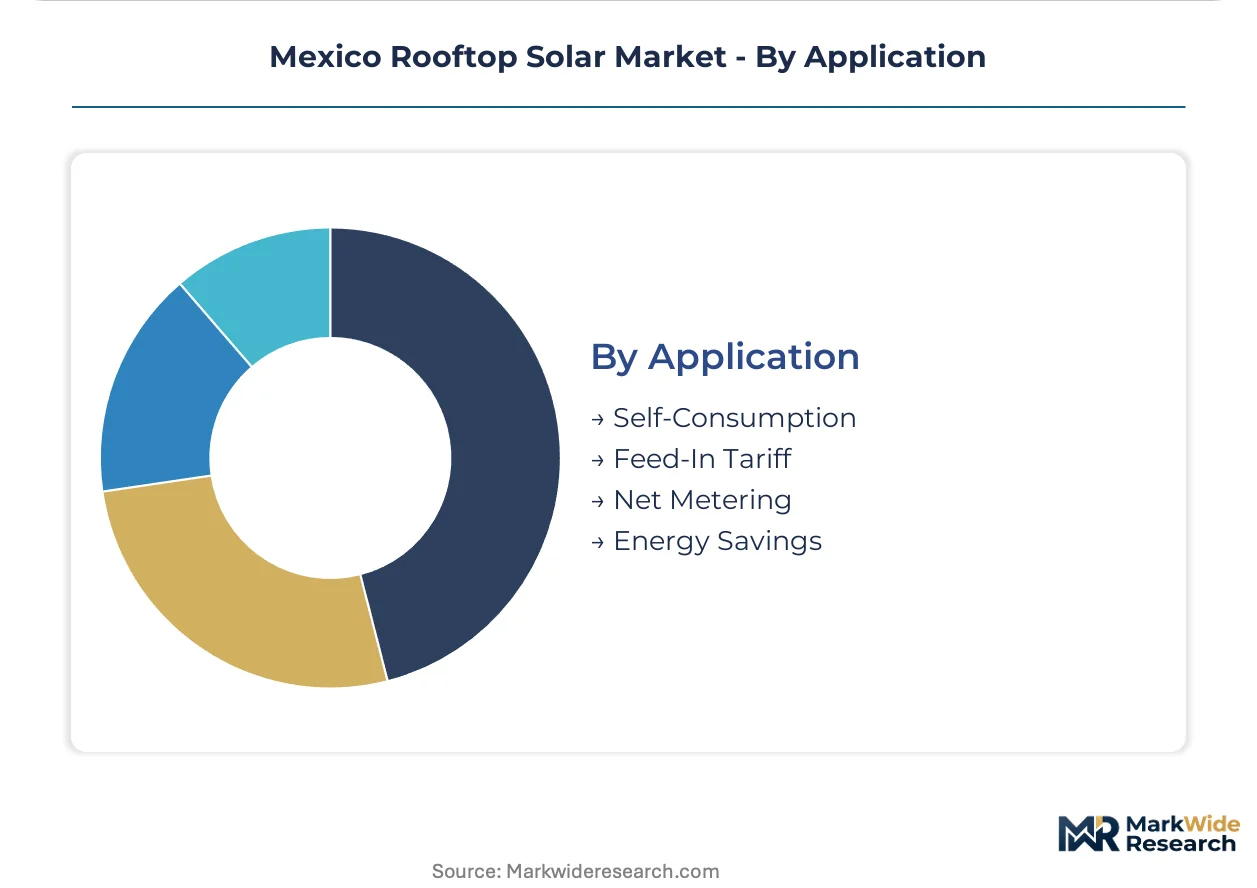
Application:
Customer type and regulatory engagement depth separate self-consumption optimization from grid-interactive revenue models, with tariff structure volatility reshaping preference hierarchies.
- Self-Consumption:Behind-the-meter generation eliminates transmission and distribution charges for industrial facilities in Puebla and Tlaxcala textile clusters. Captive use maximizes value capture where CFE's commercial tariffs include substantial fixed components.
- Net Metering:CRE's distributed generation framework permits surplus export at retail rates, enabling commercial property owners in Guadalajara to size systems above instantaneous load. Digital registry modernization has compressed permitting timelines by 40% for mid-scale projects.
- Feed-In Tariff:Fixed-price export contracts attract limited participation where regulatory stability concerns persist; most developers prefer net metering's retail rate linkage.
- Energy Savings:Performance-contracting structures guarantee demand reduction for hospitality operators in Cancún and Los Cabos where air conditioning loads dominate consumption profiles.
Self-consumption applications command the largest installed base; net metering configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's rooftop solar expansion reflects a structural trade deficit in photovoltaic equipment, with module imports from Asia dominating supply while domestic installation capacity concentrates in specific industrial corridors. Regional deployment patterns track manufacturing density, irradiance levels, and regulatory clarity across sub-national markets.
Mexico City Metro
Commercial property owners in Roma, Condesa, and Polanco districts drive mid-scale deployment to offset CFE's commercial tariff volatility. CRE's net metering reforms allow surplus export at retail rates, compressing payback periods for office and retail assets. The metropolitan zone hosts the densest concentration of qualified low-voltage technicians familiar with NOM-001-SEDE grounding requirements.
Nuevo León
Automotive suppliers and electronics manufacturers across Monterrey and San Pedro Garza García prioritize captive generation under energy-as-a-service contracts. The state's industrial parks specify monocrystalline modules for space-constrained rooftops. CFE's distribution utility maintains shorter interconnection queues here than in southern states, accelerating commissioning timelines.
Jalisco
Residential net metering participation expands fastest in Guadalajara's metropolitan zone, where standardized permitting packages navigate CRE's digital interconnection portal. Bright Mexico's installer network captures volume through turnkey deployment models. The state's CRE distributed generation registry shows the steepest residential growth curve outside Mexico City.
Bajío Region
Textile manufacturers in Puebla and Tlaxcala sign long-term power purchase agreements to bypass parent-company capital rationing for non-core infrastructure. Bifacial glass-glass modules dominate automotive plant specifications in Guanajuato's Silao cluster for hail durability. SADER-linked rural development financing supports agrivoltaic pilots combining strawberry cultivation with generation in Michoacán.
Northern Border States
Export-oriented maquiladoras in Tijuana and Ciudad Juárez specify hybrid configurations to ensure production continuity against grid instability. Battery retrofit installations accelerate in Baja California Sur where diesel generator dependence previously dominated commercial backup strategies. DGFT-aligned customs classifications create uncertainty for module shipments entering through Lázaro Cárdenas and Manzanillo ports.
Mexico Rooftop Solar Market Competitive Landscape
Listed leaders compete with private specialists across financing structures and customer acquisition channels. The vendor base organizes around three strategic archetypes: integrated module suppliers with distribution partnerships, pure-play installation networks with regional density, and energy-as-a-service platforms that retain asset ownership. Consolidation pressures concentrate in the residential tier where customer acquisition costs determine viability. Dominant competitive moves include backward integration into module supply and geographic expansion through installer network acquisitions.
Within the premium-tier module segment, Canadian Solar and SunPower Corporation occupy positions as North American-listed suppliers with established distribution channels. Among microinverter specialists, Enphase Energy exemplifies technology-driven differentiation for complex urban roof geometries. Bright Mexico represents the regional installation-network archetype, anchoring residential deployment in high-growth states through standardized permitting and digital customer acquisition.
| Leading Market Players |
|---|
| Bright Mexico |
| 3Tek SOLAR |
| SunPower Corporation |
| Canadian Solar |
| Enphase Energy |
| Tesla Inc. |
| Positive Energy Solar |
| Hanwha Q Cells |
| Enlight Mexico |
| Others |
Supply & Pricing Matrix
NOM-001-SEDE certification requirements gate both module import qualification and installer labor pricing tiers simultaneously, compressing margins for uncertified competitors while allowing accredited firms to capture premium positioning in Mexico City's commercial corridor.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across the Mexico rooftop solar market. Three-tier pricing stratifies across premium certified installers, standard regional providers, and economy-tier uncertified contractors. Price differentiation hinges on NOM-001-SEDE compliance status and module efficiency ratings. Cost compression in the economy tier is intensifying because lithium-ion battery pack imports face currency mismatch hedging requirements. Residential segments in Jalisco and Nuevo León exhibit highest price sensitivity, while automotive manufacturers in Guanajuato prioritize energy cost predictability over capital expenditure minimization.
Supply Chain Analysis
Inventory lead times for monocrystalline modules stretch 8-12 weeks due to BIS-aligned testing protocol backlogs at Mexico's national standards body. Module supply concentrates in China, South Korea, and Vietnam, with tempered glass and aluminum framing drawing from domestic foundries. Raw material dependencies center on polysilicon ingots, EVA encapsulant films, and lithium carbonate for storage coupling. Tariff exposure through DGFT-aligned customs classifications at Lázaro Cárdenas and Manzanillo ports creates shipment uncertainty. Distribution runs through Bright Mexico's installer network and Canadian Solar's distribution partnerships into regional EPC channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRE's net metering reforms constitute a regulatory inflection that disrupts traditional utility dependency, creating asymmetric growth windows for capital deployment across behind-the-meter generation assets.
For Market Incumbents: Consolidate installer network density in Jalisco and Nuevo León before digital platform competitors erode customer acquisition economics. Acquire qualified low-voltage technician capacity in tertiary cities to preempt workforce scarcity bottlenecks. Backward integration into module supply buffers DGFT-aligned tariff exposure at Mexican ports. For New Entrants and Emerging Players: Digital marketplace channels for system design and installer matching represent a service-layer gap where incumbents under-serve tertiary cities beyond Mexico City and Guadalajara. Merida's commercial real estate stock offers the most penetrable geography given irradiance levels against deployment density. Agrivoltaic pilot financing through SADER-linked rural development programs provides a differentiated go-to-market angle in Michoacán's berry-growing regions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across residential net metering deployments as standardized permitting packages compress customer acquisition costs. Long-term viability over a 5-10 year window favors installer networks with CRE digital portal navigation capabilities and regional permitting expertise. Acquisition targets should demonstrate NOM-001-SEDE certification depth and monocrystalline module supply relationships. The signal to watch is CFE interconnection queue clearance rates as an indicator of commissioning velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Network Consolidation | Bright Mexico's density in Jalisco demonstrates scalable customer acquisition economics. |
| Backward Integration into Module Supply | Canadian Solar's distribution partnerships reduce DGFT-aligned customs exposure. |
| Digital Interconnection Portal Navigation | CRE's registry modernization rewards firms with standardized permitting capabilities. |
| Agrivoltaic Pilot Development | SADER-linked financing in Michoacán opens rural deployment channels. |
| Hybrid System Configuration Expansion | Automotive suppliers in Guanajuato prioritize battery-coupled generation for tariff hedging. |
Research Methodology
A standing panel of EPC contractors, CFE interconnection officers, commercial property managers, and module procurement leads provided ongoing calibration across primary interview cycles. Secondary validation drew from CRE distributed generation registry filings, customs import records at Lázaro Cárdenas and Manzanillo, NOM certification databases, and CFE tariff schedule publications. Bottom-up project pipeline aggregation triangulated against top-down irradiance-adjusted addressable roof area estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled system type, installation segment, technology tier, and application mode as core segmentation dimensions. CAGRs derived from installer deployment velocity trajectories and module import volume trends. Forecast inputs incorporated lithium-ion battery cost compression curves and CRE regulatory stability assumptions.
Underlying assumptions cover net metering retail rate continuity and NOM-001-SEDE enforcement consistency, with deviation risk concentrated in DGFT customs reclassifications and CFE interconnection queue clearance volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Solar Phone Chargers Market