
 Cerumenolytic Agents Market | 2026-2036
Cerumenolytic Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Cerumenolytic Agents Market Outlook
Homecare buyers are rotating toward cerumenolytic products as direct-to-consumer formulations gain shelf space and clinical validation. Prestige Consumer Healthcare leverages brand equity in retail pharmacy channels to sustain household penetration. GlaxoSmithKline anchors professional trust through clinician-directed distribution networks. Eosera Inc. specializes in biotechnology-derived formulations that differentiate its portfolio from commodity peroxide solutions.
Cerumenolytic agents comprise topical formulations designed to soften, fragment, or dissolve cerumen through surfactant action, oxidative release, or osmotic hydration, typically containing active concentrations of carbamide peroxide, docusate sodium, or urea hydrogen peroxide in aqueous or glycerin bases. Their primary commercial purpose is to enable non-invasive ear canal clearance without mechanical trauma or irrigation complications. Hydrogen peroxide formulations occupy the mature volume tier with established OTC acceptance and low unit economics, while docusate sodium segments attract professional preference due to gentler epithelial compatibility and reduced ototoxicity risk. Ear wax removal applications dominate value generation, though preventative care positioning in homecare channels represents the fastest-growing demand pool as consumers shift from reactive treatment to routine auditory hygiene.
The FDA's OTC monograph system governs active ingredient eligibility and labeling standards for cerumenolytic products in the United States, while the EPA regulates manufacturing facility emissions for peroxide-based production. These frameworks elevate compliance costs for new entrants but reinforce incumbent quality signaling that shapes prescriber and pharmacist recommendation patterns. Stakeholders must monitor evolving monograph reform timelines and homecare reimbursement policy shifts to calibrate portfolio allocation between professional and consumer channels.
Market Dynamics
The FDA's OTC monograph reform timeline is compressing product development cycles while expanding self-administration protocols, forcing manufacturers to recalibrate formulations for direct-to-consumer channels before professional distribution networks mature.
Growth Catalysts
- OTC Monograph Modernization:The FDA's streamlined review pathways accelerate ingredient eligibility determinations for carbamide peroxide and docusate sodium formulations, reducing time-to-shelf for novel cerumenolytic entrants.
- Aging Demographics:The United States, Germany, and Japan exhibit elevated cerumen impaction incidence among populations over 65, driving pharmacy channel demand for home-administered solutions.
- Biotechnology Formulation Advances:Enzymatic cerumenolysis using recombinant lipases offers reduced epithelial irritation compared to oxidative chemistry, attracting clinician preference in otolaryngology practices.
Market Restraints
- Peroxide Feedstock Volatility:Hydrogen peroxide supply concentrates among industrial chemical producers in the US Gulf Coast and northwestern Europe, exposing formulation costs to energy-price transmission.
- Ototoxicity Liability Thresholds:The EPA's manufacturing emission standards for peroxide-based production elevate facility compliance capital requirements, disadvantaging small-scale entrants.
- Mechanical Irrigation Substitution:Microsuction and warm-water irrigation systems in clinical settings displace pharmaceutical solutions for immediate cerumen removal, limiting acute-care prescription volumes.
Strategic Opportunities
- Preventative Care Positioning:Monthly-use maintenance formulations for hearing aid wearers create recurring revenue streams in retail pharmacy channels previously dominated by reactive treatment purchases.
- Pediatric Formulation Gaps:Gentler surfactant bases with reduced foaming profiles address unmet demand for infant and toddler ear hygiene, where hydrogen peroxide concentrations face parental resistance.
- Telehealth Integration:Remote otoscopic examination platforms enable clinician-supervised self-administration protocols, expanding reimbursable homecare indications beyond current OTC boundaries.
Industry Challenges
- Formulation Stability Expertise:Urea hydrogen peroxide shelf-life extension requires specialized moisture-barrier packaging engineering that exceeds conventional pharmaceutical manufacturing capabilities.
- Monograph Reform Uncertainty:Pending FDA determinations on active ingredient concentration ceilings force parallel development tracks, inflating R&D expenditure without guaranteed pathway approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerumenolytic Agents Market |
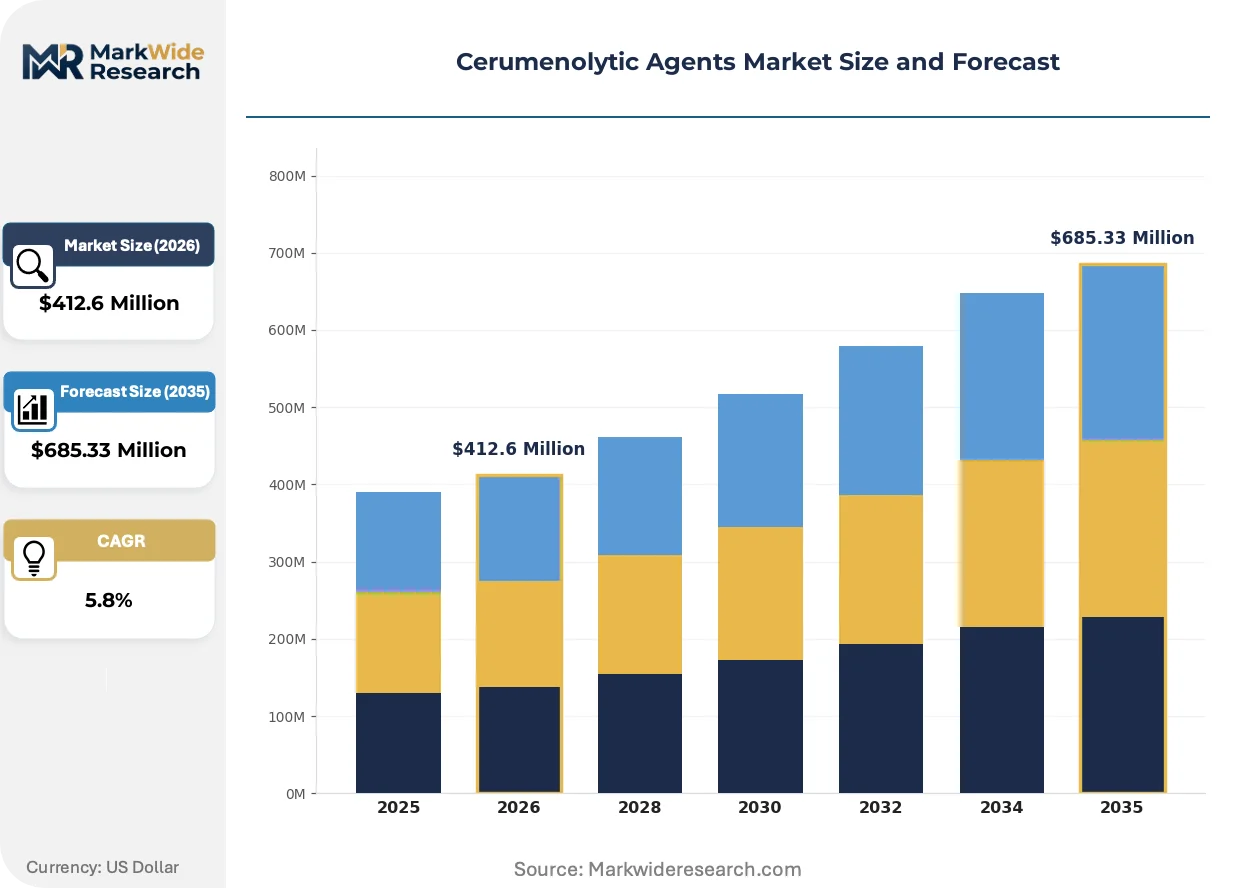
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen Peroxide, Saline Solution, Docusate Sodium, Urea Hydrogen Peroxide Application: Ear Wax Removal, Ear Health Maintenance, Preventative Care, Post-Procedure Care End User: Clinics, Hospitals, Homecare, Pharmacies Delivery Mode: Topical, Liquid Drops, Ear Syringe, Spray |
| Companies Covered | Prestige Consumer Healthcare Inc., GlaxoSmithKline, Cipla, Dr. Reddy's Laboratories, Church & Dwight, Medline Industries, Henry Schein Inc., Cardinal Health, Eosera Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerumenolytic Agents Market Strategic Shifts
Formulation chemistry and distribution architecture are diverging simultaneously, with biotechnology-derived agents challenging commodity peroxide dominance while direct-to-consumer channels bypass traditional clinician gatekeeping.
Enzymatic cerumenolysis employing recombinant triacylglycerol lipases targets lipid-dominant cerumen subtypes with targeted substrate specificity. Otolaryngology practices in tertiary care centers are piloting these formulations for patients with recurrent impaction and perforated tympanic membranes. The technology is bifurcating the market into oxidative commodity tiers and precision biologic segments with divergent pricing architectures.
The FDA's OTC monograph modernization initiative is consolidating active ingredient review timelines while introducing post-market surveillance obligations for novel formulations. Manufacturing facilities must now demonstrate stability data across expanded temperature ranges before monograph listing approval. Small-cap entrants lacking legacy quality infrastructure face accelerated compliance costs that favor established pharmaceutical manufacturers with captive analytical capabilities.
Pharmacy benefit managers are unbundling cerumenolytic reimbursement from comprehensive audiology service contracts, creating standalone OTC purchasing incentives for Medicare Advantage enrollees. Retail chains are responding with private-label formulation development that mimics branded active concentrations at reduced unit economics. This shift concentrates volume in mass-market channels while compressing margins available for professional detailing and clinician education investments.
Cerumenolytic Agents Market Segmentation
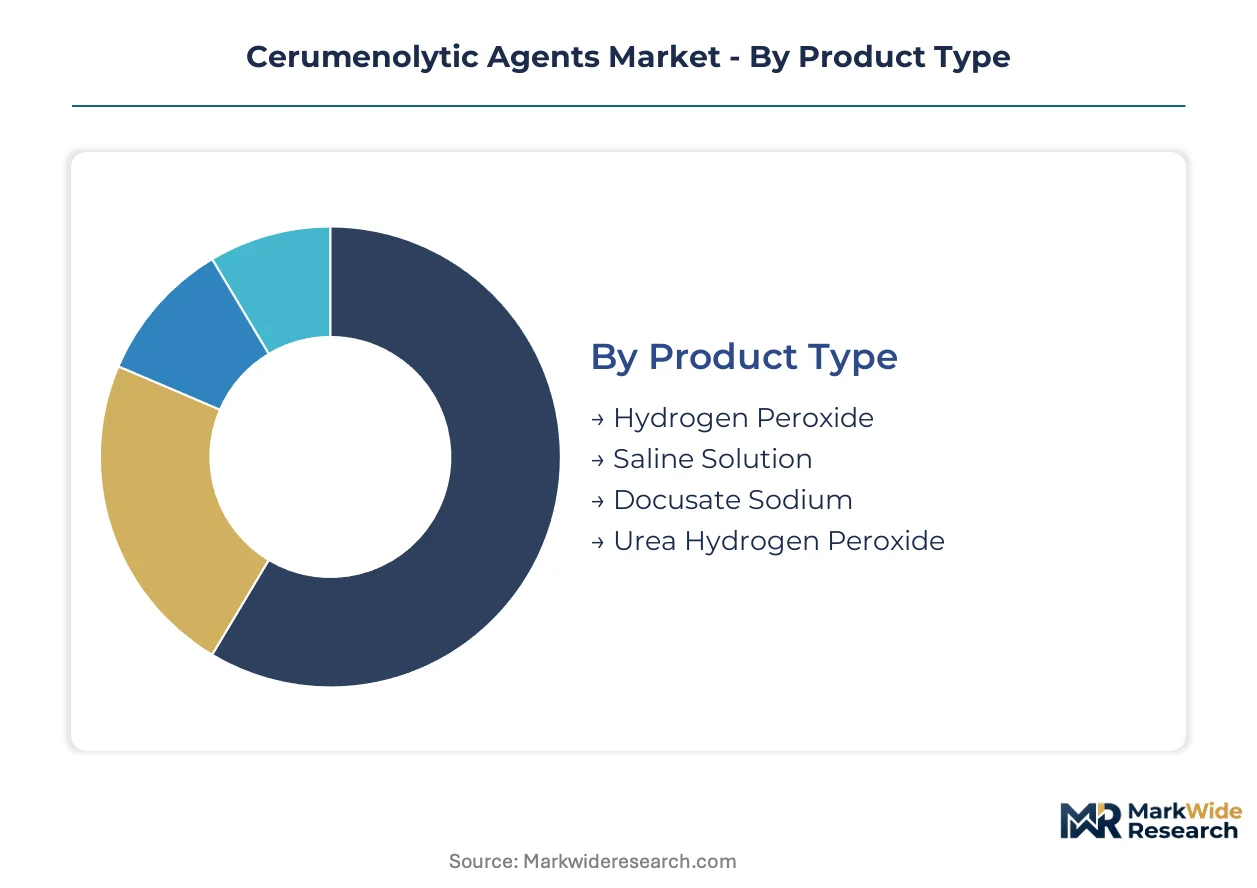
Cerumenolytic formulations distribute through divergent channel architectures depending on their active chemistry and intended use setting. Understanding these pathway distinctions enables manufacturers to calibrate packaging, pricing, and clinical education investments against actual purchase behavior.
Product Type:
Channel mix varies sharply by oxidative versus surfactant chemistry, with peroxide formulations dominating mass retail while docusate sodium concentrates in professional dispensing.
- Hydrogen Peroxide:Aqueous solutions at concentrations of 3-6% generate the highest unit volumes through pharmacy and grocery retail. United States households purchase these formulations most heavily, where FDA OTC monograph recognition eliminates prescription friction. Shelf placement in analgesics aisles drives impulse replenishment cycles.
- Docusate Sodium:Anionic surfactant formulations at 0.5% concentration exhibit superior epithelial compatibility for tympanic membrane perforation cases. Otolaryngology clinics in Germany and Japan specify these agents for patients requiring repeated cerumenolysis, creating concentrated demand within hospital procurement systems.
- Saline Solution:Isotonic formulations serve irrigation-compatible patients seeking non-chemical softening, particularly in pediatric applications where parental peroxide aversion is pronounced.
- Urea Hydrogen Peroxide:Stabilized adduct formulations extend shelf stability beyond conventional peroxide solutions, commanding premium positioning in direct-to-consumer subscription channels.
By volume, hydrogen peroxide leads. By growth pace, docusate sodium is ahead.
Application:
Revenue concentration tilts toward acute intervention, though preventative positioning is capturing margin expansion through recurring purchase structures.
- Ear Wax Removal:Reactive treatment for complete or partial cerumen impaction generates the majority of current pharmaceutical expenditure. Acute presentations in United States urgent care centers and United Kingdom general practices sustain prescription volumes for clinician-administered formulations.
- Preventative Care:Monthly maintenance protocols for hearing aid wearers and elderly populations with excessive cerumen production represent the steepest expansion trajectory. Retail pharmacy chains in Japan and Australia are merchandising these formulations adjacent to hearing aid batteries and accessories.
- Ear Health Maintenance:General hygiene positioning targets consumers without diagnosed impaction, competing with mechanical cleaning devices for share of ear care routines.
- Post-Procedure Care:Cerumenolysis following otologic surgery or foreign body removal follows institutional procurement pathways in tertiary hospitals, with formulary placement contingent on otolaryngology department preference.
Acute removal commands current revenue. Preventative protocols are climbing the fastest.
End User:
Institutional procurement patterns diverge from consumer self-selection on the basis of reimbursement architecture and clinical supervision requirements.
- Homecare:Self-administered drops and sprays purchased through retail channels or e-commerce platforms are gaining share as telehealth validation expands. United States Medicare Advantage plans in Florida and Arizona are piloting OTC benefit coverage for enrollees over 65.
- Clinics:Outpatient otolaryngology and primary care settings utilize higher-concentration formulations with irrigation compatibility, particularly in Germany where statutory insurance reimburses professional cerumen removal.
- Hospitals:Inpatient and emergency department use concentrates in academic medical centers with audiology consultation availability, with procurement governed by pharmacy and therapeutics committees.
- Pharmacies:Community pharmacy counters function as both purchase point and clinical advice source, with pharmacist recommendation influencing brand selection in France and Spain.
Homecare volumes exceed institutional purchases. Clinic channel expansion is gaining share fastest.
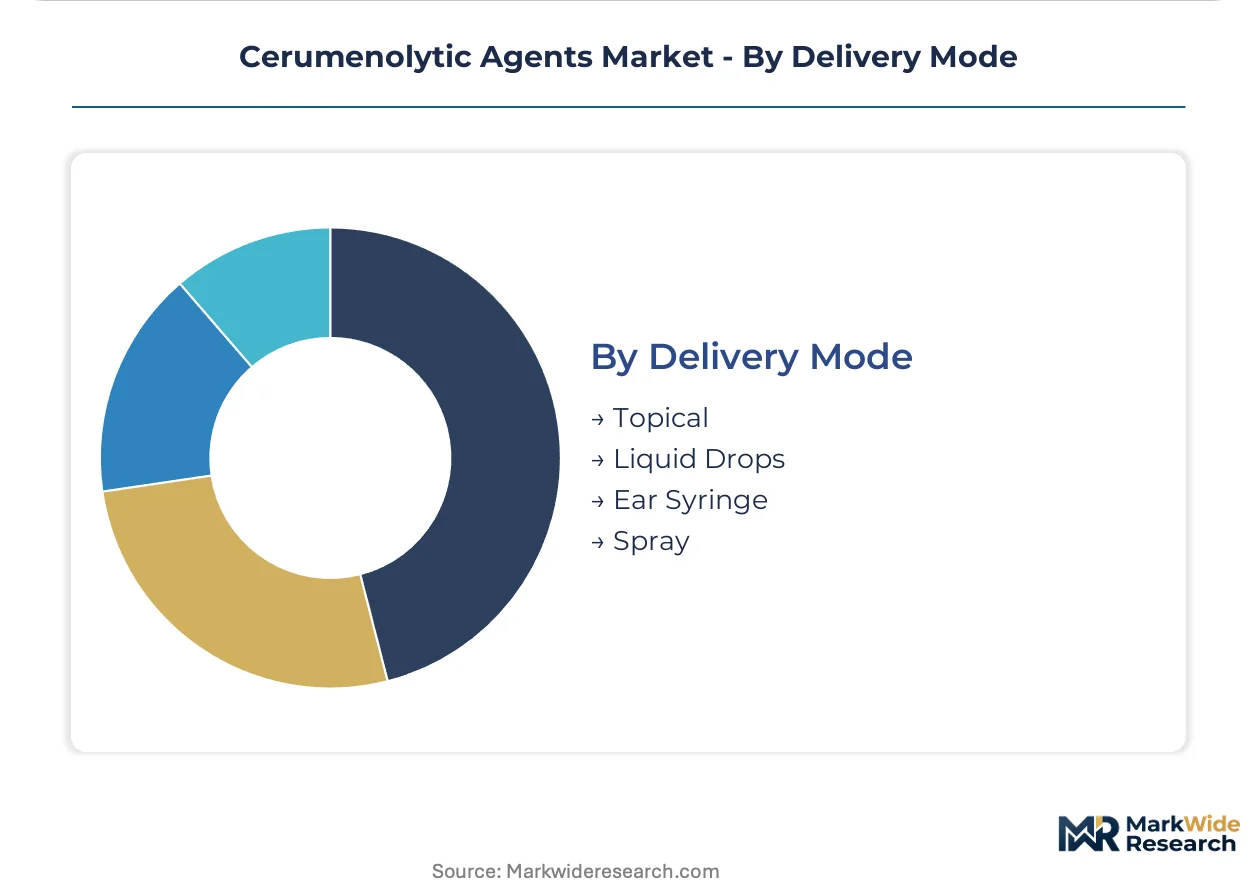
Delivery Mode:
Packaging format determines storage requirements, dosing precision, and patient compliance rates across age demographics.
- Liquid Drops:Dropper bottles with calibrated tips enable precise volumetric dosing for narrow ear canals. This format dominates pediatric applications in Italy and pediatrician recommendations in Canada.
- Ear Syringe:Integrated soft-bulb devices combining reservoir and delivery mechanism support single-use protocols in travel and acute care settings, with hospital infection control departments favoring disposable construction.
- Topical:General category encompassing all direct ear canal application methods, with formulation viscosity determining dwell time and softening efficacy.
- Spray:Metered-dose aerosol formulations reduce patient dexterity requirements and enable self-administration for elderly users with limited manual mobility, gaining traction in Japanese homecare markets.
Drop bottles lead by unit volume. Spray formats are expanding most quickly among aging demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy chains and hearing aid clinics concentrate purchasing power in aging urban corridors across five countries with divergent reimbursement architectures.
United States
Medicare Advantage enrollees in Florida and Arizona drive pharmacy counter demand for home-administered drops. The FDA's OTC monograph framework governs carbamide peroxide eligibility and labeling standards. Retail chains in the Sun Belt merchandise cerumenolytics adjacent to hearing aid batteries, capturing recurring purchase cycles among snowbird populations.
Germany
Statutory insurance reimbursement for professional cerumen removal sustains clinic-channel volumes for docusate sodium formulations. The EMA's medical device borderline determinations influence whether enzymatic formulations receive pharmaceutical or device classification. Hospital procurement in Bavaria and North Rhine-Westphalia concentrates demand for irrigation-compatible surfactant solutions.
Japan
Elderly homecare markets in Kanto and Kansai regions absorb metered-dose spray formats designed for limited manual dexterity. PMDA's post-market surveillance protocols for otologic products elevate documentation requirements for new entrants. Tokyo-based pharmacy chains pilot subscription models linking cerumenolytic replenishment to hearing aid maintenance schedules.
United Kingdom
NHS general practices in England sustain prescription volumes for acute impaction cases despite mechanical irrigation substitution. The MHRA's alignment with FDA monograph reforms accelerates parallel product registration timelines. Community pharmacy counters in Greater Manchester and Birmingham function as clinical advice nodes influencing brand selection.
Australia
Hearing aid wearers in New South Wales and Victoria generate preventative-care demand through retail pharmacy channels. The TGA's OTC registration pathways for ear care products require stability data across expanded temperature ranges. Sydney-based audiology clinics bundle cerumenolytic prescriptions with device fitting appointments, creating integrated service revenue.
Cerumenolytic Agents Market Competitive Environment
Player mix skews toward diversified consumer health conglomerates with established pharmacy distribution infrastructure. Three to five manufacturers capture the majority of shelf space in mass retail and professional dispensing channels. Strategic archetypes include brand-equity incumbents leveraging retail pharmacy relationships, biotechnology specialists pursuing enzymatic differentiation, and private-label suppliers compressing unit economics for chain store contracts. Competitive moves concentrate on portfolio diversification into preventative-care positioning and geographic expansion through regulatory pathway harmonization.
Among diversified consumer health conglomerates, Prestige Consumer Healthcare Inc. and GlaxoSmithKline occupy positions anchored by retail pharmacy channel density and clinician-directed distribution networks respectively. Eosera Inc. exemplifies the biotechnology specialist archetype, with its corporate name signaling recombinant enzyme formulation capabilities distinct from commodity peroxide chemistry. These three entities collectively represent the tiered structure separating mass-market oxidative solutions from precision biologic segments with divergent pricing architectures.
| Leading Market Players |
|---|
| Prestige Consumer Healthcare Inc. |
| GlaxoSmithKline |
| Cipla |
| Dr. Reddy's Laboratories |
| Church & Dwight |
| Medline Industries |
| Henry Schein Inc. |
| Cardinal Health |
| Eosera Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for carbamide peroxide feedstock lock in both supply access and price visibility for established manufacturers, insulating formulation costs from Gulf Coast energy volatility while compressing margin buffers for new entrants lacking legacy supplier relationships.
Pricing Analysis
Cost-plus contracts with ethylene feedstock indexation govern hydrogen peroxide procurement, anchoring formulation economics to regional natural gas benchmarks. Three-tier pricing structure across enzymatic biologics, stabilized peroxide adducts, and commodity peroxide solutions separates premium Eosera formulations from private-label retail offerings. Pricing pressure stems from pharmacy benefit manager unbundling of cerumenolytic reimbursement, intensifying cost compression in mass-market oxidative tiers. Homecare consumers exhibit highest price sensitivity, while otolaryngology clinics prioritize epithelial compatibility over unit economics.
Supply Chain Analysis
Inbound logistics costs from Houston and Rotterdam port congestion elevate working capital requirements for peroxide-based raw material procurement, particularly for European manufacturers dependent on transatlantic chemical tanker availability. Active ingredient production concentrates in the United States, Germany, and China, with carbamide peroxide synthesis anchored in the US Gulf Coast and docusate sodium manufacturing centered on the Rhine-Ruhr chemical cluster. Formulation draws from hydrogen peroxide, anionic surfactants, and recombinant enzyme inputs. Single-source vulnerability in lipase biotechnology feedstock from specialized fermentation facilities represents the dominant structural risk. Distribution runs through retail pharmacy chains, hospital procurement systems, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cerumenolytic agents sit in early-cycle expansion as self-administration protocols and preventative-care positioning extend addressable demand beyond acute impaction treatment into recurring monthly-use markets.
For Market Incumbents: Secure formulary placement in Medicare Advantage OTC benefit pilots before monograph reform consolidates eligibility pathways, while defending shelf space against private-label compression through clinician education investments in docusate sodium differentiation. Backward integration into urea hydrogen peroxide stabilization technology mitigates moisture-barrier packaging cost escalation from specialized engineering requirements. For New Entrants and Emerging Players: Differentiate on enzymatic cerumenolysis for perforated tympanic membrane cases where oxidative chemistry faces contraindication, targeting otolaryngology practices in tertiary care centers with reimbursement-compatible precision biologic positioning. Pediatric formulation gaps present the most penetrable white space, with gentler surfactant bases addressing parental resistance to peroxide concentrations. Go-to-market through telehealth-integrated remote otoscopic platforms enables clinician-supervised homecare protocols. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology specialists with recombinant lipase pipelines and captive analytical capabilities, as FDA monograph modernization elevates compliance barriers favoring established quality infrastructure. Long-term viability centers on recurring revenue models in preventative-care positioning rather than acute treatment commoditization. The signal to watch is pharmacy benefit manager coverage expansion for maintenance formulations in hearing aid wearer populations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Monograph Pathway Alignment | Early engagement with OTC modernization timelines accelerates carbamide peroxide eligibility determinations before concentration ceiling rulings. |
| Enzymatic Formulation Development | Recombinant lipase capabilities differentiate portfolios from commodity peroxide chemistry in otolaryngology preference. |
| Telehealth Platform Integration | Remote otoscopic examination enables reimbursable clinician-supervised self-administration beyond current OTC boundaries. |
| Preventative Care Subscription Models | Monthly-use maintenance protocols for hearing aid wearers convert reactive purchases into recurring revenue streams. |
| Pediatric Formulation Launch | Reduced-foaming surfactant bases address unmet demand where hydrogen peroxide concentrations face parental resistance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA OTC monograph filings, EMA medical device borderline determinations, and pharmacy procurement databases, combining structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with validation through SEC 10-K disclosures, ClinicalTrials.gov enzymatic cerumenolysis entries, and CMS Medicare Advantage plan benefit documentation. Bottom-up demand modeling from patient population incidence rates and top-down market sizing from manufacturer shipment data undergo cross-verification.
Segmentation dimensions modeled span active chemistry type, application setting, end-user channel, and delivery mode format across the projection horizon. CAGRs derive from regression analysis against aging demographic trajectories, hearing aid penetration curves, and pharmacy channel expansion rates. Forecast inputs incorporate FDA monograph reform probability-weighted scenarios and telehealth reimbursement policy adoption curves.
The analysis sits within stated boundaries; outcomes outside FDA monograph modernization timelines, peroxide feedstock cost stability, or mechanical irrigation substitution rates would require recalibration. Forecasts reflect assumptions on clinician recommendation patterns and consumer self-treatment propensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
Immunosuppressive Drugs Market