
 Global Atosiban Market | 2026-2036
Global Atosiban Market Size, Share, and Industry Trends Forecast 2026-2036
Global Atosiban Market Foresight
Maintenance and clinical support services bundled with atosiban vials is decoupling revenue from pure unit sales across obstetric units. Teva Pharmaceuticals leverages its generic injectables infrastructure to sustain cost-competitive supply chains in North America. Ferring Pharmaceuticals anchors its position through specialized reproductive health portfolios across European maternity hospitals. Boehringer Ingelheim differentiates via R&D intensity in peptide-based tocolytic formulations.
Atosiban is a synthetic oxytocin receptor antagonist administered intravenously to arrest premature uterine contractions, typically formulated as a 6.75 mg intravenous bolus followed by 300 micrograms per minute infusion. Its primary purpose is to delay preterm delivery and extend gestation in threatened preterm labor cases. Injectable solutions dominate volume throughput in hospital pharmacy channels due to immediate administration requirements in acute obstetric settings. Prefilled syringes represent the fastest-growing product configuration as birthing centers prioritize reduced preparation time and dosing accuracy. Maternity hospitals capture the deepest margin pools through direct procurement contracts and formulary control over tocolytic protocols.
FDA pregnancy labeling requirements and EMA pharmacovigilance frameworks for tocolytic agents govern clinical trial endpoints and post-market surveillance obligations for manufacturers. The EU MDR and US FDA cGMP standards enforce sterility and stability specifications for peptide injectable production, elevating compliance costs for new entrants. Stakeholders must monitor evolving reimbursement criteria for threatened preterm labor interventions across national health systems to anticipate volume shifts between hospital and outpatient administration settings.
Market Dynamics
EMA pharmacovigilance frameworks and FDA pregnancy labeling revisions are compressing clinical trial timelines while elevating post-market surveillance obligations for peptide injectable manufacturers across maternity hospital networks.
Growth Catalysts
- Prefilled syringe adoption:Birthing centers in Germany and Japan are converting from ampoules to prefilled configurations, reducing preparation errors and nursing labor in acute obstetric settings.
- EU MDR sterility requirements:The updated Medical Device Regulation is mandating enhanced stability specifications for peptide injectables, which filters out subscale competitors and consolidates procurement toward certified manufacturers.
- Maternal-fetal medicine infrastructure:The United States is expanding level III and IV neonatal intensive care units, creating dedicated tocolytic formularies that anchor atosiban volume through direct hospital contracts.
Market Restraints
- Peptide synthesis input costs:Solid-phase peptide synthesis resins and protected amino acids face price volatility from Chinese specialty chemical suppliers, compressing margin buffers for finished dose manufacturers.
- Single-source API concentration:Active pharmaceutical ingredient production for synthetic oxytocin antagonists clusters among European contract manufacturers, exposing supply continuity risk from any regional regulatory enforcement action.
- Calcium channel blocker substitution:Nifedipine retains formulary preference in several national health systems due to oral administration convenience and lower per-dose acquisition cost in outpatient threatened preterm labor management.
Strategic Opportunities
- Outpatient infusion center expansion:Japan's evolving reimbursement criteria for threatened preterm labor interventions is enabling same-day observation units to administer atosiban outside traditional inpatient wards.
- Connected delivery device convergence:Integration of prefilled syringes with Bluetooth-enabled infusion pumps is creating real-time dosing documentation for electronic health record integration in US health systems.
- Indian maternal health infrastructure:Government-funded Janani Suraksha Yojana program expansion into district hospital obstetric units is opening procurement channels for tocolytic protocols previously limited to tertiary centers.
Industry Challenges
- Peptide formulation expertise scarcity:Sterile parenteral manufacturing of oxytocin antagonists requires specialized analytical method development capabilities that outpace current bioprocess engineering graduate pipeline output.
- Multinational pharmacovigilance harmonization:Divergent FDA adverse event reporting timelines versus EMA periodic safety update report frequencies force manufacturers to maintain parallel surveillance systems with incompatible data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Atosiban Market |
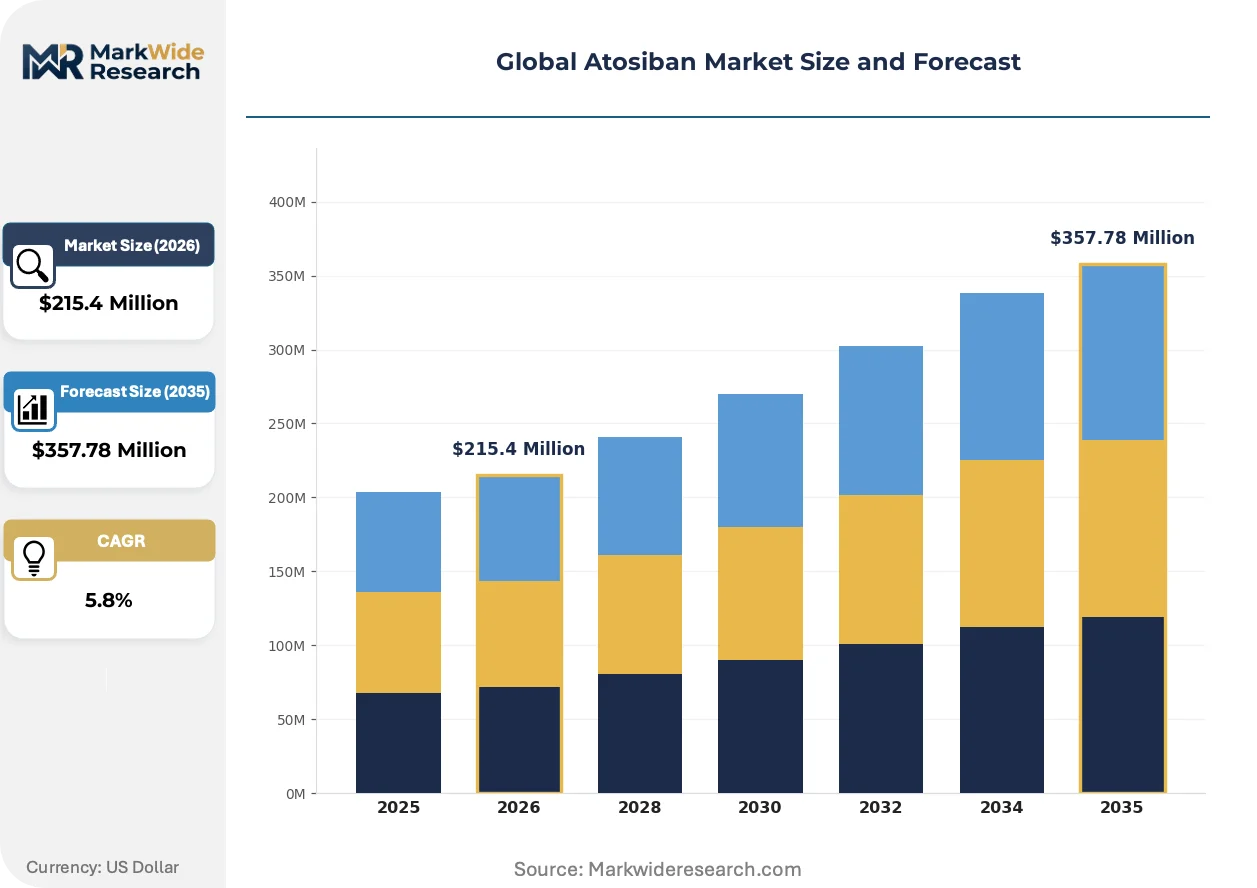
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Injectable Solution, Powder, Lyophilized, Prefilled Syringe Application: Preterm Labor Management, Labor Induction, Uterine Relaxation, Postpartum Hemorrhage Prevention End User: Maternity Hospitals, Birthing Centers, Gynecologist Clinics, Obstetric Units Distribution Channel: Hospital Pharmacy, Retail Pharmacy, Online Pharmacy, Direct Sales, Wholesale Distributors |
| Companies Covered | Teva Pharmaceuticals, Boehringer Ingelheim, Ferring Pharmaceuticals, Sun Pharma, Eisai Co., Ltd., Hikma Pharmaceuticals, AstraZeneca, Novartis AG, Sandoz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Atosiban Market Shifts & Advancements
Formulation science and administration modality innovations are compressing the gap between acute hospital intervention and ambulatory obstetric care, reshaping where and how tocolytic therapy is initiated and maintained.
Ready-to-use prefilled syringe systems are decentralizing atosiban administration from centralized hospital pharmacy compounding to point-of-care obstetric units. Maternity hospitals in Germany and the United States are adopting these configurations to reduce medication preparation time during active preterm labor episodes. This shift is compressing the role of traditional pharmacy intermediaries and transferring dosing accountability directly to labor-and-delivery nursing teams.
REACH and RoHS substance restrictions within the European Union are forcing reformulation of rubber stopper and plunger components in glass syringe assemblies. Manufacturers serving EMA-regulated markets are qualifying halogen-free elastomer alternatives and submitting updated device master files for regulatory acceptance. Prefilled syringe suppliers with early polymer biocompatibility data are capturing formulary preference in French and Dutch maternity hospital procurement cycles.
Hospital pharmacy directors are unbundling tocolytic drug acquisition from clinical support service contracts, treating atosiban as a commodity injectable while purchasing decision-support algorithms separately. This purchasing behavior is displacing traditional bundled vendor relationships in US academic medical centers and German university hospitals. The separation is most visible in multi-hospital health systems consolidating formulary management through centralized pharmacy and therapeutics committees.
Global Atosiban Market Segmentation
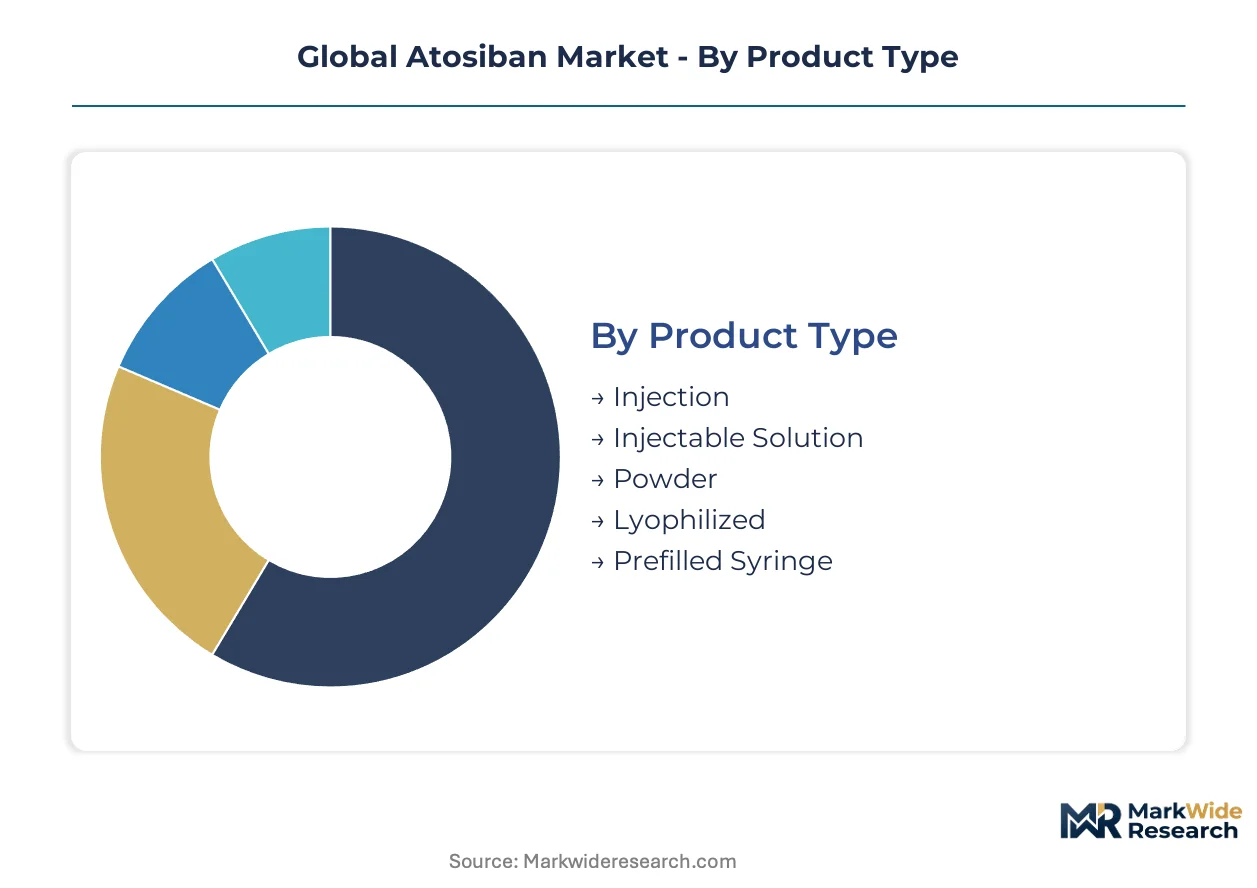
Atosiban's therapeutic positioning across acute obstetric settings creates distinct capital requirements by formulation complexity and administration modality. Segmentation reveals where sterile manufacturing investments concentrate versus where commercial infrastructure drives margin capture.
Product Type:
Injectable configurations demand the heaviest upfront capital, with sterile peptide production facilities requiring dedicated cleanroom suites and specialized analytical instrumentation.
- Injection:Standard vial presentations require aseptic filling lines and terminal sterilization validation. Maternity hospitals in the United States anchor volume through centralized pharmacy procurement contracts that prioritize lot traceability and cold-chain integrity.
- Prefilled Syringe:Device-drug combination products necessitate polymer biocompatibility testing and automated assembly systems. German birthing centers are converting to these configurations to reduce medication preparation time during active labor episodes.
- Injectable Solution:Ready-to-use liquid formulations eliminate reconstitution steps for nursing staff.
- Powder:Lyophilized cake presentations extend shelf stability for inventory-heavy procurement models.
- Lyophilized:Freeze-dried peptide matrices require specialized lyophilization equipment and residual moisture controls.
Injectable solutions absorb the bulk of installed capacity; prefilled syringes are expanding most quickly.
Application:
Clinical indication determines reimbursement pathway complexity and the regulatory evidence burden for market access.
- Preterm Labor Management:The primary approved indication requires intravenous bolus-plus-infusion protocols with continuous fetal monitoring. Japan's evolving reimbursement criteria for threatened preterm labor interventions is enabling same-day observation units to administer atosiban outside traditional inpatient wards.
- Labor Induction:Off-label use in controlled delivery timing demands enhanced pharmacovigilance documentation. EMA pharmacovigilance frameworks for tocolytic agents govern clinical trial endpoints and post-market surveillance obligations for manufacturers pursuing this indication.
- Uterine Relaxation:Intraoperative applications during cesarean delivery require rapid onset formulations.
- Postpartum Hemorrhage Prevention:Prophylactic administration protocols compete with established uterotonic agents in hospital formularies.
Preterm labor management commands the deepest formulary penetration; labor induction applications are climbing the fastest as protocols expand.
End User:
Facility type dictates procurement authority concentration and the service bundling expectations that accompany product acquisition.
- Maternity Hospitals:Level III and IV neonatal intensive care units in the United States create dedicated tocolytic formularies that anchor atosiban volume through direct hospital contracts and clinical support service agreements.
- Birthing Centers:Freestanding obstetric facilities in Germany prioritize reduced preparation time and dosing accuracy, driving prefilled syringe adoption over traditional ampoule presentations.
- Gynecologist Clinics:Outpatient settings face formulary exclusion where calcium channel blockers retain preference for oral administration convenience.
- Obstetric Units:General hospital departments without dedicated maternal-fetal medicine infrastructure rely on centralized pharmacy intermediaries for tocolytic access.
Maternity hospitals concentrate the highest procurement volumes; birthing centers are gaining share fastest as decentralized obstetric care expands.
Distribution Channel:
Channel selection reflects the tension between formulary control consolidation and the urgency of acute obstetric administration requirements.
- Hospital Pharmacy:Centralized compounding and inventory management dominates acute care settings where immediate availability overrides cost considerations.
- Direct Sales:Manufacturer-to-institution contracts bypass distributor margins for high-volume maternity hospital networks in Germany and Japan.
- Retail Pharmacy:Community-based dispensing faces limited uptake given intravenous administration requirements and inpatient monitoring protocols.
- Online Pharmacy:Digital procurement platforms gain traction for maintenance dosing in outpatient infusion center models.
- Wholesale Distributors:Regional logistics networks serve fragmented birthing center and clinic markets with less predictable demand patterns.
Hospital pharmacy channels capture the majority of transaction volume; direct sales are expanding most quickly as health systems consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis for atosiban concentrates among European contract manufacturers, while consumption clusters in tertiary maternity hospitals across high-income markets. Finished dose production runs through sterile peptide facilities in Switzerland and Germany. Patient access expands through government-funded maternal health programs in emerging economies.
United States
Level III and IV neonatal intensive care units drive volume through dedicated tocolytic formularies and direct hospital contracts. FDA pregnancy labeling requirements reshape prescribing protocols and post-market surveillance obligations for peptide injectable manufacturers. The Southeast and Texas Medical Center anchor procurement concentration as regional health systems consolidate pharmacy and therapeutics committees.
Germany
Birthing centers convert from ampoules to prefilled syringe configurations, reducing medication preparation time during active labor episodes. EU MDR sterility specifications filter out subscale competitors and consolidate procurement toward certified manufacturers. The Rhine-Ruhr and Bavarian hospital networks concentrate maternal-fetal medicine infrastructure and formulary control.
Japan
Same-day observation units administer atosiban outside traditional inpatient wards under evolving reimbursement criteria for threatened preterm labor. METI and PMDA frameworks govern device-drug combination product approvals for connected delivery systems. Tokyo and Osaka metropolitan clusters pioneer outpatient infusion center expansion for tocolytic protocols.
India
Janani Suraksha Yojana program expansion opens procurement channels for district hospital obstetric units previously limited to tertiary centers. CDSCO regulates sterile parenteral manufacturing standards for peptide injectables entering the public health supply chain. Maharashtra and Gujarat maternal health infrastructure upgrades concentrate new tocolytic protocol adoption.
Switzerland
Specialized reproductive health portfolios anchor European maternity hospital supply relationships through clinical support service bundling. Swissmedic enforces sterility and stability specifications for peptide injectable production, elevating compliance costs for market entrants. Basel and Zurich pharmaceutical clusters concentrate API synthesis expertise and finished dose manufacturing capacity.
Global Atosiban Market Competitive Landscape
Capital-heavy producers with captive sterile peptide manufacturing compete with asset-light formulators outsourcing API synthesis to European contract manufacturers. The market structure consolidates around three tiers: integrated innovators with R&D pipelines, generic injectables specialists leveraging cost-competitive supply chains, and regional licensees serving national health system tenders. Strategic moves center on prefilled syringe device qualification for EU MDR compliance and direct hospital contracting to displace distributor intermediaries.
Within the integrated innovator tier, Ferring Pharmaceuticals and Boehringer Ingelheim exemplify specialized reproductive health portfolio anchoring. Among generic injectables specialists, Teva Pharmaceuticals occupies a position leveraging North American manufacturing infrastructure for cost-competitive supply. Sun Pharma represents the emerging market licensee archetype, capturing volume through government tender participation and district hospital penetration strategies.
| Leading Market Players |
|---|
| Teva Pharmaceuticals |
| Boehringer Ingelheim |
| Ferring Pharmaceuticals |
| Sun Pharma |
| Eisai Co., Ltd. |
| Hikma Pharmaceuticals |
| AstraZeneca |
| Novartis AG |
| Sandoz |
| Others |
Supply & Pricing Matrix
Captive API synthesis in Switzerland and Germany anchors supply positions for sterile peptide manufacturers while simultaneously insulating pricing power from Chinese specialty chemical volatility. This backward integration into solid-phase peptide synthesis resins and protected amino acid sourcing allows finished dose producers to buffer margin compression that otherwise propagates from raw material spot markets.
Pricing Analysis
Cost-down pressure on standard vial presentations accelerates because hospital pharmacy directors unbundle drug acquisition from clinical support services. Three-tier pricing structure across premium prefilled syringes, standard injectable solutions, and economy lyophilized vials separates manufacturers by EU MDR certification status and cold-chain reliability. Price differentiation traces to polymer biocompatibility testing investments and automated assembly system scale. Birthing centers in Germany exhibit highest price sensitivity due to outpatient reimbursement constraints; United States academic medical centers show lowest sensitivity where formulary control prioritizes lot traceability over per-unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-deviated peptide injectables remain underdeveloped, forcing destruction protocols that inflate effective cost per delivered dose. API synthesis concentrates in Switzerland, Germany, and Italy among European contract manufacturers with captive sterile parenteral capabilities. Finished dose production draws from solid-phase peptide synthesis resins, halogen-free elastomer stoppers, and glass syringe assemblies. Single-source vulnerability in Chinese protected amino acid suppliers exposes continuity risk from regional regulatory enforcement. Distribution runs through hospital pharmacy channels and direct manufacturer contracts, bypassing wholesale intermediaries in high-volume maternity networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where sterile manufacturing capabilities and prefilled syringe device qualification determine who captures consolidated procurement contracts. Players are pursuing backward integration into peptide synthesis to escape API margin extraction.
For Market Incumbents: Lock in formulary control through EU MDR-certified prefilled syringe portfolios and direct contracting with United States level III neonatal intensive care units. Calcium channel blocker substitution in outpatient settings threatens volume retention; defend by embedding clinical decision-support algorithms into hospital pharmacy systems. Capacity addition in Swiss sterile peptide facilities secures supply continuity against single-source API concentration. For New Entrants and Emerging Players: District hospital obstetric units in India represent the most penetrable buyer archetype as Janani Suraksha Yojana program expansion creates first-time tocolytic protocol adoption. Prefilled syringe configurations for same-day observation units in Japan offer second white-space target under evolving reimbursement criteria. Go-to-market through government tender participation with cost-competitive lyophilized presentations bypasses entrenched hospital pharmacy relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by generic injectables specialists seeking sterile peptide manufacturing capabilities. Long-term viability hinges on regulatory certification moats and captive API supply rather than pure commercial scale. Watch EMA pharmacovigilance framework enforcement actions against European contract manufacturers as inflection indicator for supply-side consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Prefilled Syringe Qualification | Device-drug combination approval filters subscale competitors from German procurement cycles. |
| Backward Integration into Peptide Synthesis | Captive API production insulates margin from Chinese specialty chemical price volatility. |
| Direct Hospital Contracting | Manufacturer-to-institution agreements displace distributor margins in United States health systems. |
| Connected Delivery Device Development | Bluetooth-enabled infusion pump integration enables real-time EHR documentation for US hospitals. |
| Janani Suraksha Yojana Tender Participation | Government-funded maternal health program opens district hospital channels in Maharashtra and Gujarat. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and maternal-fetal medicine specialists combined with FDA pregnancy labeling submissions, EMA pharmacovigilance databases, and ClinicalTrials.gov entries. Bottom-up prescription volume modeling and top-down healthcare expenditure triangulation validated segment sizing across formulation types and administration settings.
Data-stream reconciliation between hospital pharmacy procurement databases and national health system reimbursement schedules established volume baselines across the analysis window. Segmentation dimensions included product type, clinical indication, end-user facility tier, and distribution channel structure. CAGRs derived from modeled patient population growth, protocol penetration rates, and pricing trajectory assumptions. Forecast inputs incorporated evolving FDA pregnancy labeling requirements and EMA MDR enforcement timelines.
Revisions become necessary when EMA pharmacovigilance framework enforcement actions, FDA pregnancy labeling revisions, or Chinese specialty chemical export restrictions materialize differently than assumed. Practitioners should monitor CDSCO sterile parenteral manufacturing standard updates and METI device-drug combination approval timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market