
 PAP and Paracetamol Market | 2026-2036
PAP and Paracetamol Market Size, Share, and Industry Trends Forecast 2026-2036
PAP and Paracetamol Market Outlook
API-to-formulation margin migration is rewriting competitive economics across the PAP and Paracetamol Market. Granules India Ltd anchors downstream value through integrated API and finished-dose production. Teva Pharmaceutical Industries Ltd leverages its generic scale to compete on hospital contract tenders. Dr. Reddy's Laboratories Ltd specializes in regulated-market exports with dedicated paracetamol manufacturing lines.
Para-aminophenol (PAP) serves as the key intermediate for paracetamol (acetaminophen) synthesis, typically manufactured through nitrobenzene reduction or phenol nitration routes with specific purity grades exceeding 99.5% for pharmaceutical use. Paracetamol functions primarily as an analgesic and antipyretic active pharmaceutical ingredient in over-the-counter and prescription medications across tablet, syrup, and injectable delivery forms. Immediate-release formulations dominate volume due to their established clinical profile and manufacturing simplicity, while extended-release formats command premium positioning in chronic pain management segments. Hospital procurement channels concentrate demand for higher-dosage injectable presentations, whereas pharmacy and home-care segments drive tablet and syrup consumption.
FDA dosing-limit regulations and EMA pharmacovigilance frameworks shape formulation innovation and label compliance requirements across major export destinations. India's CDSCO enforces bulk drug manufacturing standards that govern PAP producer licensing and environmental clearance protocols for phenol-based synthesis routes. Stakeholders must monitor evolving regulatory thresholds for impurities such as 4-aminophenol and p-chloroacetanilide, as these specifications determine market access and batch release criteria.
Market Dynamics
API-to-formulation margin compression is forcing producers to recalibrate capital allocation between bulk para-aminophenol synthesis and finished-dose manufacturing. India's phenol-based PAP producers face mounting environmental compliance costs while hospital procurement channels in the United States and Europe consolidate purchasing power around injectable paracetamol presentations.
Growth Catalysts
- CDSCO bulk drug licensing reforms:India's streamlined environmental clearance protocols for phenol nitration routes are accelerating capacity expansion among domestic PAP manufacturers serving export markets.
- Hospital channel consolidation:Integrated health systems in the United States are standardizing formulary inclusion of higher-dosage injectable paracetamol for perioperative pain protocols.
- Continuous flow chemistry:Adoption of microreactor technology for PAP synthesis is reducing batch-to-batch impurity variance and cutting solvent waste volumes below traditional batch thresholds.
Market Restraints
- Phenol feedstock volatility:Crude benzene price swings transmit directly to PAP production economics, compressing margins for non-integrated manufacturers lacking captive phenol supply.
- Single-origin API concentration:Overreliance on Ankleshwar and Hyderabad manufacturing clusters exposes global paracetamol supply to regional logistics disruptions and monsoon-season port congestion.
- FDA acetaminophen hepatotoxicity limits:Dose ceiling regulations and black-box warning requirements constrain formulation innovation in over-the-counter combination products.
Strategic Opportunities
- Brazilian ANVISA prequalification pathway:Early mover advantage exists for PAP producers securing active pharmaceutical ingredient certification for Latin American hospital tenders.
- Extended-release tablet platforms:Chronic pain management protocols in Germany and France are creating pull for modified-release paracetamol presentations commanding formulation premiums.
- Green chemistry incentives:The EU Green Deal's sustainable manufacturing subsidies favor producers adopting catalytic hydrogenation routes over traditional iron-acid reduction for nitrobenzene conversion.
Industry Challenges
- Process analytical technology integration:Real-time release testing requirements demand capital-intensive PAT sensor deployment that mid-scale PAP facilities struggle to finance.
- Multinational pharmacovigilance staffing:EMA's strengthened signal detection mandates require dedicated safety surveillance teams that stretch resource-constrained generic houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PAP and Paracetamol Market |
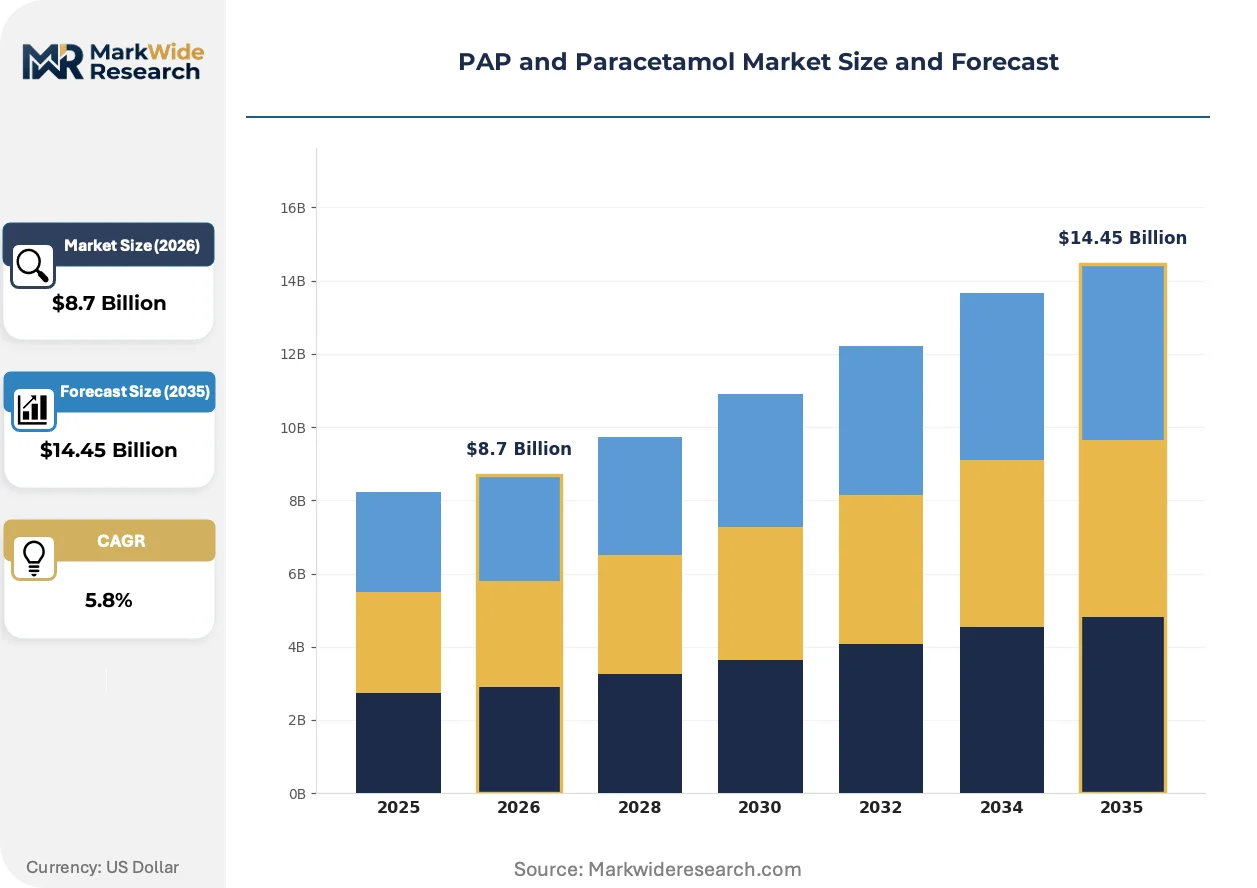
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PAP, Paracetamol Tablets, Paracetamol Syrup, Paracetamol Injection Formulation: Immediate Release, Extended Release, Effervescent, Granules Dosage Strength: 500 mg, 1000 mg, 250 mg, 650 mg End User: Hospitals, Pharmacies, Clinics, Home Care |
| Companies Covered | Johnson & Johnson, Novartis AG, Sanofi, Teva Pharmaceutical Industries Ltd, Bayer AG, Dr. Reddy's Laboratories Ltd, Pfizer Inc., Granules India Ltd, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PAP and Paracetamol Market Strategic Shifts
Digitalization of quality assurance and manufacturing execution systems is compressing batch release timelines while regulatory divergence between major markets forces parallel compliance investments. Synthetic route innovation and packaging sustainability are emerging as secondary differentiators.
Continuous manufacturing platforms for paracetamol tablet production are virtualizing traditional batch-based quality control. Major contract manufacturers in India and Germany are retrofitting fluid bed granulation lines with real-time particle size monitoring. This virtualization is collapsing the distinction between in-process testing and final release, enabling same-day batch disposition that batch record review protocols cannot match.
EMA's revised nitrosamine risk assessment guidelines for chemically synthesized APIs are forcing PAP producers to validate absence of N-nitroso-4-aminophenol at parts-per-billion thresholds. European paracetamol formulators are now demanding comprehensive nitrosamine risk assessments upstream. German and Italian manufacturers are responding by qualifying secondary PAP suppliers with demonstrated control over nitrosating agent contamination.
Hospital procurement groups in the United States are consolidating annual paracetamol contracts around single-source injectable suppliers with guaranteed cold-chain integrity. Group purchasing organizations are displacing fragmented distributor relationships with direct manufacturer agreements. This concentration is most visible in the southeastern United States, where regional health systems are standardizing on pre-filled syringe presentations for surgical suites.
PAP and Paracetamol Market Segmentation
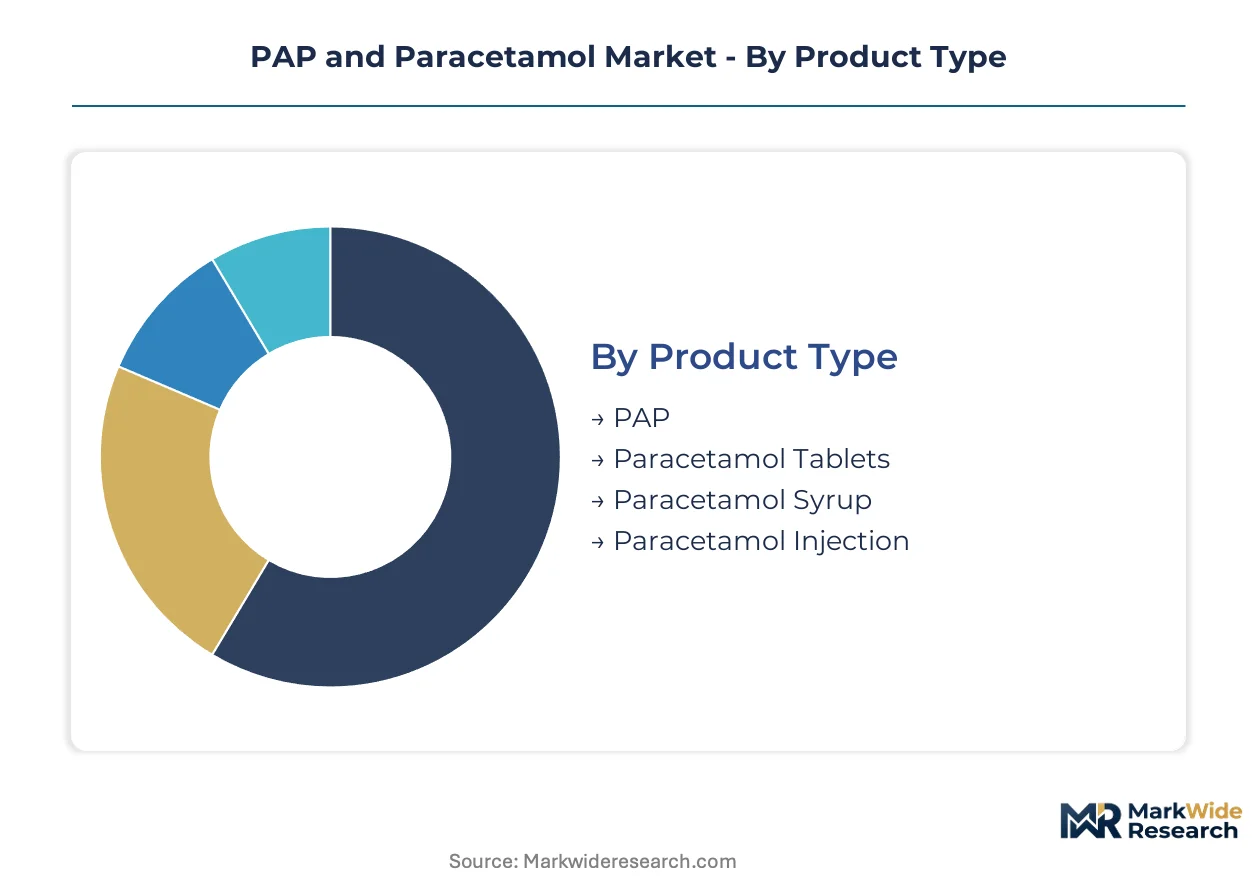
Segmentation in the PAP and Paracetamol Market reveals divergent margin profiles and regulatory exposure across the value chain. API intermediates cycle through inventory faster than finished-dose formulations, while hospital channels demand distinct presentation formats compared to retail pharmacy.
Product Type:
Cycle times vary sharply across this category, with bulk PAP turning in weeks and injectable paracetamol sitting in sterilization quarantine for months.
- Paracetamol Injection:Sterile aqueous solutions in ampoules or vials requiring terminal sterilization and endotoxin testing. Hospital surgical suites in the United States drive procurement through group purchasing organization tenders, with cold-chain integrity specifications extending lead times.
- Paracetamol Tablets:Compressed solid dosage forms dominating retail pharmacy volume. India's contract manufacturers supply regulated markets with film-coated and uncoated variants, facing FDA dissolution-profile scrutiny for bioequivalence.
- PAP:Para-aminophenol intermediate for captive paracetamol synthesis or merchant API sales. Ankleshwar cluster producers serve domestic formulators and export markets with phenol-nitration route material.
- Paracetamol Syrup:Liquid pediatric and geriatric presentations with preservative systems and flavor masking. CDSCO stability requirements govern shelf-life claims for tropical climate distribution.
Paracetamol Tablets anchors the volume base while Paracetamol Injection gains share at the steepest rate.
Formulation:
Cost tiers separate commodity immediate-release formats from value-added modified-release platforms commanding formulation premiums.
- Immediate Release:Standard dissolution profiles with rapid onset for acute pain and fever management. German and French hospital formularies specify these for perioperative protocols, with procurement concentrated around high-volume tenders.
- Extended Release:Matrix or reservoir systems sustaining plasma levels over 8-12 hours. Chronic pain management protocols in Germany create pull for modified-release tablets, with EMA bioequivalence guidelines shaping development costs.
- Effervescent:Rapidly dispersing tablets for patients with swallowing difficulties or pediatric compliance needs. European pharmacy chains stock these as premium self-medication options.
- Granules:Sachet-dosed powder presentations for flexible dosing in pediatric and geriatric populations. Japanese and Korean markets show preference for this format in convenience packaging.
Immediate Release dominates absolute volume while Extended Release expands most quickly on value terms.
Dosage Strength:
Application context dictates strength selection, with institutional settings standardizing on higher single-dose units and retail emphasizing flexible titration.
- 1000 mg:Maximum single-dose unit for adult acute pain under FDA hepatotoxicity ceiling guidelines. Hospital injectable presentations standardize on this strength for surgical analgesia protocols.
- 500 mg:Standard adult tablet strength for over-the-counter self-medication. Indian retail pharmacies move this format in highest absolute units, with blister packaging dominating.
- 650 mg:Intermediate strength bridging prescription and OTC categories in certain markets. US combination products with decongestants or antihistamines often employ this base.
- 250 mg:Pediatric-calibrated strength for weight-based dosing. Syrup and suspension formats more commonly deliver this range, with tablet scoring for flexibility.
500 mg supplies the broadest patient base while 1000 mg captures expanding hospital channel volume.
End User:
Customer type determines packaging, documentation, and procurement modality across the distribution chain.
- Hospitals:Institutional purchasers negotiating annual contracts for injectable and high-volume oral presentations. US group purchasing organizations consolidate demand around pre-filled syringe formats with guaranteed supply security.
- Pharmacies:Retail dispensaries stocking consumer-facing tablet and syrup formats. European pharmacy chains maintain paracetamol as a staple category with private-label competition.
- Clinics:Outpatient facilities requiring intermediate volume packaging between hospital bulk and retail unit-dose. Indian primary health centers procure through government tender systems.
- Home Care:Direct-to-patient channels including e-commerce and long-term care supply. Post-acute pain management protocols in Germany drive demand for extended-release home dispensing.
Pharmacies anchor the volume base while Hospitals gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement in Germany tolerates premium pricing for sterile injectable presentations, while Indian retail pharmacy channels squeeze margins on commodity tablet formats. This elasticity gap shapes where producers allocate formulation capacity.
United States
Group purchasing organizations consolidate annual contracts for 1000 mg injectable paracetamol used in perioperative protocols. FDA hepatotoxicity labeling requirements and dose-ceiling regulations constrain combination product development. The southeastern hospital corridor standardizes on pre-filled syringe formats from direct manufacturer agreements.
Germany
Chronic pain management protocols generate pull for extended-release paracetamol tablets commanding formulation premiums. EMA bioequivalence guidelines and nitrosamine risk assessment frameworks shape API sourcing requirements. The Rhine-Ruhr industrial belt hosts contract manufacturers qualifying secondary PAP suppliers for European hospital tenders.
India
Ankleshwar and Hyderabad manufacturing clusters supply bulk PAP and finished-dose formulations for export markets. CDSCO streamlined environmental clearance protocols accelerate capacity expansion for phenol-nitration route producers. Monsoon-season port congestion and regional logistics disruptions expose concentrated supply vulnerabilities.
Brazil
ANVISA prequalification pathways for active pharmaceutical ingredients create early-mover advantages in Latin American hospital procurement. Government tender systems for primary health centers drive volume demand for standard tablet strengths. São Paulo-based distributors channel imports from Indian API manufacturers into regional pharmacy networks.
China
Domestic pharmaceutical manufacturers expand paracetamol API output for captive formulation use and merchant sales. NMPA bulk drug manufacturing standards and environmental enforcement tighten around phenol-based synthesis routes. The Yangtze River Delta concentration of chemical intermediates producers faces rising compliance costs for catalytic hydrogenation technology adoption.
PAP and Paracetamol Market Competitive Environment
Vertically integrated API producers and pure-play formulation specialists split the market along value-chain positioning lines. The structure concentrates around three archetypes: bulk intermediate manufacturers with captive downstream integration, generic pharmaceutical houses competing on hospital contract tenders, and multinational branded marketers defending OTC shelf presence. Capacity expansion in Indian PAP synthesis and strategic partnerships for regulated-market distribution represent the dominant competitive moves.
Among Indian integrated producers, Granules India Ltd and Dr. Reddy's Laboratories Ltd exemplify the API-to-formulation margin capture archetype. Teva Pharmaceutical Industries Ltd occupies a position representing generic scale advantages in hospital channel consolidation. These three entities anchor the competitive landscape without exhausting its diversity.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Novartis AG |
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| Bayer AG |
| Dr. Reddy's Laboratories Ltd |
| Pfizer Inc. |
| Granules India Ltd |
| GlaxoSmithKline plc |
| Others |
Value Chain & Pricing Dynamics
Phenol feedstock volatility determines both pricing tier spreads and supply chain shape across the PAP and Paracetamol Market. Crude benzene price swings compress margins for non-integrated manufacturers while rewarding producers with captive phenol supply, creating a structural wedge between commodity API pricing and premium formulation premiums.
Pricing Analysis
Contract manufacturing service agreements and technical support packages drive lifetime value for hospital procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates EMA-certified injectable presentations from CDSCO-standard API bulk and unbranded retail tablets. Cost compression in commodity tablet grades is intensifying because Indian retail pharmacies consolidate annual tenders around lowest-unit-cost suppliers. Hospital group purchasing organizations exhibit the least price sensitivity due to formulary standardization requirements, while independent retail dispensaries in emerging markets demonstrate acute price elasticity.
Supply Chain Analysis
Single-origin API concentration in Ankleshwar and Hyderabad exposes global paracetamol supply to regional logistics disruptions and monsoon-season port congestion. Production draws from phenol nitration routes in India, catalytic hydrogenation clusters in Germany, and nitrobenzene reduction facilities in China. Tariff exposure between the United States and Indian API exporters creates margin pressure for contract manufacturers serving regulated markets. Distribution runs through direct manufacturer agreements with hospital group purchasing organizations in the United States, layered distributor networks in Brazil, and government tender systems in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from sterile injectable technical support and cold-chain logistics is expanding faster than commodity API hardware sales. Contract manufacturing organizations capturing recurring sterilization validation and batch release testing contracts outpace pure-play bulk producers in margin sustainability.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA, EMA, and ANVISA prequalification for injectable presentations. Defensive consolidation moves include acquiring secondary PAP suppliers with demonstrated nitrosamine control and expanding captive phenol production in India to offset feedstock volatility. The threat of hospital channel consolidation around single-source suppliers demands securing direct agreements with southeastern United States group purchasing organizations.
For New Entrants and Emerging Players: Build out Brazilian ANVISA prequalification capabilities to capture early-mover advantage in Latin American hospital tenders. White-space targets include extended-release tablet platforms for German chronic pain protocols and green chemistry catalytic hydrogenation routes qualifying for EU Green Deal subsidies. The most penetrable segment is pre-filled syringe injectables for US surgical suites, with go-to-market execution through regional health system direct contracting rather than distributor intermediation.
For Investors and Strategic Acquirers: EMA's revised nitrosamine risk assessment guidelines reshape the acquisition landscape by elevating valuation premiums for PAP producers with validated absence protocols. Long-term viability centers on integrated API-to-formulation assets with regulatory diversification across three or more major markets. The target archetype is mid-scale Indian manufacturers with CDSCO licensing and pending FDA establishment inspection status. Monitor ANVISA prequalification completion rates as the signal for Latin American market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Prequalification Pathway | ANVISA certification unlocks Brazilian government hospital tenders worth substantial contract volume. |
| Backward Integration into Phenol | Captive benzene-to-phenol supply insulates margins from crude oil price transmission volatility. |
| Continuous Manufacturing Transition | Microreactor PAP synthesis reduces solvent waste below traditional batch environmental thresholds. |
| Extended-Release Platform Development | Matrix tablet technology commands formulation premiums in German chronic pain protocols. |
| Nitrosamine Risk Assessment Qualification | Validated absence protocols at parts-per-billion thresholds satisfy EMA's revised API guidelines. |
Study Parameters
Desk research of FDA establishment inspection records, EMA assessment reports, and CDSCO manufacturing licensing databases preceded structured interviews with pharmaceutical procurement directors, API plant managers, regulatory affairs specialists, and hospital formulary committee members. Primary fieldwork with Indian PAP manufacturers and German contract formulators was cross-referenced against secondary validation from customs trade data, SEC 10-K pharmaceutical segment disclosures, and hospital group purchasing organization contract announcements. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level estimates.
Assumptions held fixed include current FDA hepatotoxicity labeling requirements, EMA nitrosamine thresholds, and CDSCO environmental clearance protocols; variations were tested around phenol feedstock price bands and hospital channel consolidation rates. The analytical framework segmented by product type, formulation technology, dosage strength, and end-user channel across the projection horizon. CAGRs were derived from weighted average growth contributions across these dimensions, with specific inputs including Indian monsoon-season logistics disruption frequencies and US surgical suite paracetamol utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical producers or sudden FDA enforcement actions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Global Thin Film Drugs Market