
 Intravenous Pegloticase Market | 2026-2036
Intravenous Pegloticase Market Size, Share, and Industry Trends Forecast 2026-2036
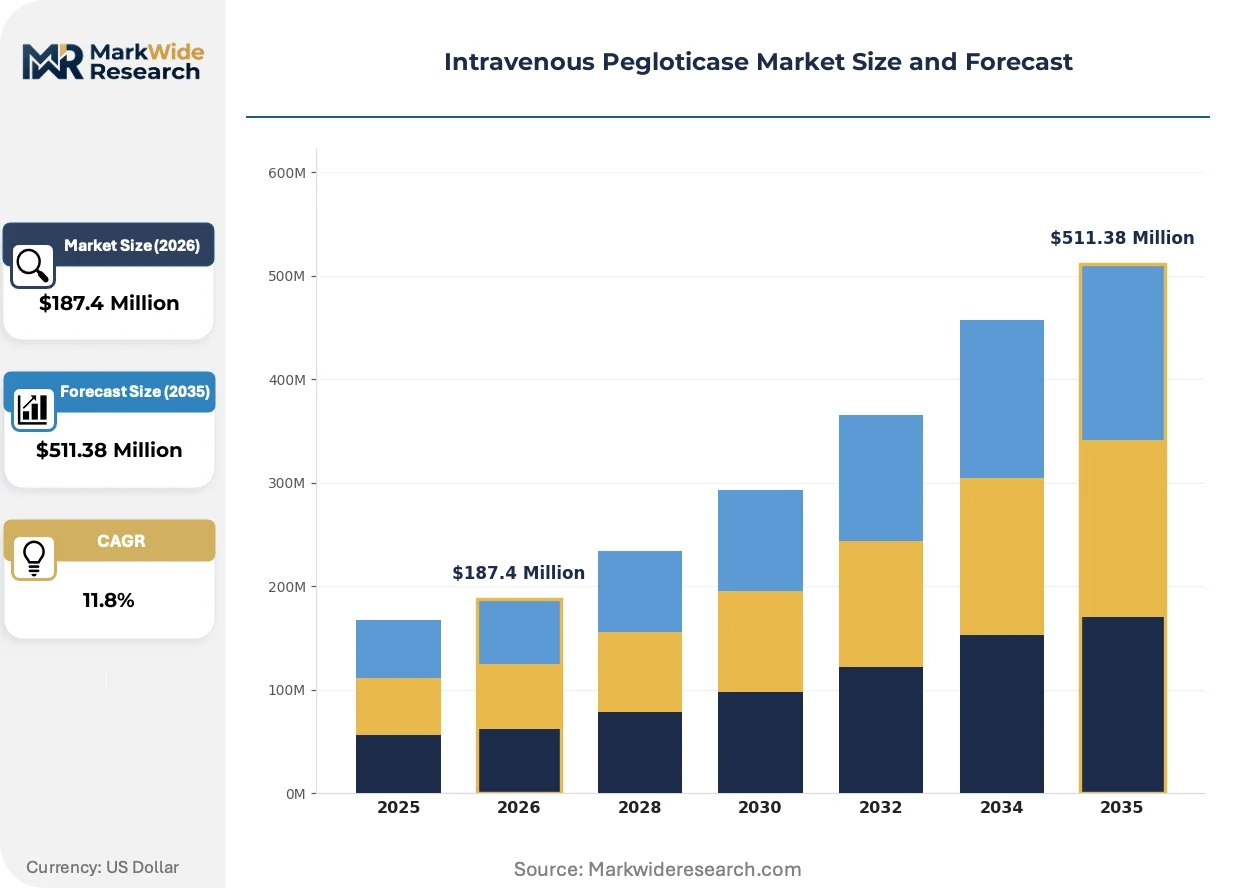
Intravenous Pegloticase Market Outlook
Multi-source biologic procurement is expanding as hospital systems diversify pegloticase suppliers beyond single-manufacturer agreements. Horizon Therapeutics plc anchors the branded pegloticase segment through its established infusion site network and REMS-certified provider relationships. Takeda Pharmaceutical Company Limited competes in adjacent rare-disease biologics and leverages its plasma-derived therapy infrastructure to sustain hospital formulary presence. Selecta Biosciences, Inc. differentiates through immune tolerance platform technologies that address the immunogenicity limitations constraining chronic pegloticase therapy.
Intravenous pegloticase is a recombinant porcine uricase enzyme, pegylated with monomethoxy polyethylene glycol to extend circulating half-life to approximately ten to twelve days, administered via intravenous infusion to catalyze uric acid oxidation in patients with refractory gout. The indication segment stratifies sharply, with chronic gout dominating current utilization while hyperuricemia in tumor lysis syndrome represents an emerging off-label expansion vector. Single-dose vials command premium positioning due to REMS compliance requirements and waste-minimization protocols, whereas multi-dose configurations occupy cost-sensitive hospital purchasing contracts.
The FDA's REMS program for pegloticase mandates prescriber certification and patient monitoring, directly shaping site-of-care economics and limiting administration to qualified infusion centers. EMA's biosimilar guidance for pegylated enzymes and WHO prequalification standards for biologic manufacturing create layered compliance thresholds for market entrants. Stakeholders must monitor immunogenicity mitigation innovations and site-of-care shift dynamics as determinants of long-term therapy persistence and revenue durability.
Market Dynamics
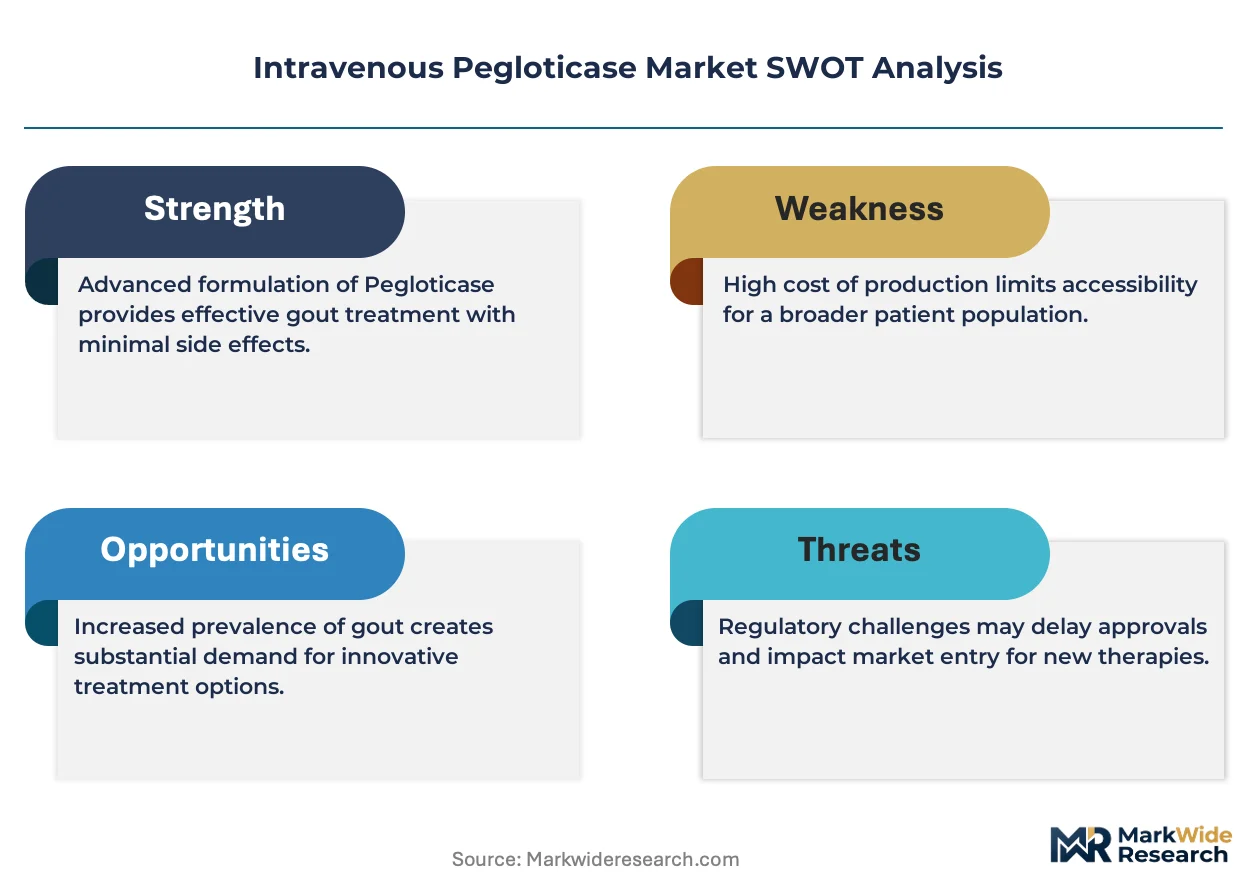
The FDA's Risk Evaluation and Mitigation Strategy for pegloticase creates a certification bottleneck that concentrates administration to REMS-qualified infusion centers, fundamentally restructuring site-of-care economics and prescriber behavior around biologic urate-lowering therapy.
Growth Catalysts
- REMS-Certified Site Expansion:Hospital-based infusion centers in the United States are scaling pegloticase administration capacity to capture refractory chronic gout patient volume. The FDA's prescriber certification mandate creates captive demand pools for qualified facilities.
- Immunogenicity Mitigation Platforms:Novel immune tolerance technologies are extending therapy persistence by suppressing anti-drug antibody formation. These approaches address the primary discontinuation driver limiting chronic pegloticase utilization.
- Specialty Pharmacy Network Density:Concentrated rheumatology clinic infrastructure in metropolitan clusters supports intravenous biologic delivery. Site proximity reduces patient travel burden and improves infusion schedule adherence.
Market Restraints
- Pegylated Enzyme Manufacturing Concentration:Limited contract manufacturing organizations possess the bioconjugation expertise for polyethylene glycol attachment. Supply vulnerability concentrates in single-source supplier relationships for critical raw materials.
- Infusion Center Capacity Constraints:REMS compliance overhead and nursing specialization requirements restrict site expansion. Qualified administration venues face scheduling bottlenecks that limit patient throughput.
- Oral Urate-Lowering Substitution:Febuxostat and allopurinol remain first-line therapy for treatment-naïve gout patients. Pegloticase reimbursement requires documented failure of oral agents, compressing addressable patient pools.
Strategic Opportunities
- Tumor Lysis Syndrome Adjacent Application:Hyperuricemia management in oncology settings represents an off-label expansion pathway. Pegloticase's rapid uric acid oxidation kinetics offer advantages over rasburicase in select clinical scenarios.
- Home Infusion Channel Development:REMS protocol adaptations could enable qualified home health administration. This channel shift would capture patients distant from hospital-based infusion centers.
- Biosimilar Manufacturing Readiness:EMA guidance for pegylated enzyme biosimilars creates pathway clarity for follow-on entrants. Early process development investment positions manufacturers for post-exclusivity market entry.
Industry Challenges
- Anti-Drug Antibody Surveillance Complexity:Immunogenicity monitoring requires specialized laboratory infrastructure and interpretation expertise. Testing turnaround times delay clinical decision-making on therapy continuation.
- Cold Chain Integrity Maintenance:Pegloticase requires controlled temperature storage and handling through distribution. Last-mile logistics failures risk product degradation and waste.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Pegloticase Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Dose Vials, Multi-Dose Vials, Pre-Mixed Solutions, Injectable Solutions End User: Hospitals, Clinics, Home Healthcare, Ambulatory Surgical Centers Delivery Mode: Intravenous Injection, Continuous Infusion, Bolus Injection, Subcutaneous Injection Indication: Chronic Gout, Hyperuricemia, Joint Inflammation, Uric Acid Nephropathy |
| Companies Covered | Krystal Biotech, Inc., Sarepta Therapeutics, Inc., Horizon Therapeutics plc, Takeda Pharmaceutical Company Limited, Pfizer Inc., Teijin Pharma Ltd., BioMarin Pharmaceutical Inc., PTC Therapeutics, Selecta Biosciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Pegloticase Market Strategic Shifts
Bioconjugation chemistry advances and site-of-care reconfiguration are compressing administration economics while regulatory frameworks for complex biologics mature across jurisdictions.
Automated infusion pump integration with electronic health record systems is automating dose verification and adverse event documentation workflows. Hospital outpatient departments are deploying these platforms to reduce nursing documentation burden and improve REMS compliance audit readiness. The technology is automating error-prone manual steps in high-risk biologic administration.
EMA's biosimilar guidance for pegylated enzymes establishes comparability exercise standards for glycosylation pattern and PEGylation site heterogeneity. Manufacturers must demonstrate equivalent pharmacokinetic profiles and immunogenicity risk profiles to reference products. European follow-on developers are responding with enhanced analytical characterization investments.
Consolidated buying by integrated delivery networks is compressing vendor selection criteria toward total cost-of-therapy metrics. Rheumatology clinic chains are displacing fragmented physician practice purchasing with centralized formulary committees. This concentration is most visible in United States metropolitan markets with dominant health system presence.
Intravenous Pegloticase Market Segmentation
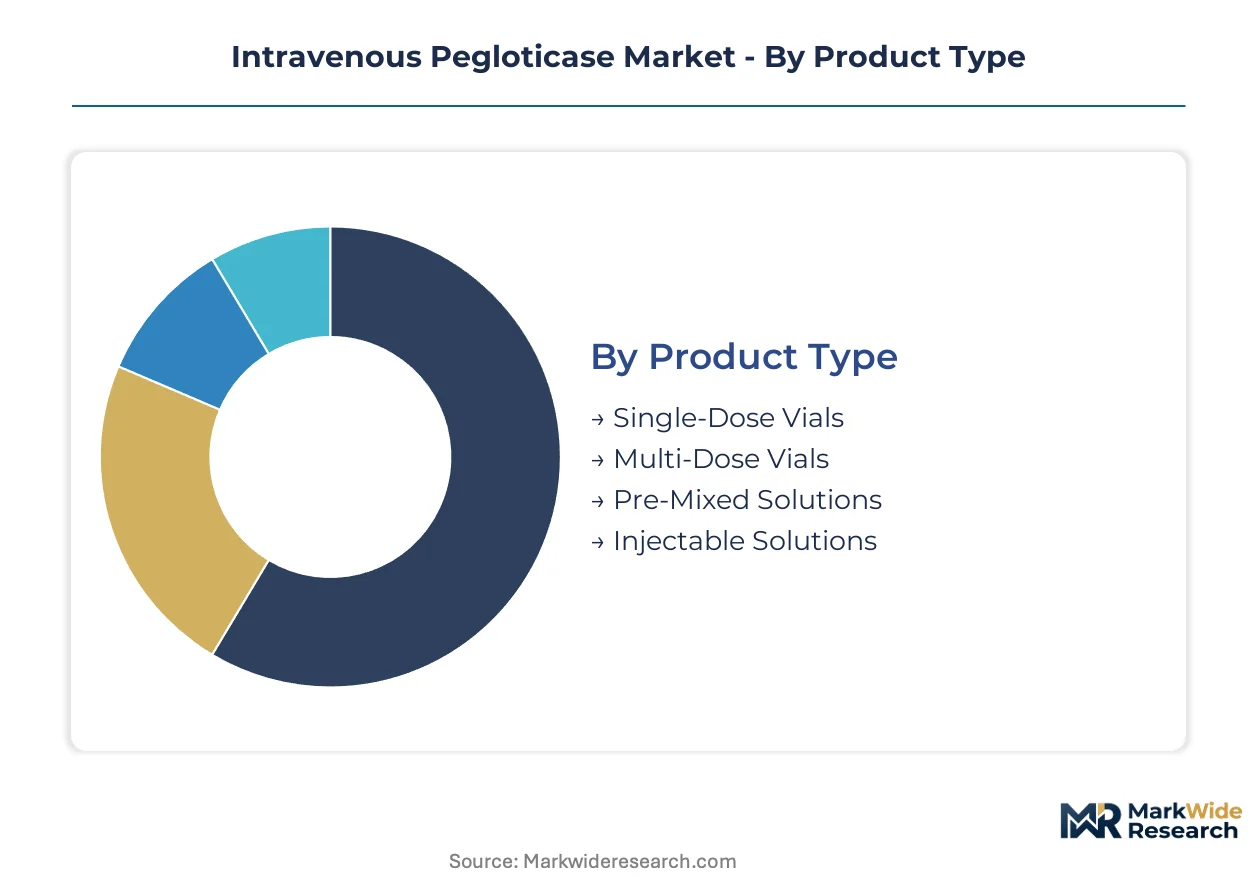
Pegloticase segmentation reflects the tension between REMS compliance infrastructure and patient access convenience. Configuration choices directly determine site-of-care economics and therapy persistence rates.
Product Type:
Premium single-unit packaging dominates reimbursement pathways while multi-dose formats penetrate cost-sensitive procurement channels.
- Single-Dose Vials:Individual-unit packaging eliminates cross-contamination risk and simplifies REMS audit trails. Hospital outpatient departments in the United States specify this format for refractory chronic gout patients requiring documented dosing precision.
- Multi-Dose Vials:Concentrated presentations reduce per-infusion material cost through nursing efficiency and waste minimization. Integrated delivery networks in metropolitan clusters negotiate these configurations for high-volume infusion centers.
- Pre-Mixed Solutions:Pharmacy-prepared formulations reduce compounding burden at point-of-care.
- Injectable Solutions:Ready-to-administer presentations streamline workflow in ambulatory settings.
Mature deployment sits with Single-Dose Vials. Newer deployment is concentrated in Multi-Dose Vials.
End User:
Institutional capacity constraints are redirecting patient flow toward lower-acuity venues with REMS certification.
- Hospitals:Academic medical centers anchor pegloticase administration through rheumatology division infrastructure and 24-hour adverse event response capability. These sites capture complex comorbid patients excluded from community settings.
- Clinics:Rheumatology-focused ambulatory practices achieve REMS qualification through nursing specialization and protocol standardization. Proximity to patient residence drives volume concentration in suburban corridors.
- Home Healthcare:Qualified infusion nursing services extend access to mobility-limited populations.
- Ambulatory Surgical Centers:Procedure-oriented facilities with existing biologic infrastructure add pegloticase to service mix.
Volume concentrates in Hospitals. Fastest expansion occurs in Clinics.
Delivery Mode:
Administration mechanics balance pharmacokinetic optimization against nursing labor intensity and patient tolerance.
- Intravenous Injection:Standard infusion over two hours with premedication protocol achieves steady-state uric acid oxidation. Hospital-based infusion centers deploy this mode for chronic gout patients with established venous access.
- Continuous Infusion:Extended delivery formats suit oncology-adjacent hyperuricemia applications requiring sustained enzymatic activity. Critical care settings in tertiary hospitals utilize this approach for tumor lysis syndrome management.
- Bolus Injection:Rapid administration protocols reduce chair time in high-throughput environments.
- Subcutaneous Injection:Alternative route development targets future home administration scenarios.
Established practice centers on Intravenous Injection. Experimental deployment is advancing in Continuous Infusion.
Indication:
Approved versus exploratory applications separate reimbursable utilization from investment-phase development.
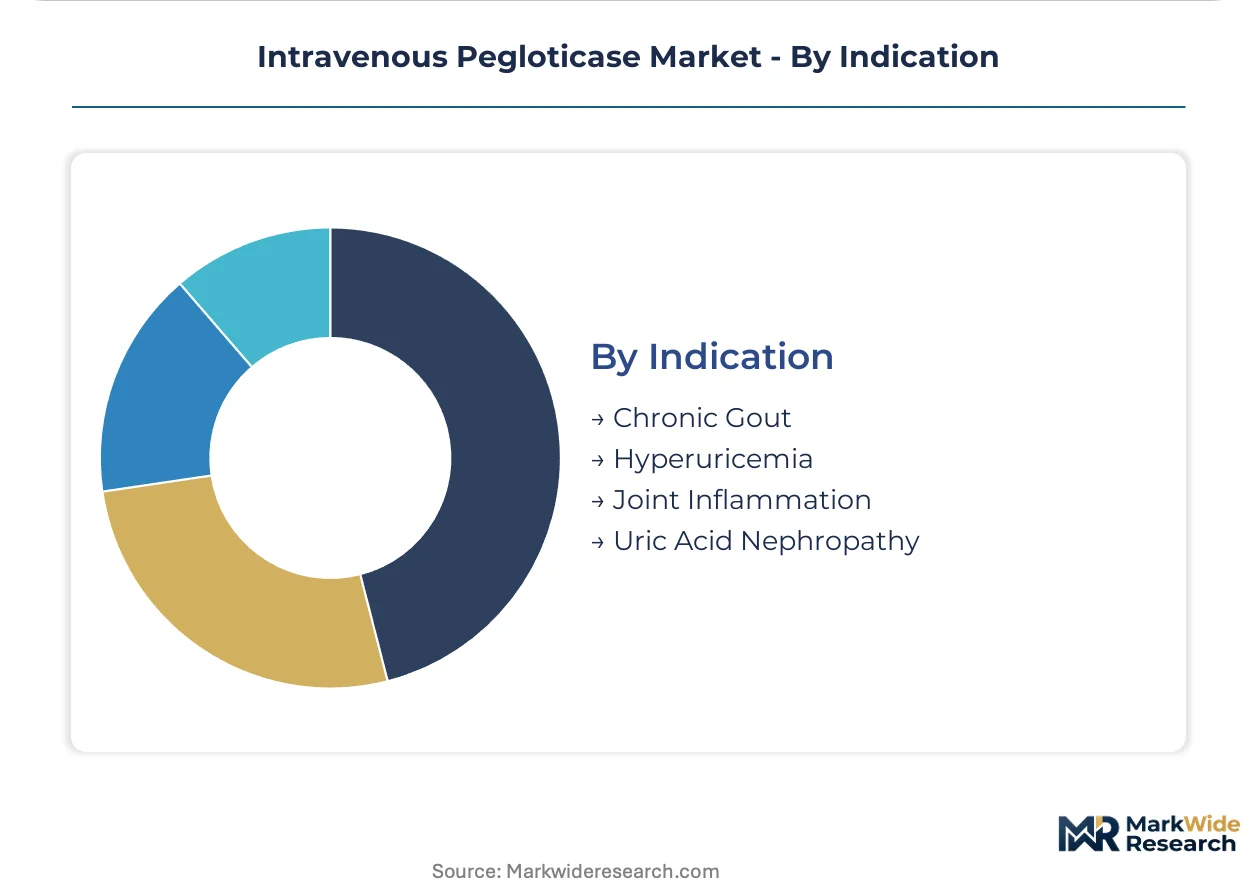
- Chronic Gout:Refractory disease with failure on oral urate-lowering therapy constitutes the FDA-approved indication and reimbursement anchor. Rheumatology clinics in the United States document prior allopurinol or febuxostat intolerance to secure coverage authorization.
- Hyperuricemia:Elevated uric acid states beyond classic gout represent the primary off-label expansion target. Oncology units in academic medical centers apply pegloticase for tumor lysis syndrome when rasburicase is contraindicated.
- Joint Inflammation:Symptomatic management of gouty arthritis drives acute care consultation.
- Uric Acid Nephropathy:Renal protection applications remain investigational with limited clinical protocol adoption.
Commercial maturity rests with Chronic Gout. Steepest expansion trajectory belongs to Hyperuricemia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant enzyme manufacturing infrastructure anchors geographic market development for intravenous pegloticase, with bioconjugation expertise and REMS-certified infusion networks determining regional penetration depth.
United States
Hospital-based infusion centers in metropolitan clusters drive refractory chronic gout patient volume, with rheumatology clinic density supporting intravenous biologic administration. The FDA's Risk Evaluation and Mitigation Strategy mandates prescriber certification and patient monitoring, concentrating therapy delivery to qualified sites. Greater Boston and the Northeast Corridor host academic medical centers with 24-hour adverse event response capabilities.
Germany
Rheumatology division infrastructure in university hospitals captures complex comorbid patients requiring specialized pegloticase administration. EMA biosimilar guidance for pegylated enzymes establishes comparability standards that shape manufacturer investment decisions. The Rhine-Ruhr metropolitan region concentrates infusion center capacity with established nursing specialization protocols.
Japan
PMDA regulatory frameworks for biologic urate-lowering therapies create structured approval pathways for refractory gout indications. METI industrial policy supports domestic bioconjugation manufacturing investments to reduce import dependency. The Kanto region around Tokyo anchors specialist rheumatology practice networks with established biologic infusion workflows.
United Kingdom
NHS specialist commissioning frameworks determine pegloticase access criteria for patients failing oral urate-lowering therapy. NICE technology appraisal processes establish cost-effectiveness thresholds that influence formulary placement. London and the Southeast concentrate tertiary rheumatology referral centers with REMS-equivalent governance structures.
Switzerland
Swissmedic biologic licensing requirements align with EMA standards while maintaining independent pharmacovigilance oversight. The country's pharmaceutical manufacturing heritage supports contract bioconjugation capabilities for pegylated enzyme production. Basel and the Northwest region host biotech clusters with specialized protein modification expertise.
Intravenous Pegloticase Market Competitive Environment
Portfolio diversification dominates the current landscape as established biologic manufacturers extend into rare-disease enzyme therapies. The vendor base concentrates around three archetypes: large-cap pharmaceutical conglomerates with infusion infrastructure assets, mid-cap rare-disease specialists with REMS program expertise, and platform-technology developers addressing immunogenicity limitations. Strategic partnerships and technology licensing represent the primary competitive vectors, with manufacturers seeking bioconjugation capabilities and site-of-care network access.
Among the named participants, Horizon Therapeutics plc and Takeda Pharmaceutical Company Limited occupy positions reflecting established biologic commercialization infrastructure, while Selecta Biosciences, Inc. exemplifies the immune-tolerance platform archetype. These three entities represent distinct strategic postures within the pegloticase value chain: legacy biologic distribution networks, plasma-derived therapy manufacturing heritage, and next-generation immunogenicity mitigation technology respectively.
| Leading Market Players |
|---|
| Krystal Biotech, Inc. |
| Sarepta Therapeutics, Inc. |
| Horizon Therapeutics plc |
| Takeda Pharmaceutical Company Limited |
| Pfizer Inc. |
| Teijin Pharma Ltd. |
| BioMarin Pharmaceutical Inc. |
| PTC Therapeutics |
| Selecta Biosciences, Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive bioconjugation capabilities in the United States and Switzerland anchor both supply security and pricing power for pegloticase manufacturers, with in-house polyethylene glycol attachment expertise insulating against contract manufacturing bottlenecks while supporting premium positioning for REMS-compliant single-dose formats.
Pricing Analysis
Service bundling separates REMS certification support from standalone product supply, with comprehensive packages commanding premiums over unbundled vial-only transactions. Three-tier pricing structure across REMS-certified premium, standard hospital contract, and economy multi-dose tiers reflects site qualification overhead and waste-minimization protocols. Cost compression in the economy tier is intensifying because integrated delivery networks negotiate volume-based procurement contracts. Community rheumatology clinics exhibit highest price sensitivity due to limited patient throughput, while academic medical centers prioritize service reliability over unit cost.
Supply Chain Analysis
Reverse logistics for temperature-compromised pegloticase lots flows through specialized cold-chain recovery networks, with quarantined product returning to manufacturer quality assurance facilities for reclassification or destruction. Manufacturing concentration rests on the United States, Switzerland, and Japan for bioconjugation expertise and fill-finish operations. Critical inputs include recombinant uricase enzyme, monomethoxy polyethylene glycol, and sterile vial components. Single-source vulnerability concentrates in specialized PEGylation reagent suppliers. Distribution runs through REMS-certified specialty pharmacy networks with direct-to-site cold chain delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intravenous pegloticase market functions as a cost-of-compliance story, with the FDA's Risk Evaluation and Mitigation Strategy erecting a certification barrier that protects incumbent margins while forcing aspirants to absorb substantial site qualification investments.
For Market Incumbents: Acquire immune tolerance platform technologies to extend therapy persistence and defend against oral urate-lowering substitution threats. Consolidate REMS-certified infusion site networks to capture patient volume before biosimilar entry erodes pricing power. Expand backward integration into recombinant enzyme production to reduce single-source supplier dependency. For New Entrants and Emerging Players: EMA biosimilar guidance for pegylated enzymes in Europe opens a window for comparability exercise investment ahead of reference product exclusivity expiration. Target metropolitan clinic segments with underpenetrated rheumatology infrastructure and limited incumbent site density. Pursue licensing arrangements with established bioconjugation specialists to accelerate manufacturing readiness without captive facility investment. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-technology acquisitions by large-cap biologic manufacturers seeking immunogenicity mitigation capabilities. Long-term viability hinges on therapy persistence improvements that expand addressable patient pools beyond refractory chronic gout. Monitor anti-drug antibody surveillance innovation as the critical inflection signal for sustained revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Site Network Expansion | Captures refractory gout patient volume in underserved metropolitan corridors. |
| Immune Tolerance Platform Licensing | Addresses anti-drug antibody formation that limits chronic therapy persistence. |
| Biosimilar Manufacturing Readiness | Positions for EMA-guided pegylated enzyme follow-on entry post-exclusivity. |
| Home Infusion Channel Development | Extends access beyond hospital-based REMS-certified infusion centers. |
| Tumor Lysis Syndrome Protocol Expansion | Opens oncology-adjacent hyperuricemia applications in academic medical centers. |
Study Parameters
Document review covered FDA REMS documentation, EMA biosimilar guidance, and clinical trial registries, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary sources included formulary databases, hospital procurement records, and SEC filings from disclosed market participants. Bottom-up patient volume estimates and top-down market sizing were triangulated for consistency.
Historical prescription data and panel-based stakeholder input were cross-referenced to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type, end-user facility category, delivery mode, and indication status. CAGRs were derived from patient population projections, therapy persistence rates, and pricing trajectory assumptions. Immunogenicity mitigation technology adoption curves and site-of-care shift dynamics served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for immune tolerance platforms; alternative pathways for immunogenicity suppression would alter the outlook for therapy persistence and revenue durability. Forecasts reflect assumptions regarding REMS program continuity, biosimilar entry timing, and oral urate-lowering therapy failure rates. Practitioners should monitor anti-drug antibody surveillance innovation and home infusion regulatory adaptations for early signals of market inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
China Opioids Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market