
 Enbrel Market | 2026-2036
Enbrel Market Size, Share, and Industry Trends Forecast 2026-2036
Enbrel Market Insights
Pre-filled syringe bundling with patient support programs is repositioning how physicians and patients select TNF-alpha inhibitor therapy. Amgen Inc. leverages its decades-long manufacturing experience in biologics to sustain supply chain reliability for originator etanercept. Pfizer Inc. anchors its commercial presence through co-marketing agreements that extend reach across rheumatology and dermatology practices. Samsung Bioepis Co. Ltd. competes on biosimilar cost positioning while navigating complex patent litigation landscapes in key markets.
Etanercept constitutes a recombinant fusion protein combining the soluble TNF receptor p75 with the Fc portion of human IgG1, produced through Chinese hamster ovary cell culture and administered via subcutaneous injection to neutralize pro-inflammatory cytokines in autoimmune disease. Biologics occupy the dominant revenue position due to established clinical efficacy data and physician familiarity, though biosimilars represent the fastest-expanding category as regulatory frameworks mature and payer pressure intensifies. Subcutaneous injection leads delivery mode preference for Enbrel therapy, reflecting patient convenience and reduced healthcare facility dependency compared to intravenous alternatives.
FDA biosimilar guidelines under the BPCIA, EMA scientific advice pathways, and WHO prequalification standards collectively shape product development timelines, interchangeability designations, and market access conditions for etanercept competitors. The FDA's interchangeability determination process directly influences pharmacy-level substitution authority and payer formulary placement decisions across the United States. Stakeholders must monitor evolving regulatory precedents on biosimilar switching studies and real-world evidence requirements to anticipate competitive positioning shifts.
Market Dynamics
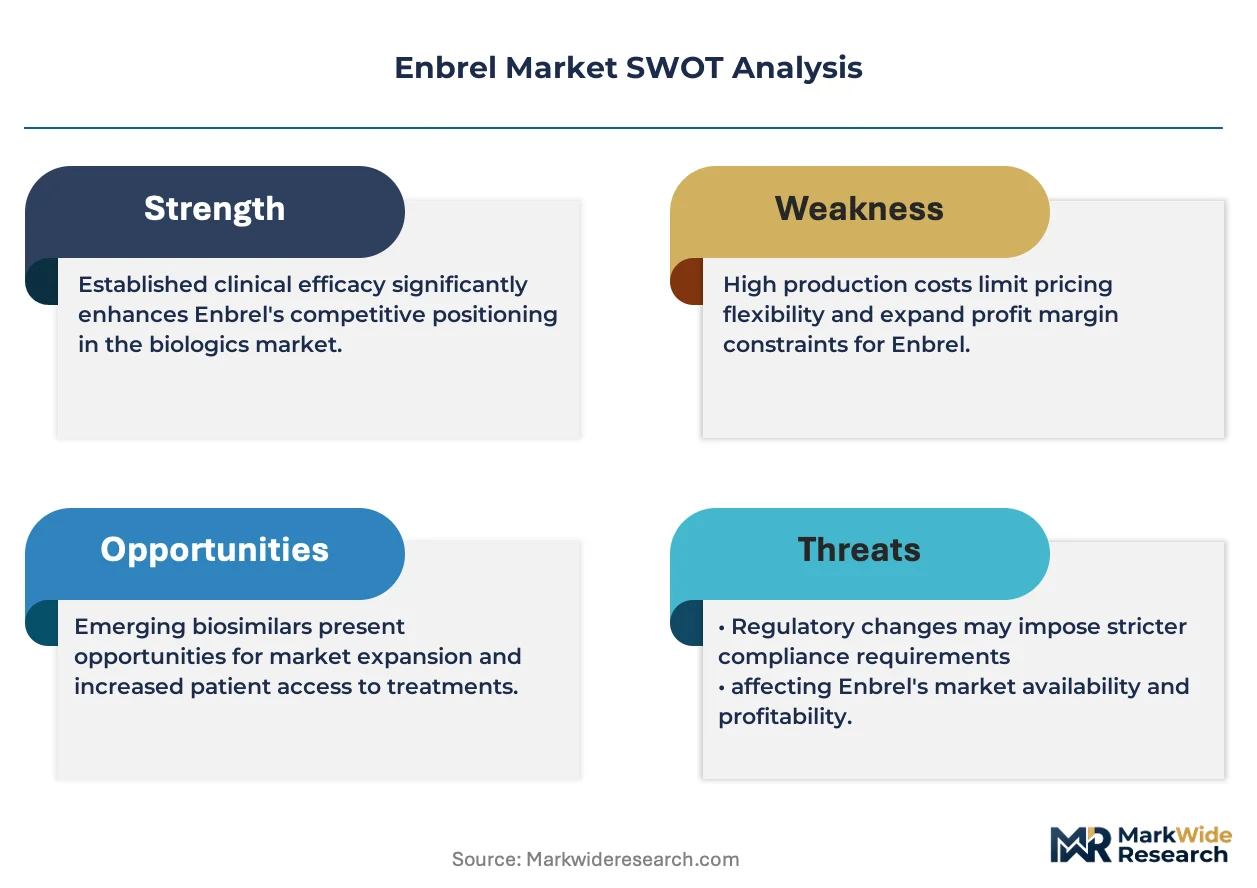
Originator brand loyalty in the United States confronts biosimilar cost pressure as FDA interchangeability determinations reshape pharmacy-level substitution authority and payer formulary negotiations.
Growth Catalysts
- BPCIA biosimilar pathway maturation:FDA interchangeability standards clarify substitution protocols, enabling pharmacy-level biosimilar dispensing that expands patient access to etanercept therapy.
- Rheumatology clinic consolidation:Large specialty practice networks in the United States standardize TNF-alpha inhibitor protocols, streamlining formulary placement for established biologics.
- Subcutaneous delivery preference:Patient self-administration models reduce infusion center dependency and align with value-based care incentives from Medicare Advantage plans.
Market Restraints
- Patent litigation complexity:Biosimilar manufacturers face extended legal challenges from originator holders, delaying market entry and compressing commercialization windows.
- Chinese hamster ovary cell supply concentration:Biologics production depends on limited qualified cell line suppliers, creating vulnerability in upstream raw material security.
- Reimbursement rate compression:Medicare Part B ASP-based pricing and Medicaid best-price requirements constrain net revenue realization for originator products.
Strategic Opportunities
- Real-world evidence integration:Switching studies and patient registry data can support interchangeability petitions under FDA guidance, accelerating biosimilar uptake.
- Dermatology practice expansion:Psoriasis and psoriatic arthritis indications in dermatology clinics represent underpenetrated prescription volume relative to rheumatology saturation.
- Patient support program digitalization:Mobile-enabled adherence tracking and copay assistance platforms reduce therapy abandonment rates in commercial insurance populations.
Industry Challenges
- Cold chain logistics complexity:Temperature-controlled distribution from manufacturing through last-mile delivery requires validated infrastructure that strains regional pharmacy networks.
- Immunogenicity surveillance capability:Post-market pharmacovigilance for neutralizing antibody development demands specialized laboratory partnerships that biosimilar entrants must construct rapidly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enbrel Market |
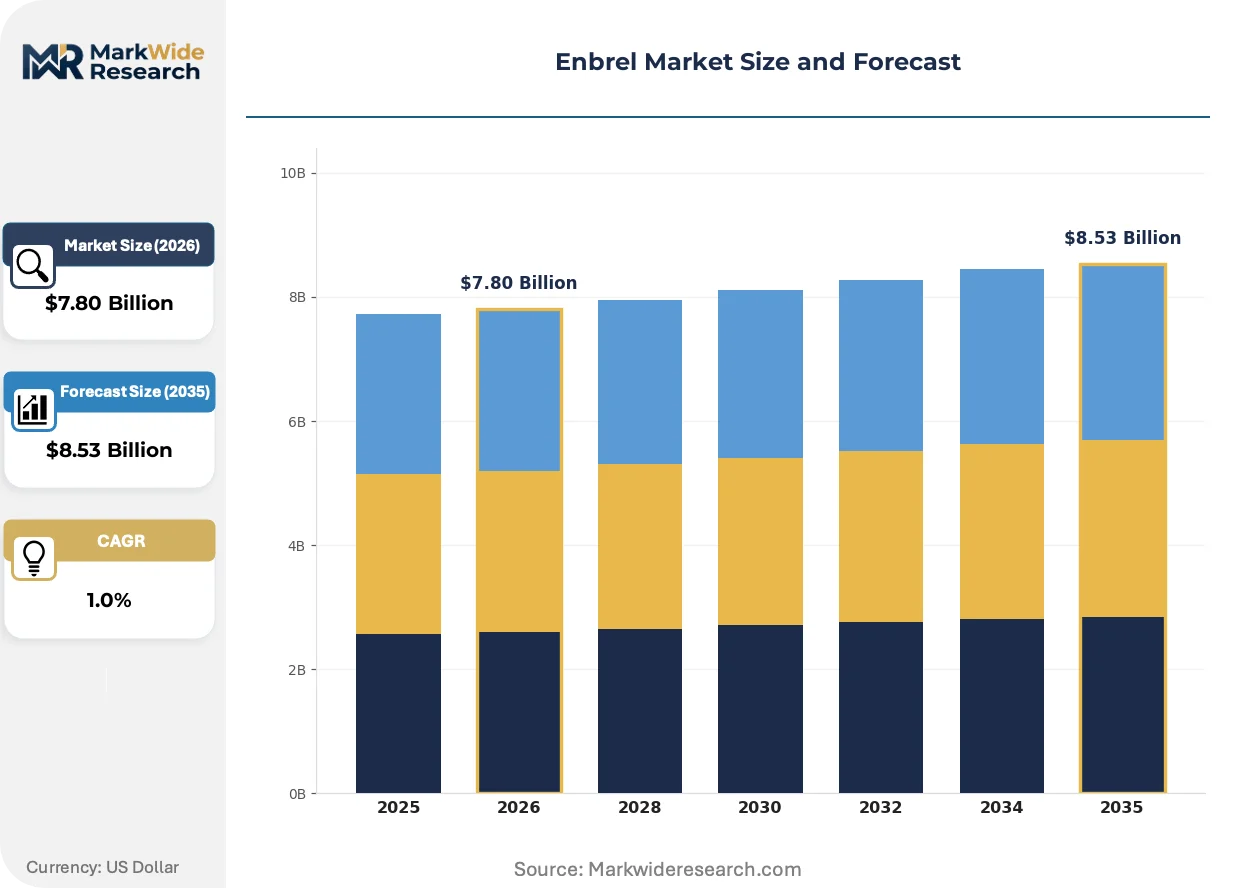
| Market Size in 2026 | $7.80 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Biosimilars, Combination Therapies Therapy Area: Rheumatoid Arthritis, Psoriasis, Ankylosing Spondylitis, Juvenile Idiopathic Arthritis Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Oral Administration, Topical Application End User: Hospitals, Specialty Clinics, Homecare Settings, Pharmacies |
| Companies Covered | Amgen Inc., Pfizer Inc., Samsung Bioepis Co. Ltd., Biogen Inc., Novartis AG, Merck & Co. Inc., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Celltrion Healthcare Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enbrel Market Trends and Innovations
Pre-filled syringe and autoinjector formats are compressing site-of-care requirements while biosimilar developers invest in analytical biosimilarity packages that satisfy evolving FDA expectations for structural and functional equivalence.
High-concentration etanercept formulations are unifying patient convenience with reduced injection frequency. Rheumatology practices in the United States are adopting these presentations to minimize nursing time and patient training burden. The technology is unifying originator and biosimilar competitive positioning around injection experience rather than molecular differentiation alone.
EMA scientific advice pathways and FDA BPCIA guidance are converging on expectations for extensive analytical characterization and immunogenicity assessment. Biosimilar sponsors must demonstrate structural similarity across glycosylation profiles and aggregate content. European reference product sourcing requirements complicate global development strategies for multi-regional filers.
Specialty pharmacy channel consolidation is concentrating dispensing authority among three national distributors. Independent rheumatology practices face administrative burden from mandated specialty pharmacy relationships that fragment prescription fulfillment. This shift is most visible in Medicare Part D and commercial managed care populations where pharmacy benefit managers enforce narrow network requirements.
Enbrel Market Segmentation

Segmentation of the Enbrel market reveals how molecular architecture, clinical indication, administration route, and care setting each shape procurement decisions and reimbursement pathways. Understanding these axes enables stakeholders to align manufacturing capacity with concentrated demand pockets and regulatory requirements.
Product Type:
Recombinant protein engineering and cell culture sophistication define competitive positioning across molecular categories.
- Biologics:Etanercept fusion proteins manufactured via Chinese hamster ovary cell culture deliver established clinical efficacy profiles that sustain physician prescribing habits in United States rheumatology practices. Originator biologics command formulary preference where FDA interchangeability determinations remain pending and payer step-therapy protocols favor demonstrated real-world safety data.
- Biosimilars:Analytical biosimilarity packages demonstrating structural equivalence to reference etanercept are expanding pharmacy-level substitution authority under maturing BPCIA guidance. Samsung Bioepis and other sponsors leverage cost positioning to secure Medicare Advantage and Medicaid formulary placement where state substitution laws permit.
- Small Molecules:Oral JAK inhibitors and conventional DMARDs occupy earlier treatment lines and combination protocols with TNF-alpha inhibitors.
- Combination Therapies:Etanercept paired with methotrexate or other immunomodulators addresses refractory disease presentations.
Biologics lead on scale; biosimilars lead on momentum.
Therapy Area:
Disease severity, progression risk, and unmet medical need vary sharply across autoimmune indications.
- Rheumatoid Arthritis:Joint destruction prevention drives long-term etanercept maintenance therapy in United States Medicare populations, with rheumatology clinic networks standardizing TNF-alpha inhibitor protocols as first-line biologic after methotrexate failure. Medicare Part B ASP-based reimbursement and prior authorization requirements shape prescribing patterns.
- Psoriasis:Dermatology practices represent underpenetrated prescription volume relative to rheumatology saturation, with plaque severity scoring systems determining biologic eligibility under commercial insurance policies. Patient self-administration models align with reduced healthcare facility dependency preferences.
- Ankylosing Spondylitis:Axial skeleton involvement and diagnostic delays concentrate demand in academic medical center rheumatology departments.
- Juvenile Idiopathic Arthritis:Pediatric dosing requirements and growth monitoring protocols necessitate specialized pediatric rheumatology referral networks.
Rheumatoid arthritis leads on scale; psoriasis leads on momentum.
Delivery Mode:
Patient convenience and site-of-care economics drive administration technology selection.
- Subcutaneous Injection:Pre-filled syringe and autoinjector formats enable home administration, reducing infusion center costs and aligning with Medicare Advantage value-based care incentives. High-concentration formulations further compress injection frequency and nursing time requirements.
- Intravenous Infusion:Hospital outpatient departments retain infusion preference for combination protocols and patients with needle phobia or adherence concerns.
- Oral Administration:Small molecule alternatives occupy non-biologic treatment lines and combination approaches.
- Topical Application:Localized psoriasis presentations may receive topical corticosteroid or vitamin D analogue adjunctive therapy.
Subcutaneous injection leads on scale; high-concentration subcutaneous formulations lead on momentum.
End User:
Reimbursement mechanics and care coordination requirements fragment dispensing authority across settings.
- Specialty Clinics:United States rheumatology and dermatology practices concentrate biologic prescribing, with large specialty networks standardizing formulary protocols that streamline prior authorization workflows. Consolidated practice management systems enable real-world evidence collection for switching studies.
- Hospitals:Academic medical centers and community hospitals manage infusion-based protocols and complex comorbidity presentations requiring multidisciplinary care.
- Homecare Settings:Self-administration models expand with specialty pharmacy distribution networks and patient support program digitalization.
- Pharmacies:Retail and specialty pharmacy channel consolidation concentrates dispensing among national distributors with validated cold chain infrastructure.
Specialty clinics lead on scale; homecare settings lead on momentum.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Etanercept therapy originated in United States biotechnology clusters during the 1990s recombinant protein revolution, with subsequent commercialization establishing the country as the foundational market for TNF-alpha inhibitor development and adoption patterns.
United States
Medicare Part B ASP-based reimbursement and rheumatology clinic consolidation sustain originator brand preference despite biosimilar availability. The FDA's BPCIA interchangeability pathway underpins pharmacy-level substitution authority debates. Boston and San Francisco biotech corridors concentrate legacy manufacturing infrastructure and patient registry data collection for switching studies.
Germany
Statutory health insurance reference pricing and EMA biosimilar guidance accelerate etanercept biosimilar penetration in outpatient rheumatology care. The AMNOG early benefit assessment framework shapes reimbursement negotiations for new biologic entrants. The Rhine-Main and Munich metropolitan regions host specialized immunology practices that standardize TNF-alpha inhibitor protocols across large patient populations.
Japan
Aging demographics and ankylosing spondylitis diagnostic expansion drive biologic demand in academic medical center rheumatology departments. PMDA biosimilar guidelines emphasize immunogenicity surveillance requirements that extend post-market study obligations. The Kanto region surrounding Tokyo concentrates prescription volume and specialist referral networks for autoimmune disease management.
United Kingdom
NICE technology appraisals and NHS England commissioning frameworks restrict etanercept prescribing to specific disease severity thresholds and prior authorization pathways. The MHRA post-Brexit regulatory autonomy enables divergence from EMA biosimilar guidance on interchangeability designations. The Greater Manchester and West Midlands health systems pilot real-world evidence collection for biologic switching protocols.
France
HAS transparency committee evaluations and hospital pharmacy tendering consolidate etanercept procurement across public sector rheumatology services. ANSM pharmacovigilance requirements mandate systematic immunogenicity reporting that shapes prescriber confidence in biosimilar alternatives. The Paris metropolitan area and Lyon biotech cluster anchor clinical trial infrastructure and reference product sourcing for biosimilar development programs.
Enbrel Market Competitive Landscape
Premium-margin players sit above commodity-margin players across patent protection duration and manufacturing sophistication, with originator biologics commanding formulary preference through established real-world safety databases while biosimilar entrants compete on acquisition cost and interchangeability status. The vendor base stratifies into three archetypes: legacy biologics manufacturers with decades-long cell culture expertise, biosimilar specialists leveraging analytical biosimilarity packages for regulatory acceleration, and diversified pharmaceutical conglomerates with rheumatology franchise breadth. Dominant competitive moves include patent litigation defense to compress biosimilar commercialization windows and specialty pharmacy partnership consolidation to control distribution channel access.
Within the originator biologics tier, Amgen Inc. and Pfizer Inc. exemplify established market presence through co-marketing structures that extend physician reach across rheumatology and dermatology specialties. Samsung Bioepis Co. Ltd. occupies the biosimilar specialist position, representing cost-competitive entry strategies that navigate complex intellectual property landscapes while pursuing FDA interchangeability designations. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Amgen Inc. |
| Pfizer Inc. |
| Samsung Bioepis Co. Ltd. |
| Biogen Inc. |
| Novartis AG |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Celltrion Healthcare Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Chinese hamster ovary cell culture specialists in Massachusetts and California command wage premiums that compress margins for biosimilar entrants while sustaining originator pricing power across premium and standard tiers. Labor-cost differentials between legacy biologics manufacturers and emerging biosimilar sponsors directly determine the spread between interchangeability-designated and reference-product pricing.
Pricing Analysis
Aspiration-based reimbursement contracting dominates United States etanercept procurement, with Medicare Part B ASP benchmarks and Medicaid best-price requirements compressing net revenue realization. Price differentiation separates originator biologics with established immunogenicity databases from FDA-interchangeable biosimilars competing on acquisition cost. Pricing pressure intensifies as pharmacy benefit managers consolidate formulary placement authority and mandate step-therapy protocols. Rheumatology practices with high Medicare Advantage penetration exhibit greatest price sensitivity; academic medical centers with research funding demonstrate lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle the majority of etanercept dispensing, with three national distributors controlling cold chain logistics from manufacturing through patient delivery. Cell culture media and single-use bioreactor components draw from suppliers concentrated in the United States, Germany, and Japan. Single-source vulnerability in pristane-free cell line qualification creates upstream risk for multi-product biologics facilities. Temperature-controlled distribution rests on validated infrastructure that strains regional pharmacy networks managing last-mile delivery to homecare settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Enbrel market functions as a stable compounder anchored by chronic disease maintenance requirements and limited therapeutic substitution in established rheumatology protocols. Autoimmune disease prevalence demographics sustain prescription volume regardless of economic cyclicality.
For Market Incumbents: Cement formulary preference through real-world evidence investments that support FDA interchangeability defense and switching study sponsorship. Expand backward integration into Chinese hamster ovary cell line development to reduce raw material security exposure. Prioritize specialty pharmacy partnership consolidation to control distribution channel access against biosimilar cost positioning. For New Entrants and Emerging Players: Specialty pharmacy networks with narrow Medicare Part D contracts represent the most penetrable channel for biosimilar volume capture. Target dermatology practices in the United States where TNF-alpha inhibitor protocols remain less standardized than rheumatology saturation. Pursue state-level substitution law advocacy to accelerate pharmacy-level dispensing authority ahead of interchangeability determinations. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with rheumatology franchise breadth are the most active acquirers in this space, seeking biologics manufacturing capabilities and established physician relationships. Acquisition targets should display analytical biosimilarity package maturity and pending FDA interchangeability petitions. Watch for CMS reimbursement rate compression announcements as inflection indicators for originator margin trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interchangeability Petition | Pharmacy-level substitution authority under BPCIA guidance accelerates biosimilar uptake in Medicare populations. |
| Real-World Evidence Registry | Switching study data supports originator formulary defense against cost-competitive biosimilar entry. |
| Specialty Pharmacy Partnership | Narrow network consolidation with national distributors controls patient access and adherence monitoring. |
| High-Concentration Formulation Launch | Reduced injection frequency aligns with Medicare Advantage value-based care incentives and nursing efficiency. |
| Cell Line Backward Integration | In-house Chinese hamster ovary cell development mitigates single-source raw material vulnerability. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and France, with primary inputs from each market informing cross-regional comparisons. The analysis combines structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down revenue triangulation ensure convergence across independent estimation approaches.
Rate-of-change decomposition separates volume growth from price realization effects across the projection horizon. Segmentation dimensions include product type, therapy area, delivery mode, and end-user setting alongside regional regulatory cluster differentiation. CAGRs derive from patient population epidemiology, treatment line progression rates, and biosimilar penetration assumptions. Forecast inputs incorporate rheumatology clinic consolidation trends and pharmacy benefit manager formulary placement protocols.
Revisions become necessary when FDA interchangeability determinations, patent litigation outcomes, or Medicare reimbursement rate adjustments materialize outside base-case assumptions. Forecasts reflect documented assumptions regarding biosimilar switching study completion timelines and state substitution law expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Global Antipsychotic Drugs Market