
 Hair Growth Supplement and Treatment Market | 2026-2036
Hair Growth Supplement and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Growth Supplement and Treatment Market Analytics
The capital-intensity gap between pharmaceutical-grade manufacturers and commodity supplement producers is collapsing as clinical validation requirements escalate across all channels. Nutrafol leverages its physician-dispensed platform to sustain premium positioning in the dermatology channel. Viviscal anchors its European heritage credentials to compete against newer entrants in the North American direct-to-consumer space. Hims & Hers controls telehealth prescription flow to extend its reach beyond supplements into regulated topical and oral therapies.
Hair growth supplements and treatments encompass orally administered nutritional formulations, topically applied pharmacological solutions, and device-assisted delivery systems engineered to modulate follicular cycling, inhibit dihydrotestosterone activity, or correct micronutrient deficiencies implicated in telogen effluvium. The primary commercial purpose centers on non-surgical intervention for androgenetic alopecia, traction alopecia, and chemotherapy-induced hair loss across outpatient and self-directed care settings. Topical solutions and serums capture the dominant margin pool due to higher per-unit pricing and repeat purchase frequency, while vitamins and tablets occupy the volume-leadership position through broader retail distribution. Natural extracts within the formulation dimension attract the fastest-growing investment as consumers migrate from synthetic chemicals toward botanical-derived actives with published clinical evidence.
FDA oversight of minoxidil concentration claims and FTC substantiation requirements for before-and-after marketing shape product development budgets and launch timelines for all entrants. The EPA registers certain preservative systems used in topical formulations, creating additional compliance layers for multi-ingredient serums. Stakeholders must monitor how regulatory divergence between the FDA's drug-cosmetic boundary and the EU's stricter REACH chemical restrictions affects global product portfolio architecture and manufacturing location decisions.
Market Dynamics
The FDA's tightening drug-cosmetic boundary enforcement is compressing formulation timelines and forcing capital reallocation toward clinical validation infrastructure across all market tiers.
Growth Catalysts
- Telehealth prescription platforms:Direct-to-consumer channels in the United States bypass traditional pharmacy networks and accelerate patient access to regulated therapies.
- REACH botanical standards:The EU's chemical registration framework validates natural extract safety profiles, enabling premium positioning for plant-derived actives in European dermatology channels.
- Dermatology clinic expansion:Trichology centers in Germany, South Korea, and Brazil integrate non-surgical protocols, creating institutional demand for physician-dispensed supplement lines.
Market Restraints
- API supply concentration:Minoxidil active pharmaceutical ingredient production clusters in Chinese and Indian chemical hubs, exposing formulators to export licensing volatility.
- Clinical trial cost inflation:FDA substantiation requirements for hair count claims now demand photographic endpoint studies exceeding twelve months, elevating entry capital thresholds.
- Generic topical substitution:Compounding pharmacies in the United States produce unbranded minoxidil-finasteride combinations at price points below commercial serums.
Strategic Opportunities
- Post-chemotherapy recovery segment:Oncology centers in the United States and United Kingdom seek partnership-ready supplement protocols for alopecia areata management.
- IRA manufacturing incentives:Domestic production tax credits under the Inflation Reduction Act reduce facility cost burdens for U.S.-based topical formulation plants.
- AI-driven follicle imaging:Smartphone-connected trichoscopy apps enable remote monitoring, creating subscription attachment points for supplement replenishment programs.
Industry Challenges
- Trichologist certification bottlenecks:The limited pipeline of board-certified specialists constrains clinic network expansion and protocol standardization.
- Cross-border formulation harmonization:Divergent preservative approvals between FDA and ECHA force dual-SKU strategies that fragment inventory economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Growth Supplement and Treatment Market |
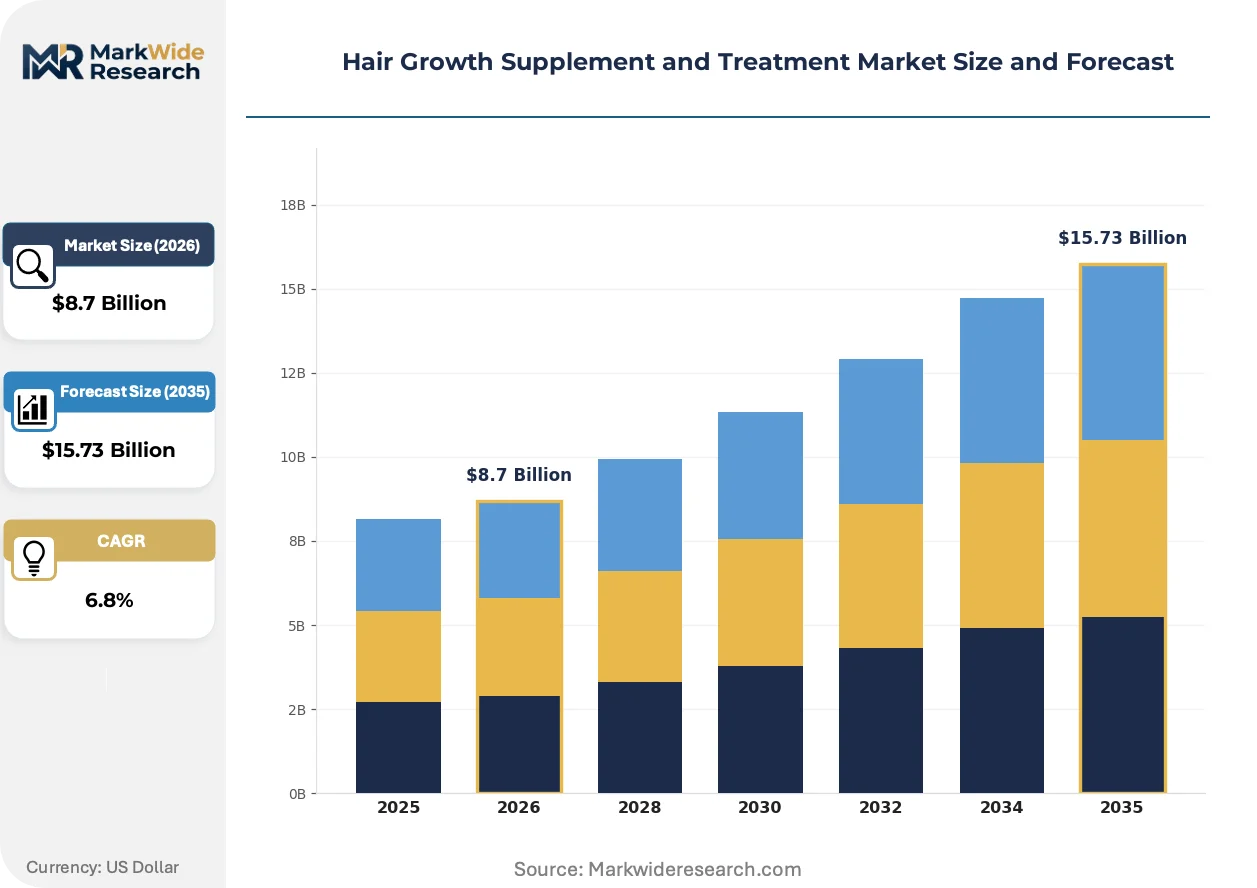
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Topical Solutions, Serums, Tablets Application: Male Pattern Baldness, Female Hair Loss, Scalp Treatment, Post-Chemotherapy Formulation: Natural Extracts, Synthetic Chemicals, Hormonal Treatments, Combination Formulations Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Health Food Stores |
| Companies Covered | Life Extension, Viviscal, Nutrafol, Garden of Life, Ritual, Happy Head, Horbäach, Briogeo, Hims & Hers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Growth Supplement and Treatment Market Evolving Landscape
Formulation science and patient data infrastructure are converging to reshape how efficacy is demonstrated and monetized across prescription and consumer channels.
Low-level laser therapy devices are bifurcating the at-home treatment segment from clinic-dependent protocols. Capillus and iRestore units now sell through dermatology dispensaries and Amazon storefronts simultaneously. This channel duality is compressing margin structures for device manufacturers while expanding addressable patient populations beyond metropolitan clinic catchments.
REACH Annex XVII restrictions on formaldehyde-releasing preservatives are forcing reformulation of European topical serums by 2025. German and French manufacturers accelerate phenoxyethanol and ethylhexylglycerin substitution programs. The compliance burden falls heaviest on mid-tier brands lacking captive toxicology testing infrastructure.
Subscription auto-replenishment now dominates direct-to-consumer acquisition economics. Hims & Hers and Roman have unbundled the initial consultation from product margin, treating supplements as loss-leader attachments to prescription flows. This behavioral shift concentrates lifetime value calculation in telehealth platforms rather than retail shelf velocity.
Hair Growth Supplement and Treatment Market Segmentation
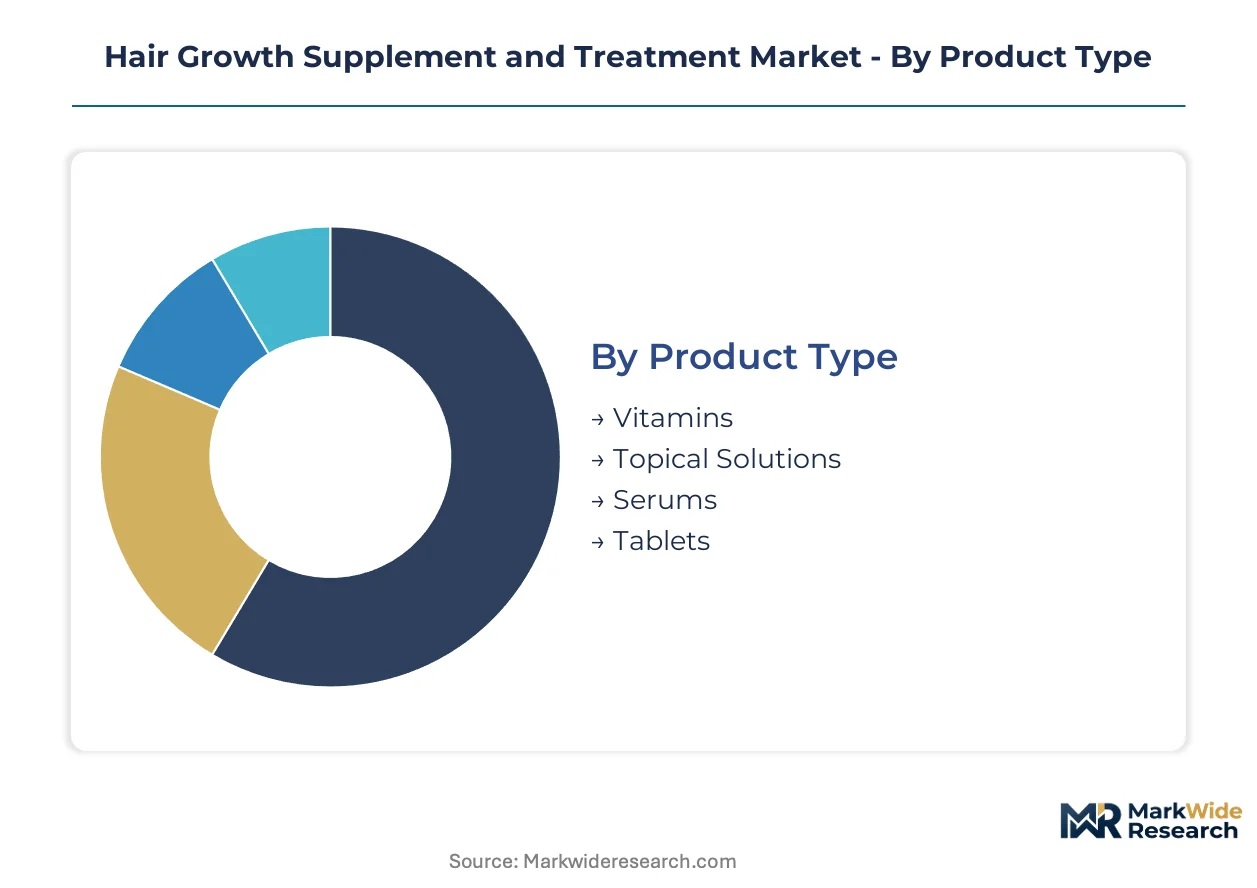
Segmentation in hair growth markets determines regulatory pathway selection and margin capture potential. Product form dictates whether FDA drug classification applies, while distribution channel shapes customer acquisition economics and repeat purchase velocity.
Product Type:
Substitution pressure from compounding pharmacies and private-label entrants is eroding margin pools most aggressively in tablet and vitamin categories, forcing branded players toward clinically differentiated topical formats.
- Topical Solutions:Alcohol-based or aqueous vehicles delivering minoxidil or alternative vasodilators directly to follicular units. Dermatology clinics in the United States and Germany are consolidating procurement around prescription-strength concentrations as telehealth platforms normalize medical-grade access.
- Serums:Higher-viscosity formulations incorporating peptide complexes, growth factors, or botanical extracts. South Korean manufacturers lead innovation in fermented extract delivery systems, with Seoul-based trichology centers driving institutional adoption of premium serum protocols.
- Vitamins:Oral micronutrient blends targeting biotin, zinc, and iron deficiencies linked to telogen effluvium.
- Tablets:Systemic pharmacological interventions including finasteride and dutasteride for androgenetic alopecia.
Tablets retain volume leadership; serums hold the steepest expansion curve.
Application:
Cost tier stratification separates medical necessity-driven segments from discretionary cosmetic categories, with reimbursement eligibility determining pricing power.
- Male Pattern Baldness:The largest addressable population segment, characterized by predictable progression of androgenetic alopecia. United States direct-to-consumer platforms have concentrated demand capture through subscription bundling of oral finasteride with topical minoxidil.
- Post-Chemotherapy:Acute hair loss requiring specialized scalp care and growth stimulation protocols. Oncology centers in the United Kingdom and United States are formalizing partnership frameworks with supplement manufacturers for patient discharge kits.
- Female Hair Loss:Diffuse thinning patterns driven by hormonal fluctuation, nutritional deficiency, or autoimmune factors.
- Scalp Treatment:Condition-specific interventions for psoriasis, seborrheic dermatitis, or folliculitis compromising hair retention.
Male pattern baldness dominates revenue concentration; post-chemotherapy applications are expanding most quickly.
Formulation:
Customer type migration—from synthetic-tolerant legacy users to botanical-preferring wellness consumers—is fragmenting R&D allocation across incompatible formulation philosophies.
- Natural Extracts:Plant-derived actives including saw palmetto, pumpkin seed oil, and marine collagen peptides. REACH Annex XVII compliance in Germany and France is accelerating toxicology investment for preservative-free botanical preservation systems.
- Hormonal Treatments:Anti-androgenic compounds modulating 5-alpha reductase activity or androgen receptor binding. FDA REMS requirements for finasteride dispensing constrain channel expansion beyond certified pharmacy networks.
- Synthetic Chemicals:Laboratory-synthesized molecules including minoxidil, ketoconazole, and prostaglandin analogues.
- Combination Formulations:Multi-mechanism products integrating hormonal, vascular, and nutritional pathways.
Synthetic chemicals retain volume leadership; natural extracts hold the steepest expansion curve.
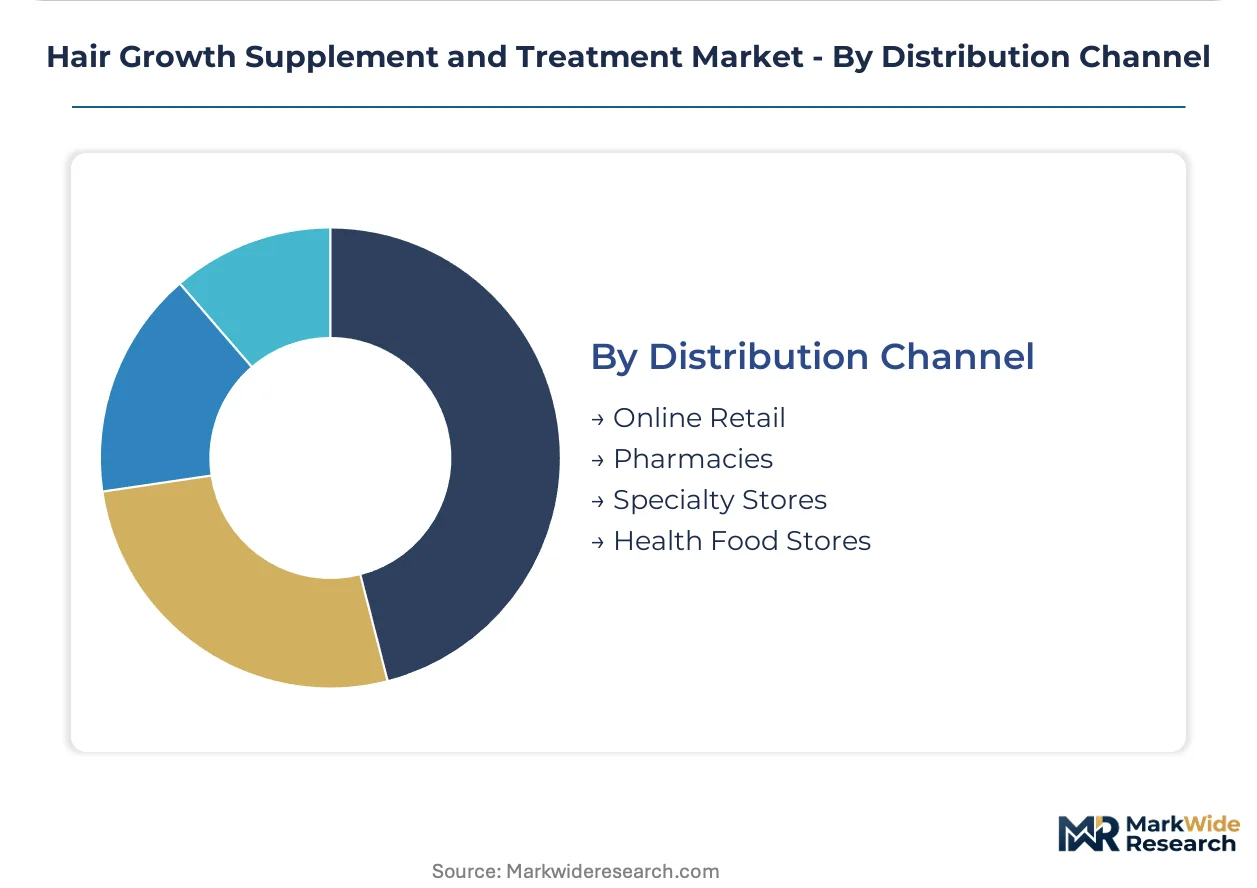
Distribution Channel:
Supply concentration in API manufacturing clusters shapes channel economics, with vertically integrated formulators capturing margin from raw material through patient delivery.
- Online Retail:Direct-to-consumer platforms, marketplace aggregators, and subscription services. Hims & Hers and Roman have unbundled consultation from product margin, using supplements as loss-leader attachments to prescription flows.
- Pharmacies:Brick-and-mortar and mail-order dispensaries handling regulated therapeutics. CVS and Walgreens in the United States are expanding private-label topical minoxidil lines at price points compressing branded serum margins.
- Specialty Stores:Dermatology dispensaries, trichology clinics, and medical spa retail counters.
- Health Food Stores:Natural products retailers emphasizing organic certification and clean-label positioning.
Pharmacies retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across geographies. United States consumers absorb premium pricing for prescription-strength treatments, while price sensitivity dominates mass-market supplement uptake in India and Southeast Asian corridors.
United States
Telehealth platforms concentrate patient acquisition in coastal metropolitan corridors. FDA enforcement of drug-cosmetic boundaries tightens formulation standards for topical serums. Boston and San Francisco dermatology clusters drive institutional adoption of physician-dispensed supplement protocols.
Germany
Trichology centers in Munich and Hamburg integrate non-surgical hair restoration into standard dermatology practice. ECHA REACH Annex XVII restrictions on preservative systems force reformulation of European topical serums by 2025. The Rhine-Ruhr manufacturing belt hosts specialized toxicology testing infrastructure for botanical extract validation.
South Korea
Seoul-based beauty technology companies advance fermented extract delivery systems for scalp treatment protocols. MFDS registration requirements for functional cosmetics create compliance barriers for imported supplement lines. The Gyeonggi-do province concentrates contract manufacturing capacity for K-beauty hair care exports.
United Kingdom
Oncology centers in London and Manchester formalize partnership frameworks for post-chemotherapy scalp care protocols. MHRA oversight of medicinal product claims constrains marketing language for nutritional supplements. The Cambridge-Oxford corridor attracts venture investment in follicle imaging diagnostics.
Brazil
São Paulo trichology clinics expand institutional procurement of physician-grade supplement lines. ANVISA registration timelines for imported active pharmaceutical ingredients extend product launch cycles. The Campinas pharmaceutical cluster develops local minoxidil formulation capacity to reduce import dependency.
Hair Growth Supplement and Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the hair growth supplement and treatment market. Pharmaceutical-grade manufacturers with captive clinical validation infrastructure capture margin from commodity supplement producers. Three archetypes dominate: telehealth-integrated platforms, dermatology-dispensed premium brands, and private-label contract manufacturers. Strategic moves concentrate on M&A to secure API supply chains and geographic licensing partnerships to bypass regulatory bottlenecks.
Among telehealth-integrated platforms, Hims & Hers occupies a position exemplifying the unbundled consultation model, using supplements as entry attachments to prescription flows. Within the dermatology-dispensed tier, Nutrafol represents premium positioning sustained through physician channel relationships. Viviscal anchors the European heritage archetype competing in North American direct-to-consumer channels. These three companies illustrate how channel control and regulatory navigation separate market tiers.
| Leading Market Players |
|---|
| Life Extension |
| Viviscal |
| Nutrafol |
| Garden of Life |
| Ritual |
| Happy Head |
| Horbäach |
| Briogeo |
| Hims & Hers |
| Others |
Value Network & Pricing Analysis
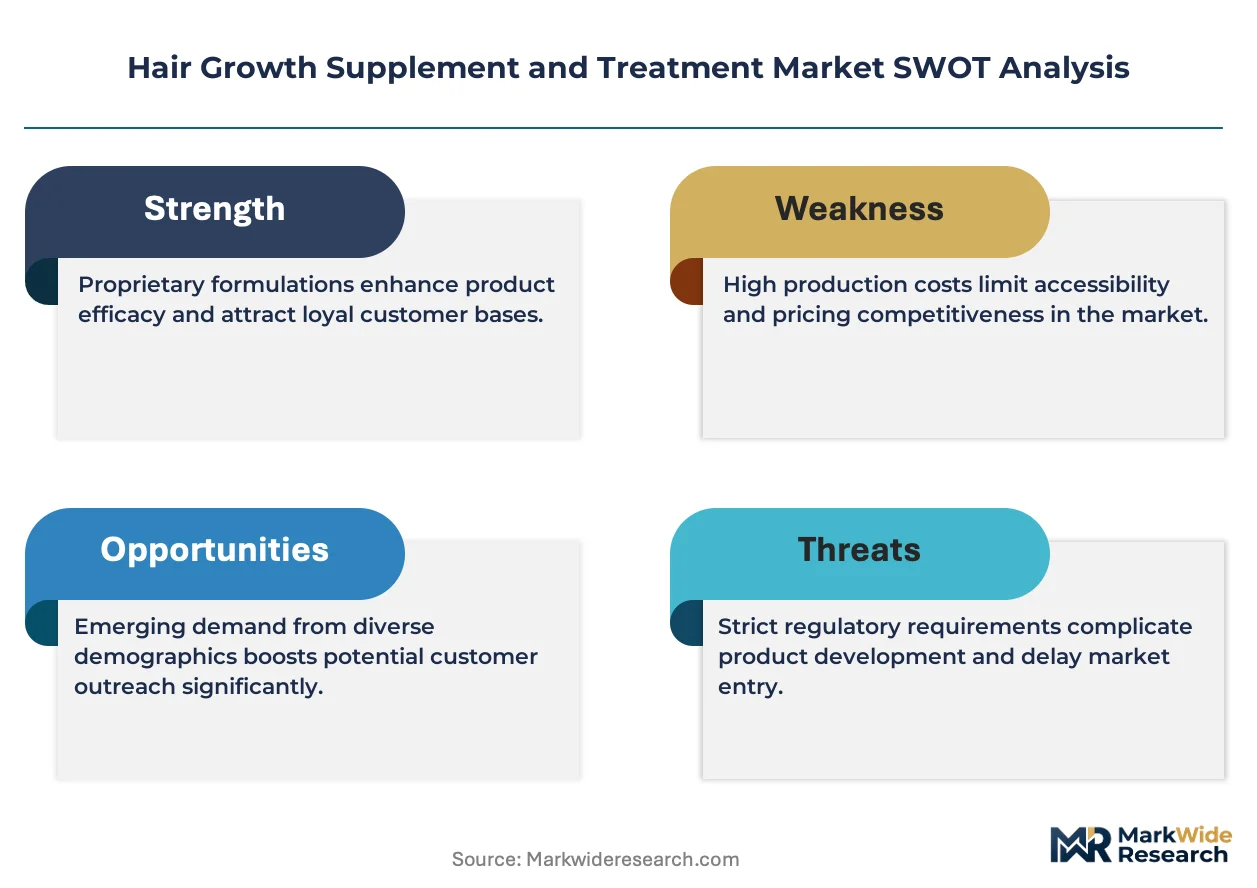
Generic minoxidil substitution by United States compounding pharmacies is displacing branded serum economics while simultaneously shifting procurement gravity toward Indian and Chinese API hubs. This input swap compresses margin pools for formulation-heavy players and rewards vertically integrated manufacturers with captive active pharmaceutical ingredient supply.
Pricing Analysis
Subscription auto-replenishment drives lifetime value capture for telehealth platforms treating supplements as entry attachments to prescription flows. Three-tier pricing structure across premium physician-dispensed, standard retail, and economy private-label levels separates Nutrafol's dermatology channel positioning from CVS private-label minoxidil compression. Pricing pressure stems from generic topical substitution as compounding pharmacies undercut commercial serum price points. Direct-to-consumer platforms exhibit lowest price sensitivity; mass-market retail buyers demonstrate highest elasticity.
Supply Chain Analysis
API export licensing volatility from Chinese and Indian chemical hubs exposes formulators to supply interruption. Minoxidil active pharmaceutical ingredient production draws from Zhejiang province and Mumbai manufacturing belts, while botanical extract supply rests on German and French toxicology validation infrastructure. Single-source vulnerability concentrates in minoxidil precursor chemicals subject to export control fluctuations. Distribution runs through dermatology dispensaries, telehealth platforms, and pharmacy networks in tiered channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hair growth supplement and treatment market sits in early-cycle expansion as telehealth prescription platforms normalize medical-grade access for previously cosmetic-only patient segments.
For Market Incumbents: Shield premium positioning through physician channel exclusivity and clinical validation infrastructure investment against compounding pharmacy substitution. Deepen backward integration into botanical extract supply through German toxicology partnerships to secure REACH-compliant preservative systems. Channel control in dermatology dispensaries remains the critical defensive lever. For New Entrants and Emerging Players: Differentiate on post-chemotherapy recovery protocols where oncology center partnership frameworks remain underpenetrated. Target the United Kingdom and United States hospital discharge kit segment with alopecia areata management supplements. Pursue AI-driven follicle imaging integration as a subscription attachment mechanism for patient retention. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors telehealth-integrated players with prescription flow control over pure-play supplement brands. Five-to-ten year viability hinges on regulatory navigation capability across FDA drug-cosmetic boundaries. Acquisition targets should demonstrate EU REACH compliance infrastructure. The signal to watch is FDA enforcement intensity on cosmetic versus drug classification for topical peptide formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Twelve-month photographic endpoint studies satisfy FDA substantiation requirements for hair count claims. |
| Regulatory Approval Pathway | MFDS functional cosmetics registration in South Korea creates compliance moats against imported competitors. |
| Backward Integration | In-house minoxidil API production insulates formulators from Indian and Chinese export licensing volatility. |
| Direct-to-Consumer Launch | Telehealth platform unbundling of consultation from product margin replicates Hims & Hers acquisition economics. |
| Distribution Channel Expansion | Dermatology clinic procurement consolidation in Germany and Brazil captures institutional supplement demand. |
Research Methodology
A spread of perspectives from trichology center directors, dermatology clinic procurement managers, telehealth platform executives, and compounding pharmacy operators converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation against FDA 510(k) filings, ECHA REACH registration databases, ClinicalTrials.gov intervention records, and customs trade data for minoxidil API flows. Bottom-up patient population modeling and top-down market sizing triangulated volume and value estimates.
Segmentation dimensions modeled span product type, application indication, formulation chemistry, and distribution channel across the projection horizon. CAGRs derived from patient population growth, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated telehealth prescription platform expansion rates and dermatology clinic network development in target geographies.
Material uncertainties — regulatory reclassification of topical peptides as drugs, API export restriction imposition, and telehealth prescribing authority changes — sit outside the modeled envelope. Forecasts reflect assumptions about FDA enforcement continuity and REACH Annex XVII implementation timelines. Practitioners should keep alternative scenarios live as drug-cosmetic boundary adjudication evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Herbal Nutraceuticals Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market