
 Fibromyalgia Antidepressant Market | 2026-2036
Fibromyalgia Antidepressant Market Size, Share, and Industry Trends Forecast 2026-2036
Fibromyalgia Antidepressant Market Insights
Prescription-grade extended-release formulations is redrawing competitive boundaries in fibromyalgia antidepressant therapy. Pfizer leverages its neurology infrastructure to sustain branded duloxetine positioning across major markets. Eli Lilly and Company anchors its portfolio through specialized pain-care channels that prioritize clinician education. AbbVie differentiates via integrated access programs linking pharmacological intervention to complementary therapy protocols.
Fibromyalgia antidepressants comprise serotonin-norepinephrine reuptake inhibitors, tricyclic compounds, and atypical agents formulated for chronic neuropathic pain modulation, typically requiring bioavailability above 80% and steady-state plasma concentration within 3-7 days to achieve therapeutic effect in centralized pain states. These compounds serve primary commercial purpose by addressing FDA-recognized fibromyalgia diagnostic criteria including widespread pain index scores and symptom severity scales. Duloxetine and milnacipran dominate the product-type landscape as established first-line pharmacological interventions with mature manufacturing bases and consolidated margin pools. The extended-release delivery mode represents the fastest-growing structural category, driven by patient adherence protocols and formulary preference for reduced dosing frequency in long-term care facilities.
FDA, EMA, and national health technology assessment bodies shape market access through divergent evidentiary standards for chronic pain indications, with FDA requiring dual-endpoint trials and European regulators emphasizing quality-adjusted life year thresholds. The FDA's 2022 draft guidance on chronic pain drug development introduced new patient-reported outcome measures that manufacturers must integrate into Phase III protocols. Stakeholders should monitor how evolving pharmacovigilance requirements for antidepressant suicidality labeling affect prescriber confidence in fibromyalgia-specific indications.
Market Dynamics
The FDA's 2022 draft guidance on chronic pain drug development has introduced dual-endpoint trial requirements that manufacturers must now integrate into Phase III protocols, fundamentally altering clinical development timelines and evidentiary standards for fibromyalgia antidepressant approvals.
Growth Catalysts
- Specialty Pain Clinic Expansion:Hospital-affiliated pain centers across the United States are building dedicated fibromyalgia pharmacological intervention programs that prioritize serotonin-norepinephrine reuptake inhibitors as first-line therapy.
- Extended-Release Formulation Preference:Long-term care facilities and Medicare Part D formularies are driving demand for reduced dosing frequency antidepressants that improve adherence in elderly populations with centralized pain states.
- EMA Parallel Scientific Advice:European regulators are streamlining cross-border trial design consultations that accelerate multinational study protocols for fibromyalgia-specific indications.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Duloxetine and milnacipran raw material supply chains cluster heavily in specific Asian manufacturing zones, creating vulnerability to single-source disruptions.
- Black Box Labeling Requirements:FDA-mandated suicidality warnings for all antidepressant classes dampen prescriber confidence in off-label fibromyalgia prescribing despite established efficacy data.
- Generic Substitution Pressure:Patent-expired duloxetine formulations face aggressive pharmacy benefit manager tiering that compresses branded product margins irrespective of formulation differentiation.
Strategic Opportunities
- Underpenetrated European Markets:Germany and France maintain lower diagnosis rates for centralized pain syndromes compared to US benchmarks, creating headroom for clinician education investments.
- Digital Therapeutic Adjacency:FDA breakthrough device designation pathways for cognitive behavioral therapy apps enable combination product strategies that pair pharmacological intervention with behavioral protocols.
- Japan's Aging Demographic:METI-supported chronic pain management initiatives in Japanese prefectures are expanding reimbursement for novel antidepressant mechanisms beyond traditional tricyclic compounds.
Industry Challenges
- Patient-Reported Outcome Validation:Validating fibromyalgia-specific PRO instruments that satisfy FDA dual-endpoint requirements demands extended psychometric testing timelines that compress competitive windows.
- Integrated Care Coordination:Aligning pharmacological protocols with physical therapy and sleep medicine workflows requires cross-specialty protocol development that strains traditional sales force structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibromyalgia Antidepressant Market |
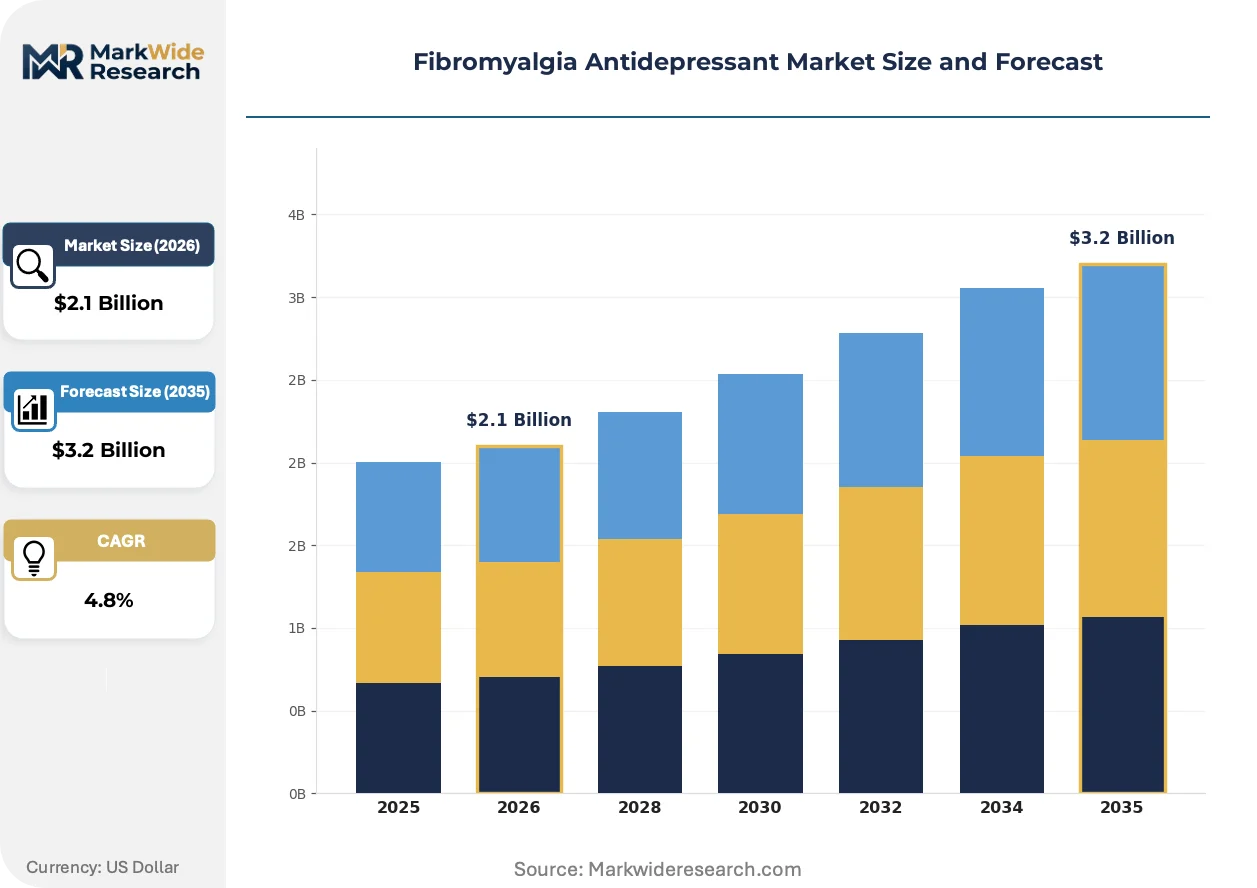
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Duloxetine, Milnacipran, Amitriptyline, Venlafaxine End User: Clinics, Private Practices, Long-Term Care Facilities, Home Care Treatment Approach: Complementary Therapy, Pharmacological Intervention, Cognitive Behavioral Therapy, Alternative Medicine Delivery Mode: Oral, Injectable, Transdermal Patch, Extended Release |
| Companies Covered | Pfizer, Eli Lilly and Company, AbbVie, Teva Pharmaceutical Industries, GlaxoSmithKline, TONIX Pharmaceuticals, Aptinyx, Sanofi, Johnson & Johnson Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibromyalgia Antidepressant Market Trends and Innovations
Extended-release delivery technologies and biomarker-driven patient stratification are actively fragmenting traditional antidepressant positioning in fibromyalgia care, creating distinct performance tiers that separate premium formulations from commodity generics.
Multilayer matrix tablet technology for duloxetine is bifurcating the chronic pain market into adherence-optimized and cost-optimized segments. Rheumatology practices in the United States are adopting once-daily formulations at accelerated rates compared to primary care settings. This technological shift is compressing margins on immediate-release inventory while enabling premium pricing for bioequivalent extended-release alternatives that demonstrate measurable adherence improvements.
The FDA's evolving pharmacovigilance framework for antidepressant suicidality labeling is tightening post-market surveillance requirements across all pain indications. Manufacturers must now integrate real-world evidence collection systems that track suicidal ideation signals in fibromyalgia cohorts separately from depression populations. Neurology-focused prescribers in academic medical centers are responding by demanding more granular risk-benefit documentation that extends beyond standard package inserts.
Specialty pharmacy distribution is consolidating fibromyalgia antidepressant fulfillment around limited networks that manage prior authorization complexity. Payer-imposed step-therapy protocols now require documented tricyclic antidepressant failure before approving serotonin-norepinephrine reuptake inhibitors for centralized pain. This channel restructuring is most pronounced in United States commercial insurance markets where pharmacy benefit managers have narrowed formulary access to contracted specialty distributors.
Fibromyalgia Antidepressant Market Segmentation
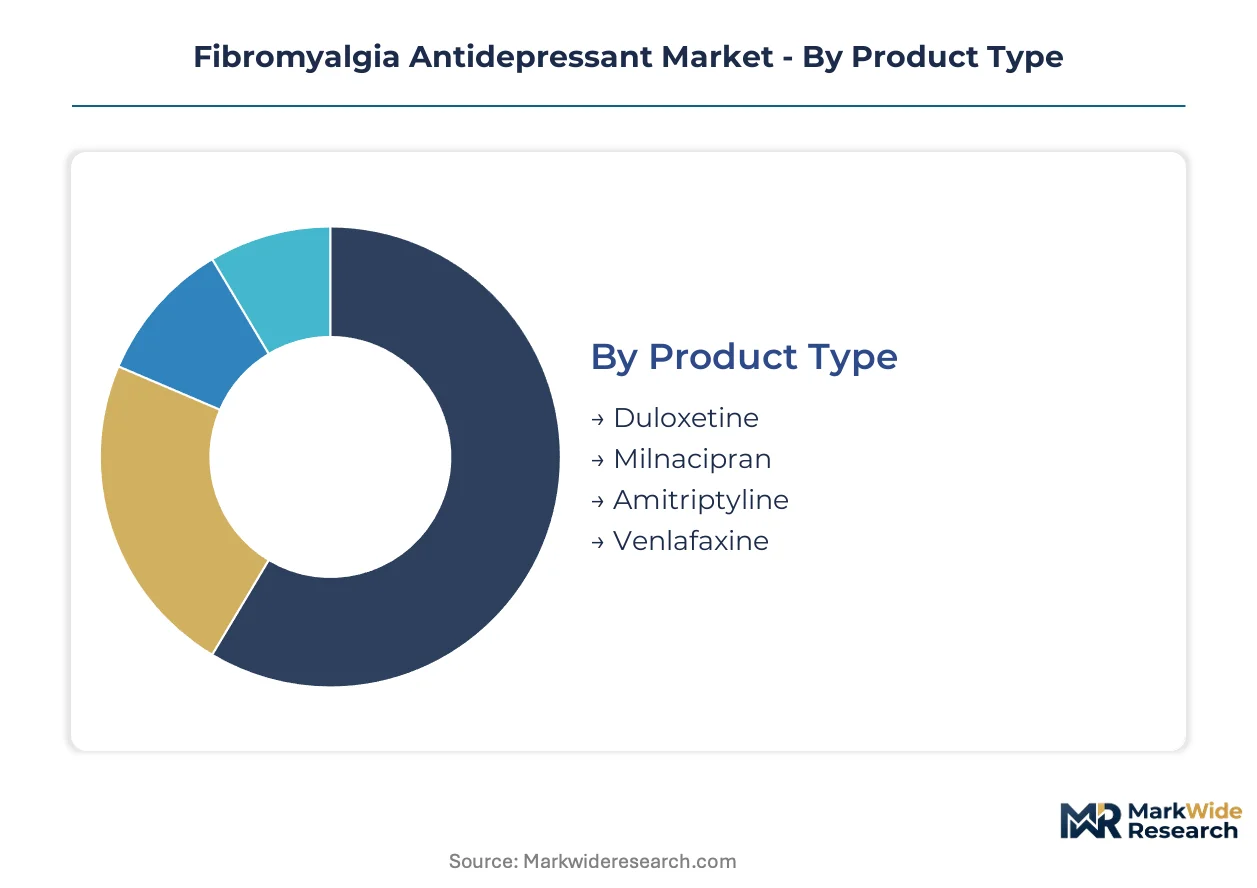
Segmentation in fibromyalgia antidepressant therapy reveals distinct pressure points where generic substitution, formulation innovation, and care setting economics collide. Manufacturers navigate divergent margin pools across product chemistry, patient access channels, and delivery technologies that reshape competitive boundaries.
Product Type:
Generic substitution pressure concentrates most intensely on mature serotonin-norepinephrine reuptake inhibitors where patent cliffs have fully eroded pricing power.
- Duloxetine:This serotonin-norepinephrine reuptake inhibitor achieves bioavailability above 80% with steady-state plasma concentration within 3-7 days. Demand concentrates in United States specialty pain clinics where Medicare Part D formularies prioritize extended-release duloxetine for adherence protocols in elderly centralized pain patients. Branded formulations face aggressive pharmacy benefit manager tiering that compresses margins irrespective of manufacturing sophistication.
- Milnacipran:A dual-acting norepinephrine-serotonin reuptake inhibitor with distinct noradrenergic potency that differentiates it from duloxetine's pharmacological profile. Japan's METI-supported chronic pain initiatives are expanding reimbursement for milnacipran mechanisms beyond traditional tricyclic compounds, creating geographic diversification for manufacturers with PMDA-registered facilities.
- Amitriptyline:This tricyclic antidepressant retains off-label fibromyalgia prescribing through low-cost immediate-release formulations.
- Venlafaxine:An atypical serotonin-norepinephrine reuptake inhibitor with dose-dependent noradrenergic activity used when first-line options fail.
Duloxetine retains volume leadership; extended-release milnacipran formulations hold the steepest expansion curve.
End User:
Cost tier stratification separates high-touch institutional settings from dispersed community-based prescribing where reimbursement complexity escalates.
- Clinics:Hospital-affiliated pain centers across the United States are building dedicated fibromyalgia pharmacological intervention programs. These facilities prioritize serotonin-norepinephrine reuptake inhibitors as first-line therapy and demand granular risk-benefit documentation extending beyond standard package inserts.
- Private Practices:Rheumatology and neurology practices in academic medical centers are adopting once-daily extended-release formulations at accelerated rates compared to primary care settings. FDA-mandated suicidality warnings for all antidepressant classes dampen prescriber confidence in off-label fibromyalgia prescribing despite established efficacy data.
- Long-Term Care Facilities:Medicare Part D formularies drive demand for reduced dosing frequency antidepressants that improve adherence in elderly populations with centralized pain states.
- Home Care:Dispersed patient management relies on caregiver-administered oral formulations with simplified titration protocols.
Specialty clinics command premium positioning; long-term care facilities are expanding most quickly as Medicare reimbursement shifts toward institutional chronic pain management.
Treatment Approach:
Application-based fragmentation separates reimbursable pharmacological protocols from adjacent behavioral and alternative modalities that require distinct evidentiary standards.
- Complementary Therapy:Integrated access programs link pharmacological intervention to physical therapy and sleep medicine workflows. Cross-specialty protocol development strains traditional sales force structures but creates stickier patient relationships for coordinated care providers.
- Pharmacological Intervention:FDA-recognized fibromyalgia diagnostic criteria including widespread pain index scores and symptom severity scales anchor commercial purpose for prescription-grade compounds. The FDA's 2022 draft guidance on chronic pain drug development introduced new patient-reported outcome measures that manufacturers must integrate into Phase III protocols.
- Cognitive Behavioral Therapy:FDA breakthrough device designation pathways for cognitive behavioral therapy apps enable combination product strategies that pair pharmacological intervention with behavioral protocols.
- Alternative Medicine:Non-prescription modalities including acupuncture and herbal preparations compete at the margin of evidence-based fibromyalgia care.
Pharmacological intervention retains volume leadership; cognitive behavioral therapy adjacency holds the steepest expansion curve.
Delivery Mode:
Technology maturity separates established oral platforms from emerging transdermal and injectable formats that require manufacturing infrastructure investments.
- Oral:Immediate-release tablets dominate prescription volume through established manufacturing bases and consolidated margin pools. Multilayer matrix tablet technology is bifurcating the chronic pain market into adherence-optimized and cost-optimized segments.
- Extended Release:Once-daily formulations demonstrate measurable adherence improvements that enable premium pricing for bioequivalent alternatives. This structural category is gaining share fastest as long-term care facilities and Medicare Part D formularies prioritize reduced dosing frequency.
- Injectable:Parenteral delivery addresses bioavailability concerns in patients with gastrointestinal absorption variability.
- Transdermal Patch:Steady-state plasma concentration maintenance without hepatic first-pass metabolism appeals to polypharmacy patients.
Oral delivery retains volume leadership; extended-release formulations hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing for duloxetine and milnacipran concentrates heavily in specific Asian production zones, creating geographic vulnerability that shapes regional market strategies. Demand dispersion follows reimbursement maturity, with developed markets showing higher diagnosis rates and formulary access for serotonin-norepinephrine reuptake inhibitors.
United States
Specialty pain clinics across the United States are building dedicated fibromyalgia pharmacological intervention programs that prioritize serotonin-norepinephrine reuptake inhibitors as first-line therapy. The FDA's 2022 draft guidance on chronic pain drug development introduced dual-endpoint trial requirements that manufacturers must integrate into Phase III protocols. Hospital-affiliated pain centers in academic medical clusters like Boston and the Research Triangle demand granular risk-benefit documentation extending beyond standard package inserts.
Germany
Germany maintains lower diagnosis rates for centralized pain syndromes compared to US benchmarks, creating headroom for clinician education investments in fibromyalgia antidepressant therapy. The EMA's parallel scientific advice streamlines cross-border trial design consultations that accelerate multinational study protocols. Rheumatology practices in Bavaria and North Rhine-Westphalia are adopting extended-release formulations at measured rates compared to American specialty clinic adoption curves.
Japan
METI-supported chronic pain management initiatives in Japanese prefectures are expanding reimbursement for novel antidepressant mechanisms beyond traditional tricyclic compounds. The PMDA maintains distinct evidentiary standards for chronic pain indications that manufacturers navigate through localized clinical development programs. Manufacturing facilities in the Kanto region around Tokyo anchor regional supply chains for extended-release formulation production.
United Kingdom
The NHS England's chronic pain service specifications influence prescribing patterns for fibromyalgia antidepressants through formulary tiering and step-therapy protocols. NICE technology appraisals emphasize quality-adjusted life year thresholds that differ from FDA dual-endpoint requirements. Specialist pain services in London and Manchester are integrating pharmacological intervention with physical therapy workflows under integrated care system mandates.
France
ANSM pharmacovigilance requirements for antidepressant suicidality labeling affect prescriber confidence in fibromyalgia-specific indications through tightened post-market surveillance. France's lower centralized pain diagnosis rates compared to US benchmarks create expansion opportunity for manufacturer-funded clinician education. Hospital-based pain centers in Île-de-France and Auvergne-Rhône-Alpes are piloting combination protocols linking pharmacological intervention to cognitive behavioral therapy adjacency.
Fibromyalgia Antidepressant Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in fibromyalgia antidepressant therapy, with formulation innovation separating premium-positioned manufacturers from commodity generic suppliers. The market structure shows tiered consolidation around extended-release delivery technologies, immediate-release generic substitution pools, and emerging atypical mechanisms. Three archetypes dominate: multinational neurology-focused pharmaceutical companies with established pain-care channels, generic manufacturers with consolidated duloxetine supply chains, and specialty pharmaceutical developers targeting novel mechanisms. Competitive moves concentrate on extended-release formulation differentiation and specialty pharmacy distribution contracting.
Among multinational pharmaceutical developers, Pfizer leverages its neurology infrastructure to sustain branded positioning across major markets, while Eli Lilly and Company anchors its portfolio through specialized pain-care channels that prioritize clinician education. AbbVie differentiates via integrated access programs linking pharmacological intervention to complementary therapy protocols. These three companies exemplify distinct strategic archetypes: infrastructure-led market presence, channel-focused education investment, and care-coordination integration.
| Leading Market Players |
|---|
| Pfizer |
| Eli Lilly and Company |
| AbbVie |
| Teva Pharmaceutical Industries |
| GlaxoSmithKline |
| TONIX Pharmaceuticals |
| Aptinyx |
| Sanofi |
| Johnson & Johnson Services |
| Others |
Pricing and Supply Chain Analysis
FDA dual-endpoint trial requirements for chronic pain indications gate both supply qualification and price differentiation simultaneously, as manufacturers must demonstrate adherence-optimized formulation performance to command premium positioning against commodity generics. Extended-release bioequivalence standards create a certification moat that separates reimbursable tiers from immediate-release substitution pools.
Pricing Analysis
FDA bioequivalence standards dictate the pricing tier structure across fibromyalgia antidepressant therapy, with extended-release formulations achieving premium positioning through measurable adherence documentation while immediate-release duloxetine faces aggressive pharmacy benefit manager tiering. Price differentiation rests on formulation sophistication and Medicare Part D formulary status as primary drivers. Cost compression in immediate-release segments intensifies because of generic substitution pressure from Indian and Chinese manufacturers. Long-term care facilities demonstrate the least price sensitivity due to bundled reimbursement protocols, while independent community pharmacies face the highest sensitivity due to direct patient cost-sharing exposure.
Supply Chain Analysis
Strategic stockpiling of duloxetine and milnacipran active pharmaceutical ingredients dominates inventory strategy among manufacturers seeking to buffer against single-source disruptions in concentrated Asian production zones. API manufacturing concentrates heavily in India, China, and selected Japanese prefectures. Raw material dependencies include naphthol derivatives, chloroacetyl chloride, and specialized enteric coating polymers. Tariff exposure on Chinese-sourced intermediates creates structural vulnerability for extended-release matrix tablet production. Distribution runs through contracted specialty pharmacy networks that manage prior authorization complexity for serotonin-norepinephrine reuptake inhibitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across fibromyalgia antidepressant therapy as extended-release formulation innovation and digital therapeutic adjacency create distinct performance tiers that separate premium-positioned manufacturers from commodity suppliers. The shift toward integrated care coordination generates niche positioning for combination product strategies.
For Market Incumbents: Compound defensive positioning through backward integration into API manufacturing for duloxetine and milnacipran to reduce exposure to single-source Asian supply zones, while simultaneously locking extended-release formulation patents into specialty pharmacy distribution contracts that prior-authorization step-therapy protocols favor. Generic substitution pressure from Teva and Indian manufacturers demands channel control investments in hospital-affiliated pain clinic networks. For New Entrants and Emerging Players: Lead with cognitive behavioral therapy adjacency as the most penetrable white-space target, exploiting FDA breakthrough device designation pathways to pair pharmacological intervention with reimbursable behavioral protocols in German and French markets where centralized pain diagnosis rates lag US benchmarks. Target rheumatology practices in academic medical centers with once-daily formulation messaging that emphasizes adherence metrics over cost comparisons. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty pharmaceutical developers holding extended-release formulation platforms but lacking integrated access programs. Five-to-ten year viability hinges on regulatory continuity for dual-endpoint trial requirements and Medicare Part D reimbursement stability. Watch for FDA pharmacovigilance tightening on antidepressant suicidality labeling as the inflection signal that would compress prescriber confidence and trigger portfolio restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | FDA bioequivalence standards for duloxetine matrix tablets enable premium pricing through adherence documentation. |
| Specialty Pharmacy Distribution Contracting | Prior-authorization management with Express Scripts and CVS Caremark secures formulary tier protection. |
| API Manufacturing Backward Integration | Captive supply of milnacipran intermediates reduces vulnerability to Indian and Chinese export restrictions. |
| Digital Therapeutic Adjacency Investment | FDA breakthrough device designation for CBT apps creates combination product reimbursement pathways. |
| European Clinician Education Programs | German and French centralized pain diagnosis gaps create headroom for manufacturer-funded specialist training. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, formulary directors at major pharmacy benefit managers, hospital procurement managers in academic medical centers, and payer access specialists, then refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov protocols, and Medicare Part D formulary databases. Bottom-up prescription volume modeling triangulated with top-down pharmaceutical expenditure estimates across the analysis window.
Variance decomposition across product type, delivery mode, end-user setting, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segmented volume projections weighted by pricing tier dynamics and reimbursement pathway maturity. Forecast inputs incorporated extended-release formulation adoption curves, specialty pharmacy network expansion rates, and FDA pharmacovigilance evolution timelines.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA chronic pain indication pathways; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Leukotriene Inhibitors Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Vaginitis Therapeutics Market