
 Long-Acting Monoclonal Antibodies Market | 2026-2036
Long-Acting Monoclonal Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Acting Monoclonal Antibodies Market Foresight
Hospital and specialty pharmacy procurement channels for long-acting monoclonal antibodies is fragmenting as payers, group purchasing organizations, and integrated delivery networks each push divergent formulary and rebate terms. AbbVie anchors its position through captive manufacturing of high-yield Chinese hamster ovary cell lines. Eli Lilly and Company differentiates via subcutaneous delivery platforms that reduce infusion center dependency. Johnson & Johnson competes through oncology portfolio breadth and established hospital contracts.
Long-acting monoclonal antibodies are engineered immunoglobulins, predominantly IgG isotypes, with modified Fc regions or attached polyethylene glycol moieties that extend serum half-life from weeks to months, enabling less frequent dosing in chronic disease management. The therapy area dimension shows oncology commanding current revenue pools while autoimmune disorders represent the fastest-expanding indication as IL-23 and IL-17 inhibitors displace conventional systemic therapies. Delivery mode segmentation reveals subcutaneous formulations capturing preference for home healthcare administration, though intravenous routes sustain margin concentration in hospital settings where higher reimbursement rates persist.
FDA's Biosimilar User Fee Act framework and EMA's biosimilar approval pathways compress originator exclusivity, accelerating generic competition and pressuring pricing architecture. The European Union's F-Gas Regulation and REACH chemical standards constrain solvent and reagent choices in mammalian cell manufacturing, elevating compliance costs for European production facilities. Stakeholders must monitor evolving pharmacovigilance requirements for extended half-life biologics and assess manufacturing location strategies against divergent regulatory inspection regimes.
Market Dynamics
FDA and EMA biosimilar pathways are compressing originator exclusivity timelines while hospital procurement intensifies around extended dosing intervals. These dual pressures are restructuring competitive positioning across oncology and autoimmune portfolios.
Growth Catalysts
- Extended Half-Life Engineering:Fc region modification and PEGylation technologies enable quarterly dosing schedules that reduce infusion center burden. Rheumatology and dermatology practices are converting patients from conventional systemic therapies.
- Infusion Center Network Expansion:United States, Germany, and Japan are deploying specialized biologic administration facilities that support intravenous long-acting formulations. Hospital systems are consolidating oncology procurement around these networks.
- REACH and F-Gas Compliance Adaptation:European manufacturing facilities are retrofitting solvent recovery systems to meet chemical standards. This regulatory pressure is accelerating process intensification investments that yield higher cell line productivity.
Market Restraints
- Chinese Hamster Ovary Cell Supply Concentration:High-yield CHO cell lines remain concentrated among three dominant contract development and manufacturing organizations. Any contamination event or export restriction disrupts entire originator pipelines.
- Biosimilar Price Compression:FDA's Biosimilar User Fee Act framework accelerates generic entry within 12-16 months of patent cliff. Originators face immediate reimbursement pressure without formulation differentiation.
- Cold Chain Infrastructure Gaps:Sub-Saharan African and Southeast Asian markets lack validated 2-8°C distribution networks for subcutaneous formulations. Temperature excursion rates exceed acceptable pharmacovigilance thresholds.
Strategic Opportunities
- Home Healthcare Administration:Subcutaneous auto-injector platforms bypass infusion center dependency entirely. Japan's aging population and Germany's rural healthcare gaps create immediate addressable demand.
- IL-23 and IL-17 Inhibitor Expansion:Psoriatic arthritis and hidradenitis suppurativa represent underpenetrated autoimmune indications. Clinical trial pipelines are redirecting from saturated TNF-alpha blockade.
- Process Analytical Technology Integration:Real-time quality monitoring converges with continuous bioprocessing to reduce batch failure rates. FDA's Quality by Design framework incentivizes these capital deployments.
Industry Challenges
- Pharmacovigilance Signal Detection:Extended half-life complicates adverse event attribution windows. Regulators demand longer post-marketing surveillance periods that strain safety database infrastructure.
- Multi-Product Facility Contamination Risk:Campaign switching between oncology and autoimmune biologics requires extensive cleaning validation. FDA inspection findings around cross-contamination are intensifying.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Acting Monoclonal Antibodies Market |
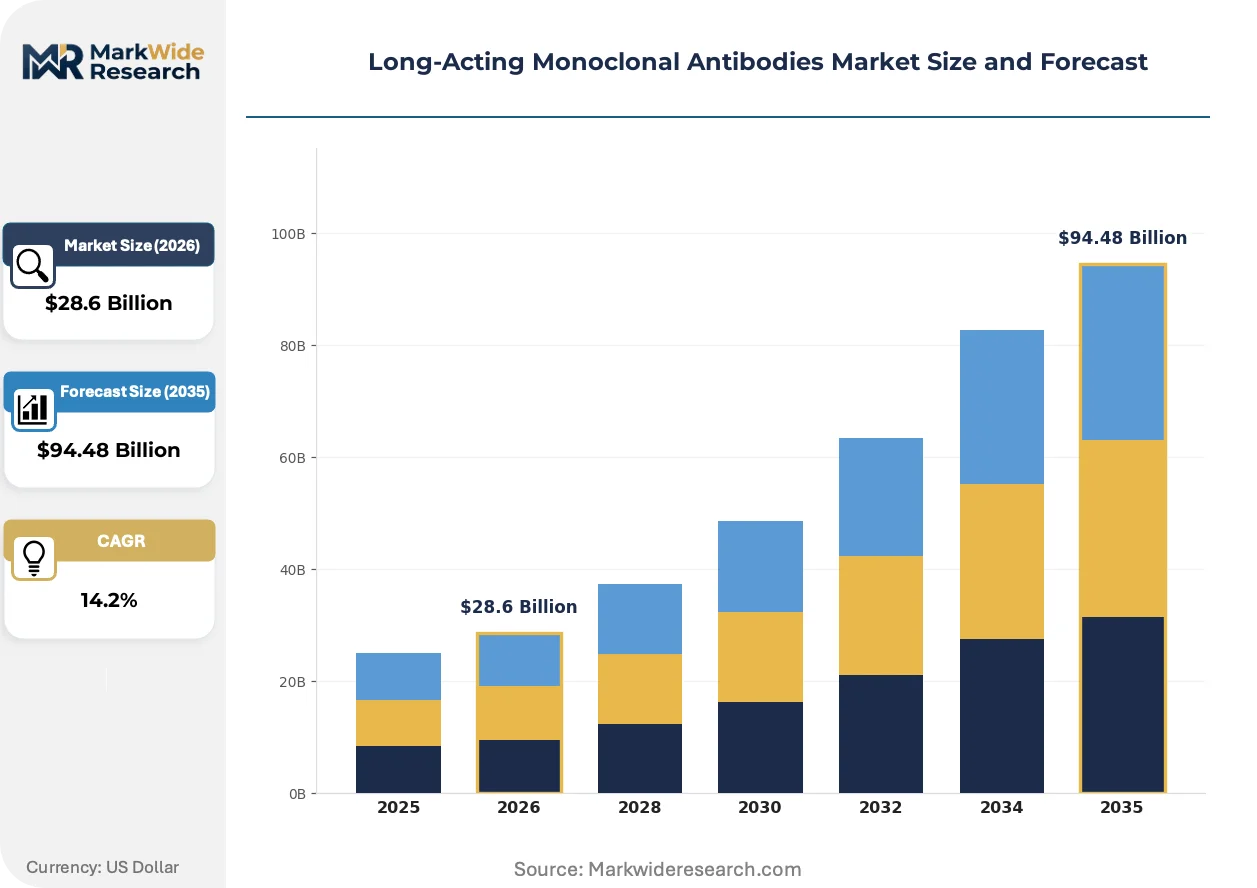
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IgG, IgA, IgM, IgE Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Cardiovascular Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Oral End User: Hospitals, Clinics, Home Healthcare, Research Laboratories |
| Companies Covered | F. Hoffmann-La Roche, Johnson & Johnson, AbbVie, Amgen, Eli Lilly and Company, AstraZeneca, Merck & Co., Novartis, Bristol Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Acting Monoclonal Antibodies Market Shifts & Advancements
Bioprocessing virtualization and delivery platform innovation are compressing traditional manufacturing and administration paradigms simultaneously. Three distinct vectors are restructuring how long-acting antibodies reach patients.
Continuous bioprocessing with integrated single-use technologies is virtualizing legacy stainless-steel batch operations. Contract manufacturers in Singapore and Switzerland are adopting perfusion cell culture with online analytics. This virtualization is collapsing facility footprints while maintaining comparable titers to conventional fed-batch systems.
EMA's F-Gas Regulation and REACH chemical restrictions are constraining solvent selection for European mammalian cell production. Manufacturers are substituting traditional protein A chromatography resins with synthetic alternatives to reduce fluorinated compound dependency. German and Irish production facilities are absorbing compliance costs through process intensification rather than geographic relocation.
Integrated delivery networks are consolidating oncology biologic purchasing around outcome guarantees rather than per-dose reimbursement. United States hospital systems are negotiating risk-sharing arrangements that tie formulary placement to progression-free survival metrics. This behavioral shift concentrates procurement authority within pharmacy and therapeutics committees that span multiple hospital sites.
Long-Acting Monoclonal Antibodies Market Segmentation
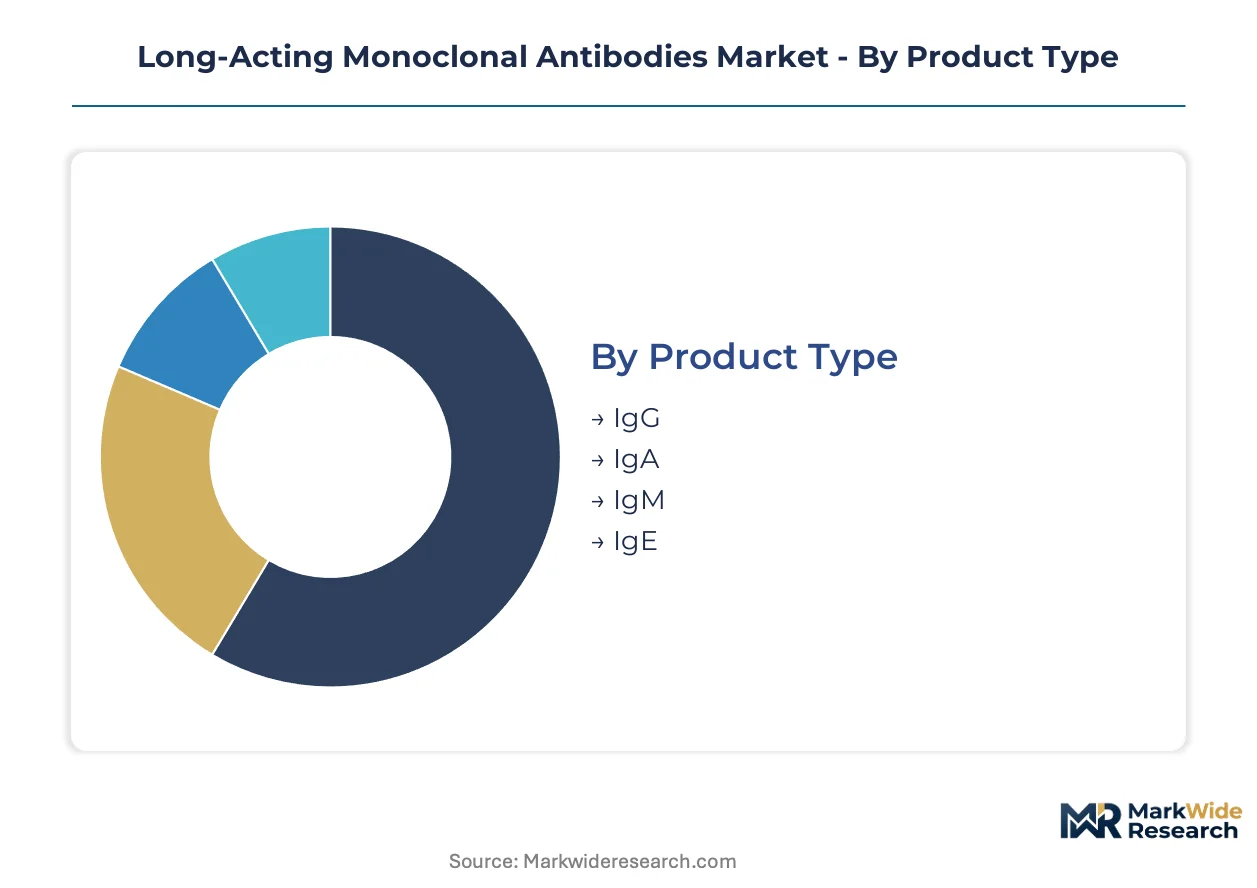
Segmentation in long-acting monoclonal antibodies reveals how engineering choices, administration routes, and care settings fragment procurement patterns. Manufacturers must align formulation development with specific channel economics and reimbursement structures.
Product Type:
After-sales service intensity varies sharply across immunoglobulin isotypes, with Fc engineering complexity driving support requirements for shelf-life validation and cold chain monitoring.
- IgG:Predominant isotype for therapeutic monoclonal antibodies, engineered with modified Fc regions to extend serum half-life through neonatal Fc receptor recycling. Demand concentrates in United States hospital systems where quarterly dosing reduces infusion center burden. FcRn engineering patents differentiate originator portfolios.
- IgA:Mucosal-targeting isotype with dimeric structure suited for respiratory and gastrointestinal indications. Manufacturing yields remain lower than IgG, constraining supply scale. German and Japanese research laboratories are the primary procurement channel for investigational programs.
- IgM:Pentameric structure enables high-avidity binding for complement activation. Pentamer assembly complexity elevates batch failure rates.
- IgE:Specialized isotype for allergic disease modulation and parasite targeting. Limited approved indications restrict commercial infrastructure investment.
By volume, IgG leads. By growth pace, IgA is ahead.
Therapy Area:
Cost tier stratification separates oncology biologics from autoimmune therapies, with reimbursement premiums and clinical trial investment creating divergent margin profiles.
- Oncology:Checkpoint inhibitors and antibody-drug conjugates command highest per-dose pricing, supported by progression-free survival endpoints in FDA and EMA approvals. United States integrated delivery networks consolidate procurement around risk-sharing contracts. Biosimilar entry is compressing originator exclusivity windows.
- Autoimmune Disorders:IL-23 and IL-17 inhibitors are displacing TNF-alpha blockade in psoriasis and psoriatic arthritis. Rheumatology practices in Germany and Japan are converting patients to quarterly dosing regimens. Payer preference for extended intervals accelerates uptake.
- Infectious Diseases:Long-acting HIV prevention antibodies require population-scale deployment models. PEPFAR and Global Fund procurement frameworks dominate volume.
- Cardiovascular:PCSK9 inhibitors demonstrate LDL reduction durability. Cardiology clinic adoption lags specialty pharmacy channels.
By revenue concentration, Oncology dominates. By expansion trajectory, Autoimmune Disorders climbs the fastest.
Delivery Mode:
Customer type segmentation bifurcates between institutional buyers seeking margin concentration and patients prioritizing administration convenience.
- Subcutaneous:Auto-injector and pre-filled syringe formulations enable home healthcare administration, bypassing infusion center dependency. Japan's aging rural population and Germany's distributed healthcare geography create immediate addressable demand. PEGylation and hyaluronidase co-formulation reduce injection volume burden.
- Intravenous:Sustains highest reimbursement rates in United States hospital outpatient departments. Oncology biologics retain IV preference for dose flexibility and therapeutic drug monitoring. Infusion center network density in Germany and Japan supports continued channel concentration.
- Intramuscular:Depot formulations for infectious disease prophylaxis require specific anatomical administration training. Public health program procurement dominates volume.
- Oral:Encapsulated antibody approaches remain investigational, with gastrointestinal degradation limiting bioavailability. Research laboratory procurement for pharmacokinetic studies.
By installed base, Intravenous leads. By patient preference shift, Subcutaneous gains share fastest.
End User:
Supply concentration patterns align with end user scale, with multi-site health systems extracting procurement advantages unavailable to fragmented clinic networks.
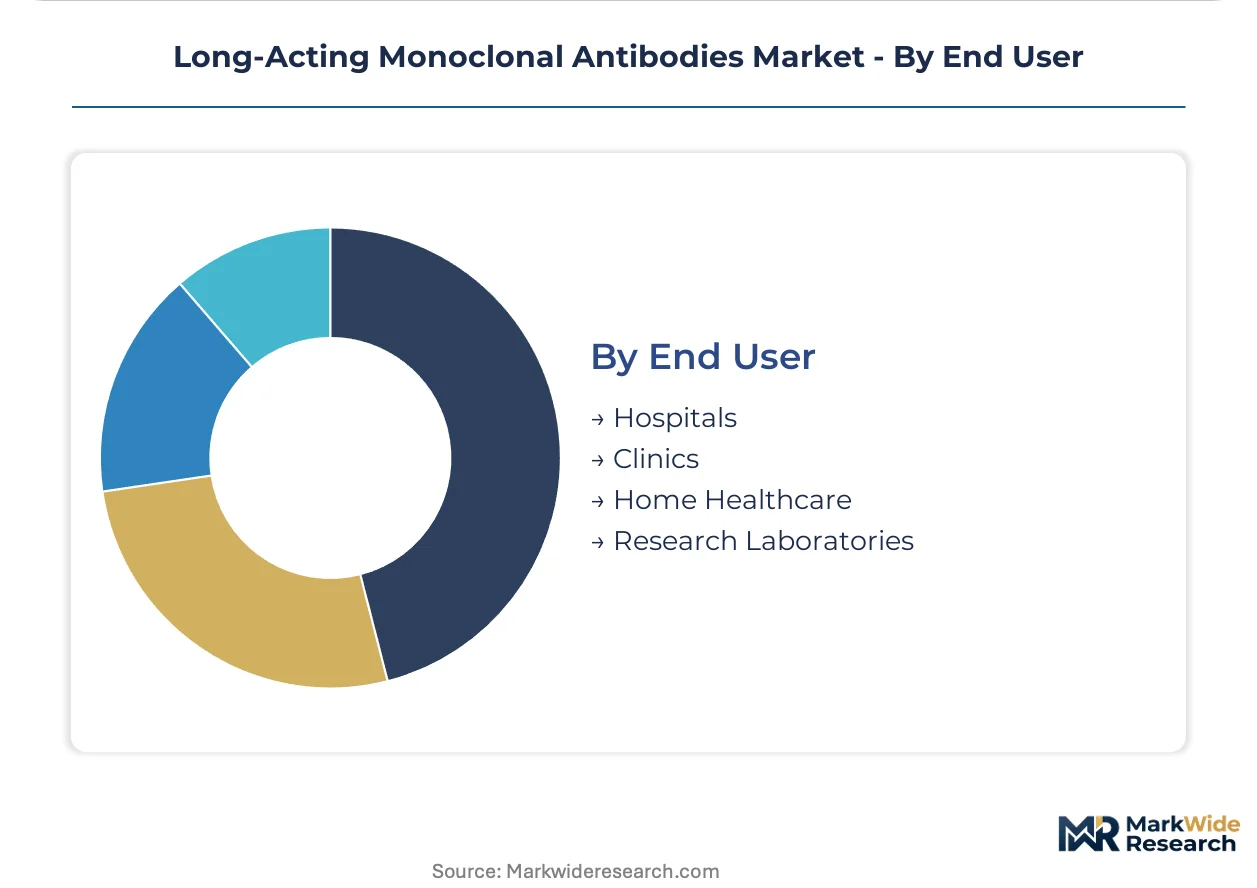
- Hospitals:Integrated delivery networks and academic medical centers consolidate oncology biologic purchasing through pharmacy and therapeutics committees. United States 340B program participation creates pricing tier complexity. Biosimilar formulary placement decisions concentrate authority within multi-hospital systems.
- Home Healthcare:Subcutaneous formulation availability expands addressable market to patients beyond infusion center catchment areas. Germany's rural healthcare gaps and Japan's aging demographics drive channel investment. Reimbursement parity with institutional settings remains variable.
- Clinics:Independent rheumatology and dermatology practices convert from conventional systemic therapies. Group purchasing organization membership determines formulary access.
- Research Laboratories:Investigational antibody procurement for early-phase clinical trials. Contract research organization relationships mediate vendor selection.
By procurement volume, Hospitals lead. By channel expansion rate, Home Healthcare shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized infusion center networks and cold chain distribution infrastructure anchor geographic demand concentration for long-acting monoclonal antibodies. Hospital procurement consolidation and biosimilar regulatory pathways vary sharply across national healthcare systems.
United States
Oncology biologic procurement concentrates within integrated delivery networks negotiating risk-sharing contracts tied to progression-free survival metrics. FDA's Biosimilar User Fee Act framework accelerates generic entry timelines, compressing originator exclusivity windows. The 340B program creates pricing tier complexity across hospital outpatient departments in Texas, California, and New York Metro clusters.
Germany
Rheumatology practices convert patients from TNF-alpha blockade to IL-23 and IL-17 inhibitors with quarterly dosing schedules. EMA's F-Gas Regulation and REACH chemical standards constrain solvent selection in mammalian cell production, elevating compliance costs for Bavarian and North Rhine-Westphalia manufacturing facilities. Berlin-Brandenburg academic medical centers anchor oncology biologic procurement through pharmacy and therapeutics committees.
Japan
Aging demographics and rural healthcare gaps drive subcutaneous auto-injector preference for home healthcare administration. PMDA's pharmacovigilance requirements demand extended post-marketing surveillance for extended half-life biologics. Kanto region infusion center density supports intravenous oncology formulations, while Osaka-Kansai clusters concentrate autoimmune therapy conversion.
Switzerland
Contract manufacturing organizations adopt continuous bioprocessing with single-use technologies to virtualize legacy stainless-steel operations. Swissmedic inspection regimes and proximity to EMA headquarters attract process intensification investment. Basel and Zurich production facilities absorb REACH compliance costs through higher cell line productivity rather than geographic relocation.
Singapore
Perfusion cell culture with online analytics collapses facility footprints while maintaining comparable titers to conventional fed-batch systems. Strategic location between Asian demand centers and European regulatory frameworks attracts multi-product biologics manufacturing. Jurong Island biologics clusters serve as regional distribution hubs for Southeast Asian markets lacking validated cold chain infrastructure.
Long-Acting Monoclonal Antibodies Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified pharmaceutical conglomerates with captive manufacturing infrastructure, biotech specialists focused on Fc engineering platforms, and emerging biosimilar developers exploiting abbreviated regulatory pathways. Competitive positioning hinges on formulation differentiation, manufacturing yield optimization, and infusion center network access. M&A activity targets cell line engineering capabilities and subcutaneous delivery platform assets.
Among diversified pharmaceutical conglomerates, F. Hoffmann-La Roche and Johnson & Johnson occupy positions defined by oncology portfolio breadth and established hospital contracting relationships. AbbVie anchors the high-yield manufacturing archetype through captive Chinese hamster ovary cell line production. Eli Lilly and Company exemplifies the delivery innovation vector with subcutaneous platform development reducing infusion center dependency.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Johnson & Johnson |
| AbbVie |
| Amgen |
| Eli Lilly and Company |
| AstraZeneca |
| Merck & Co. |
| Novartis |
| Bristol Myers Squibb |
| Others |
Supply & Pricing Matrix
Frankfurt-to-Singapore air freight corridors carry temperature-controlled biologics at premium rates that concentrate pricing power among manufacturers with captive cold chain networks, while downstream hospital buyers extract volume rebates that stratify originator portfolios across premium and standard tiers.
Pricing Analysis
Three-tier pricing structure across premium originator, biosimilar, and contract manufacturing levels segments the market by Fc engineering complexity and infusion center bundling. Price differentiation hinges on quarterly dosing convenience and neonatal Fc receptor patent exclusivity. Cost compression in the biosimilar tier is intensifying because FDA abbreviated pathways accelerate generic entry timelines. Integrated delivery networks show lowest price sensitivity; independent rheumatology clinics exhibit highest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days strain contract manufacturers as hospital systems consolidate procurement leverage. Production concentrates in Switzerland, Singapore, and Germany where EMA-aligned inspection regimes and continuous bioprocessing investments anchor supply. Raw material dependencies include protein A chromatography resins, Chinese hamster ovary cell lines, and single-use bioreactor bags. Single-source vulnerability around high-yield CHO cell lines threatens pipeline continuity. Distribution runs through hospital specialty pharmacies and infusion center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States integrated delivery networks consolidate oncology biologic procurement across multi-hospital systems, fragmenting formulary authority that originators once negotiated site-by-site.
For Market Incumbents: Insulate manufacturing margins through backward integration into high-yield Chinese hamster ovary cell line production, locking supply continuity against CDMO concentration risk. Defend oncology portfolio positioning by embedding progression-free survival guarantees within risk-sharing contracts that pharmacy and therapeutics committees cannot replicate with biosimilar alternatives.
For New Entrants and Emerging Players: Pursue subcutaneous auto-injector platform partnerships that bypass infusion center dependency in Japan's rural prefectures and Germany's distributed healthcare geography. Home healthcare administration represents the most penetrable channel expansion. Target IL-23 inhibitor development for psoriatic arthritis where TNF-alpha blockade saturation creates switching momentum.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates spinning off legacy mammalian cell manufacturing assets as they pivot toward cell and gene therapy platforms. Long-term viability favors facilities with FDA and EMA dual-inspection history and continuous bioprocessing retrofit completion. Watch for biosimilar approval acceleration as the inflection signal compressing originator exclusivity windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Fc Engineering Patent Expansion | Neonatal Fc receptor recycling extensions defend quarterly dosing intervals against biosimilar erosion. |
| Subcutaneous Delivery Platform Development | Auto-injector partnerships with Eli Lilly reduce hospital outpatient department reimbursement dependency. |
| Continuous Bioprocessing Retrofit | Single-use perfusion systems collapse facility footprints while maintaining EMA F-Gas Regulation compliance. |
| Integrated Delivery Network Risk-Sharing | Progression-free survival guarantees secure formulary placement across United States hospital systems. |
| IL-23 Inhibitor Clinical Trial Advancement | Psoriatic arthritis and hidradenitis suppurativa indications displace saturated TNF-alpha blockade markets. |
Research Methodology
Cross-validation between formulary database audits and hospital procurement contract analysis anchors the qualitative findings in documented purchasing behavior. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov entries, and GPO contract databases. Bottom-up patient flow modeling and top-down revenue triangulation converge across the analysis window.
Calibration against historical biosimilar entry timelines and originator price erosion patterns shapes the projection framework. Segmentation dimensions include immunoglobulin isotype, therapy area, delivery mode, and end-user channel across the modeling period. CAGRs derive from patient population growth, dosing interval conversion rates, and biosimilar penetration assumptions. Forecast inputs incorporate infusion center network expansion trajectories and REACH compliance cost absorption.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy, biologics price inflation, or healthcare utilization would shift the trajectory. Forecasts reflect documented assumptions around regulatory approval timelines and manufacturing yield improvements. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Critical Care Therapeutics Market