
 Global Human Growth Hormone (HGH) Market | 2026-2036
Global Human Growth Hormone (HGH) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Growth Hormone (HGH) Market Foresight
Pediatric endocrinology clinics is reorganizing demand patterns across the HGH value chain as adult hormone replacement protocols gain institutional traction. Novo Nordisk A/S leverages its recombinant protein manufacturing scale to sustain supply continuity across European and Asian markets. Pfizer Inc. anchors its position through long-acting formulation development, while Eli Lilly and Company differentiates via pediatric specialty clinic partnerships.
Human growth hormone comprises a 191-amino acid polypeptide produced via recombinant DNA technology in Escherichia coli or mammalian cell lines, designed to replicate pituitary-derived somatotropin for stimulating linear growth and metabolic regulation. Recombinant HGH commands the dominant share of commercial volume due to its established purity profiles and batch consistency, while biosimilar HGH represents the fastest-expanding category as regulatory pathways in the United States and Europe mature. The therapy area dimension clusters around growth hormone deficiency and Turner syndrome where diagnostic penetration remains highest, though Prader-Willi syndrome applications are gaining specialist attention.
FDA oversight of biologics licensing and EMA's centralized marketing authorization procedures govern market access, with both agencies tightening post-market surveillance for immunogenicity signals. The WHO's prequalification standards and national pricing boards in Germany and Japan further constrain commercial flexibility. Stakeholders must monitor evolving biosimilar interchangeability rulings and pediatric orphan drug exclusivity periods to calibrate portfolio investments.
Market Dynamics
Long-acting HGH formulations are compressing injection frequency from daily to weekly cycles, fundamentally altering patient adherence economics and reordering competitive advantage around sustained-release delivery platforms rather than raw molecule supply.
Growth Catalysts
- EMA's centralized pediatric orphan drug pathways:Accelerated marketing authorization for rare endocrine indications reduces time-to-revenue for novel formulations targeting Turner syndrome and Prader-Willi syndrome.
- Adult hormone replacement protocols:Endocrinology practices in Germany and Japan are expanding diagnostic screening for adult growth hormone deficiency, creating new prescription volume beyond pediatric GHD.
- Recombinant protein manufacturing scale:Multi-thousand-liter bioreactor deployments in Denmark and Singapore are flattening unit cost curves for 191-amino acid polypeptide production.
Market Restraints
- FDA biosimilar interchangeability uncertainty:Absence of explicit substitution guidance at pharmacy level creates formulary access friction and dampens payer willingness to mandate biosimilar-first policies.
- Cold chain distribution concentration:Temperature-controlled logistics for liquid HGH formulations concentrate in three European contract manufacturers, exposing supply continuity to single-node disruption risks.
- Recombinant E. coli expression limitations:Prokaryotic production systems cannot perform mammalian glycosylation patterns required for next-generation fusion proteins, constraining product pipeline diversification.
Strategic Opportunities
- Underpenetrated Brazilian diagnostic infrastructure:Growth hormone deficiency screening rates in São Paulo and Rio de Janeiro pediatric networks lag North American benchmarks by substantial margins.
- Needle-free delivery convergence:Integration of transdermal microneedle arrays with existing HGH formulations could displace conventional syringe-based administration in Japan's aging patient population.
- India's PLI scheme for biologics:Production-linked incentives for recombinant protein manufacturing are attracting contract development investment toward Hyderabad and Bengaluru biotech clusters.
Industry Challenges
- Pharmacovigilance signal detection capacity:Post-market immunogenicity surveillance requires specialized bioanalytical expertise that contract research organizations struggle to staff at EMA-mandated reporting frequencies.
- Legacy vial-to-pen device transition:Pediatric clinics face capital expenditure burdens and nursing retraining costs when migrating from multidose vial protocols to disposable pen injector systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Growth Hormone (HGH) Market |
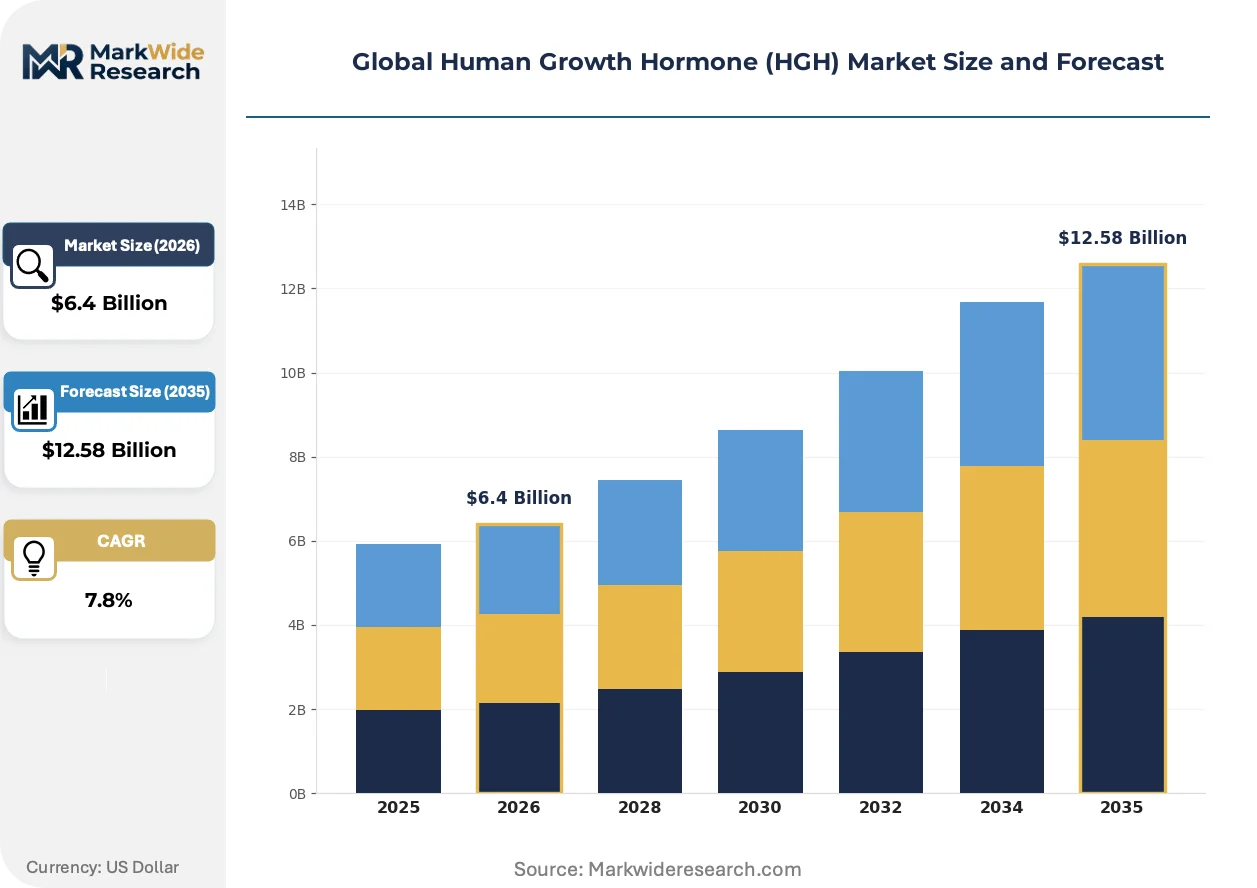
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant HGH, Somatropin, Somatrem, Biosimilar HGH, Peptide HGH Therapy Area: Growth Hormone Deficiency, Turner Syndrome, Chronic Kidney Disease, Prader-Willi Syndrome, Idiopathic Short Stature End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Pediatric Care Centers, Research Institutes Delivery Method: Injectable, Nasal Spray, Oral Administration, Transdermal Patch, Implantable Device |
| Companies Covered | Novo Nordisk A/S, Pfizer Inc., Eli Lilly and Company, Merck KGaA, Ipsen S.A., Ferring Pharmaceuticals, Sandoz International GmbH, Anhui Anke Biotechnology, Genentech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Growth Hormone (HGH) Market Shifts & Advancements
Formulation science and regulatory science are advancing in parallel, with delivery platform innovation outpacing molecular modification while agencies tighten evidentiary standards for immunogenicity and long-term metabolic safety.
PEGylated HGH analogs and albumin-binding fusion technologies are decomposing the historical trade-off between efficacy and convenience. Pediatric endocrinology networks in the United States are piloting weekly regimens at accelerating rates. This compression of dosing frequency is decomposing adherence barriers that previously limited therapy persistence in adolescent populations.
REACH authorization requirements for novel excipients in parenteral formulations are extending preclinical toxicology timelines for European market entry. Manufacturers are responding by front-loading EMA scientific advice consultations and parallel-tracking FDA IND submissions to prevent sequential regulatory delays. Long-acting formulation developers face the steepest compliance cost escalation under these tightened substance evaluation protocols.
Hospital procurement consortia in Germany are consolidating HGH purchasing through tender-based frameworks that unbundle device costs from drug substance pricing. This aggregation of buying power is compressing net realized prices for originator products while creating volume guarantees that favor suppliers with manufacturing redundancy across multiple production sites. The Rhineland and Bavaria hospital alliances are executing the most aggressive contract restructuring.
Global Human Growth Hormone (HGH) Market Segmentation
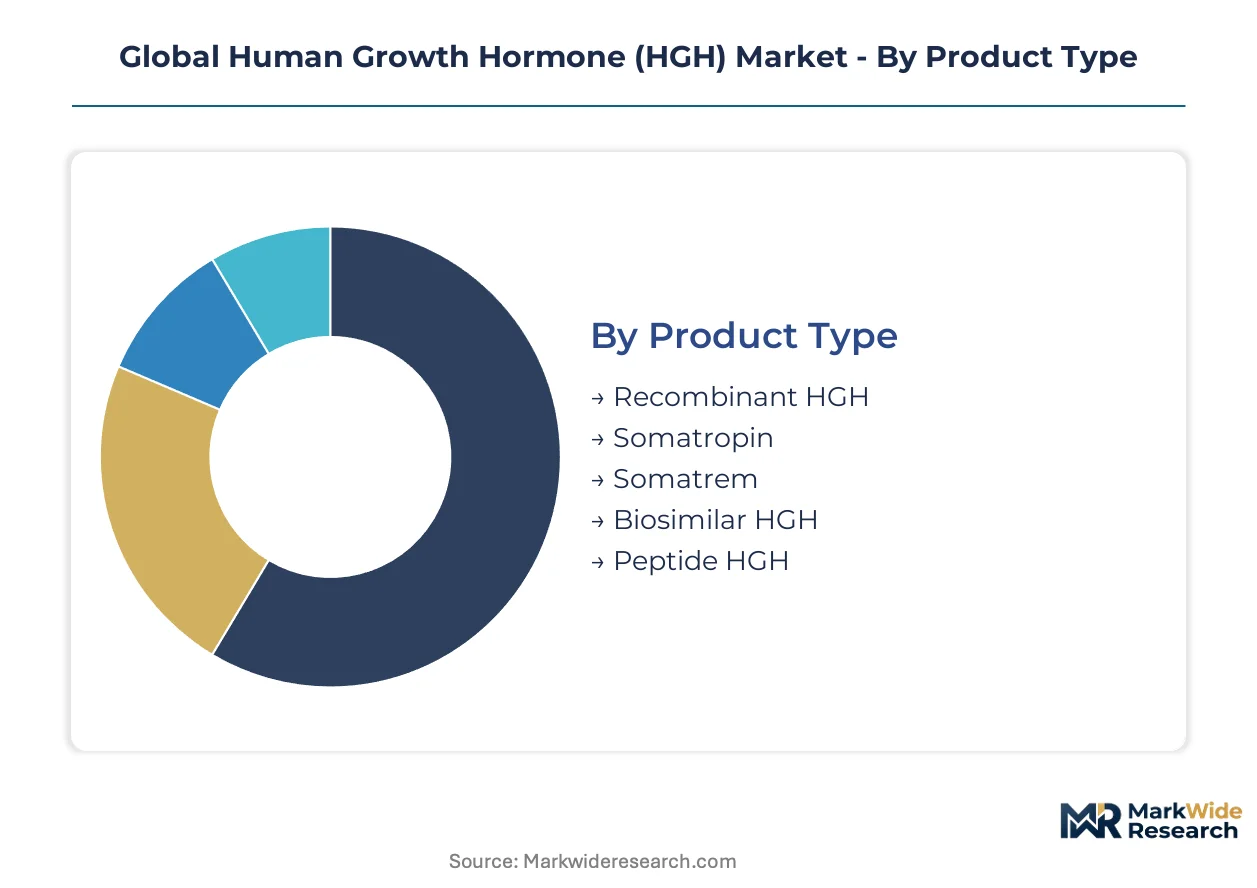
HGH market segmentation reveals divergent commercial architectures across molecular platforms and clinical settings. Product type stratification separates high-volume recombinant supply from emerging biosimilar competition, while therapy area fragmentation concentrates revenue in pediatric endocrinology against expanding adult replacement protocols.
Product Type:
Domestic production gravity anchors recombinant HGH manufacturing in Denmark and Singapore, whereas biosimilar sourcing flows through contract manufacturers in India and South Korea targeting export markets.
- Recombinant HGH:Escherichia coli-derived 191-amino acid polypeptide manufactured via fed-batch fermentation achieves batch-to-batch consistency exceeding 99.5% purity specifications. Demand concentrates in United States pediatric networks where FDA biologics licensing requirements favor established recombinant platforms over novel expression systems.
- Biosimilar HGH:Analytical biosimilarity demonstrations against reference products via mass spectrometry and bioassay comparability protocols enable abbreviated regulatory pathways. Expansion accelerates in Germany and Japan where EMA centralized procedures and PMDA guidance documents have clarified interchangeability evidentiary standards.
- Somatropin:Identical amino acid sequence to endogenous human growth hormone, produced through mammalian cell culture systems.
- Somatrem:Methionyl-modified variant requiring post-translational processing, manufactured primarily for legacy contract obligations.
- Peptide HGH:Synthetic fragment approaches targeting specific receptor domains, constrained by oral bioavailability limitations.
Recombinant HGH commands the established base. The steepest expansion runs through biosimilar HGH.
Therapy Area:
Cost tier stratification separates premium-priced orphan indications from volume-driven idiopathic short stature protocols, with reimbursement intensity varying across national health technology assessment frameworks.
- Growth Hormone Deficiency:Congenital and acquired pituitary dysfunction requiring lifelong replacement therapy, diagnosed via insulin tolerance testing and arginine stimulation protocols. Pediatric endocrinology clinics in the United States and Germany generate prescription density exceeding other developed markets due to newborn screening integration and specialist referral networks.
- Turner Syndrome:Chromosomal disorder affecting approximately 1 in 2,500 female births, with HGH therapy initiated in early childhood to maximize final adult height. Patient identification rates in Japanese tertiary centers approach 90% of estimated prevalence, creating concentrated demand pools.
- Prader-Willi Syndrome:Genetic imprinting disorder with growth failure and metabolic dysregulation, requiring multidisciplinary management.
- Chronic Kidney Disease:Growth retardation in pediatric renal failure populations, with dosing protocols adjusted for glomerular filtration rates.
- Idiopathic Short Stature:Height below third percentile without identifiable pathology, subject to variable reimbursement and ethical prescribing debates.
Growth hormone deficiency anchors revenue stability. Turner syndrome delivers the most reliable volume expansion trajectory.
End User:
Customer type fragmentation concentrates procurement authority in hospital pharmacy committees versus dispersed specialty clinic prescribing, with pediatric care centers occupying intermediate positions on formulary control spectrum.
- Hospitals:Integrated health systems managing complex endocrine cases with inpatient initiation protocols.
- Specialty Clinics:Independent pediatric endocrinology practices in the United States drive off-label adult diagnostic expansion.
- Pediatric Care Centers:Dedicated children's hospital networks in Germany and Japan centralizing rare disease management.
- Diagnostic Laboratories:Stimulation testing facilities supporting referral confirmation.
- Research Institutes:Academic medical centers conducting long-acting formulation clinical trials.
Hospital procurement aggregates volume leverage. Pediatric care centers are gaining the fastest share in outpatient protocol migration.
Delivery Method:
Supply concentration in device manufacturing clusters shapes regional availability, with pen injector assembly concentrated in Switzerland and Ireland while transdermal platform development localizes in Japanese materials science corridors.
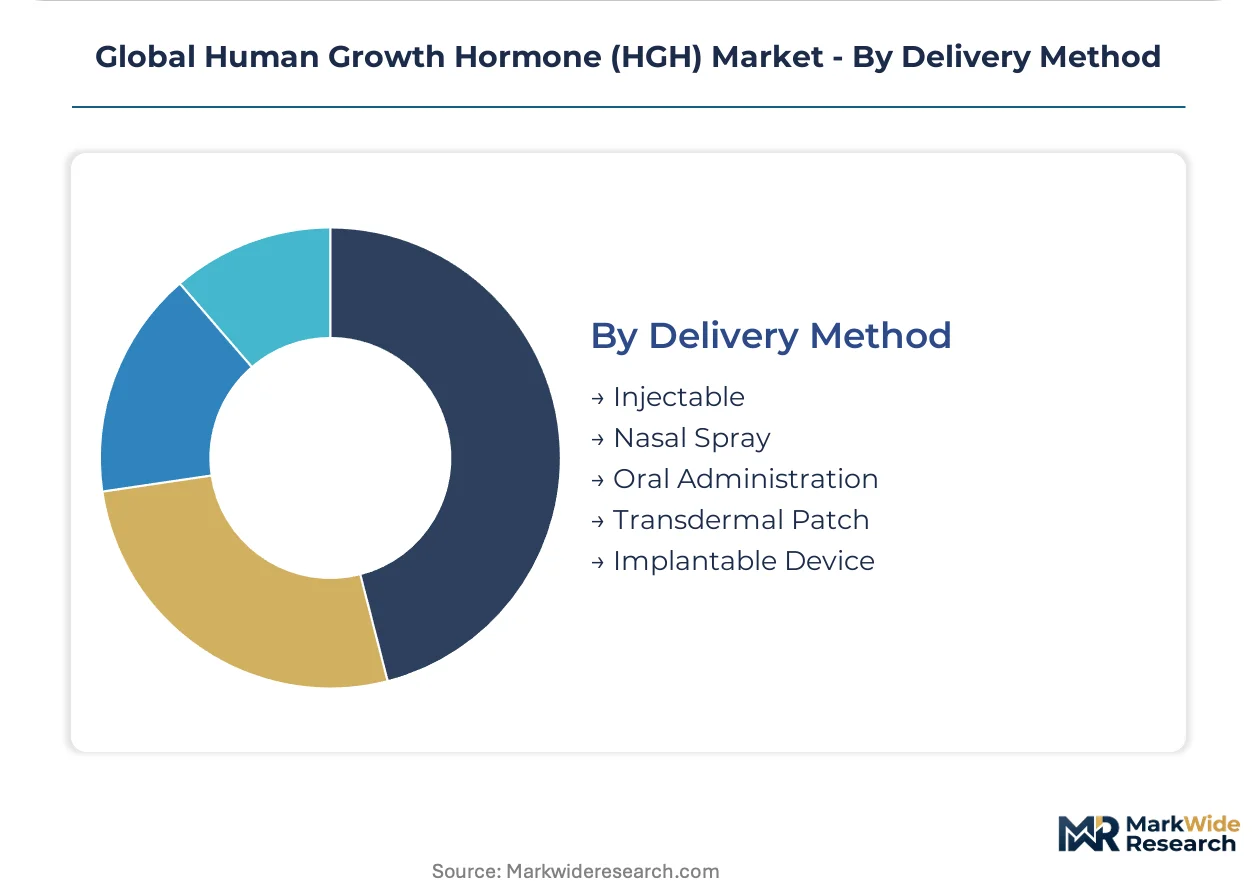
- Injectable:Subcutaneous administration via prefilled pen devices or multidose vials, with needle gauge and injection depth specifications varying by formulation viscosity. Daily injection burden in adolescent populations drives adherence failure rates exceeding 30% in real-world United States registry data.
- Nasal Spray:Mucosal absorption formulations bypassing first-pass metabolism, with bioavailability limitations constraining therapeutic equivalence.
- Oral Administration:Encapsulation technologies protecting against gastric degradation remain preclinical.
- Transdermal Patch:Microneedle array platforms under development at Japanese pharmaceutical-device convergence programs.
- Implantable Device:Osmotic pump depot systems in early feasibility studies.
Injectable formats dominate commercial reality. Transdermal patch platforms are climbing the fastest toward regulatory submission milestones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric endocrinology networks and hospital procurement consortia concentrate purchasing authority across five national markets. Reimbursement frameworks for rare endocrine disorders and cold chain distribution infrastructure determine commercial access intensity in each geography.
United States
FDA biologics licensing requirements favor established recombinant platforms, with pediatric networks in Boston and Philadelphia generating prescription density exceeding other developed markets. The agency's evolving biosimilar interchangeability pathways create formulary access friction. Multi-thousand-liter bioreactor deployments in North Carolina anchor domestic manufacturing scale.
Germany
EMA centralized pediatric orphan drug pathways accelerate marketing authorization for novel formulations targeting Turner syndrome. Hospital procurement consortia in Rhineland and Bavaria execute aggressive tender-based contract restructuring. The country's national pricing board constrains commercial flexibility while creating volume guarantees for suppliers with manufacturing redundancy.
Japan
PMDA guidance documents clarify interchangeability evidentiary standards for biosimilar entry. METI standards govern transdermic platform development in Osaka materials science corridors. Patient identification rates in Tokyo tertiary centers approach prevalence benchmarks, creating concentrated demand pools for long-acting formulations.
India
CDSCO regulatory pathways mature for recombinant protein manufacturing under production-linked incentive schemes. Hyderabad and Bengaluru biotech clusters attract contract development investment toward multi-thousand-liter capacity. Diagnostic infrastructure gaps in tier-two pediatric networks lag metropolitan screening rates.
Brazil
ANVISA oversight governs biologics market entry for imported recombinant formulations. Growth hormone deficiency screening rates in São Paulo pediatric networks lag North American benchmarks. Temperature-controlled logistics concentration in São Paulo state exposes supply continuity to single-node disruption risks.
Global Human Growth Hormone (HGH) Market Competitive Landscape
Player mix skews toward integrated biopharmaceutical conglomerates with recombinant protein manufacturing scale. Three to five originator firms command premium positioning through long-acting formulation portfolios, while biosimilar specialists compete on abbreviated regulatory pathways and contract manufacturing economics. Strategic moves concentrate on sustained-release delivery platform licensing and pediatric specialty clinic partnership networks.
Among European-origin integrated biopharmaceuticals, Novo Nordisk A/S and Merck KGaA exemplify archetypes anchored in multi-thousand-liter fermentation capacity. Pfizer Inc. represents the scale-driven transatlantic conglomerate model. Eli Lilly and Company occupies a position within the pediatric specialty partnership tier. These three firms collectively illustrate competitive positioning around formulation innovation rather than raw molecule supply.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Pfizer Inc. |
| Eli Lilly and Company |
| Merck KGaA |
| Ipsen S.A. |
| Ferring Pharmaceuticals |
| Sandoz International GmbH |
| Anhui Anke Biotechnology |
| Genentech Inc. |
| Others |
Supply & Pricing Matrix
Multi-thousand-liter bioreactor deployments in Denmark and Singapore compress unit production costs for 191-amino acid polypeptide manufacturing, concentrating supply-side leverage among integrated fermentation operators while establishing price floors that contract manufacturers in India and South Korea struggle to undercut without sacrificing batch consistency standards.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate hospital procurement frameworks in Germany and Japan, where national pricing boards reference fermentation input costs and cold chain logistics tariffs in quarterly adjustments. Three-tier pricing structure across originator long-acting formulations, standard recombinant products, and biosimilar alternatives separates premium positioning anchored in FDA biologics licensing from economy tiers driven by CDSCO-abbreviated pathways. Cost compression in the biosimilar tier is intensifying because EMA interchangeability rulings remain pending, forcing price competition on clinical equivalence rather than substitution guarantees. Pediatric care centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while specialty clinics managing adult hormone replacement protocols demonstrate lowest sensitivity to device-premium bundling.
Supply Chain Analysis
Strategic stockpiling of master cell banks and working seed lots prevails over just-in-time raw material procurement in this industry, reflecting the 18-24 month lead time for EMA-compliant fermentation facility qualification. Manufacturing gravity centers on Denmark, Singapore, and North Carolina for originator supply, with contract production expanding through Hyderabad and Bengaluru under India's PLI scheme. Production draws from Chinese-sourced recombinant protein expression vectors, German-engineered bioreactor control systems, and Swiss-manufactured pen injector components. Single-source vulnerability concentrates in temperature-controlled fill-finish operations at three European contract manufacturers. Distribution runs through hospital pharmacy consortia in Germany, specialty clinic networks in the United States, and regional cold chain hubs in São Paulo serving Brazilian pediatric networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-maintenance subscriptions and patient adherence monitoring services are expanding faster than drug substance revenue in this market, creating attach-rate opportunities that recast competitive advantage around ongoing patient relationships rather than one-time formulation sales.
For Market Incumbents: Secure manufacturing redundancy across multiple fermentation sites to satisfy German hospital consortia tender requirements for volume guarantees. Lock in long-acting formulation patent estates through pediatric orphan drug exclusivity extensions, defending against biosimilar entrants exploiting FDA interchangeability uncertainty. Vertical integration into pen injector device production reduces exposure to Swiss and Irish assembly concentration risks. For New Entrants and Emerging Players: Differentiate on needle-free delivery platform development targeting Japan's aging adult hormone replacement population, where transdermal microneedle convergence commands reimbursement premium potential. White-space concentration exists in Brazilian diagnostic infrastructure expansion and Indian tier-two pediatric network screening programs. Partner with established cold chain logistics operators rather than building proprietary distribution capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated biopharmaceuticals with long-acting formulation portfolios and captive device manufacturing capabilities. Five-to-ten year viability favors targets with EMA scientific advice track records and multi-indication pediatric orphan drug pipelines. Watch FDA biosimilar interchangeability guidance publication as the critical inflection signal for portfolio reallocation toward or away from biosimilar specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Weekly dosing regimens from Pfizer and Novo Nordisk compress adherence barriers in adolescent populations. |
| EMA Scientific Advice Front-Loading | Parallel-track FDA IND submissions prevent sequential regulatory delays for novel excipient authorization. |
| Pediatric Specialty Clinic Partnerships | Eli Lilly's network investments in Boston and Philadelphia generate prescription density exceeding independent practices. |
| Biosimilar Interchangeability Investment | Sandoz and Anhui Anke navigate FDA evidentiary uncertainty to capture formulary access upon substitution clarity. |
| Transdermal Platform Convergence | Japanese materials science corridors in Osaka advance microneedle array integration with existing HGH formulations. |
Research Methodology
Operator-level perspectives from pediatric endocrinologists, hospital pharmacy directors, regulatory affairs leads at biopharmaceutical firms, and cold chain logistics operators anchored the qualitative base for this study. Primary interview insights combined with secondary validation from FDA biologics licensing records, EMA centralized marketing authorization procedures, ClinicalTrials.gov long-acting formulation trials, and German hospital procurement tender databases. Bottom-up prescription volume modeling and top-down reimbursement framework analysis were triangulated against manufacturing capacity disclosures and national pricing board rulings.
Sensitivity analysis around biosimilar interchangeability timing, pediatric orphan drug exclusivity periods, and adult diagnostic screening penetration rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular platform, therapy area indication, end-user procurement authority, and delivery method format, with regional regulatory clusters capturing FDA, EMA, PMDA, CDSCO, and ANVISA pathway differentiation. CAGRs were derived from epidemiological prevalence projections, treatment initiation rate assumptions, and pricing trajectory scenarios informed by hospital consortia contract restructuring patterns.
Material uncertainties — regulatory pathway acceleration or delay, immunogenicity signal emergence requiring label restriction, and cold chain single-node disruption events — sit outside the modeled envelope. Forecasts reflect stated assumptions regarding reimbursement stability and manufacturing scale-up execution. Revision becomes warranted when FDA biosimilar interchangeability guidance crosses publication thresholds or when EMA pharmacovigilance mandate frequencies exceed contract research organization staffing capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Testosterone Nasal Gels Market