
 Hospital Bedsheet and Pillow Cover Market | 2026-2036
Hospital Bedsheet and Pillow Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Bedsheet and Pillow Cover Market Intelligence
India's expanding textile manufacturing corridor is reshaping supply dynamics for hospital linens. Emes Textiles Pvt. Ltd. leverages its vertically integrated spinning-to-finishing infrastructure to serve institutional buyers across South Asia. Raenco Mills Pvt. Ltd. anchors its position through specialized healthcare-grade cotton processing that meets stringent infection control protocols. Angelica competes on route density, operating extensive linen service networks that reduce turnaround times for acute care facilities.
Hospital bedsheets and pillow covers constitute engineered textile products designed for high-temperature laundering, typically woven from cotton or cotton-polyester blends with thread counts optimized for durability and patient comfort. These items function as critical infection control barriers in clinical environments, requiring compliance with flammability standards and fluid resistance specifications. Flat sheets and fitted sheets together occupy the dominant product category, though pillowcases are gaining share as facilities prioritize head-contact surface hygiene. Cotton maintains its leading material position among premium purchasers, while polyester blends capture cost-sensitive volume through faster drying cycles and extended replacement intervals.
The EPA regulates antimicrobial claims on treated textiles, compelling manufacturers to substantiate efficacy data before marketing infection-resistant linens. FDA oversight of hospital-grade products intersects with OSHA bloodborne pathogen standards to shape procurement specifications for acute care settings. Stakeholders must monitor evolving state-level healthcare textile mandates and assess whether recycled fiber content requirements will alter raw material sourcing strategies.
Market Dynamics
Hospital consolidation across the United States is compressing procurement cycles and forcing linen suppliers to reconfigure fulfillment networks around centralized distribution hubs serving multi-facility health systems.
Growth Catalysts
- EPA Antimicrobial Substantiation Requirements:Tighter efficacy validation protocols are accelerating hospital upgrades from untreated cotton to engineered infection-control textiles.
- Surgical Volume Concentration in Tertiary Centers:Complex procedure migration toward academic medical centers is intensifying linen throughput and replacement frequency.
- India's Textile Manufacturing Corridor:Vertically integrated spinning-to-garment clusters in Tamil Nadu and Gujarat are shortening lead times for institutional buyers.
Market Restraints
- Raw Cotton Price Volatility:Weather-driven supply disruptions in Maharashtra and Texas are compressing margins for cotton-dominant product lines.
- Single-Source Concentration in Bleaching Chemicals:European chlor-alkali production curbs under REACH energy protocols are creating input bottlenecks for healthcare-grade finishing.
- Flammability Standard Incompatibility:Divergent NFPA and state-level fire safety codes are fragmenting product SKUs and inflating compliance costs.
Strategic Opportunities
- Rural Hospital Network Expansion:Federally qualified health centers in the US Southeast are modernizing linen infrastructure under CMS quality incentive programs.
- RFID-Enabled Linen Tracking Convergence:Integration of textile-embedded sensors with hospital asset management platforms is creating subscription revenue streams.
- EU Green Deal Textile Mandates:Recycled fiber content thresholds for institutional procurement are opening circular supply partnerships.
Industry Challenges
- Industrial Laundering Technician Shortage:Specialized operators certified in thermal disinfection protocols are scarce in secondary US markets.
- FDA 510(k) Timeline Compression:Antimicrobial claim submissions for novel fabric treatments face extended review queues.
- Legacy ERP Integration Friction:Hospital materials management systems require costly middleware to sync with supplier IoT inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Bedsheet and Pillow Cover Market |
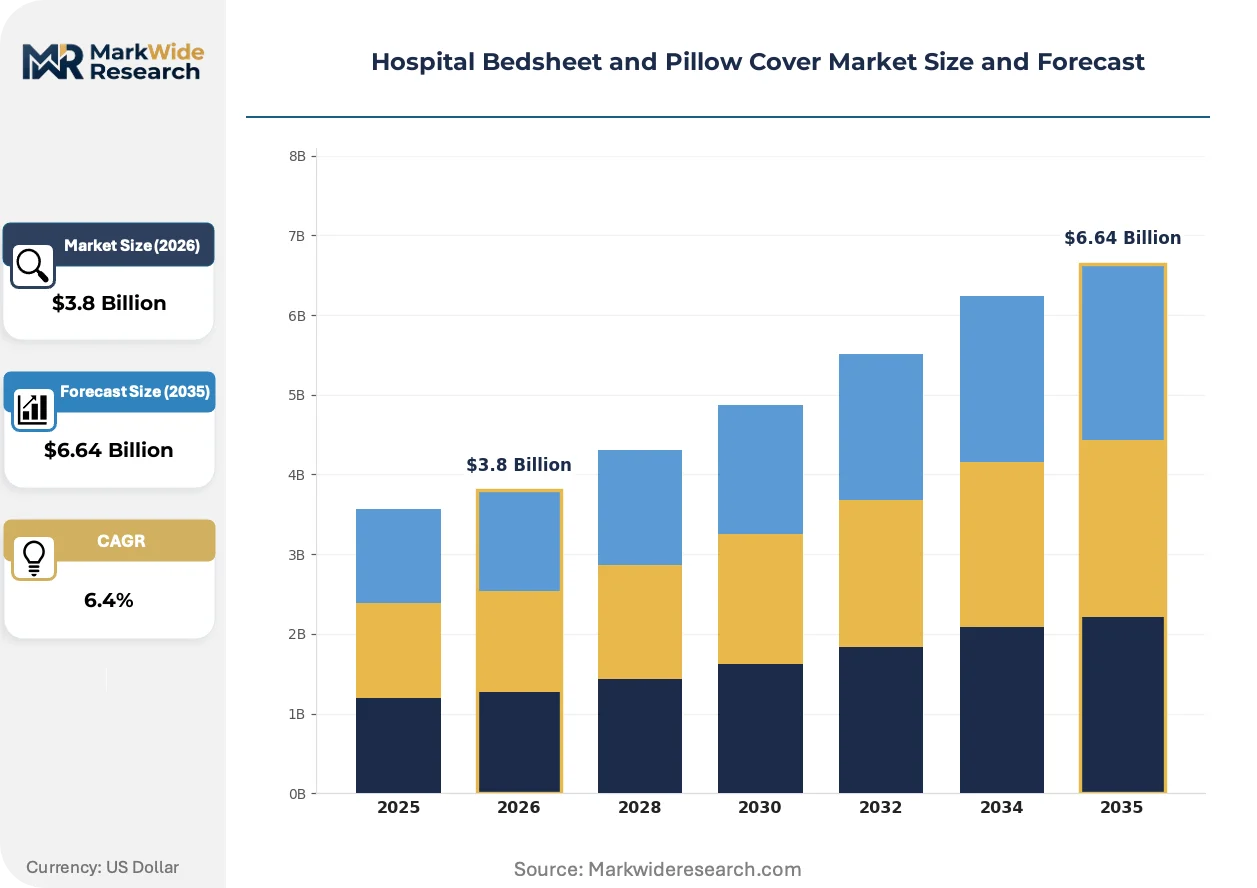
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Sheets, Fitted Sheets, Pillowcases, Bed Covers Material: Cotton, Polyester, Blends, Microfiber End User: Hospitals, Clinics, Nursing Homes, Home Care Distribution Channel: Online Retail, Wholesalers, Distributors, Direct Sales |
| Companies Covered | Emes Textiles Pvt. Ltd., Raenco Mills Pvt. Ltd., Angelica, V-linen Pvt. Ltd., Elizabethtown Laundry Company, Celtic Linen, Healthcare Services Group, ImageFIRST Healthcare Laundry Specialist, Unitex Textile Rental Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Bedsheet and Pillow Cover Market Strategic Shifts & Innovations
Material science advances and traceability mandates are converging to transform how hospital linens are specified, tracked, and retired from service across acute care networks.
Silver-ion and copper-infused fiber technologies are embedding durable antimicrobial properties directly into yarn structures rather than relying on surface coatings that degrade through industrial laundering cycles. Tertiary care hospitals in California and Texas are piloting these textiles for ICU and surgical units where infection control carries the highest clinical stakes. This embedded functionality is digitizing inventory management by enabling longer replacement intervals and predictive failure monitoring through integrated RFID systems.
REACH restrictions on per- and polyfluoroalkyl substances are forcing European linen processors to abandon traditional stain-resistant finishes by 2025. The ECHA restriction timeline is compressing reformulation windows for healthcare textile suppliers serving EU hospital networks. German and French procurement consortia are now requiring third-party OEKO-TEX certification as a baseline qualification, shifting competitive advantage toward suppliers with certified chemical management systems.
Acute care facilities are unbundling linen services from bundled facility management contracts and reverting to direct supplier relationships with specialized healthcare textile vendors. This disintermediation is fragmenting volume concentration previously captured by national laundry service conglomerates. The pattern is most pronounced in the US Midwest, where hospital systems are building captive linen processing capacity to capture cost transparency and quality control.
Hospital Bedsheet and Pillow Cover Market Segmentation
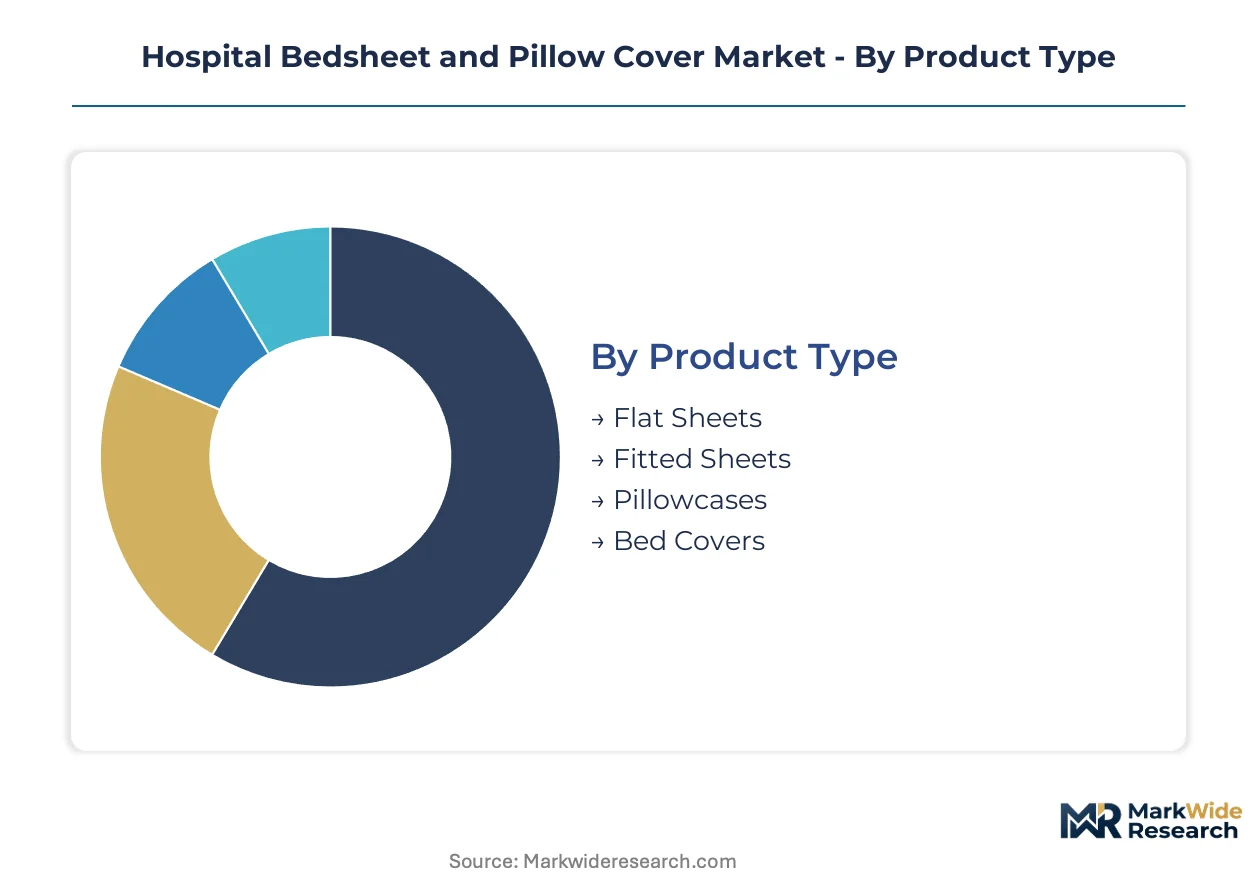
Hospital linen procurement varies sharply across care settings, with infection control protocols and laundering infrastructure dictating product specifications. Segmentation reveals how material choices and distribution pathways align with facility scale and patient acuity requirements.
Product Type:
Mature sheet formats dominate volume, while specialized covers emerge as facilities unbundle linen services from bundled contracts.
- Flat Sheets:Rectangular woven textiles without elastic retention, sized for standard hospital mattresses with reinforced hems for industrial laundering durability. Demand concentrates in tertiary care hospitals across the United States where high-temperature sterilization cycles accelerate replacement frequency.
- Fitted Sheets:Elastic-cornered designs with deep pockets for secure mattress anchoring during patient repositioning. California and Texas academic medical centers are driving specification upgrades to antimicrobial-embedded fitted formats for ICU and surgical units.
- Pillowcases:Envelope-style closures with higher thread counts for head-contact surface hygiene.
- Bed Covers:Protective outer layers for spill resistance and thermal regulation in patient rooms.
Flat sheets handle the majority of throughput; fitted sheets are the fastest mover on share.
Material:
Cost tier stratification separates premium natural fibers from synthetic alternatives optimized for rapid-cycle institutional laundering.
- Cotton:Long-staple varieties processed to healthcare-grade purity standards with natural breathability and moisture absorption. Premium purchasers in the United States specify cotton for patient comfort in long-stay rehabilitation settings.
- Polyester:Synthetic polymer fibers engineered for dimensional stability through repeated thermal disinfection cycles. Cost-sensitive volume procurement in India's expanding hospital network favors polyester for faster drying and extended replacement intervals.
- Blends:Cotton-polyester combinations balancing comfort with processing efficiency.
- Microfiber:Ultra-fine synthetic filaments with enhanced fluid resistance and reduced linting.
Cotton commands the premium tier; microfiber is climbing the fastest on specification frequency.
End User:
Application intensity varies from acute care high-throughput environments to lower-frequency community-based settings.
- Hospitals:Acute care facilities with centralized linen processing infrastructure and stringent EPA antimicrobial substantiation requirements. Surgical volume concentration in United States tertiary centers is intensifying replacement cycles for this segment.
- Clinics:Outpatient and ambulatory settings with lower bed density and reduced laundering frequency. Federally qualified health centers in the US Southeast are modernizing linen infrastructure under CMS quality incentive programs.
- Nursing Homes:Long-term care facilities with extended patient stays and comfort-prioritized procurement.
- Home Care:Distributed patient settings with consumer-grade purchasing patterns and limited industrial laundering access.
Hospitals absorb the dominant procurement volume; home care is expanding most quickly as post-acute discharge protocols shift.
Distribution Channel:
Supply concentration patterns reflect the consolidation pressure from health system centralization versus fragmented independent facility purchasing.
- Direct Sales:Manufacturer-to-institution relationships capturing multi-facility health system contracts with volume pricing and customized logistics. United States hospital consolidation is compressing procurement cycles around direct supplier relationships with specialized healthcare textile vendors.
- Wholesalers:Intermediate inventory aggregators serving smaller independent facilities without centralized purchasing power.
- Distributors:Regional logistics specialists with route density advantages for just-in-time replenishment.
- Online Retail:Digital procurement platforms for ancillary purchases and emergency replenishment.
Direct sales channels command the largest contract value; online retail is gaining share fastest among secondary market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA antimicrobial substantiation requirements and FDA hospital-grade product oversight anchor procurement patterns in the United States, while ECHA REACH restrictions and EU Green Deal textile mandates reshape European sourcing. India's vertically integrated manufacturing clusters and Japan's precision textile processing complete the geographic concentration map.
United States
Hospital consolidation into multi-facility health systems compresses procurement cycles around centralized distribution hubs. CMS quality incentive programs drive linen infrastructure modernization at federally qualified health centers in the Southeast. California and Texas academic medical centers pilot silver-ion embedded textiles for ICU infection control.
Germany
ECHA's 2025 PFAS restriction deadline forces healthcare textile processors to abandon traditional stain-resistant finishes. German procurement consortia mandate OEKO-TEX certification as baseline qualification for institutional suppliers. The North Rhine-Westphalia industrial corridor hosts reformulation R&D for REACH-compliant healthcare-grade finishing chemicals.
India
Expanding hospital networks in Maharashtra and Gujarat generate cost-sensitive volume demand for polyester-dominant product lines. BIS healthcare textile standards intersect with state-level hospital accreditation requirements to shape material specifications. Tamil Nadu's spinning-to-garment clusters shorten lead times for South Asian institutional buyers.
Japan
PMDA oversight of hospital-grade products reinforces stringent infection control protocols for acute care procurement. METI industrial policy supports precision textile manufacturing for medical applications. The Osaka-Kobe industrial zone specializes in high-thread-count cotton processing for premium patient comfort segments.
United Kingdom
NHS procurement consolidation shifts volume toward direct manufacturer relationships and away from bundled facility management contracts. UK fire safety regulations fragment product SKUs against divergent NFPA-equivalent standards. The Midlands textile manufacturing belt rebuilds healthcare linen capacity following post-2010 offshoring.
Hospital Bedsheet and Pillow Cover Market Key Industry Players
Capability concentration sits with specialized healthcare textile processors; scale advantage sits with integrated linen service networks. The vendor base organizes into three tiers: vertically integrated South Asian manufacturers, route-dense North American rental service operators, and regional wholesale distributors serving independent facilities. Competitive positioning hardens through M&A consolidation of multi-facility health system contracts and captive processing capacity investments by hospital systems seeking cost transparency.
Among vertically integrated specialists, Emes Textiles Pvt. Ltd. and Raenco Mills Pvt. Ltd. occupy positions anchored in Tamil Nadu and Gujarat manufacturing infrastructure. Angelica exemplifies the route-density archetype, with linen service networks reducing turnaround times for acute care facilities. These three represent the strategic spectrum: backward-integrated spinning-to-finishing control, specialized healthcare-grade cotton processing, and logistics-intensive service bundling.
| Leading Market Players |
|---|
| Emes Textiles Pvt. Ltd. |
| Raenco Mills Pvt. Ltd. |
| Angelica |
| V-linen Pvt. Ltd. |
| Elizabethtown Laundry Company |
| Celtic Linen |
| Healthcare Services Group |
| ImageFIRST Healthcare Laundry Specialist |
| Unitex Textile Rental Services, Inc. |
| Others |
Cost & Logistics Intelligence
Tamil Nadu's spinning-to-garment clusters concentrate finished linen capacity for institutional buyers, translating manufacturing density into pricing leverage for South Asian suppliers competing on contract volume. Raw cotton volatility in Maharashtra and bleaching chemical bottlenecks from European chlor-alkali curbs compress margins for cotton-dominant product lines, forcing tiered pricing stratification across material grades.
Pricing Analysis
Price spreads widen significantly between United States tertiary care procurement and India's cost-sensitive hospital network expansion. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified antimicrobial linens from untreated cotton and polyester-dominant alternatives. Pricing pressure stems from REACH-mandated reformulation costs for PFAS-free finishes. Federally qualified health centers in the US Southeast exhibit highest price sensitivity; academic medical centers in California and Texas prioritize infection-control certification over unit cost.
Supply Chain Analysis
Extended payment terms from multi-facility health systems strain working capital for regional distributors serving independent facilities. Manufacturing concentrates in India, China, and Pakistan, with yarn spinning anchored in Tamil Nadu and Gujarat clusters. Supply chains draw from long-staple cotton, synthetic polymer feedstocks, and healthcare-grade finishing chemicals. Single-source vulnerability sits with European chlor-alkali processors under REACH energy protocols. Distribution runs through direct sales channels capturing consolidated health system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hospital linen market tracks a cyclical recovery pattern as surgical volume concentration in tertiary centers drives replacement cycle intensity following pandemic-deferred infrastructure investments.
For Market Incumbents: Insulate market position through captive bleaching chemical supply arrangements and RFID-enabled linen tracking subscriptions that embed switching costs. EPA antimicrobial substantiation timelines favor incumbents with existing efficacy datasets. Backward integration into Tamil Nadu spinning capacity defends margin position against raw cotton volatility. For New Entrants and Emerging Players: Rural hospital networks in the US Southeast present underpenetrated demand as CMS quality incentive programs fund linen infrastructure modernization. Federally qualified health centers lack centralized procurement leverage. Direct sales partnerships with regional GPOs offer the most viable go-to-market angle against established route-dense service networks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital system captive processing investments and multi-facility contract concentration favor scaled operators with logistics density. Target vertically integrated manufacturers with OEKO-TEX certification and established EPA substantiation records. Watch RFID adoption rates in academic medical centers as inflection signal for subscription revenue traction.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Certification Investment | EPA substantiation records accelerate hospital upgrade cycles for treated textiles. |
| RFID Tracking Platform Deployment | Embedded sensors integrate with hospital asset management for predictive replacement. |
| Captive Linen Processing Capacity | Midwest health systems build in-house facilities to capture cost transparency. |
| REACH-Compliant Finishing Reformulation | PFAS-free chemistry investments secure EU procurement consortia qualification. |
| Rural Network Distribution Partnership | Federally qualified health center relationships access CMS-funded modernization. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, linen service operations directors, textile manufacturing plant managers, and GPO contracts specialists. Secondary validation drew from EPA antimicrobial claim registrations, FDA 510(k) filings, hospital procurement databases, and CMS quality incentive program disclosures. Bottom-up volume estimates triangulated against top-down health system expenditure patterns.
Calibration against historical replacement cycle data and surgical volume projections anchored growth rate derivation across the analysis window. Segmentation modeling incorporated product type, material grade, end-user acuity tier, and distribution channel concentration. CAGRs reflected procedure migration patterns toward tertiary centers and antimicrobial fabric upgrade penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated South Asian manufacturers or hospital system captive processing investments would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Mattress Topper Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
India Home Furnishing Market