
 United States Decorative Laminates Market | 2026-2036
United States Decorative Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
United States Decorative Laminates Market Intelligence
CARB Phase 2 compliance certification is reorganizing competitive access in the United States decorative laminates industry, filtering out smaller suppliers unable to sustain testing and documentation costs. Wilsonart International leverages vertical integration across resin impregnation and decorative paper production to control quality and cost. Mohawk Industries, Inc anchors its position through massive distribution scale spanning big-box retail and specialty dealer networks. Panolam Industries International, Inc. differentiates via specialized product lines targeting healthcare and institutional specifications.
Decorative laminates are composite surfacing materials manufactured by impregnating kraft paper and decorative paper sheets with thermosetting resins, then bonding them under heat and pressure to create rigid sheets typically ranging from 0.028 to 1.0 inches in thickness, used primarily to provide durable, aesthetically finished surfaces on substrates such as particleboard or medium-density fiberboard. High Pressure Laminate dominates commercial and heavy-traffic applications where abrasion resistance and impact performance justify premium positioning. Low Pressure Laminate competes aggressively in residential furniture and cabinetry where cost efficiency outweighs extreme durability requirements. The Flooring application segment is capturing disproportionate growth as luxury vinyl tile alternatives drive laminate producers to innovate texture replication and waterproof core technologies.
The EPA enforces TSCA Title VI formaldehyde emission limits, while OSHA maintains workplace exposure standards affecting resin handling and press operations, and the California Air Resources Board maintains Phase 2 benchmarks that de facto shape national product specifications. These overlapping frameworks elevate compliance costs but also create structural advantages for capitalized manufacturers with in-house laboratories and certified supply chains. Stakeholders must monitor evolving state-level amendments to formaldehyde rules and assess whether backward integration into resin synthesis offers sufficient margin protection against raw material volatility and regulatory escalation.
Market Dynamics
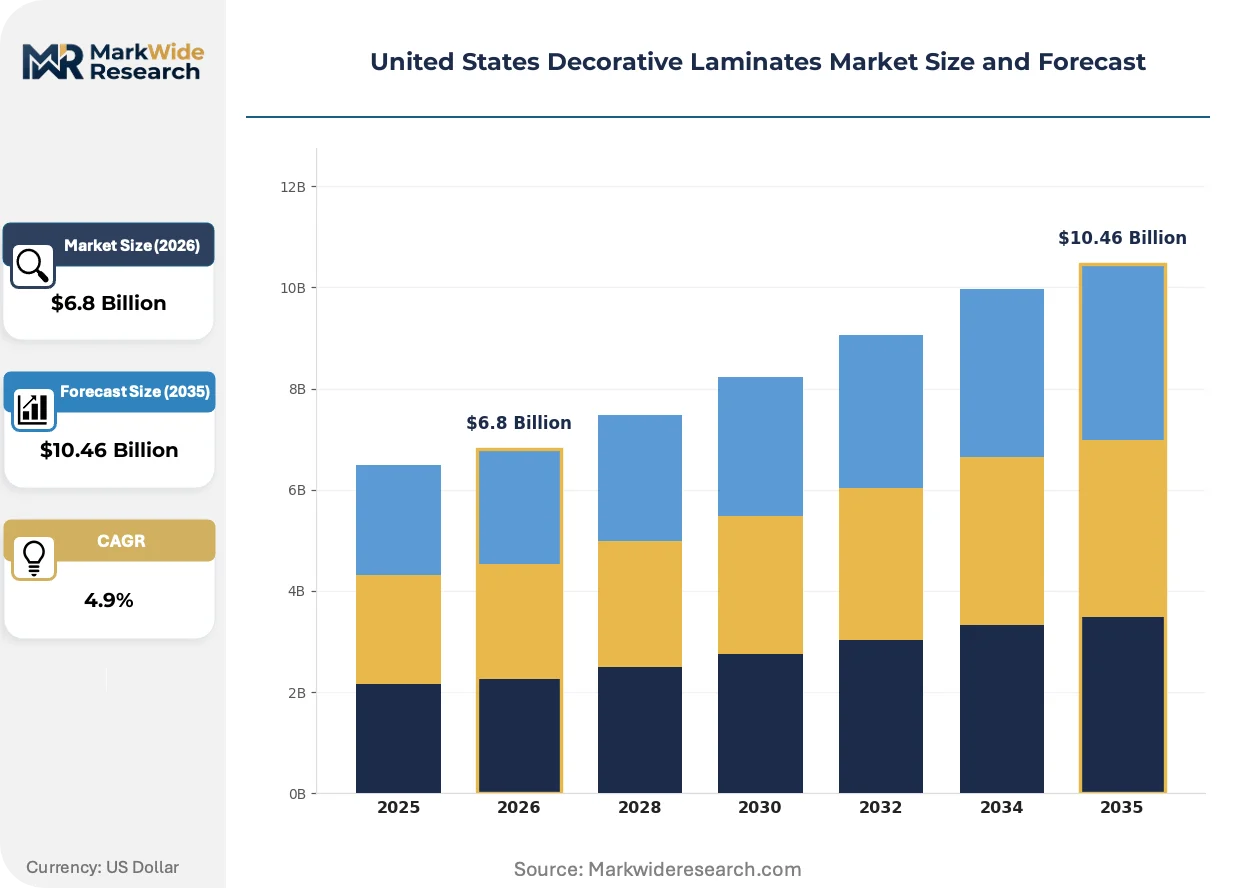
The United States decorative laminates market is undergoing a structural reorganization driven by EPA TSCA Title VI formaldehyde emission standards, which are systematically disqualifying uncertified producers and consolidating competitive access around capitalized manufacturers with in-house testing infrastructure.
Growth Catalysts
- Residential renovation pull-through:Sun Belt states including Florida, Texas, and Arizona are experiencing construction and remodeling volumes that outpace national averages, generating concentrated demand for surfacing materials in kitchen and bath applications.
- Healthcare specification expansion:Infection-control protocols in hospitals and long-term care facilities are driving specification of non-porous, chemically resistant laminate surfaces that withstand aggressive cleaning regimens.
- Waterproof core innovation:Advancements in high-density fiberboard and resin formulations are extending laminate flooring into moisture-prone residential zones previously reserved for vinyl or tile.
Market Restraints
- Formaldehyde compliance cost escalation:CARB Phase 2 and EPA TSCA Title VI testing, documentation, and third-party certification expenses impose disproportionate burdens on smaller producers lacking captive laboratory capacity.
- Decorative paper supply concentration:North American and European specialty paper mills control critical decorative print base stock, exposing laminators to input volatility and extended lead times during demand surges.
- Thermoset resin price volatility:Melamine-formaldehyde and phenolic resin costs fluctuate with natural gas and methanol feedstock pricing, compressing margin stability for non-integrated manufacturers.
Strategic Opportunities
- Texas and Florida metro expansion:Dallas-Fort Worth, Houston, Orlando, and Tampa construction pipelines exceed national permitting rates, creating geographic white space for distribution capacity expansion.
- Digital printing convergence:Combination of inkjet decoration with traditional gravure printing enables short-run customization and rapid pattern turnaround for commercial interior projects.
- IRA energy efficiency incentives:Federal tax credits for residential energy improvements are stimulating whole-home renovation activity that includes surfacing material upgrades.
Industry Challenges
- Press operator skill scarcity:Multi-opening hydraulic press operation and resin formulation chemistry require specialized technical training that vocational programs have deprioritized, constraining production scaling.
- Legacy ERP integration friction:Batch manufacturing execution systems in established facilities resist seamless connection with modern customer-facing configurators and e-commerce platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Decorative Laminates Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Pressure Laminate, Low Pressure Laminate, Backed Laminate, Decorative Paper Application: Furniture, Wall Panels, Flooring, Countertops End User: Residential, Commercial, Industrial, Retail Distribution Channel: Direct Sales, Retail Distribution, Online Sales, Wholesalers |
| Companies Covered | Panolam Industries International, Inc., LL Flooring, Inc., Wilsonart International, OMNOVA Solutions, Inc., Shaw Industries Group, Inc., Mohawk Industries, Inc, ATI Decorative Laminates, Armstrong World Industries, Inc, Formica Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Decorative Laminates Market Strategic Shifts & Innovations
Surface replication technology and regulatory compliance automation are actively redefining competitive capability requirements in the United States decorative laminates sector, separating capitalized innovators from legacy operators.
Embossed-in-register (EIR) synchronization technology is fragmenting the traditional price-performance hierarchy in laminate flooring. Home improvement retailers and multi-family developers are adopting EIR-enhanced products at accelerating rates. The technology is fragmenting market segmentation by enabling mid-tier producers to replicate premium hardwood and stone aesthetics without corresponding cost structures.
EPA TSCA Title VI enforcement protocols are compressing the supplier base toward certified producers with documented chain-of-custody systems. Third-party certification costs and quarterly testing burdens are elevating compliance as a competitive moat. Flooring and cabinetry segments are responding by consolidating procurement around suppliers with established CARB Phase 2 and EPA certification credentials.
Builder and contractor procurement patterns are compressing specification cycles and demanding integrated sample-to-delivery digital workflows. Specialty dealer networks and big-box retail channels are being disrupted by direct-to-contractor platforms with real-time inventory visibility. Sun Belt metropolitan construction markets exhibit the most pronounced shift toward consolidated purchasing through national distributor agreements.
United States Decorative Laminates Market Segmentation
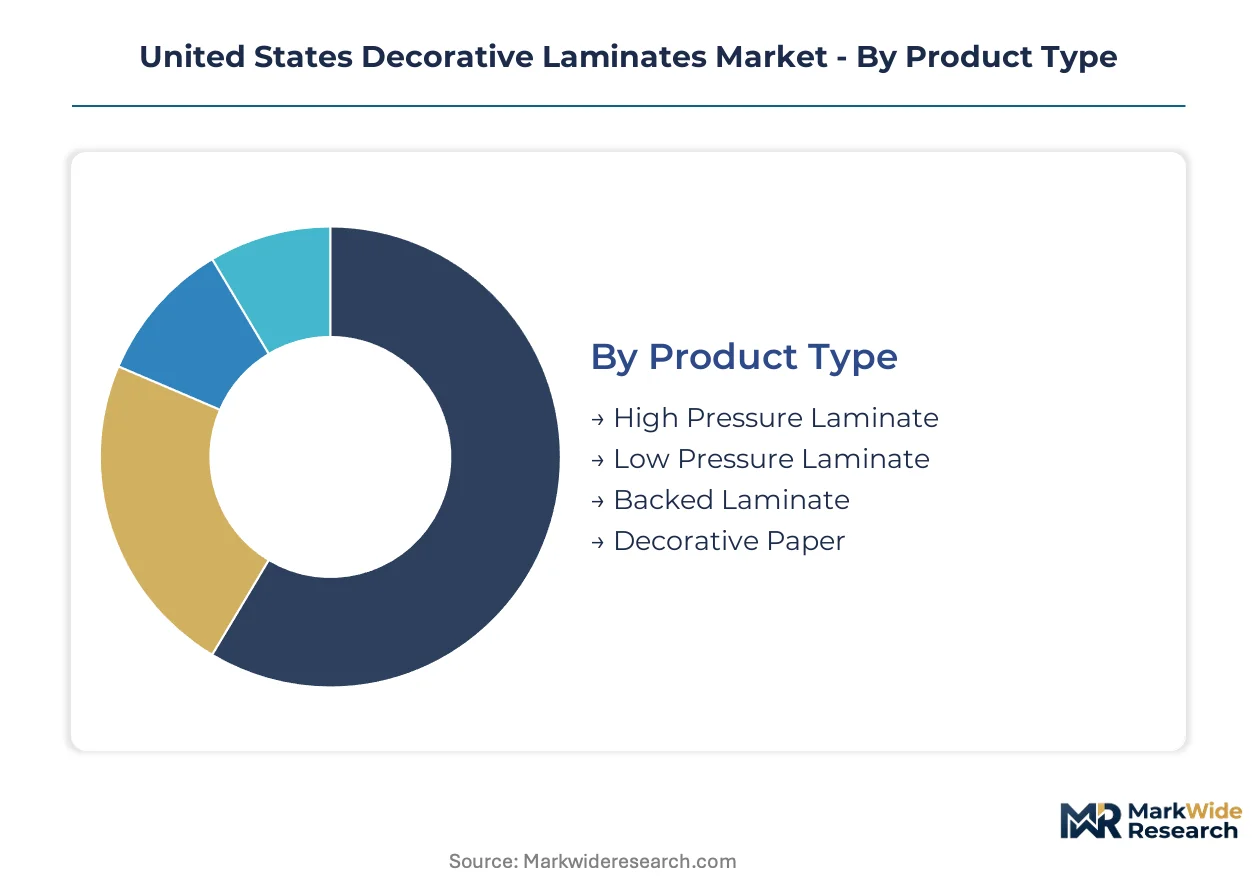
Segmentation in the United States decorative laminates market reveals how substitution pressures and regulatory compliance reshape competitive positioning across product tiers. Each dimension exposes distinct vulnerability patterns to alternative materials like luxury vinyl tile, solid surface, or engineered stone.
Product Type:
Luxury vinyl tile and engineered quartz are exerting concentrated substitution pressure on mid-tier laminate categories, forcing producers to differentiate through performance certification and texture fidelity.
- High Pressure Laminate:Constructed from multiple layers of kraft paper impregnated with phenolic resin and topped with decorative melamine-impregnated paper, fused under heat and pressure exceeding 1,000 PSI. Demand concentrates in healthcare facilities and commercial interiors across Texas and Florida where abrasion resistance and impact performance justify premium specification against solid surface alternatives.
- Low Pressure Laminate:Manufactured with a single decorative layer bonded directly to substrate under moderate pressure, offering cost efficiency for residential furniture and cabinetry. Sun Belt remodeling activity in Phoenix and Tampa metro areas drives volume as homeowners prioritize budget-conscious kitchen refreshes over full renovations.
- Backed Laminate:Features pre-attached balancing or substrate layers that reduce downstream processing steps for fabricators.
- Decorative Paper:Unpressed printed papers for on-site lamination or specialty overlay applications serving custom millwork shops.
High Pressure Laminate retains volume leadership; Low Pressure Laminate holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade applications from mass-market residential deployment, with moisture sensitivity creating distinct competitive battlegrounds.
- Flooring:Waterproof core innovations using high-density fiberboard and advanced resin formulations are extending laminate into moisture-prone residential zones previously reserved for vinyl or ceramic tile. Dallas-Fort Worth and Orlando construction pipelines are absorbing disproportionate volumes as multi-family developers specify EIR-synchronized products.
- Countertops:Postformed and flat-laminated surfaces face direct displacement from engineered quartz in premium residential kitchens, but maintain specification in rental property turnover and commercial breakrooms where cost thresholds dominate.
- Furniture:Vertical and horizontal surface applications in residential case goods and office systems.
- Wall Panels:Vertical surfacing for commercial interiors, healthcare corridors, and institutional spaces requiring impact resistance and cleanability.
Flooring commands the largest revenue base; countertops face the most intense substitution headwinds.
End User:
Customer type determines procurement channel access and specification authority, with consolidated purchasing patterns favoring national distributors over fragmented dealer networks.
- Residential:Homeowners and multi-family developers driving Sun Belt renovation cycles through big-box retail and direct-to-contractor platforms.
- Commercial:Corporate office, hospitality, and institutional clients with certified sustainability requirements and chain-of-custody documentation demands.
- Industrial:Manufacturing facilities and laboratories requiring chemical-resistant surfacing for workbenches and equipment enclosures.
- Retail:Fixture manufacturers and point-of-purchase display producers with short-run customization needs and rapid turnaround requirements.
Residential captures absolute volume; commercial delivers the highest margin realization per square foot.
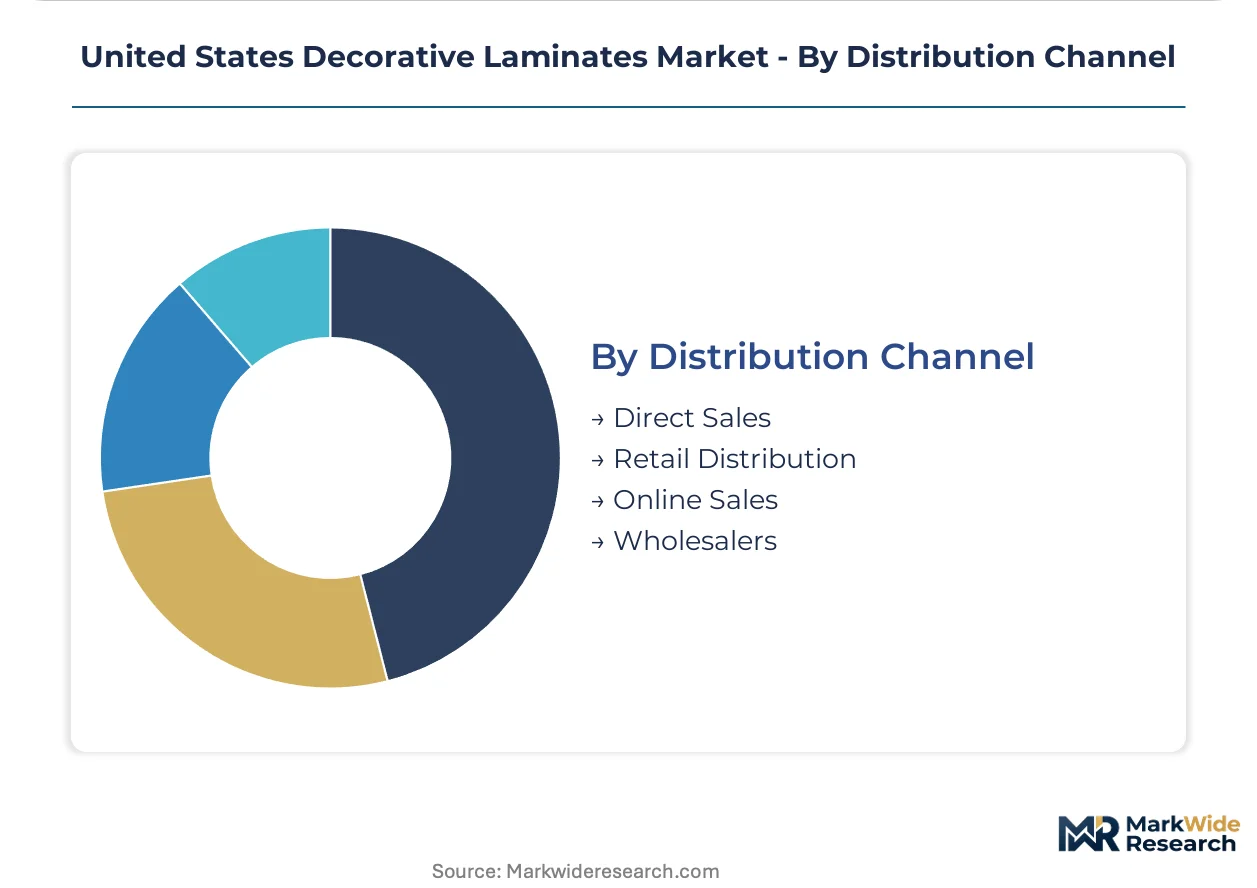
Distribution Channel:
Supply concentration in decorative paper and resin inputs shapes channel economics, with inventory carrying costs favoring scaled intermediaries over direct manufacturer engagement.
- Direct Sales:Large-volume contractors and national retail chains procuring full truckload quantities with customized specification support.
- Retail Distribution:Big-box home improvement centers and specialty surfacing dealers serving walk-in homeowners and small contractors.
- Wholesalers:Regional distributors maintaining mixed-product inventories for independent fabricators and smaller retailers.
- Online Sales:Direct-to-consumer and sample-to-delivery platforms with real-time inventory visibility disrupting traditional dealer relationships.
Retail Distribution maintains the broadest geographic footprint; Online Sales is climbing the fastest amid builder procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's residential energy efficiency tax credits are stimulating whole-home renovation cycles across the United States, with surfacing material upgrades tracking concentrated construction activity in Sun Belt metropolitan areas.
Texas
Dallas-Fort Worth and Houston construction pipelines exceed national permitting rates, driving specification of EIR-synchronized laminate flooring in multi-family developments. EPA TSCA Title VI enforcement compresses the supplier base toward certified producers with documented chain-of-custody systems. Austin and San Antonio metro areas absorb disproportionate volumes of low-pressure laminate for residential kitchen refreshes.
Florida
Orlando and Tampa residential remodeling volumes outpace national averages, generating concentrated demand for moisture-resistant laminate surfaces in kitchen and bath applications. Florida's adoption of California Air Resources Board Phase 2 benchmarks as de facto standards elevates compliance costs for uncertified producers. Miami-Dade and Broward counties exhibit pronounced shifts toward consolidated purchasing through national distributor agreements.
California
Los Angeles and San Francisco Bay Area commercial interiors drive specification of high-pressure laminate for healthcare and institutional applications requiring infection-control surfaces. CARB Phase 2 compliance certification filters out smaller suppliers unable to sustain quarterly testing and documentation burdens. Sacramento and San Diego construction markets favor waterproof core laminate flooring for moisture-prone residential zones.
Arizona
Phoenix metro area remodeling activity prioritizes budget-conscious surfacing solutions, positioning low-pressure laminate competitively against luxury vinyl tile alternatives. Arizona Department of Environmental Quality aligns state-level formaldehyde monitoring with federal TSCA Title VI thresholds. Tucson and Flagstaff distribution channels consolidate procurement around suppliers with established EPA certification credentials.
Southeast (Georgia/Carolinas)
Atlanta and Charlotte multi-family housing developments specify laminate flooring with texture replication technologies rivaling hardwood aesthetics. OSHA workplace exposure standards affect resin handling and press operations across regional manufacturing facilities. Savannah and Charleston port logistics support decorative paper import flows from European specialty mills.
United States Decorative Laminates Market Key Industry Players
Listed leaders compete with private specialists across certification and distribution dimensions, producing a tiered structure where capitalized manufacturers with in-house laboratories capture disproportionate share. The competitive landscape fragments across three strategic archetypes: vertically integrated resin-to-laminate producers, scale-driven flooring specialists, and healthcare-focused specification players. Dominant competitive moves include backward integration into decorative paper production and geographic expansion into Sun Belt distribution white space.
Within the integrated manufacturing tier, Wilsonart International and Mohawk Industries exemplify capitalized operators with captive supply chain control. Panolam Industries International occupies a position among specification-focused specialists targeting institutional end-use requirements. ATI Decorative Laminates and Armstrong World Industries represent diversified surface solutions providers with cross-category portfolio breadth.
| Leading Market Players |
|---|
| Panolam Industries International, Inc. |
| LL Flooring, Inc. |
| Wilsonart International |
| OMNOVA Solutions, Inc. |
| Shaw Industries Group, Inc. |
| Mohawk Industries, Inc |
| ATI Decorative Laminates |
| Armstrong World Industries, Inc |
| Formica Group |
| Others |
Cost & Logistics Intelligence
EPA TSCA Title VI certification gates both supplier qualification and price differentiation simultaneously, compressing the competitive field toward capitalized producers while enabling certified manufacturers to command premiums over uncertified imports. Certification costs and quarterly testing burdens create structural moats that translate into pricing power for compliant domestic operators.
Pricing Analysis
Certification level creates the primary spread across the United States decorative laminates market, with EPA TSCA Title VI and CARB Phase 2 compliance separating premium specification-grade products from economy-tier imports. Three-tier pricing structure across premium, standard, and economy levels reflects vertical integration depth, brand recognition, and after-sales technical support bundling. Cost compression in economy-tier low-pressure laminate is intensifying because luxury vinyl tile alternatives erode residential share. Multi-family developers and national retail chains exhibit the highest price sensitivity, while healthcare facility procurement teams prioritize infection-control performance over unit cost.
Supply Chain Analysis
North American specialty paper mills and European decorative print base stock producers anchor the upstream supply base for United States laminators. Kraft paper impregnation with phenolic resin and melamine-formaldehyde formulation draws from methanol and natural gas feedstocks tethered to Gulf Coast petrochemical corridors. Single-source vulnerability concentrates in decorative paper supply, with extended lead times during demand surges exposing fabricators to project delays. Distribution runs through scaled regional wholesalers maintaining mixed-product inventories for independent fabricators, alongside direct sales channels serving national retail chains and large-volume contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproof core innovation and EPA enforcement acceleration are disrupting traditional competitive hierarchies in the United States decorative laminates market, rewarding capitalized operators with captive laboratory infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into resin synthesis and decorative paper production, securing margin protection against feedstock volatility. Expand certified production capacity in Dallas-Fort Worth and Orlando metro areas to capture Sun Belt construction pipeline concentration. Prioritize ERP modernization to enable real-time inventory visibility for contractor-facing digital platforms, neutralizing direct-to-contractor platform disruption. For New Entrants and Emerging Players: Digital printing convergence for short-run commercial interior customization represents a service-layer gap where incumbents under-serve architect and designer specification cycles. Target healthcare and institutional segments in California and Texas where infection-control protocols drive premium specification and procurement consolidation lags manufacturing capacity. Pursue white-label partnerships with regional distributors lacking in-house digital decoration capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: EPA TSCA Title VI full enforcement reshapes the acquisition landscape toward certified producers with documented chain-of-custody systems and in-house testing infrastructure. Mid-tier manufacturers with captive resin impregnation and established Sun Belt distribution footprints represent the most viable acquisition archetypes. Monitor state-level formaldehyde rule amendments beyond federal baselines as the signal indicating regulatory escalation trajectory and compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive melamine-formaldehyde production insulates margin stability against methanol feedstock volatility. |
| Waterproof Core Technology Development | High-density fiberboard innovations extend laminate flooring into moisture-prone residential zones. |
| Digital Printing Capability Investment | Inkjet decoration enables short-run customization for commercial interior architect specifications. |
| Sun Belt Distribution Expansion | Dallas-Fort Worth and Orlando capacity captures construction pipeline concentration exceeding national rates. |
| Healthcare Specification Certification | Infection-control surface validation opens institutional procurement channels with premium margin realization. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with decorative laminate plant managers, procurement leads at downstream furniture OEMs, distribution channel partners, and technical R&D directors at resin formulation facilities. Secondary validation incorporated EPA TSCA Title VI certification databases, CARB compliance registries, customs and trade flow data, and SEC 10-K filings from publicly traded flooring and surfacing companies. Bottom-up volume modeling triangulated against top-down construction spending and renovation activity indices.
Across the analysis window, the forecasting framework segmented volume and value outputs by product type, application, end-user category, and distribution channel, with geographic disaggregation at state and metropolitan statistical area levels. CAGRs were derived from regression analysis against housing starts, remodeling expenditure indices, and regulatory compliance cost trajectories. Industry-specific forecast inputs included multi-family housing permit pipelines and healthcare construction spending patterns.
Underlying assumptions cover sustained Sun Belt population migration and EPA enforcement continuity, with deviation risk concentrated in decorative paper supply disruptions and thermoset resin feedstock price spikes. Recalibration cycles align with material shifts in federal energy efficiency incentive programs and state-level formaldehyde rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Pillow Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Wall Art Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Mattresses and Accessories Market