
 Plantation Shutters Market | 2026-2036
Plantation Shutters Market Size, Share, and Industry Trends Forecast 2026-2036
Plantation Shutters Market Outlook
Residential renovation activity is consolidating demand among premium homebuyers seeking energy-efficient window treatments. Hunter Douglas leverages its vertical manufacturing network to control raw material conversion from timber to finished louver systems. Norman Window Fashions anchors its position through captive Asian production facilities that sustain cost discipline across wood and composite lines. Eclipse Shutters differentiates via specialized polymer formulations that compete on moisture resistance in humid coastal zones.
Plantation shutters are hinged window coverings with adjustable horizontal louvers, typically constructed from solid wood, engineered composites, or extruded vinyl with blade widths ranging from 2.5 to 4.5 inches, designed to regulate light ingress, airflow, and thermal transfer through operable slat angles. Wood and composite materials dominate value capture due to premium positioning in custom residential specifications, while vinyl segments lead volume throughput in production housing and multi-family developments. Professional installation channels concentrate margin pools through measured-service bundling, whereas DIY segments expand access through big-box retail partnerships.
EPA formaldehyde emission standards under TSCA Title VI govern composite wood substrates used in shutter construction, compelling manufacturers to certify supply chains or pivot to solid timber alternatives. California Air Resources Board (CARB) Phase 2 requirements extend these mandates to products sold in the state, creating a de facto national compliance threshold. Stakeholders must monitor evolving state-level building codes and material disclosure protocols that will determine competitive access across the North American specification landscape.
Market Dynamics
California's Title 24 building energy code is tightening thermal performance requirements for fenestration products, forcing manufacturers to reformulate material stacks and certification protocols across residential construction channels.
Growth Catalysts
- Energy Efficiency Mandates:California's Title 24 code compels specification of thermally rated window treatments in new construction and renovation projects.
- Historic Preservation Tax Credits:Federal and state-level incentives for historic home restoration sustain demand for custom wood shutter systems in designated districts.
- Composite Material Advances:Engineered polymer formulations deliver moisture resistance and dimensional stability for humid coastal installations.
Market Restraints
- Solid Timber Supply Concentration:Premium hardwood sourcing concentrates in Southeast Asian and South American export markets, exposing margins to freight volatility and export licensing delays.
- Formaldehyde Emission Compliance:EPA TSCA Title VI and CARB Phase 2 testing requirements add certification costs and extended lead times for composite substrate imports.
- Vinyl Substitution Pressure:Lower-cost extruded vinyl alternatives capture volume in production housing segments, compressing price realization for wood and composite lines.
Strategic Opportunities
- Smart Home Integration:Motorized louver systems with app-controlled positioning and automated solar tracking create premium upgrade paths in luxury residential markets.
- Southern Climate Adaptation:Hurricane-rated shutter systems with impact-resistant cores address building code amendments across Florida, Louisiana, and Texas Gulf Coast counties.
- Retrofit Measurement Services:Digital templating and rapid-install protocols reduce project duration for renovation contractors seeking one-day completion guarantees.
Industry Challenges
- Skilled Installation Labor Scarcity:Precision fitting of custom shutters demands trained craftspeople, with qualified technician pools contracting in metropolitan construction markets.
- Multi-Jurisdiction Certification Complexity:Manufacturers must maintain parallel compliance documentation for EPA, CARB, and emerging state-level material disclosure registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plantation Shutters Market |
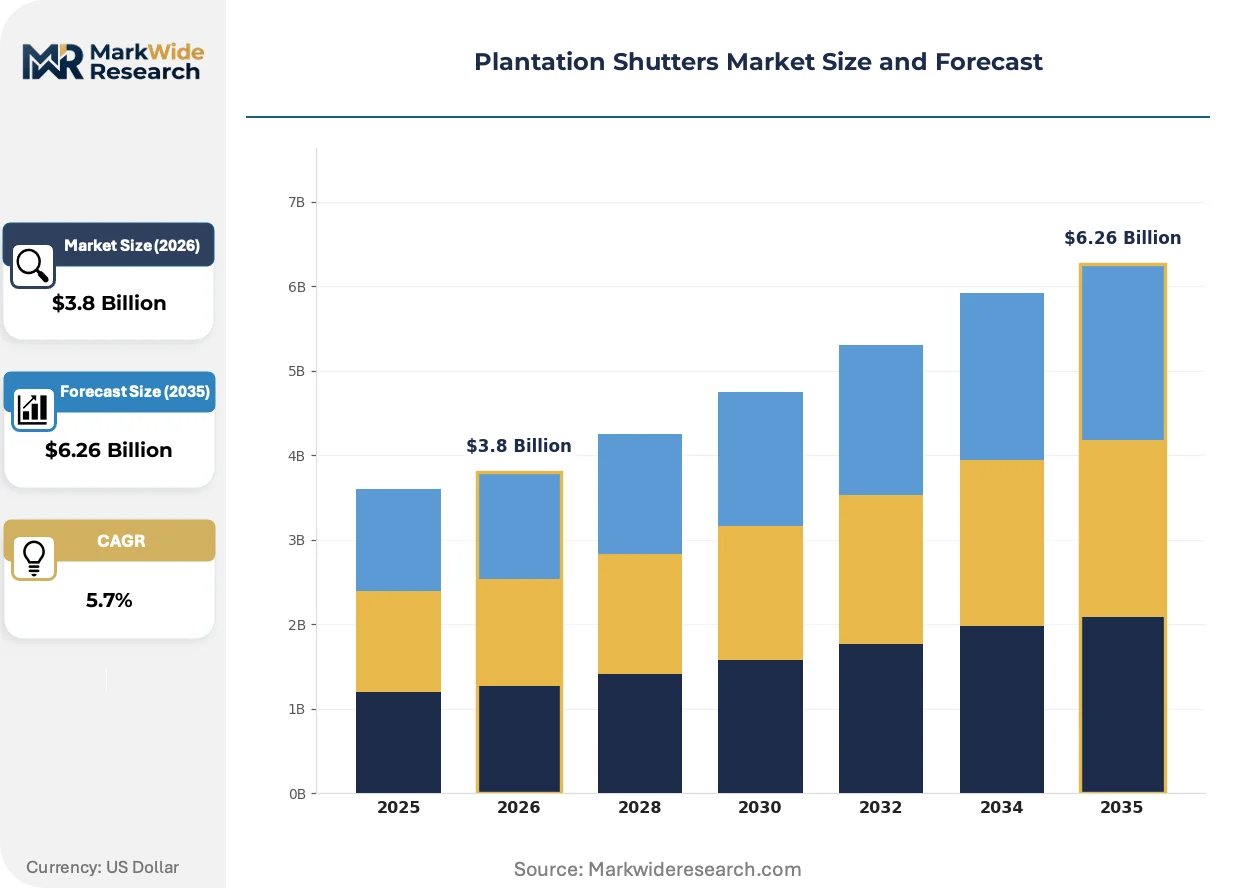
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Faux Wood, Vinyl, Composite Style: Traditional, Modern, Contemporary, Classic Installation Type: Inside Mount, Outside Mount, DIY, Professional End User: Residential, Commercial, Hospitality, Education |
| Companies Covered | Sunburst Shutters, Eclipse Shutters, Hunter Douglas, Rockwood Shutters, Southern Shutter Company, Norman Window Fashions, ALTA Window Fashions, Shanghai Toma Building Material, Graber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plantation Shutters Market Strategic Shifts
Material science breakthroughs and regulatory pressure on thermal performance are restructuring competitive advantage around certified efficiency credentials rather than aesthetic differentiation alone.
Cellular composite cores with integrated thermal breaks are overtaking solid wood construction in high-performance specifications. Custom residential builders in California and Pacific Northwest markets specify these systems for Title 24 compliance. The shift is compressing market share for traditional timber-only fabricators lacking certified composite lines.
EPA formaldehyde emission standards under TSCA Title VI now govern composite wood substrates nationwide, extending California's CARB Phase 2 thresholds to all interstate commerce. Manufacturers must certify supply chains through third-party testing or pivot to solid timber alternatives. This regulatory friction most affects mid-tier suppliers dependent on imported MDF and particleboard components.
Measured-service bundling is consolidating professional installation channels as homeowners prioritize guaranteed fit-and-finish over cost-minimizing DIY approaches. Big-box retail partnerships with certified installer networks are displacing independent contractor sourcing in suburban renovation markets. This channel shift is most visible in Texas and Florida metropolitan statistical areas where single-family renovation permits remain elevated.
Plantation Shutters Market Segmentation
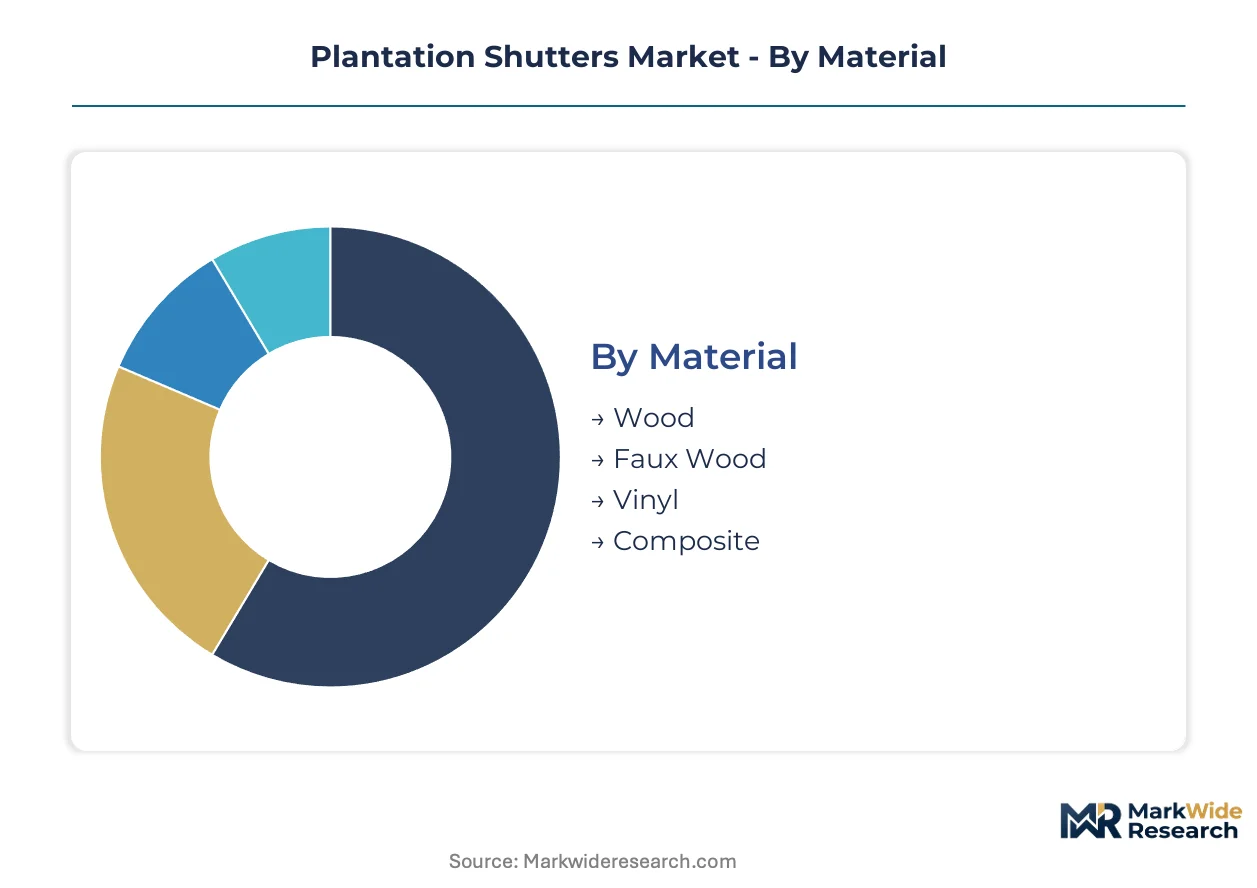
Material selection dictates thermal performance certification paths and margin structures across specification channels. Style and installation type determine whether manufacturers compete on measured-service premiums or big-box volume throughput.
Material:
Customization intensity spans from hand-finished solid timber to extruded vinyl production runs, with compliance costs clustering at the composite and engineered wood tiers.
- Wood:Premium hardwoods including basswood, poplar, and alder deliver dimensional stability for wide louver spans. Demand concentrates in California historic districts and Pacific Northwest custom residential where CARB Phase 2 certification and Title 24 thermal ratings command specification priority.
- Faux Wood:Engineered polymer composites with wood-grain surfacing achieve moisture resistance for humid coastal installations. Florida and Louisiana Gulf Coast counties specify these systems for hurricane-rated fenestration compliance without solid timber maintenance burdens.
- Vinyl:Extruded PVC formulations dominate production housing and multi-family developments through cost discipline and color consistency.
- Composite:Cellular cores with integrated thermal breaks address California Title 24 energy code mandates in new construction.
Most installed capacity flows through Vinyl. Expansion is steepest in Composite.
Style:
Aesthetic positioning maps directly to renovation versus new construction channels, with preservation requirements anchoring traditional specifications.
- Traditional:2.5-inch to 3.5-inch louvers with center-tilt rods match historic fenestration proportions. Federal and state historic preservation tax credits sustain specification in designated districts across Charleston, Savannah, and New Orleans.
- Modern:Hidden tilt rods and 4.5-inch blades emphasize clean sightlines for contemporary architecture. Austin, Denver, and Portland metropolitan markets specify these systems for infill residential and adaptive reuse projects.
- Contemporary:Asymmetrical panel configurations and specialty shapes accommodate architectural glazing. Texas and Florida custom builders specify these for luxury residential where window walls dominate elevation design.
- Classic:Standard louver proportions without applied molding suit production housing consistency. National builders specify these across suburban developments in Atlanta, Phoenix, and Dallas-Fort Worth.
Traditional commands premium pricing in preservation channels. Contemporary is climbing the fastest among custom residential specifications.
Installation Type:
Service bundling separates margin pools between guaranteed fit-and-finish and cost-minimized self-installation.
- Inside Mount:Recessed frame installation within window jamb reveals requires precise measurement tolerances. Professional channels dominate this segment through digital templating and one-day completion guarantees in Houston, Miami, and Los Angeles renovation markets.
- Outside Mount:Surface-applied frames accommodate irregular openings or shallow jamb depths. DIY segments capture volume here through big-box retail partnerships where homeowners prioritize cost over precision fitting.
- DIY:Pre-cut standard sizes with snap-together frames expand access through Home Depot and Lowe's distribution. This channel compresses margins for manufacturers but builds brand recognition for upgrade conversion.
- Professional:Measured-service bundling with certified installer networks consolidates suburban renovation markets. Texas and Florida metropolitan statistical areas show strongest displacement of independent contractor sourcing.
Professional channels capture the highest margin per unit. DIY is gaining share fastest through retail partnership expansion.
End User:
Application context determines performance specification intensity and replacement cycle frequency.
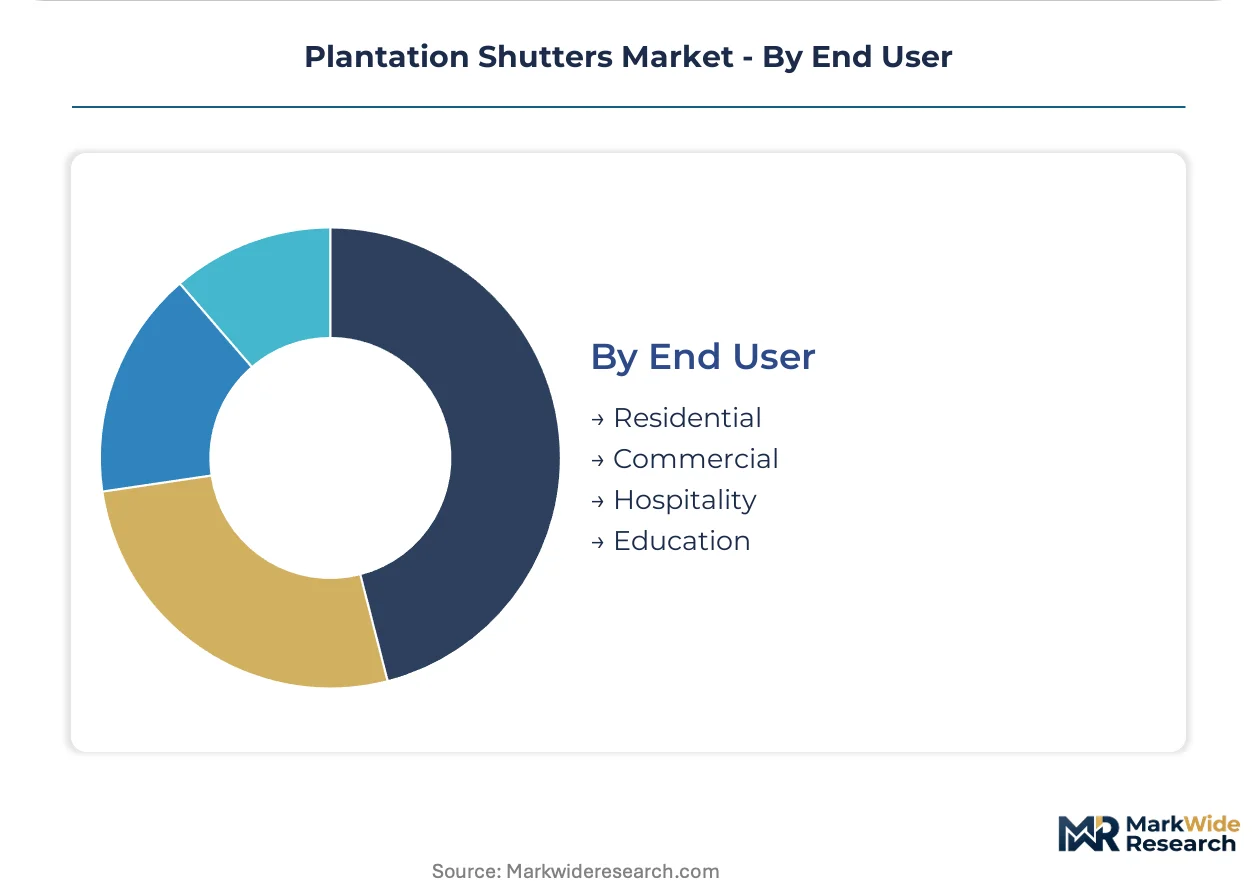
- Residential:Single-family renovation and new construction account for the majority of value capture. California energy codes and southern climate adaptation drive specification toward certified thermal performance and impact resistance.
- Commercial:Office and retail installations prioritize durability and standardized maintenance protocols. Property management firms specify composite and vinyl systems for reduced lifecycle costs.
- Hospitality:Hotel and resort properties balance aesthetic differentiation with operational durability. Coastal properties in Florida and California specify moisture-resistant materials for salt-air exposure.
- Education:K-12 and university facilities emphasize safety, durability, and institutional procurement compliance. California school districts specify CARB Phase 2 certified materials for indoor air quality mandates.
Residential absorbs the majority of production capacity. Hospitality shows the steepest expansion trajectory among non-residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Southern United States anchors demand concentration for plantation shutters, with historic preservation districts and hurricane-building codes driving specification intensity across Texas, Florida, and Louisiana metropolitan corridors.
United States
Residential renovation permits in Houston, Miami, and Los Angeles sustain professional installation channel growth. EPA TSCA Title VI formaldehyde emission standards govern composite wood substrates nationwide, extending California's CARB Phase 2 thresholds to interstate commerce. Dallas-Fort Worth and Atlanta suburban developments absorb volume throughput for production housing specifications.
Canada
Energy-efficient window treatment demand concentrates in Toronto and Vancouver custom residential markets. Health Canada administers product safety standards for interior finish materials through the Canada Consumer Product Safety Act. Ontario and British Columbia renovation contractors specify thermally rated systems for cold-climate performance.
United Kingdom
Historic property restoration in London and Edinburgh sustains traditional wood shutter specifications. UK Building Regulations Part L sets thermal performance standards for fenestration in residential construction. Southeast England and Scotland central belt metropolitan areas show strongest displacement of curtains with hard window treatments.
Germany
Passive house construction standards in Berlin and Munich drive demand for thermally broken composite systems. The German Energy Saving Ordinance (EnEV) mandates minimum thermal insulation values for building envelopes including window treatments. Bavaria and North Rhine-Westphalia fabrication clusters supply certified components across Central European markets.
Australia
Coastal climate adaptation in Sydney and Brisbane prioritizes moisture-resistant polymer formulations. The National Construction Code sets bushfire attack level requirements for external window coverings in designated zones. New South Wales and Queensland residential builders specify impact-rated systems for cyclone-prone northern regions.
Plantation Shutters Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retrofit lines for composite thermal break construction and CARB Phase 2 certification. The vendor base stratifies across three tiers: vertically integrated timber converters with captive Southeast Asian supply, polymer specialists with extrusion capabilities, and regional fabricators serving measured-service installation networks. Two strategic archetypes define competitive positioning: premium custom shops competing on historic preservation credentials, and scale operators capturing production housing volume through big-box retail partnerships. Geographic expansion into hurricane-rated product lines and backward integration into certified composite substrate production represent the dominant competitive moves.
Among North American fabricators, Hunter Douglas exemplifies the vertically integrated archetype through upstream control over timber conversion, while Norman Window Fashions anchors the Asia-based production model. Eclipse Shutters occupies a position within the polymer specialization tier. These three companies collectively represent the strategic vectors—integration depth, offshore cost discipline, and material science differentiation—that structure competitive dynamics across residential specification channels.
| Leading Market Players |
|---|
| Sunburst Shutters |
| Eclipse Shutters |
| Hunter Douglas |
| Rockwood Shutters |
| Southern Shutter Company |
| Norman Window Fashions |
| ALTA Window Fashions |
| Shanghai Toma Building Material |
| Graber |
| Others |
Value Chain & Pricing Dynamics
Southeast Asian hardwood timber flows through three distinct pricing tiers before reaching end buyers, with basswood and poplar conversion costs in Vietnam and Indonesia determining baseline material economics for premium wood shutter lines. Freight volatility from Ho Chi Minh City and Surabaya export ports compresses margins for mid-tier fabricators lacking long-term supply contracts, while California CARB Phase 2 certification costs add a compliance premium that stratifies final pricing by certification status rather than aesthetic grade alone.
Pricing Analysis
Retailer markup layers separate factory gate pricing from consumer-facing tiers, with big-box partnerships commanding volume discounts that independent measured-service channels cannot match. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal performance rating rather than raw material cost alone. Cost compression in the vinyl segment intensifies because extruded PVC formulations from Chinese producers flood production housing specifications. Production housing developers exhibit highest price sensitivity, while historic district renovation contractors prioritize CARB-certified custom work over cost minimization.
Supply Chain Analysis
Regional distribution centers in Dallas, Atlanta, and Los Angeles anchor hub-and-spoke patterns that feed measured-service installer networks across southern and western metropolitan corridors. Manufacturing capacity concentrates in China, Vietnam, and Indonesia for composite substrate and finished louver production, with domestic U.S. fabrication limited to final assembly and custom finishing. Raw material sourcing draws from Malaysian and South American hardwood plantations, South Korean polymer resin suppliers, and domestic PVC resin producers. Single-source vulnerability in Southeast Asian timber exports exposes lead times to export licensing delays. Distribution runs through manufacturer-direct installer networks and big-box retail partnerships with certified installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plantation shutter manufacturing presents a geographic-arbitrage opportunity between Southeast Asian production costs and U.S. regulatory compliance premiums, with CARB Phase 2 certification requirements in California creating a cost barrier that offshore producers must absorb or bypass through domestic assembly investments.
For Market Incumbents: Hedge against vinyl substitution pressure by deepening captive supply of certified composite substrates and expanding thermal break fabrication capacity in Texas or Florida to reduce logistics exposure to West Coast port congestion. Anchor position through exclusive measured-service installer networks in Houston, Miami, and Los Angeles renovation markets where precision fitting commands premium pricing. For New Entrants and Emerging Players: Boutique hospitality renovators in Florida and California coastal markets remain underserved by standardized product lines, offering entry points for moisture-resistant polymer formulations with rapid-install protocols. Capture share through digital templating services that guarantee one-day completion, targeting independent contractors displaced by big-box certified networks in Dallas-Fort Worth and Atlanta suburbs. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier fabricators lack CARB certification and thermal break production capabilities, creating acquisition targets with stranded customer relationships. Prioritize platforms with established installer networks and composite substrate supply agreements over pure manufacturing assets. Monitor California Title 24 amendment announcements as the signal indicating accelerated demand shift toward certified thermal performance products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Substrate Production | Captive supply of CARB Phase 2 certified cores eliminates third-party certification delays and import lead time volatility. |
| Hurricane-Rated Product Line Expansion | Impact-resistant shutter systems address Florida and Texas Gulf Coast building code amendments with premium positioning. |
| Digital Templating and Rapid-Install Protocol Development | One-day completion guarantees differentiate measured-service channels from DIY big-box alternatives in renovation markets. |
| Smart Home Motorization Integration | App-controlled louver positioning captures upgrade revenue in luxury residential segments across Austin and Denver. |
| Regional Distribution Center Optimization | Hub consolidation in Dallas and Atlanta reduces freight costs to southern metropolitan statistical areas with elevated permit activity. |
Study Parameters
Coverage spans the United States, Canada, United Kingdom, Germany, and Australia, with primary inputs from each market's specification channels and regulatory environments. Primary interviews with shutter fabrication plant managers, residential renovation contractors, big-box category buyers, and historic preservation commission staff combined with secondary validation from EPA TSCA Title VI certification databases, CARB Phase 2 compliance registries, and municipal building permit filings. Bottom-up demand modeling from renovation permit data triangulates against top-down market size estimates derived from distributor shipment reports and customs trade records.
Rate-of-change decomposition separates volume growth from price realization across material segments, with CAGRs derived from regression analysis of historic permit trends and regulatory implementation timelines. Segmentation dimensions include material type, installation channel, end-use application, and regional climate adaptation requirements. Forecast inputs incorporate California Title 24 thermal performance thresholds, hurricane building code adoption patterns across Gulf Coast counties, and composite material substitution elasticities in humid coastal markets.
Underlying measurement precision varies by segment; vinyl production housing specifications carry tighter precision than custom wood historic preservation channels due to standardized product reporting. Forecasts reflect documented assumptions regarding regulatory implementation schedules, timber supply continuity, and installer labor availability. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that export licensing delays, freight rate volatility, or accelerated state-level energy code adoption could materially revise demand trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
Interior Design Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Bookends Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
Bifold Door Market