
 Global Homeware Market | 2026-2036
Global Homeware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Homeware Market Analysis
Asset-light leasing and subscription-based furnishing models are rewriting competitive entry barriers in homeware, allowing digital-native retailers to challenge legacy manufacturers without heavy balance-sheet investment. IKEA leverages its captive supply chain and flat-pack logistics architecture to sustain margin advantages across price tiers. Williams-Sonoma anchors premium kitchenware positioning through direct-to-consumer channel control and culinary lifestyle branding. Herman Miller competes in the corporate and home-office crossover segment with ergonomic specialization that commands specification-driven procurement.
Global homeware encompasses durable and semi-durable goods for residential and commercial interior environments, spanning furniture constructed from engineered wood and solid timber composites, kitchenware in ceramic and stainless-steel grades, textiles with specified thread counts and flame-retardant treatments, and decorative objects serving aesthetic and functional roles. The primary commercial purpose centers on outfitting living, working, and hospitality spaces with standardized, replaceable, or upgradable interior components. Furniture and kitchenware dominate value capture given higher unit economics and repeat purchase cycles, while online retail channels are displacing traditional wholesale distribution as logistics networks enable direct fulfillment of bulky goods. Textiles and decor represent faster-turning segments where trend velocity and seasonal refresh rates compress design-to-shelf timelines.
EPA regulations on formaldehyde emissions from composite wood products shape material sourcing decisions for US-bound furniture, while REACH restrictions on phthalates and heavy metals redirect European textile and decor supply chains toward certified alternatives. China's SAMR enforcement of updated GB standards for indoor air quality is pressuring exporters to reformulate finishes and adhesives. Stakeholders must monitor regulatory divergence across these three jurisdictions to avoid compliance-driven margin erosion and supply disqualification.
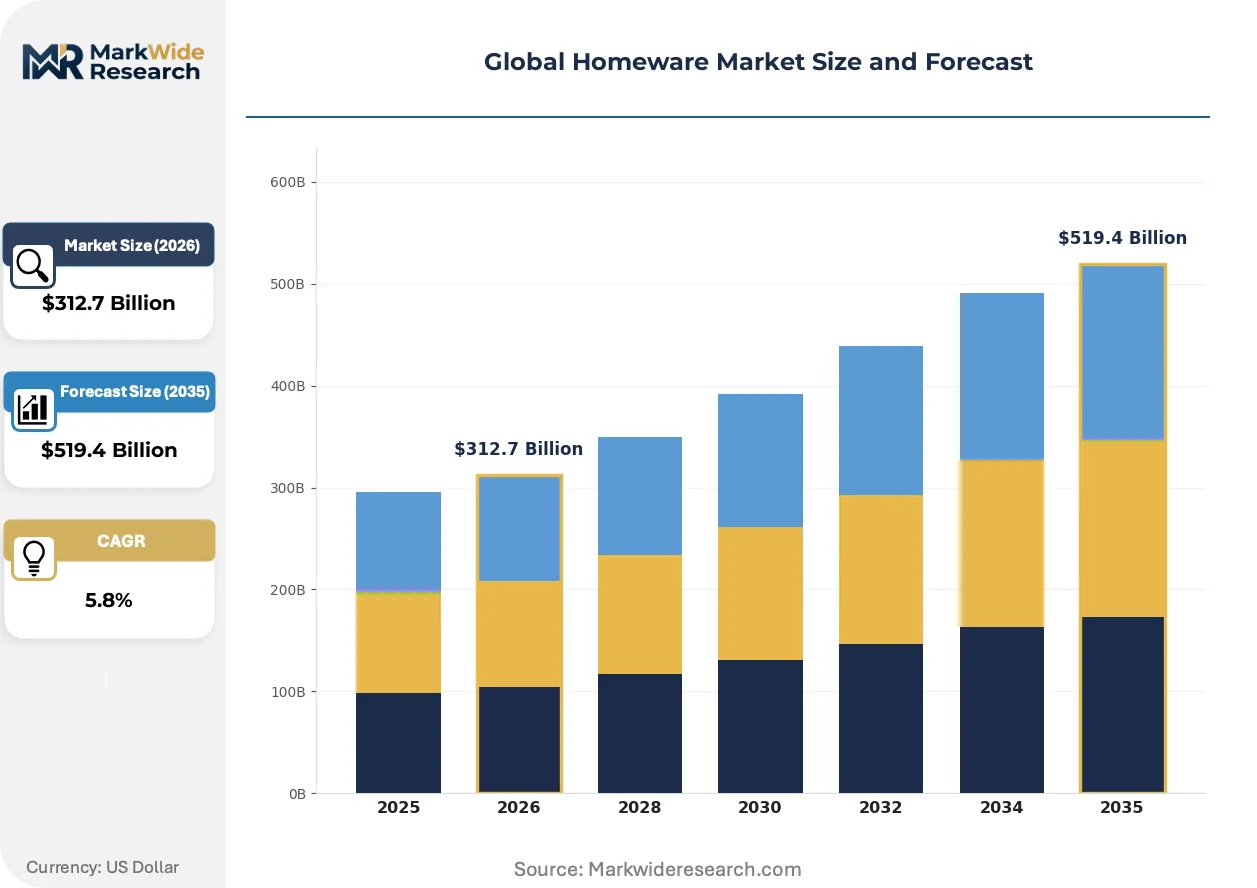
Market Dynamics
Millennial household formation patterns are fragmenting demand across rental, ownership, and hybrid living arrangements, forcing manufacturers to modularize product lines and compress design cycles for faster inventory turns.
Growth Catalysts
- REACH compliance mandates:European restrictions on phthalates and heavy metals in textiles are accelerating certified alternative sourcing, creating first-mover advantages for suppliers with pre-validated material libraries.
- India PLI scheme for furniture manufacturing:Production-linked incentives are drawing capital toward domestic capacity expansion, reducing import dependence for engineered wood and metal components.
- Flat-pack logistics architecture:Container density optimization through knock-down assembly is lowering landed costs for bulky furniture, enabling direct-to-consumer fulfillment at competitive price points.
Market Restraints
- Volatile engineered wood input costs:Resin and composite timber prices fluctuate with petrochemical feedstock markets, compressing margins for mid-tier furniture producers unable to pass through increases.
- Chinese GB standard enforcement:SAMR's updated indoor air quality regulations are disqualifying non-compliant finishes from export eligibility, forcing reformulation investments without guaranteed volume recovery.
- Substitution by secondhand marketplaces:Peer-to-peer resale platforms for furniture and decor are capturing younger cohorts, eroding new-unit demand in discretionary categories.
Strategic Opportunities
- Underpenetrated Indian urban markets:Tier-2 and Tier-3 city household formation is outpacing organized retail presence, creating whitespace for localized production and distribution partnerships.
- Subscription-based furnishing models:Asset-light leasing platforms are rewriting competitive entry barriers, allowing digital-native retailers to challenge legacy manufacturers without heavy balance-sheet investment.
- EU Green Deal circularity requirements:Extended producer responsibility frameworks for furniture end-of-life are incentivizing design-for-disassembly and material recovery systems.
Industry Challenges
- Certification timeline compression:Multi-jurisdictional compliance with EPA formaldehyde rules, REACH chemical restrictions, and evolving GB standards requires parallel testing tracks that strain quality assurance bandwidth.
- Supply chain reconfiguration friction:Relocating component sourcing from concentrated Asian hubs to regional alternatives involves qualification delays and specification mismatches in engineered wood grades.
- Digital-native talent scarcity:Traditional manufacturers lack embedded expertise in direct-to-consumer platform operations and data-driven demand forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Homeware Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $519.4 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Kitchenware, Textiles, Decor Material: Wood, Metal, Glass, Plastic Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales End User: Households, Hospitality, Corporates, Institutions |
| Companies Covered | Ashley Furniture Industries, Herman Miller, IKEA, Natuzzi, La-Z-Boy, Wayfair, Steelcase, Roche Bobois, Williams-Sonoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Homeware Market Emerging Trajectories
Virtual visualization tools and modular production systems are collapsing the traditional separation between manufacturing scale and customization depth, enabling mass-market personalization without inventory bloat.
Augmented reality configurators are virtualizing the showroom experience, allowing millennial renters to overlay furniture dimensions and finishes onto apartment spaces via smartphone cameras. HomeGoods and Wayfair-type platforms are deploying these tools at scale, reducing return rates for bulky items. The technology is virtualizing spatial planning decisions that previously required physical presence, compressing the consideration-to-purchase cycle.
EPA formaldehyde emission standards for composite wood products are tightening material sourcing specifications, pressuring manufacturers toward certified low-emitting resins and third-party verification. Mills supplying US-bound furniture must maintain chain-of-custody documentation from veneer through finished goods. Kitchen cabinetry and children's furniture segments face the steepest compliance costs given stricter exposure limits.
Rental and subscription procurement models are displacing traditional ownership cycles among urban millennials, with operators like Feather and Fernish bundling delivery, assembly, and end-of-life retrieval. These platforms capture customers seeking flexibility without capital commitment, particularly in high-mobility coastal metros. The model concentrates demand forecasting risk with operators while shifting inventory ownership off consumer balance sheets.
Global Homeware Market Segmentation
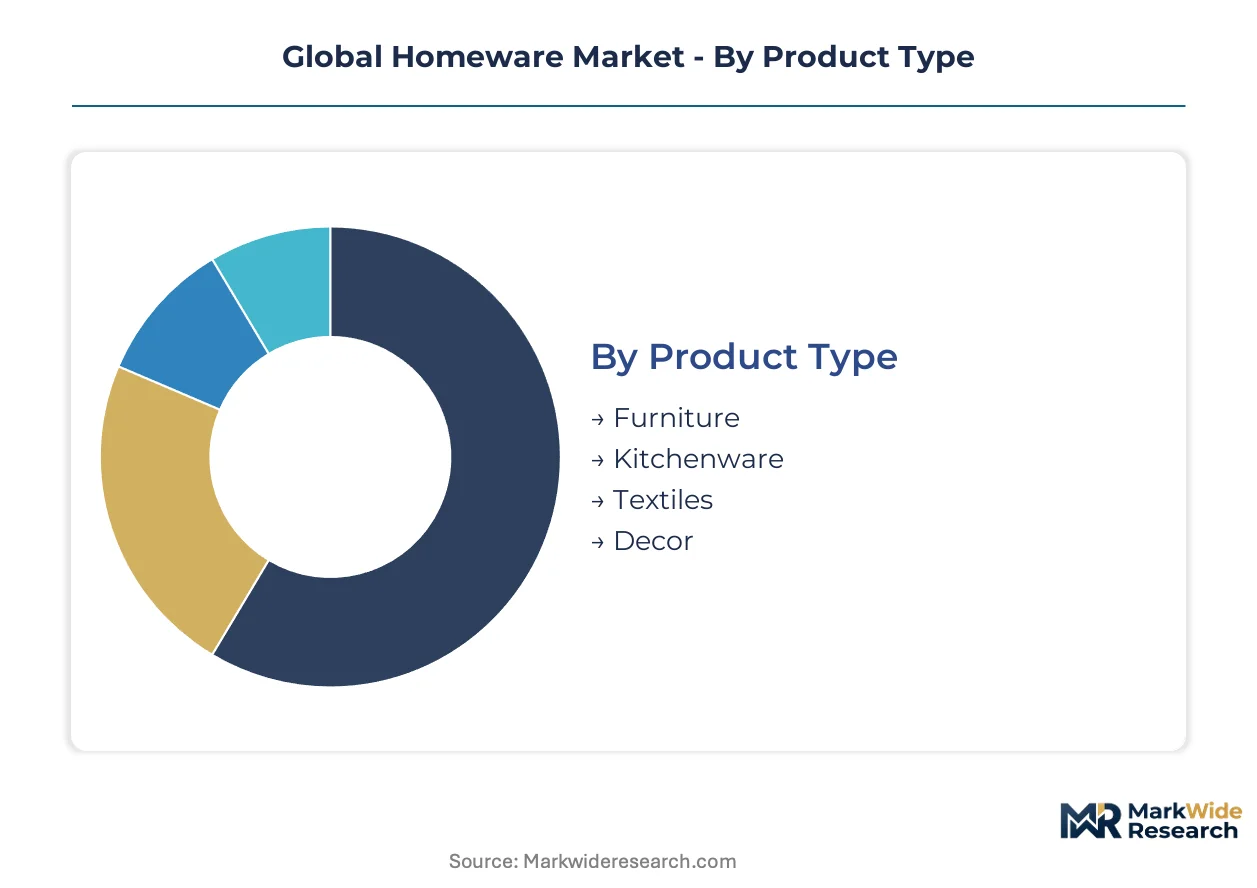
Segmentation in homeware reveals divergent margin profiles and inventory velocity patterns. Furniture and kitchenware tie up working capital for months while textiles and decor refresh seasonally. Understanding these cycle-time differences shapes procurement strategy and channel investment priorities.
Product Type:
Furniture turns slowest with the highest unit economics, kitchenware occupies the middle ground with replacement-driven demand, and textiles plus decor rotate fastest on trend cycles.
- Furniture:Engineered wood and solid timber composites dominate construction, with flat-pack knock-down designs optimizing container density for direct fulfillment. Demand concentrates in millennial household formation across India and Southeast Asia, where urban rental markets favor modular, transportable pieces that survive multiple relocations.
- Kitchenware:Ceramic and stainless-steel grades serve distinct price tiers, with thermal performance specifications driving professional-grade procurement. Replacement cycles accelerate in markets where cooking frequency rose post-pandemic, particularly in European and North American households upgrading from entry-level to premium cookware sets.
- Textiles:Specified thread counts and flame-retardant treatments differentiate commercial from residential grades. Hospitality procurement in Dubai and Singapore drives volume for certified hotel linen programs.
- Decor:Aesthetic and functional objects compress design-to-shelf timelines to eight weeks or less. Social media trend velocity in Brazil and Mexico shapes seasonal assortment planning for mass-market retailers.
Furniture anchors the volume base while decor gains share at the steepest rate.
Material:
Cost tier stratification runs from commodity resins through certified sustainable timber, with regulatory compliance costs widening the gap between entry and premium grades.
- Wood:Composite timber with low-emitting resins commands premium positioning under EPA formaldehyde rules and EU REACH timber regulations. Certification documentation from forest to finished goods protects US and European market access.
- Metal:Stainless steel grades 304 and 316 serve kitchenware durability requirements, with brushed finishes differentiating premium tiers. Indian PLI scheme incentives are expanding domestic stainless production for furniture frames and hardware.
- Glass:Tempered and borosilicate variants serve thermal shock resistance needs in cookware and serveware. Lead-free crystal maintains niche positioning in European decorative objects.
- Plastic:Food-grade polymers and recycled content blends face tightening restrictions under China's GB standards and California Proposition 65. Bioplastic alternatives gain trial in Scandinavian markets with aggressive circularity mandates.
Wood captures the highest value per kilogram while recycled-content plastic climbs fastest on regulatory pressure.
Distribution Channel:
Customer type and purchase occasion determine channel selection, with bulk institutional procurement diverging sharply from individual household decision-making.
- Online Retail:AR visualization tools and last-mile logistics for bulky goods have unlocked furniture categories previously requiring physical inspection. Wayfair-type platforms in the US and Zolando equivalents in Europe now capture one-third of millennial homeware spending.
- Offline Retail:Tactile evaluation remains essential for upholstery comfort and textile hand-feel. IKEA's warehouse format and Williams-Sonoma's culinary lifestyle showrooms represent divergent experiential strategies.
- Wholesale:Hotel and restaurant supply contracts run on 12-24 month frameworks with specification-driven procurement. Middlemen aggregate fragmented manufacturer output for institutional buyers lacking direct sourcing bandwidth.
- Direct Sales:Subscription furnishing operators like Feather bypass retail markup by owning inventory and capturing lifetime customer value through turnover rather than margin per unit.
Offline retail retains the transaction volume base while direct sales models expand most quickly among urban renters.
End User:
Application environment dictates durability specifications, with commercial settings demanding fire-rated textiles and institutional procurement requiring anti-microbial surface treatments absent from residential grades.
- Households:Fragmentation across rental, ownership, and hybrid living arrangements forces manufacturers to modularize product lines. Indian urban household formation in Tier-2 cities is outpacing organized retail presence.
- Hospitality:Hotel renovation cycles and Airbnb operator outfitting drive demand for commercial-grade durability at mid-market price points. Dubai and Singapore hotel development pipelines concentrate procurement volume.
- Corporates:Hybrid work policies have collapsed the distinction between residential and office furniture, with Herman Miller-type ergonomic specialization commanding specification-driven procurement for home-office crossover.
- Institutions:Schools, healthcare facilities, and government procurement run on extended tender timelines with strict domestic content requirements in India and the US.
Households anchor the volume base while hospitality gains share at the steepest rate on post-pandemic travel recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for furniture manufacturing is redirecting foreign direct investment toward domestic engineered wood and metal component capacity. Germany's REACH enforcement timeline is accelerating certified alternative sourcing for textile suppliers. China's SAMR updates on GB standards are disqualifying legacy finishes from export eligibility.
United States
Millennial household formation in Texas and Florida is outpacing national averages, driving modular furniture demand for rental-to-ownership transitions. EPA formaldehyde emission rules for composite wood products mandate third-party certification for kitchen cabinetry and children's furniture segments. North Carolina's Piedmont Triad hosts concentrated upholstery manufacturing clusters serving direct-to-consumer platforms.
Germany
EU Green Deal circularity requirements are incentivizing design-for-disassembly in furniture manufacturing ahead of extended producer responsibility implementation. ECHA's REACH restrictions on phthalates and heavy metals redirect textile supply chains toward OEKO-TEX certified alternatives. North Rhine-Westphalia's Ruhr Valley retains engineered wood processing infrastructure now retrofitting for low-emitting resin systems.
China
Urban household formation in Chengdu and Hangzhou is sustaining demand for flat-pack furniture optimized for high-mobility renters. SAMR's updated GB standards for indoor air quality are pressuring exporters to reformulate finishes and adhesives for US and European market access. Guangdong Province's Pearl River Delta maintains concentration of knock-down furniture assembly for IKEA-type logistics architectures.
India
Tier-2 city household formation in Ahmedabad and Pune is outpacing organized retail presence, creating whitespace for localized production partnerships. PLI scheme incentives for furniture manufacturing are drawing capital toward domestic engineered wood and metal component capacity. Gujarat's Sanand industrial corridor is emerging as a hub for flat-pack furniture assembly targeting Middle East export markets.
Brazil
Social media-driven decor demand in São Paulo and Rio de Janeiro is compressing design-to-shelf timelines for seasonal assortment refreshes. ANVISA's evolving standards for food-contact materials shape kitchenware import specifications. Minas Gerais' Uberlândia cluster hosts metal furniture frame production serving domestic wholesale distribution networks.
Global Homeware Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin architectures. Flat-pack logistics operators and direct-to-consumer platforms now capture one-third of millennial homeware spending in developed markets. Three archetypes dominate: scale-driven mass-market retailers with captive supply chains, premium lifestyle brands with culinary or ergonomic specialization, and asset-light subscription operators. Consolidation pressure is intensifying through vertical integration into component manufacturing and cross-border e-commerce platform acquisitions.
Among scale-driven mass-market retailers, IKEA exemplifies flat-pack logistics architecture with container density optimization. Williams-Sonoma occupies a position within the premium lifestyle tier, anchoring direct-to-consumer channel control in kitchenware. Herman Miller sits within the ergonomic specialization segment, commanding specification-driven procurement for corporate and home-office crossover applications. These three entities represent divergent strategic responses to millennial demand fragmentation across rental, ownership, and hybrid living arrangements.
| Leading Market Players |
|---|
| Ashley Furniture Industries |
| Herman Miller |
| IKEA |
| Natuzzi |
| La-Z-Boy |
| Wayfair |
| Steelcase |
| Roche Bobois |
| Williams-Sonoma |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into landed cost spreads between flat-pack furniture imports and regional manufacturing alternatives, compressing margins for distributors unable to hedge freight exposure while amplifying price differentiation between certified low-emitting and standard-grade engineered wood products.
Pricing Analysis
Certification level under EPA formaldehyde rules and EU REACH timber regulations creates the primary spread between premium and standard tiers in furniture and kitchenware. Pricing stratifies across certified low-emitting, third-party verified, and uncertified grades, with millennial renters in coastal metros showing lowest price sensitivity for subscription furnishing models while Tier-2 Indian households drive volume at economy tiers. Cost compression in mid-tier engineered wood furniture is intensifying because resin input costs fluctuate with petrochemical feedstock markets.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for knock-down furniture exporters serving North American markets. Manufacturing concentrates in China's Guangdong Province, India's Gujarat corridor, and Vietnam's Binh Duong province, with engineered wood resins, stainless steel grades 304 and 316, and low-emitting adhesive formulations anchoring raw material dependencies. Distribution runs through direct-to-consumer platforms, IKEA-type warehouse formats, and wholesale hotel supply networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded expertise in flat-pack logistics architecture and direct-to-consumer platform operations represents the scarcest capability set, separating incumbents with captive supply chains from digital-native challengers attempting to replicate fulfillment density without decades of network investment.
For Market Incumbents: Harden compliance documentation systems against multi-jurisdictional certification timelines spanning EPA formaldehyde rules, REACH chemical restrictions, and China's evolving GB standards. Deepen backward integration into engineered wood processing and low-emitting resin formulation to defend margin position against volatile petrochemical input costs. Prioritize channel control through AR visualization tool deployment and last-mile logistics ownership for bulky goods fulfillment. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-2 urban markets where household formation outpaces organized retail presence and domestic PLI scheme incentives reduce import dependence for metal components and engineered wood. Target subscription furnishing models for high-mobility millennial renters in coastal metros, leveraging asset-light inventory ownership against legacy manufacturers' balance-sheet constraints. Deploy AR configurators as the primary go-to-market angle to compress consideration-to-purchase cycles without physical showroom investment. For Investors and Strategic Acquirers: EU Green Deal extended producer responsibility implementation reshapes the acquisition landscape toward design-for-disassembly capabilities and material recovery systems. Long-term viability centers on platforms with embedded circularity infrastructure and certified alternative material libraries validated across REACH, EPA, and GB standard jurisdictions. Monitor SAMR enforcement actions on Chinese export eligibility as the signal to watch for supply chain reconfiguration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Flat-Pack Logistics Optimization | Container density gains through knock-down assembly lower landed costs for direct-to-consumer bulky goods fulfillment. |
| Certified Material Library Investment | Pre-validated alternatives to phthalates and heavy metals accelerate REACH compliance and protect European market access. |
| AR Visualization Platform Deployment | Virtual showroom experiences reduce return rates for furniture and compress millennial purchase consideration cycles. |
| Subscription Furnishing Model Launch | Asset-light inventory turnover captures lifetime customer value without capital-intensive retail footprint expansion. |
| India PLI Scheme Partnership | Domestic engineered wood and metal component capacity reduces import dependence and targets Middle East export markets. |
Methodological Framework
Cross-validation between customs trade data and direct-to-consumer platform transaction records anchors the qualitative findings from primary interviews with flat-pack logistics directors, engineered wood mill procurement leads, hospitality furnishing buyers, and AR platform product managers. Secondary sources include EPA certification databases, ECHA REACH registration dossiers, SAMR GB standard updates, and India PLI scheme disbursement filings. Bottom-up demand modeling across product type, material grade, distribution channel, and end-user segments triangulates against top-down trade flow analysis.
Calibration against historical volume trajectories and regulatory implementation timelines shapes the analytical framework across the analysis window. Segmentation dimensions encompass furniture construction method, kitchenware thermal performance tier, textile certification grade, and decor trend velocity. CAGRs derive from fitted growth curves adjusted for millennial household formation patterns and renovation cycle intensities. Forecast inputs incorporate resin price indices, container freight rate movements, and certification timeline compression effects.
Sensitivities concentrate around SAMR enforcement intensity on Chinese export eligibility, REACH restriction expansion to additional chemical classes, and secondhand marketplace penetration among younger cohorts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Flush Door Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Pillow Market
Homecare and Decor
Bamboo Panels Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Home Decor Market
Homecare and Decor
India Wallpapers Market