
 Europe Commercial Blinds and Shades Market | 2026-2036
Europe Commercial Blinds and Shades Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Blinds and Shades Market Foresight
Germany is reconfiguring supply dynamics for commercial shading across Northern Europe through expanded manufacturing of precision-engineered motorized systems. WAREMA Renkhoff SE leverages its domestic production base to sustain specification relationships with major office developers. Hunter Douglas competes through R&D intensity in daylight optimization technologies. SERVIS CLIMAX, a.s. anchors Central European distribution with vertically integrated aluminum extrusion capabilities.
Commercial blinds and shades encompass adjustable solar screening devices fabricated from fabric, vinyl, wood, or aluminum slats, engineered to modulate visible light transmission, thermal gain, and glare indices within built environments. These systems integrate manual chain drives, spring mechanisms, or electric motors operating at 24–230V to achieve programmed louver positions, with primary commercial purpose centered on energy load reduction and visual comfort compliance in occupied spaces. Roller blinds dominate volume specifications across European office portfolios due to streamlined installation and minimal facade intrusion, while motorized installations capture expanding margin pools as building management system integration becomes standard in premium developments. Cellular shades represent the fastest-growing material-form configuration, buoyed by insulating air-pocket geometries that satisfy stringent national energy codes.
The EU Green Deal, REACH chemical compliance for coated textiles, and CE marking under the Construction Products Regulation collectively mandate flame-retardant substrates, restricted substance thresholds, and declared thermal performance metrics for commercial shading. ECHA scrutiny of per- and polyfluoroalkyl substances in water-repellent fabric treatments is redirecting manufacturer formulation strategies toward silicone-based alternatives. Stakeholders must monitor how the EU AI Act and evolving smart-building interoperability standards reshape procurement criteria for connected shading systems.
Market Dynamics
The EU Green Deal's tightening thermal performance mandates are forcing commercial property owners to replace static glazing with responsive shading systems, compressing specification cycles and elevating motorized retrofits from amenity to compliance necessity.
Growth Catalysts
- Energy Performance of Buildings Directive:The revised EPBD mandates automated solar control in large commercial renovations across EU member states, creating immediate specification pull for motorized roller systems.
- Hospitality refurbishment waves:Hotel operators in Spain and Italy are installing integrated shading to meet LEED and BREEAM certification thresholds for premium positioning.
- Cellular shade geometries:Honeycomb air-pocket designs deliver R-value improvements that satisfy German EnEV and comparable national codes, accelerating material substitution.
Market Restraints
- Aluminum extrusion supply concentration:Precision rail and headrail sourcing clusters in Central European foundries, exposing fabricators to energy cost pass-through volatility.
- PFAS formulation transition:ECHA restrictions on per- and polyfluoroalkyl substances in water-repellent textile coatings force silicone-based alternative validation, extending product development timelines.
- Static glazing substitution threat:Electrochromic and thermochromic smart glass advances in Nordic pilot projects threaten to bypass external shading entirely in premium new construction.
Strategic Opportunities
- Polish and Romanian office stock:Underpenetrated Class B and C commercial buildings in these markets present retrofit volume as EU cohesion funds flow toward energy efficiency.
- Building management system convergence:BACnet and KNX protocol integration positions shading vendors as IoT infrastructure participants rather than component suppliers.
- France's RE2020 environmental regulation:The thermal performance threshold escalation creates mandated demand for high-performance cellular and pleated configurations in new commercial construction.
Industry Challenges
- Façade engineer scarcity:Specialized commissioning expertise for motorized system integration with HVAC controls remains concentrated in German and Dutch technical consultancies, constraining project velocity elsewhere.
- CE marking documentation burden:Construction Products Regulation compliance requires third-party thermal performance declaration for each fabric and hardware combination, fragmenting SKU economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Blinds and Shades Market |
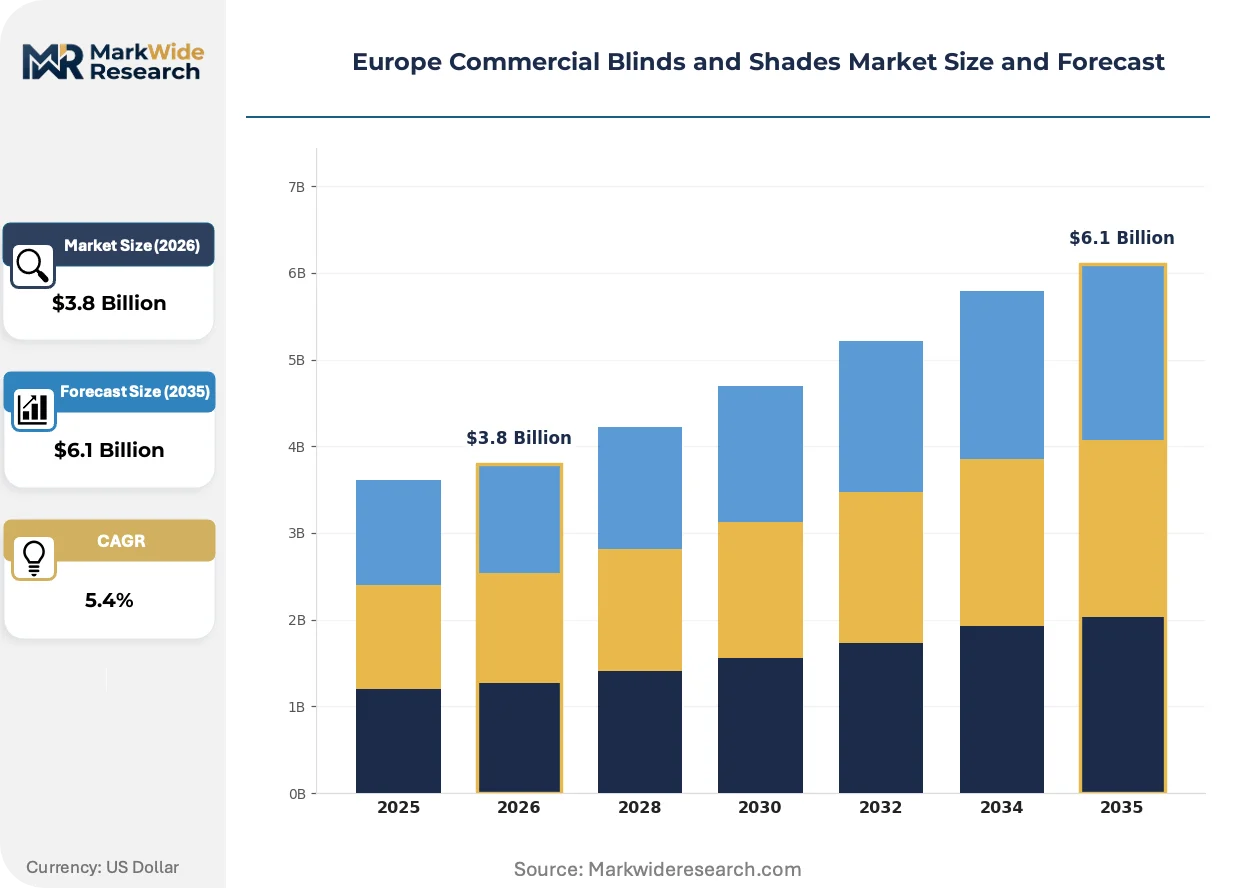
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Blinds, Venetian Blinds, Roman Shades, Cellular Shades Material: Fabric, Vinyl, Wood, Aluminum End User: Offices, Hotels, Retail Stores, Educational Institutions Installation Type: Window Mounted, Ceiling Mounted, Wall Mounted, Motorized |
| Companies Covered | Griesser AG, Advanced Window Blinds Ltd, Hunter Douglas, SERVIS CLIMAX, a.s., Alulux GmbH, WAREMA Renkhoff SE, Hillarys, ALL BLINDS CO., LTD., John Lewis plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Blinds and Shades Market Shifts & Advancements
Connected shading architecture is collapsing the boundary between building envelope and energy management infrastructure. Three concurrent developments are compressing specification logic and redrawing competitive boundaries.
Photovoltaic-integrated blind systems are collapsing the distinction between solar screening and on-site generation. These dual-function units embed thin-film cells on slat or roller surfaces, delivering 80-120 W per square meter of glazed area. Dutch and Danish commercial developers are piloting installations in net-zero office targets, forcing traditional shading vendors to partner with PV specialists or cede premium specification.
REACH chemical compliance is redirecting coating chemistry across the supply base. ECHA's expanded PFAS restriction proposals are accelerating silicone and bio-based water-repellent formulation shifts, with textile finishers in Portugal and northern Italy retooling finishing lines ahead of enforcement windows. Fabric suppliers with validated alternative chemistries are capturing specification preference from lagging competitors.
Outcome-based energy performance contracting is altering procurement authority. Facility management providers and energy service companies are assuming shading specification decisions from architects, prioritizing guaranteed thermal load reduction over aesthetic compliance. This shift concentrates vendor relationships in Germany and the Netherlands, where ESCO market structure is most developed.
Europe Commercial Blinds and Shades Market Segmentation
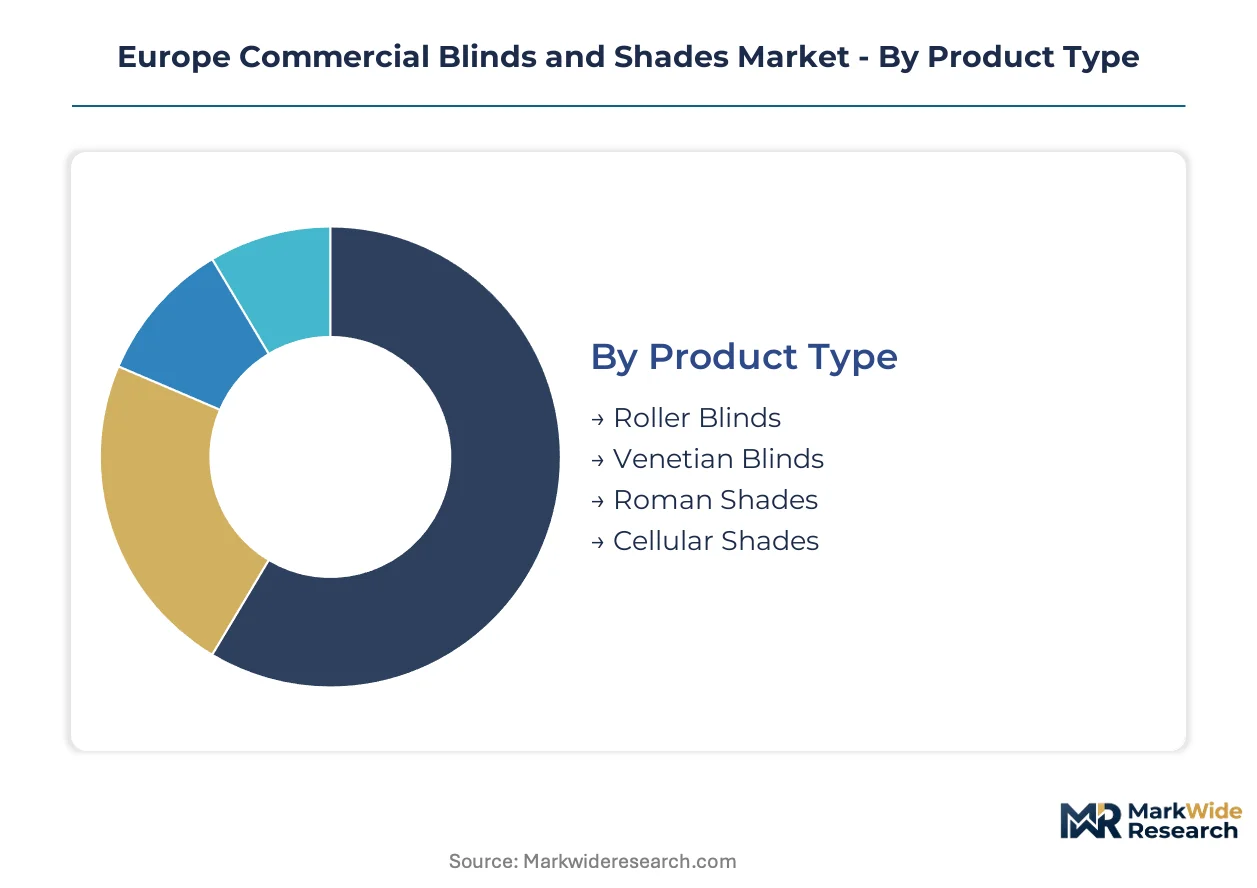
Segmentation in commercial shading reveals how specification authority splits between energy compliance mandates and aesthetic procurement. Product geometry and material chemistry determine thermal performance certification, while installation topology governs integration complexity with building management infrastructure.
Product Type:
Cost tier stratification in commercial portfolios separates standardized retrofits from premium new-build specifications, with geometry-driven thermal performance as the primary price delimiter.
- Roller Blinds:Fabric or vinyl sheets wound onto aluminum barrels, specified in 300-400mm drop increments for standard office modules. German and Dutch office refurbishment cycles concentrate volume here, driven by EPBD compliance deadlines that favor rapid-install solutions over complex alternatives.
- Cellular Shades:Honeycomb-structured fabric layers trap air in hexagonal cells, delivering R-value improvements that satisfy French RE2020 and German EnEV thresholds. Hospitality operators in Spain and Italy specify these for LEED positioning, accepting premium positioning for measurable load reduction.
- Venetian Blinds:Horizontal aluminum or wood slats tilt via wand or motor control, offering precise glare management for workstations. Slat width (25mm, 50mm) differentiates price positioning.
- Roman Shades:Soft-fold fabric panels stack evenly when raised, specified in boutique hospitality and heritage office conversions where visual warmth overrides pure efficiency metrics.
Roller blinds hold installed capacity across Northern European office stock. Cellular shades are rotating up the share rankings as national energy codes tighten thermal performance minimums.
Material:
Application context dictates material selection, with fire safety certification and facade exposure severity filtering viable options for each end-use environment.
- Fabric:Woven polyester, fiberglass, or natural fiber substrates carry flame-retardant coatings meeting BS 5867 and EN 13501-1 classifications. REACH-compliant silicone water-repellent finishes are displacing legacy PFAS treatments across Portuguese and Italian textile mills.
- Aluminum:Extruded slats and headrails from Central European foundries offer durability in high-cycle commercial environments. Energy cost pass-through volatility in Czech and Polish smelters is compressing fabricator margins.
- Vinyl:PVC-based films deliver moisture resistance for healthcare and food-service adjacencies, though plasticizer migration concerns under REACH scrutiny are redirecting specification toward coated fabric alternatives.
- Wood:FSC-certified hardwood slats serve premium hospitality and executive office segments where tactile warmth supports brand positioning, despite higher maintenance burden and dimensional instability in humid climates.
Fabric commands specification volume across climate zones requiring breathable, lightweight screening. Aluminum is climbing fastest in motorized system integration where structural rigidity enables precise louver positioning.
End User:
Customer type segmentation tracks how procurement authority varies across asset classes, from facilities-managed office portfolios to owner-operated hospitality.
- Offices:Corporate real estate and multi-tenant buildings specify motorized roller systems with BACnet integration, prioritizing energy load reduction metrics over aesthetic differentiation. German Class A stock leads retrofit intensity.
- Hotels:Brand-standard compliance drives specification of blackout-compatible cellular shades in guest rooms and automated screening in public areas. Spanish and Italian premium positioning accelerates BREEAM-targeted procurement.
- Retail Stores:Visual merchandising requirements favor sheer or perforated fabrics that balance product visibility with UV protection for displayed goods.
- Educational Institutions:Public procurement frameworks in France and Italy emphasize lifecycle cost and fire safety certification over smart-building integration.
Offices hold installed capacity from decades of commercial construction. Hotels are gaining share fastest as refurbishment waves concentrate specification pull in Southern European markets.
Installation Type:
Volume distribution across mounting topologies reflects the retrofit-versus-new-build split in European commercial construction activity.
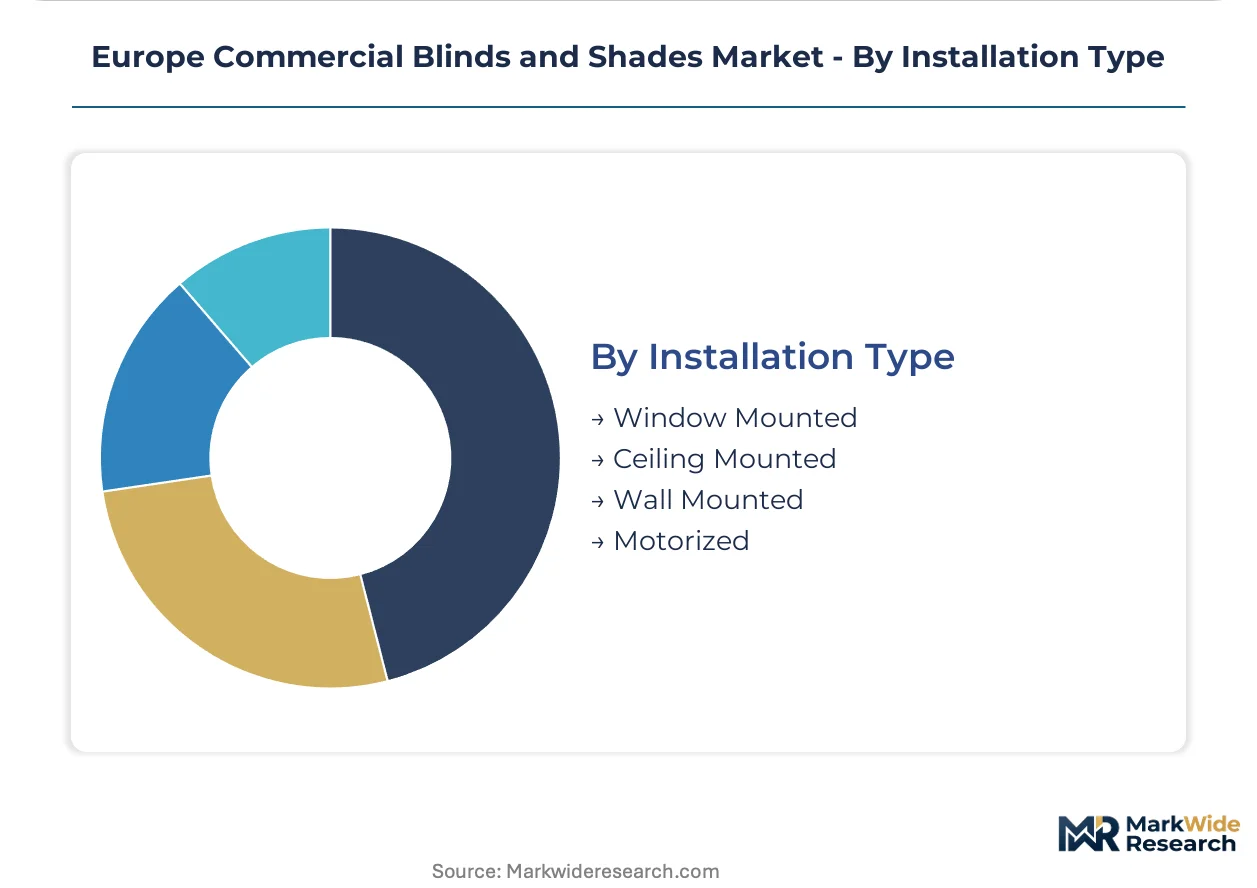
- Motorized:24-230V electric drives with programmable positioning integrate via KNX or BACnet protocols into building management systems. German and Dutch ESCO market structure concentrates specification authority for outcome-based energy contracts.
- Window Mounted:Bracket systems affixing to frame reveals dominate retrofit applications where minimal facade intrusion preserves glazing warranties.
- Ceiling Mounted:Recessed headrails in suspended ceiling systems serve open-plan offices requiring clean sightlines.
- Wall Mounted:Surface-applied brackets accommodate irregular facade conditions in heritage building conversions.
Window mounted retains capacity from legacy stock prevalence. Motorized systems are climbing fastest as EPBD mandates and ESCO contracting reshape procurement logic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors demand dynamics across the region, with national transpositions of the Energy Performance of Buildings Directive creating staggered compliance waves from 2026 through 2035. Motorized shading specification concentrates in markets with mature ESCO infrastructure and aggressive thermal retrofit mandates.
Germany
Class A office refurbishment cycles and EnEV thermal thresholds drive motorized roller system demand. The federal government's Building Energy Act tightens facade performance requirements for commercial renovations. Munich and Frankfurt development clusters concentrate specification authority with major facility management providers.
France
RE2020 environmental regulation escalates thermal performance minimums for new commercial construction. The country's national building code mandates automated solar control in buildings exceeding specific energy consumption thresholds. The Île-de-France region anchors specification volume through Paris office development and heritage conversion projects.
Netherlands
Outcome-based energy performance contracting and mature ESCO market structure reshape procurement authority away from architects. The national building code transposes EPBD requirements with accelerated timelines for large commercial stock. Rotterdam and Amsterdam harbor districts concentrate pilot deployments of photovoltaic-integrated screening systems.
Spain
Hospitality refurbishment waves concentrate demand for blackout-compatible cellular shades and automated public-area screening. LEED and BREEAM certification thresholds drive premium positioning in Madrid and Barcelona hotel markets. The country's national energy efficiency fund channels cohesion resources toward thermal retrofit subsidies.
Poland
Underpenetrated Class B and C commercial stock presents retrofit volume as EU cohesion funds flow toward building energy efficiency. The national transposition of EPBD requirements lags Western counterparts, compressing specification timelines for compliance-driven upgrades. Warsaw and Kraków development corridors concentrate early motorized system adoption.
Europe Commercial Blinds and Shades Market Competitive Landscape
Precision-engineered domestic manufacturers and vertically integrated Central European fabricators split the market across performance tiers. Consolidation pressure concentrates around building management system integration capabilities and REACH-compliant textile supply chains. Three archetypes dominate: German precision-engineering specialists, Central European aluminum-integrated producers, and daylight-optimization technology developers. Competitive moves center on backward integration into aluminum extrusion and strategic partnerships with photovoltaic cell suppliers.
Among German-based precision manufacturers, WAREMA Renkhoff SE and Griesser AG exemplify the domestic-engineering archetype, while SERVIS CLIMAX, a.s. represents the Central European vertically integrated position. Hunter Douglas occupies a position within the daylight-optimization technology tier, reflecting R&D-intensive competitive positioning.
| Leading Market Players |
|---|
| Griesser AG |
| Advanced Window Blinds Ltd |
| Hunter Douglas |
| SERVIS CLIMAX, a.s. |
| Alulux GmbH |
| WAREMA Renkhoff SE |
| Hillarys |
| ALL BLINDS CO., LTD. |
| John Lewis plc |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's energy cost pass-through volatility shapes both aluminum extrusion pricing power and downstream tier differentiation for motorized shading systems across Northern Europe.
Pricing Analysis
Geographic price spreads between German precision-engineered systems and Central European fabricator offerings compress as REACH-compliant silicone coating validation extends development timelines. Three-tier pricing structure across premium, standard, and economy levels separates BACnet-integrated motorized installations from manual retrofits and basic cellular configurations. Pricing pressure stems from electrochromic smart glass pilot deployments in Nordic markets threatening to bypass external shading in premium new construction. Class B and C office retrofit buyers exhibit highest price sensitivity, while hospitality operators pursuing LEED certification show lowest.
Supply Chain Analysis
Dual-use export controls on precision motor drives and smart-building control modules constrain component flows from non-EU sources, concentrating sourcing relationships with domestic engineering specialists. Manufacturing gravity centers on Germany, Czech Republic, and Poland for aluminum extrusion and motorized assembly, with Portuguese and Italian textile mills supplying REACH-compliant coated fabrics. Raw material dependencies include aluminum billet from Central European smelters, polyester yarn from regional petrochemical complexes, and copper windings for electric drives. Single-source vulnerability in precision rail extrusion exposes fabricators to energy cost volatility. Distribution runs through facility management providers and ESCO contractors rather than traditional architectural specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Commercial Blinds and Shades Market sits in early-cycle expansion as EPBD mandate transpositions accelerate motorized retrofit penetration from compliance necessity rather than amenity positioning.
For Market Incumbents: Insulate specification relationships by deepening backward integration into aluminum extrusion and REACH-compliant textile finishing. Secure captive supply of precision-engineered motorized drives before dual-use export controls tighten. Prioritize BACnet and KNX protocol certification investment to maintain building management system integration positioning against daylight-optimization technology developers.
For New Entrants and Emerging Players: Polish Class B and C commercial stock offers immediate retrofit volume as EU cohesion funds channel toward building energy efficiency. Target hospitality refurbishment waves in Spain and Italy where blackout-compatible cellular shade demand outpaces established supply relationships. Enter through ESCO partnership structures rather than architectural specification channels to bypass incumbent specification lock-in.
For Investors and Strategic Acquirers: Precision-engineering specialists with validated silicone-based water-repellent chemistries and KNX integration capabilities represent the priority acquisition archetype. Long-term viability hinges on photovoltaic-integrated screening system partnerships or in-house thin-film cell development. Monitor Nordic electrochromic smart glass pilot project conversion rates as inflection signal for external shading substitution threat intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of precision rails insulates margin from Czech and Polish smelter energy volatility. |
| Photovoltaic Cell Partnership | Thin-film integration positions vendors for Dutch and Danish net-zero office pilot specifications. |
| Silicone Coating Validation | REACH-compliant chemistry capture accelerates specification preference as ECHA PFAS restrictions enforce. |
| ESCO Channel Development | Outcome-based contracting relationships in Germany and Netherlands concentrate procurement authority shift. |
| KNX Protocol Certification | Building management system integration secures premium positioning in RE2020-compliant French new construction. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Construction Products Regulation filings, ECHA chemical restriction proposals, and national EPBD transposition documents across member states. Primary interviews engaged facade engineers, facility management procurement directors, ESCO contract specialists, and textile finishing plant managers. Secondary validation drew from CE marking databases, REACH compliance registries, and commercial construction permit records. Bottom-up volume estimates triangulated against top-down energy efficiency retrofit spending projections.
Forecast inputs span product geometry, material chemistry certification tier, installation topology, and end-use asset class across the analysis window. Segmentation modeling captures roller, cellular, venetian, and roman configurations; fabric, aluminum, vinyl, and wood substrates; office, hospitality, retail, and educational demand; plus motorized versus manual installation split. CAGRs derived from penetration rate assumptions tied to EPBD compliance deadline phasing and national thermal regulation escalation trajectories. Motorized system integration rates and smart glass substitution risk probability weighted scenario outputs.
Practitioners should monitor ECHA PFAS restriction enforcement timing, Nordic electrochromic glass pilot conversion rates, and EU cohesion fund disbursement velocity for early signals of forecast revision. Cross-checking against national building energy efficiency spending disclosures and ESCO contract announcement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
Pillow Market