
 Decorations and Inclusions Market | 2026-2036
Decorations and Inclusions Market Size, Share, and Industry Trends Forecast 2026-2036
Decorations and Inclusions Market Outlook
Aftermarket customization revenue is reshaping how suppliers capture value beyond commodity sales. Barry Callebaut leverages its cocoa processing scale to dominate premium chocolate inclusion supply. Kerry Group anchors its position through integrated flavor and texture systems for industrial bakeries. Cargill Incorporated competes on global agricultural sourcing, securing cost advantages in nut and seed-based inclusions.
Decorations and inclusions encompass ornamental and functional additives—ranging from tempered chocolate shards and candied fruit pieces to metallic leaf and crystallized elements—incorporated into finished goods at 0.5-15% inclusion rates by weight to enhance visual appeal, mouthfeel, or structural integrity. Glass and metal materials command premium positioning in jewelry and event applications where refractive properties and durability justify higher unit economics, while wood and ceramics sustain steady artisan craft demand through tactile warmth and hand-finish compatibility. Interior design applications lead volume through architectural surface treatments and fixture embellishments, whereas jewelry making captures disproportionate margin pools through precious metal and gemstone inclusions.
The EU's REACH framework and ECHA substance restrictions constrain cadmium and lead content in decorative metals, redirecting formulation toward compliant alloys and synthetic alternatives. FDA food-contact regulations govern edible inclusion safety, requiring supplier documentation of GRAS status and allergen controls for cross-contamination prevention. Stakeholders must monitor evolving chemical disclosure mandates across multiple jurisdictions to preempt supply chain disruption and secure preferential shelf placement with compliance-forward retailers.
Market Dynamics
REACH substance restrictions and ECHA cadmium limits are forcing reformulation across decorative metal supply chains, redirecting procurement toward compliant alloys and synthetic alternatives while compressing margins for legacy suppliers.
Growth Catalysts
- Artisan craft resurgence:Germany, Italy, and France sustain elevated demand for hand-finished wood and ceramic inclusions in premium bakery and confectionery segments.
- Edible decoration premiumization:Tempered chocolate shards and crystallized fruit pieces at 5-15% inclusion rates command price premiums in industrial bakery applications.
- REACH compliance innovation:ECHA substance restrictions on heavy metals accelerate development of compliant decorative alloys and synthetic metallic leaf alternatives.
Market Restraints
- Cocoa butter price volatility:Tempered chocolate inclusion costs fluctuate with West African supply disruptions and weather events.
- Decorative metal supply concentration:Cadmium-free alloy production clusters in German and Italian foundries, creating geographic dependency.
- Technical limitation in synthetic alternatives:Polymer-based metallic leaf lacks refractive properties of traditional metal leaf in jewelry applications.
Strategic Opportunities
- Underpenetrated US artisan segment:FDA GRAS documentation gaps block European edible decoration suppliers from specialty bakery channels.
- Regulatory tailwind from EU Green Deal:Biodegradable packaging mandates for confectionery create demand for compostable decoration substrates.
- Technology convergence:Digital printing on edible substrates merges with traditional candied fruit production for customized bakery applications.
Industry Challenges
- Cross-contamination control:Allergen management in shared nut and seed-based inclusion processing lines demands capital-intensive facility segregation.
- Certification timeline compression:FDA food-contact notifications and GRAS self-determinations require 18-24 month documentation cycles for novel edible materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorations and Inclusions Market |
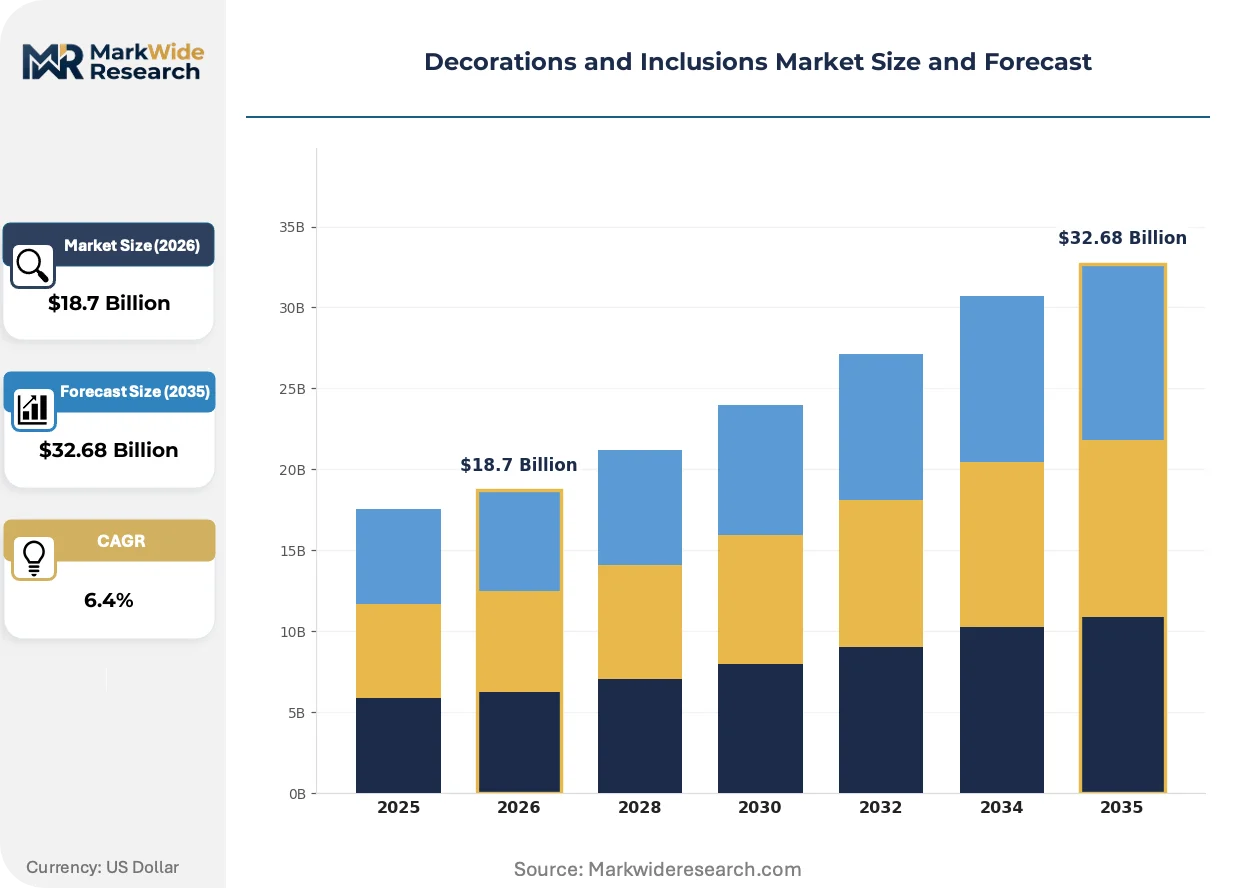
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Stones, Gemstones, Beads, Shells Material: Glass, Metal, Wood, Ceramics Application: Interior Design, Jewelry Making, Crafts, Events Customer Type: Retailers, Artisans, Event Planners, Wholesalers |
| Companies Covered | Dawn Foods, Dobla, Barry Callebaut, Kanegrade, Delicia, Cargill Incorporated, Orchard Valley Foods, Mavalerio USA, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorations and Inclusions Market Strategic Shifts
Digital design tools and sustainable material science are converging to reshape how decorations and inclusions are specified, produced, and integrated across food and non-food applications.
Edible inkjet printing technology is virtualizing traditional hand-piped decoration methods in industrial bakeries. Large-scale manufacturers in the Netherlands and Belgium adopt these systems for mass-customized cake and pastry surfaces. The technology is virtualizing the role of skilled pastry labor while compressing production cycle times from hours to minutes.
EU F-Gas Regulation phase-down mandates are accelerating cold-chain energy audits for temperature-sensitive chocolate inclusion storage. Industrial bakeries face retrofit obligations for refrigeration systems using restricted hydrofluorocarbons. German and Austrian facilities lead compliance adoption, redirecting capex toward ammonia-based and transcritical CO2 systems.
Specification behavior among artisan craft buyers is fragmenting toward direct-to-maker procurement platforms. Etsy and specialized B2B marketplaces displace traditional wholesale distributors for small-batch metallic leaf and crystallized elements. This channel shift concentrates in French and Italian jewelry-making clusters where maker-provenance commands premium positioning.
Decorations and Inclusions Market Segmentation
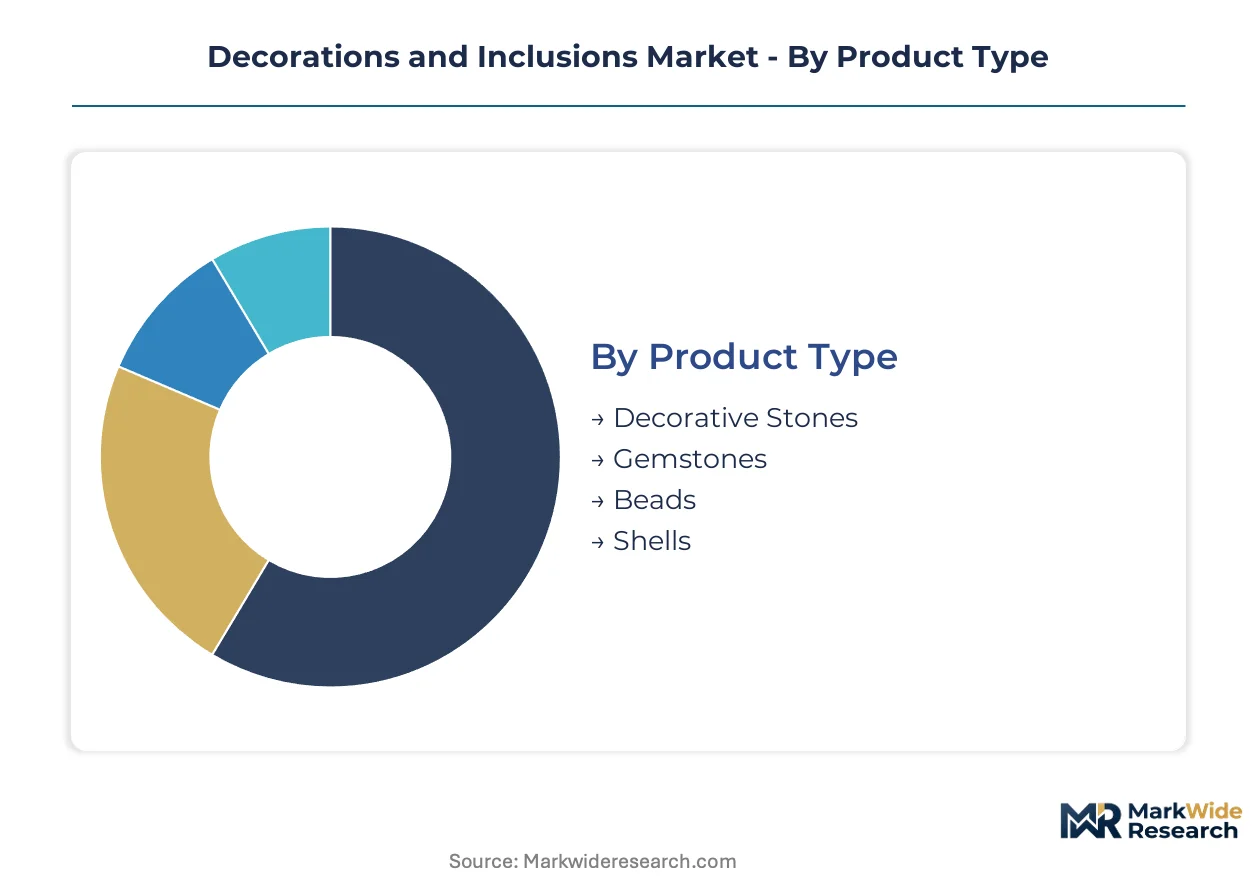
Segmentation in the Decorations and Inclusions Market reveals divergent value capture strategies across material science maturity and end-use sophistication. Product type and material categories separate commodity volume plays from premium margin pools, while application and customer dimensions expose channel fragmentation reshaping procurement patterns.
Product Type:
Mature ornamental categories coexist with emerging specialty segments as artisan craft demand evolves toward provenance-driven purchasing.
- Decorative Stones:Polished semi-precious and mineral specimens serve architectural surface treatments and event staging applications. German interior design studios and Italian furniture makers concentrate procurement for terrazzo and resin-inlay installations.
- Gemstones:Precious and semi-precious cut stones command premium positioning in jewelry inclusions where refractive properties justify unit economics. French and Swiss jewelry clusters in Paris and Geneva sustain elevated demand for calibrated melee and fancy cuts.
- Beads:Uniform drilled elements enable mass production in costume jewelry and textile embellishment.
- Shells:Natural calcium structures serve coastal-themed interior accents and sustainable craft applications.
Decorative stones handle the majority of throughput; gemstones are gaining share fastest among premium-positioned suppliers.
Material:
Cost tier stratification separates industrial-scale inputs from hand-finish-compatible substrates requiring skilled labor integration.
- Glass:Lead-free crystal and borosilicate formulations deliver refractive performance for chandelier components and luxury packaging inclusions. Venetian Murano workshops and Czech Bohemian foundries anchor European supply concentration.
- Metal:Cadmium-free alloys and precious metals comply with ECHA REACH restrictions while serving jewelry and architectural fixture applications. German foundries in Pforzheim and Italian metalworking clusters dominate compliant alloy production.
- Wood:Sustainably harvested hardwoods and veneers support tactile warmth in artisan furniture and craft segments.
- Ceramics:Fired clay bodies enable hand-painted surface decoration and structural inclusions.
Metal commands the highest value per kilogram; glass sustains the broadest cross-application penetration.
Application:
Volume concentration in commercial interiors contrasts with margin concentration in bespoke jewelry and event applications.
- Interior Design:Architectural surface treatments, fixture embellishments, and spatial installations drive bulk consumption. Dutch and Belgian design studios specify decorative inclusions for hospitality and retail environments.
- Jewelry Making:Precious metal and gemstone integration captures disproportionate margin pools through maker-provenance positioning. French Place Vendôme and Italian Vicenza clusters sustain atelier-scale demand.
- Crafts:Small-batch artisan production emphasizes hand-finish compatibility and material storytelling.
- Events:Temporary installations prioritize visual impact and rapid assembly over durability.
Interior design absorbs the largest absolute volume; jewelry making exhibits the steepest expansion trajectory in value terms.
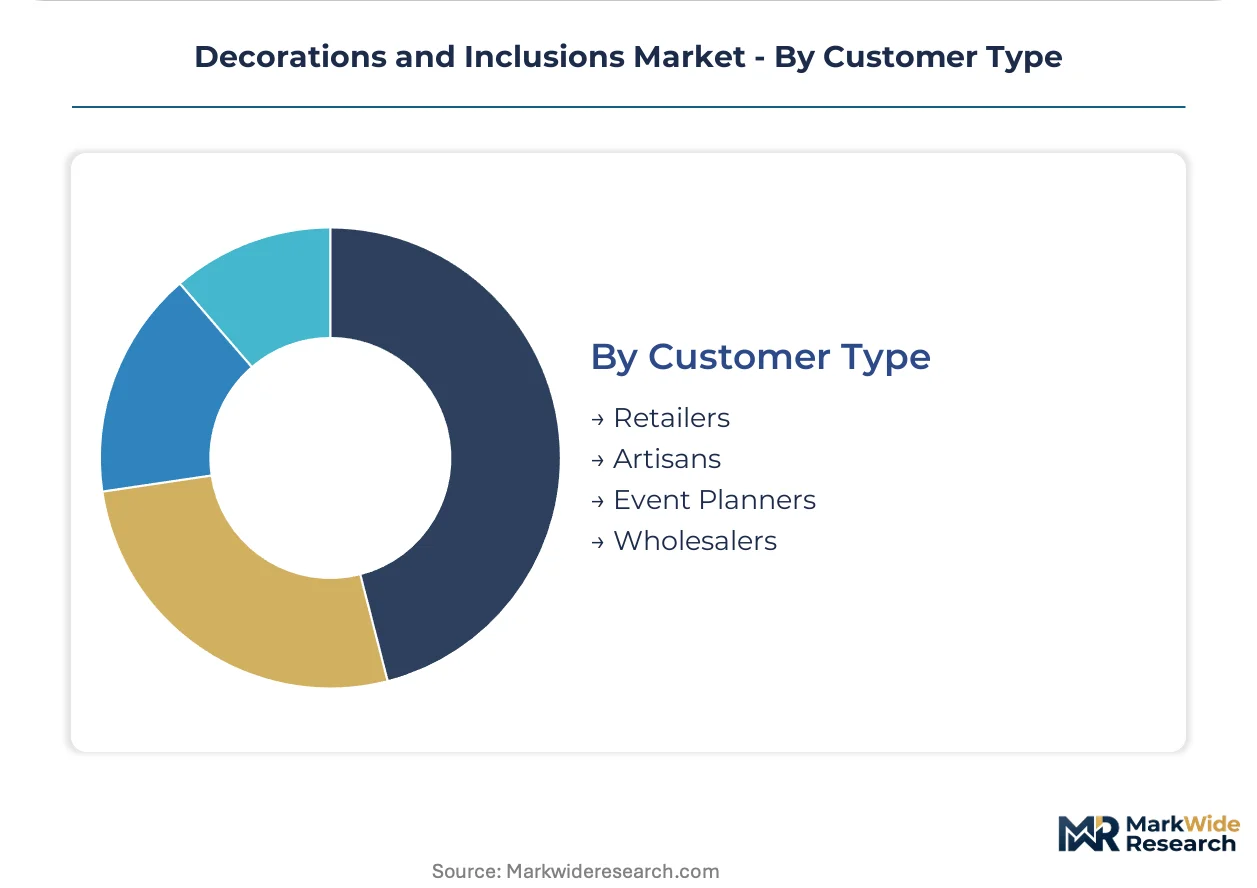
Customer Type:
Procurement authority is fragmenting toward direct-to-maker platforms while wholesale distributors retain industrial-scale accounts.
- Retailers:Branded merchandisers and specialty stores curate finished goods incorporating decorative inclusions. German and UK home décor chains maintain centralized purchasing for seasonal collections.
- Artisans:Independent makers source through Etsy and specialized B2B marketplaces for small-batch metallic leaf and crystallized elements. Italian and French jewelry-making clusters concentrate platform adoption.
- Event Planners:Corporate and wedding specialists procure temporary installations on project-specific timelines.
- Wholesalers:Traditional distributors serve industrial bakeries and confectionery manufacturers with standardized edible inclusion catalogs.
Retailers maintain the largest aggregate order values; artisans are climbing the fastest as a share of emerging supplier revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Italian foundries concentrate cadmium-free alloy production for compliant decorative metals, while Dutch and Belgian industrial bakeries drive edible inclusion adoption through digital printing integration.
Germany
Artisan craft demand for hand-finished wood and ceramic inclusions sustains premium bakery segments. ECHA REACH substance restrictions on heavy metals redirect procurement toward compliant alloys from Pforzheim foundries. Bavarian and Baden-Württemberg clusters anchor metalworking supply for jewelry and architectural fixture applications.
Italy
Murano glass workshops and Vicenza jewelry ateliers command maker-provenance premiums in decorative stones and gemstones. EU F-Gas Regulation phase-down mandates accelerate cold-chain retrofits for chocolate inclusion storage. Lombard and Venetian industrial districts concentrate crystallized element production for artisan procurement platforms.
France
Place Vendôme jewelry houses sustain elevated demand for calibrated precious metal inclusions. ANSM and CNIL oversight intersects with chemical disclosure requirements for consumer-facing decorative products. Parisian and Provence-Alpes-Côte d'Azur design studios specify architectural surface treatments for hospitality environments.
Netherlands
Industrial bakeries adopt edible inkjet printing systems for mass-customized pastry surfaces. EU Green Deal biodegradable packaging mandates create demand for compostable decoration substrates. Dutch design studios concentrate specification authority for retail and hospitality interior installations.
United States
FDA GRAS documentation gaps block European edible decoration suppliers from specialty bakery channels. Cocoa butter price volatility from West African supply disruptions affects tempered chocolate inclusion costs. California and Northeast Corridor artisan clusters drive unmet demand for provenance-tracked metallic leaf and crystallized elements.
Decorations and Inclusions Market Competitive Environment
Ingredient-scale processors and integrated flavor-texture systems split the market between commodity volume and premium formulation tiers. The vendor base concentrates around three strategic archetypes: cocoa-derived inclusion specialists with backward integration into bean sourcing, multi-ingredient platform suppliers bundling flavor and texture systems, and regional artisan-focused distributors curating small-batch catalogs. Dominant competitive moves include capacity expansion in compliant alloy foundries and technology licensing partnerships for digital printing integration.
Within the cocoa-processing tier, Barry Callebaut anchors premium chocolate inclusion supply through scale advantages in bean sourcing and tempering technology. Kerry Group exemplifies the integrated platform archetype, occupying a position across flavor systems and texture engineering for industrial bakery accounts. Cargill Incorporated sits within the agricultural sourcing tier, representing cost-competitive positioning in nut and seed-based inclusion categories through captive supply chain control.
| Leading Market Players |
|---|
| Dawn Foods |
| Dobla |
| Barry Callebaut |
| Kanegrade |
| Delicia |
| Cargill Incorporated |
| Orchard Valley Foods |
| Mavalerio USA |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
Pforzheim foundries and Venetian Murano workshops anchor European decorative metal and glass supply, with their capacity utilization rates directly transmitting into downstream pricing power for jewelry and architectural fixture manufacturers.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across decorative metal categories, separating cadmium-free compliant alloys from legacy formulations facing ECHA enforcement risk. Three-tier pricing structure across certified premium, transitioning standard, and non-compliant economy levels reflects documentation burden and substitution cost differentials. Pricing pressure stems from cocoa butter volatility affecting tempered chocolate inclusions, compressing margins for industrial bakery suppliers. Artisan craft buyers exhibit lowest price sensitivity due to maker-provenance premiums, while mass-market retailers enforce strict cost-down targets.
Supply Chain Analysis
Dual-use export controls on precision glassmaking equipment and advanced metallurgical processes constrain technology transfer to emerging decorative materials producers. Supply concentrates in Germany, Italy, and Belgium for compliant alloys, crystallized elements, and digital printing substrates respectively. Raw material flows draw from West African cocoa butter, sustainably harvested European hardwoods, and borosilicate sand deposits. Single-source vulnerability runs through German foundry concentration for cadmium-free alloys. Distribution runs through direct-to-maker platforms displacing wholesale distributors for artisan segments, while industrial bakeries retain traditional procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edible inkjet printing convergence with traditional candied fruit production creates a high-growth disruption window, accelerated by EU F-Gas Regulation cold-chain retrofit mandates forcing technology adoption decisions.
For Market Incumbents: Insulate premium positioning through backward integration into compliant alloy foundry capacity in Pforzheim and Baden-Württemberg clusters. Secure GRAS self-determination documentation for novel edible substrates before FDA notification timelines extend competitive moats. Channel control through exclusive digital printing technology licensing agreements blocks emerging platform competitors.
For New Entrants and Emerging Players: Pursue underpenetrated US artisan bakery segments where European suppliers face FDA documentation gaps blocking market entry. Target specialty metallic leaf and crystallized element niches in California and Northeast Corridor clusters with provenance-tracked supply storytelling. Direct-to-maker platform presence on Etsy and specialized B2B marketplaces offers lowest customer acquisition cost versus traditional wholesale penetration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated flavor-texture system suppliers with digital printing integration capabilities over commodity ingredient processors. Long-term viability rests on regulatory compliance infrastructure and cold-chain energy efficiency investments as EU Green Deal implementation deepens. Acquisition target archetype: regional artisan distributors with established maker-provenance relationships and compostable substrate certification pipelines. Watch EU biodegradable packaging mandate enforcement timelines as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliant Alloy Foundry Expansion | ECHA REACH enforcement secures premium positioning against legacy cadmium-dependent competitors. |
| Digital Printing Platform Integration | Industrial bakeries in Netherlands and Belgium compress production cycles from hours to minutes. |
| GRAS Documentation Investment | FDA food-contact clearance unlocks specialty bakery channels blocking European suppliers. |
| Compostable Substrate Development | EU Green Deal packaging mandates create first-mover advantage in biodegradable decoration categories. |
| Direct-to-Maker Channel Buildout | Etsy and B2B marketplace presence captures artisan procurement shift away from wholesale distributors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with ingredient procurement managers at industrial bakeries, flavor systems directors at integrated suppliers, artisan craft buyers on direct-to-maker platforms, and ECHA compliance officers; alongside secondary validation through customs trade databases, SEC filings of listed cocoa processors, FDA GRAS notification records, and EU F-Gas Regulation implementation reports. Bottom-up volume triangulation across product type and material segments was cross-checked against top-down value estimates derived from disclosed capacity expansions and foundry utilization rates.
Forecast inputs span product type maturity curves, material substitution elasticities under REACH compliance pressure, and digital printing adoption rates across industrial bakery segments. Segmentation modeling incorporates material science tier, end-use application sophistication, customer procurement authority, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-kilogram trends across premium and commodity tiers. Cocoa butter price volatility coefficients and cold-chain energy cost trajectories inform scenario boundaries.
Sensitivities concentrate around ECHA substance restriction enforcement intensity, FDA GRAS determination timeline extensions, and West African supply disruption frequency. Forecasts reflect documented assumptions on artisan craft demand persistence and digital printing technology cost curves. Material shifts in EU biodegradable packaging mandate implementation schedules or REACH heavy metal limit revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
Pillow Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market