
 India Home Furnishing Market | 2026-2036
India Home Furnishing Market Size, Share, and Industry Trends Forecast 2026-2036
India Home Furnishing Market Insights
Premium-grade fabric specifications and certified thread-count benchmarks is rotating consumer preference toward durable, long-life home textiles. Godrej Interio leverages its integrated manufacturing footprint across multiple states to control raw material costs. Wakefit sustains direct-to-consumer channel dominance through mattress-to-furnishing bundling. Wooden Street specializes in solid-wood customization, occupying a niche above mass-market laminate alternatives.
Home furnishing encompasses textile and non-textile products for residential interior enhancement, including woven upholstery with specified GSM weights, flame-retardant curtain linings, and dimension-standardized bed linen sets manufactured through jacquard or digital-print processes. Bed linen and upholstery command the widest margin pools due to repeat-purchase frequency and seasonal collection cycles. Cotton dominates material flows for climate suitability, while velvet captures premium positioning in metropolitan markets. Online retail channels are expanding fastest, though brick-and-mortar specialty shops retain tactile-purchase loyalty for high-ticket items.
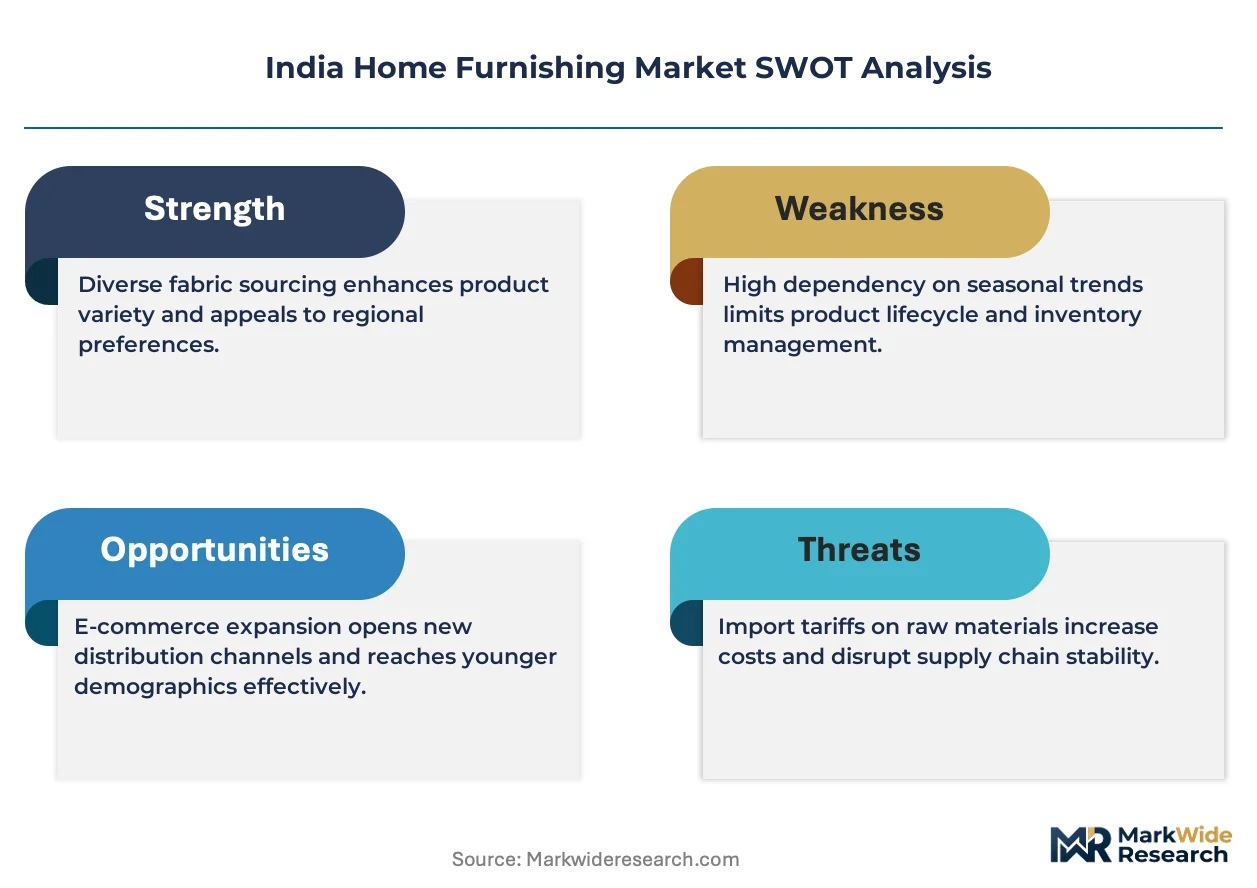
BIS textile standards, CDSCO-mandated chemical safety thresholds for imported dyes, and state-level pollution control norms for dyeing clusters in Gujarat and Tamil Nadu collectively elevate compliance costs for unorganized producers. The PLI scheme for textiles incentivizes domestic manufacturing scale-ups, redirecting import substitution toward local spinning and weaving capacity. Stakeholders must monitor BIS enforcement intensity and e-commerce platform liability rules as these will determine which supplier tiers gain shelf access versus face delisting.
Market Dynamics
Urban millennials in tier-2 cities are compressing furniture replacement cycles while BIS textile certification mandates force raw material standardization across Maharashtra, Gujarat, and Karnataka manufacturing clusters.
Growth Catalysts
- PLI scheme for textiles:Domestic spinning and weaving capacity expansion redirects import substitution toward local supply chains.
- Modular bedroom furniture:Tier-2 city millennials drive demand for customizable, space-efficient residential solutions.
- Digital-print jacquard processes:Advanced manufacturing enables rapid seasonal collection turnover for bed linen and upholstery segments.
Market Restraints
- Cotton price volatility:Climate-dependent fiber sourcing elevates input cost unpredictability for climate-suitable textile production.
- Gujarat and Tamil Nadu dyeing cluster concentration:State-level pollution control norms create compliance bottlenecks for unorganized producers.
- Brick-and-mortar tactile dependency:High-ticket furnishing purchases resist full online migration due to physical verification requirements.
Strategic Opportunities
- Karnataka real estate corridors:Furniture manufacturing hub overlap with residential construction creates integrated demand zones.
- Velvet premium positioning:Metropolitan markets show appetite for elevated fabric specifications above standard cotton offerings.
- Direct-to-consumer bundling:Mattress-to-furnishing cross-selling reduces customer acquisition costs in online channels.
Industry Challenges
- BIS certification timelines:Textile durability and flame resistance testing creates product launch delays for new entrants.
- CDSCO dye compliance:Chemical safety thresholds for imported colorants require reformulation of established supply relationships.
- Skilled jacquard weaving labor:Technical proficiency gaps constrain output scaling for complex pattern manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Home Furnishing Market |
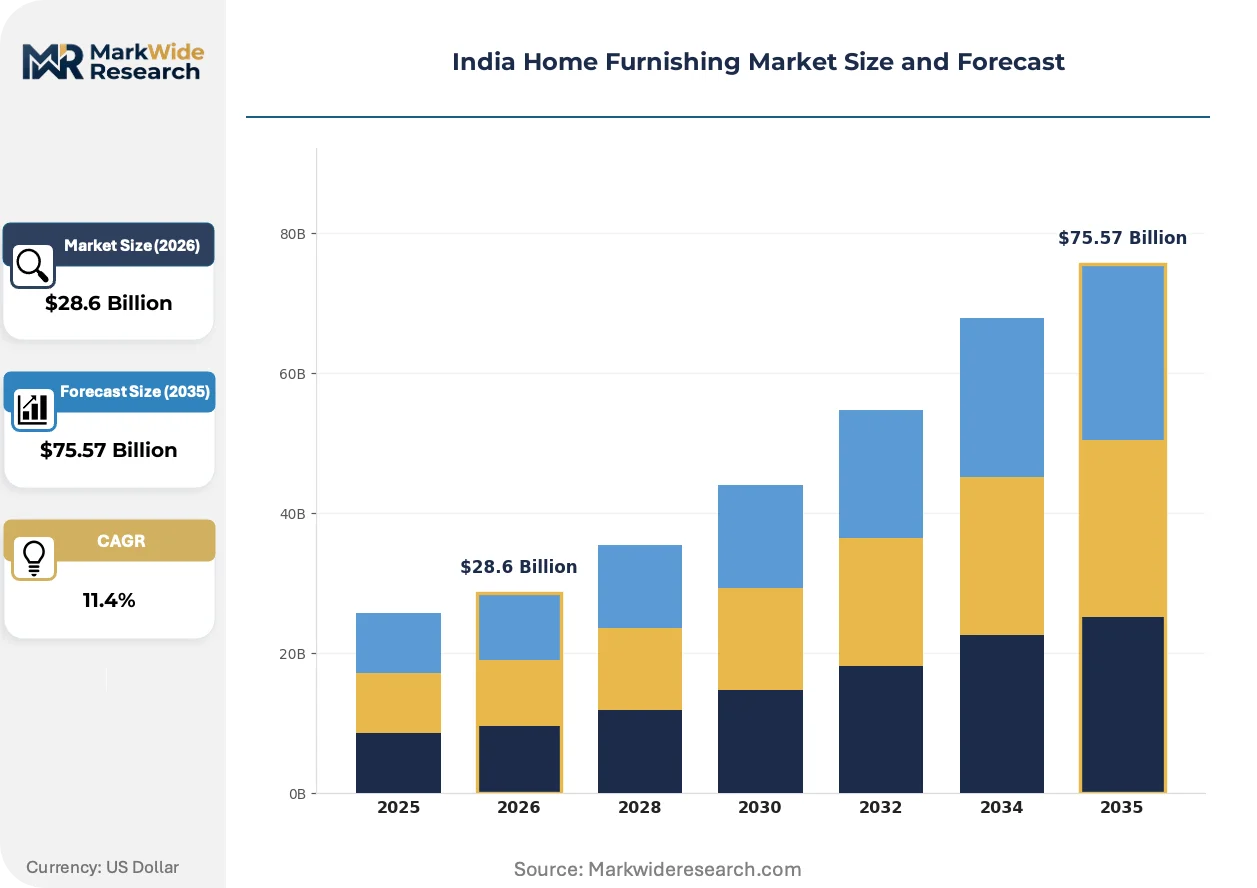
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upholstery, Curtains, Bed Linen, Cushions Material: Cotton, Polyester, Linen, Velvet Customer Type: Retail Consumers, Wholesalers, Interior Designers, Contractors Distribution Channel: Online Retail, Brick-and-Mortar, Home Improvement Stores, Specialty Shops |
| Companies Covered | Nilkamal, Wakefit, Godrej Interio, Wooden Street, IKEA India, Urban Ladder, Durian, Evok, Pepperfry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Home Furnishing Market Trends and Innovations
Certification-driven material sourcing and channel restructuring are compressing traditional supplier hierarchies while enabling new manufacturing-service hybrids.
Digital-print upholstery production is fragmenting the seasonal collection cycle. Tier-1 retailers adopt on-demand pattern customization to reduce inventory carrying costs. This technology is fragmenting the long-standing dominance of large-batch jacquard weaving houses in Surat and Panipat.
BIS textile standards enforcement is intensifying across Maharashtra and Gujarat manufacturing zones. CDSCO-mandated chemical safety thresholds for imported dyes now require pre-shipment testing documentation. Unorganized producers in Tamil Nadu dyeing clusters face delisting from e-commerce platforms lacking compliance certification.
Urban millennial buyers now prioritize certified thread-count benchmarks over price-point comparison. Online retail channels capture repeat-purchase bed linen volumes previously held by specialty shops. This behavioral pivot concentrates most visibly in Bangalore and Pune residential corridors.
India Home Furnishing Market Segmentation
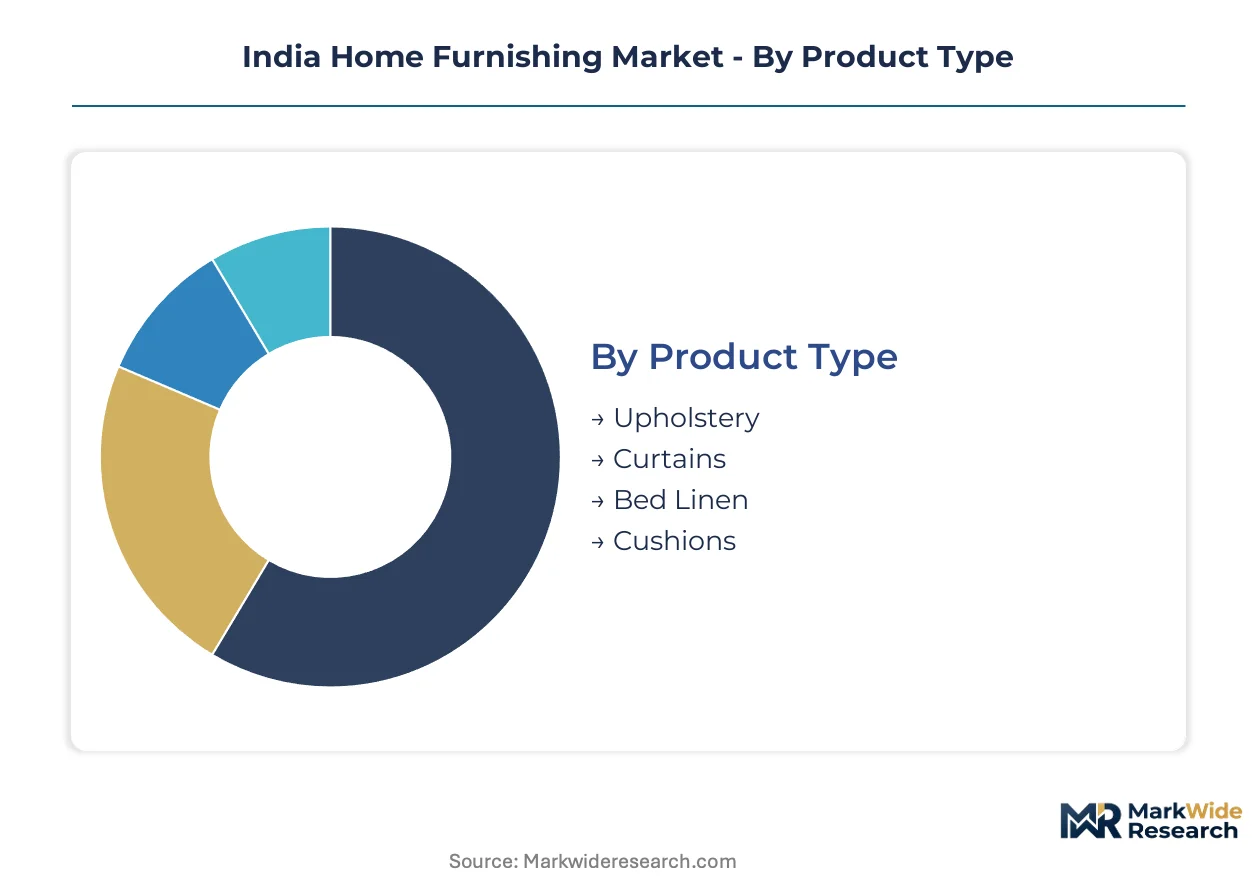
Channel fragmentation across Maharashtra, Gujarat, and Karnataka manufacturing clusters reshapes how furnishing categories reach end buyers. Material certification requirements and tactile purchase preferences create divergent distribution economics for each segment cluster.
Product Type:
Bed linen and upholstery command premium shelf positioning across online retail and brick-and-mortar specialty shops, while curtains and cushions flow more heavily through home improvement stores and contractor channels.
- Bed Linen:Jacquard and digital-print manufactured sets with specified thread-count benchmarks dominate repeat-purchase volumes. Demand concentrates in Bangalore and Pune residential corridors where urban millennials prioritize certified durability over price-point comparison.
- Upholstery:Woven fabrics with specified GSM weights and flame-retardant specifications capture the widest margin pools through seasonal collection cycles. Maharashtra and Gujarat manufacturing hubs supply tier-1 retailers adopting on-demand pattern customization to compress inventory carrying costs.
- Curtains:Flame-retardant linings with BIS-certified textile durability serve commercial and residential retrofit markets through contractor networks.
- Cushions:Modular fill products with standardized dimension sets distribute through mass-market home improvement stores and online bundling strategies.
By volume, bed linen leads. By growth pace, upholstery is ahead.
Material:
Cost tier stratification separates climate-suitable natural fibers from metropolitan premium positioning, with compliance cost burdens falling heaviest on imported synthetic supply chains.
- Cotton:Climate-suitable fiber flows dominate material sourcing for bed linen and curtain base fabrics across unorganized spinning clusters in Gujarat and Tamil Nadu. CDSCO-mandated chemical safety thresholds for dyes elevate reformulation costs for established supply relationships in these dyeing clusters.
- Velvet:Premium fabric specifications capture metropolitan market appetite above standard cotton offerings, with digital-print capabilities enabling rapid seasonal turnover for upholstery applications in Bangalore and Mumbai retail corridors.
- Polyester:Synthetic fiber imports face BIS certification timelines and pre-shipment testing documentation requirements that delay product launches for new entrants.
- Linen:Natural fiber with higher GSM specifications serves niche premium positioning through specialty shops retaining tactile-purchase loyalty for high-ticket items.
By volume, cotton leads. By margin expansion, velvet is climbing the fastest.
Customer Type:
Procurement scale and specification complexity determine channel access, with certified manufacturers capturing institutional flows while unorganized producers face e-commerce platform delisting risks.
- Retail Consumers:Urban millennial buyers in tier-2 cities compress furniture replacement cycles while prioritizing certified thread-count benchmarks, driving direct-to-consumer bundling strategies through online retail channels.
- Interior Designers:Specification-driven procurement concentrates in Karnataka real estate corridors where furniture manufacturing hub overlap with residential construction creates integrated demand zones for customized solid-wood and premium textile combinations.
- Wholesalers:Volume aggregation from Maharashtra and Gujarat manufacturing clusters serves secondary city distribution networks with standardized laminate alternatives and mass-market bed linen.
- Contractors:Project-scale procurement for commercial and residential developments sources flame-retardant curtain linings and dimension-standardized products through established supply relationships with certified manufacturers.
By transaction volume, retail consumers lead. By contract value concentration, interior designers are gaining share fastest.
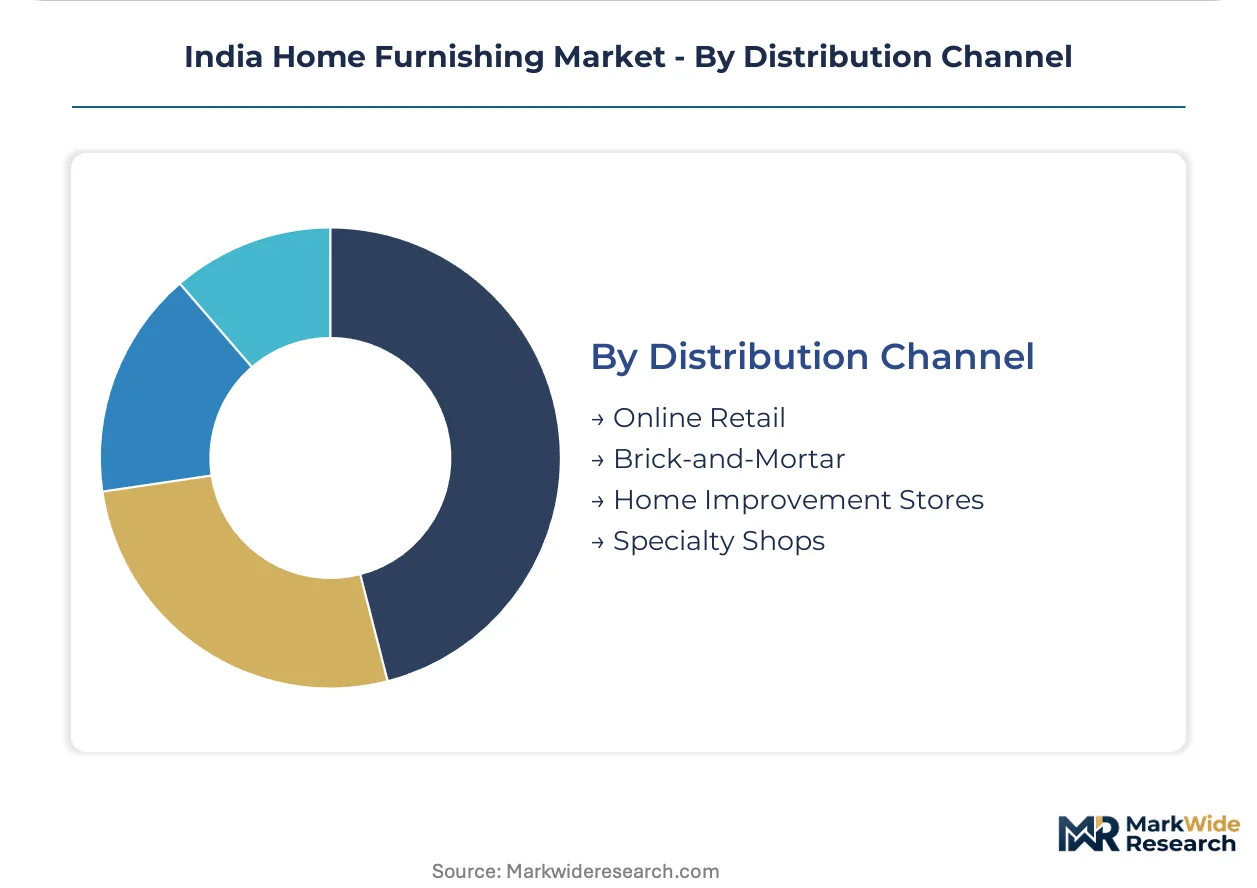
Distribution Channel:
Maturity divergence separates established tactile-dependent formats from digitally native channels expanding most quickly in repeat-purchase categories.
- Online Retail:Direct-to-consumer channel dominance sustains through mattress-to-furnishing bundling that reduces customer acquisition costs, capturing repeat-purchase bed linen volumes previously held by specialty shops.
- Specialty Shops:Brick-and-mortar tactile dependency retains high-ticket furnishing purchases requiring physical verification, particularly for velvet upholstery and solid-wood customization above mass-market laminate alternatives.
- Home Improvement Stores:Mass-market positioning for curtains, cushions, and standardized bed linen serves price-sensitive segments through Maharashtra and Gujarat retail networks.
- Brick-and-Mortar:General retail format faces compression as online retail fragments seasonal collection cycles and tier-1 retailers adopt on-demand pattern customization.
By current volume, specialty shops lead. By expansion trajectory, online retail is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spinning and weaving capacity clusters heavily in Maharashtra, Gujarat, and Karnataka, where real estate corridors overlap with furniture manufacturing hubs. BIS textile certification mandates and PLI scheme incentives are redirecting material flows toward domestic supply chains. CDSCO dye compliance requirements reshape procurement patterns in Tamil Nadu dyeing clusters.
Maharashtra
Mumbai and Pune residential corridors drive demand for premium velvet upholstery and certified bed linen with specified thread-count benchmarks. BIS enforcement intensifies across manufacturing zones, elevating compliance timelines for flame-retardant textile launches. Thane-Bhiwandi furniture clusters integrate with real estate development in the Mumbai Metropolitan Region, compressing supplier-to-site delivery windows.
Gujarat
Surat jacquard weaving houses face fragmentation as tier-1 retailers adopt on-demand digital-print customization. State-level pollution control norms from the Gujarat Pollution Control Board constrain unorganized dyeing operations in the textile belt. Ahmedabad-Vadodara manufacturing corridors supply standardized laminate alternatives and mass-market bed linen to secondary city distribution networks.
Karnataka
Bangalore urban millennials prioritize certified durability over price-point comparison, driving repeat-purchase volumes through online retail channels. The state's industrial policy incentivizes furniture manufacturing scale-ups in peri-urban corridors. Mysore-Bangalore real estate clusters create integrated demand zones where residential construction overlaps with solid-wood customization workshops.
Tamil Nadu
Tiruppur and Karur spinning clusters face elevated reformulation costs from CDSCO-mandated chemical safety thresholds for imported colorants. Unorganized producers risk e-commerce platform delisting without pre-shipment testing documentation. Chennai contractor networks source flame-retardant curtain linings for commercial retrofit markets.
Telangana
Hyderabad tier-2 city millennials compress furniture replacement cycles, driving demand for modular bedroom solutions. State textile parks under the Telangana State Industrial Infrastructure Corporation attract spinning capacity expansion. Secunderabad-Ghatkesar manufacturing zones serve as emerging distribution nodes for Andhra Pradesh and Telangana retail networks.
India Home Furnishing Market Competitive Landscape
Concentration sits with diversified conglomerates and direct-to-consumer specialists competing across distinct channel architectures. The market structure spans three tiers: integrated manufacturers with captive material sourcing, digital-native brands with bundling strategies, and niche solid-wood customizers. Dominant competitive moves include backward integration into spinning capacity and mattress-to-furnishing cross-selling architectures.
Within the diversified conglomerate tier, Godrej Interio exemplifies integrated manufacturing footprint control across multiple states. Wakefit anchors direct-to-consumer channel dominance through bundling strategies that reduce customer acquisition costs. Wooden Street occupies the solid-wood customization niche above mass-market laminate alternatives, representing specialist positioning in residential interior enhancement.
| Leading Market Players |
|---|
| Nilkamal |
| Wakefit |
| Godrej Interio |
| Wooden Street |
| IKEA India |
| Urban Ladder |
| Durian |
| Evok |
| Pepperfry |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Surat jacquard weavers and Maharashtra-based retailers lock in cotton fiber access while fixing base price visibility against BIS certification cost escalations. These arrangements insulate tier-1 buyers from Gujarat dyeing cluster volatility while exposing unorganized producers to spot market cotton price swings.
Pricing Analysis
BIS textile certification dictates the pricing tier structure across bed linen and upholstery segments. Three-tier pricing structure across certified premium, compliant standard, and uncertified economy levels separates Godrej Interio's integrated margin control from unorganized spot producers. Pricing pressure stems from CDSCO-mandated dye reformulation costs elevating input expenses for Tamil Nadu clusters. Retail consumers in tier-2 cities show highest price sensitivity, while interior designers in Bangalore corridors prioritize certified thread-count benchmarks over cost comparison.
Supply Chain Analysis
Surat-Panipat weaving corridor concentration anchors jacquard capacity access for domestic upholstery supply. Raw material flows draw from Gujarat cotton spinning clusters, Tamil Nadu dyeing operations, and imported velvet fiber shipments. Single-source vulnerability concentrates in Surat's digital-print transition lagging behind retailer on-demand requirements. Distribution runs through direct-to-consumer platforms capturing repeat-purchase bed linen volumes alongside specialty shops retaining high-ticket tactile verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against ready-to-assemble furniture imports and cross-category mattress-furnishing bundlers eroding standalone textile margins.
For Market Incumbents: Consolidate spinning capacity in Gujarat and Karnataka manufacturing corridors to captive cotton supply against price volatility. Deepen BIS certification breadth across flame-retardant and thread-count benchmarks to delist unorganized competitors from Pepperfry and Urban Ladder platform access.
For New Entrants and Emerging Players: Lead with modular bedroom customization targeting Hyderabad and Pune tier-2 millennial buyers compressing furniture replacement cycles. Exploit white-space in solid-wood furnishing above laminate alternatives through peri-urban Bangalore workshop networks. Deploy direct-to-consumer bundling with mattress specialists to compress customer acquisition costs.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated textile-furniture hybrids with captive dyeing certification and multi-state manufacturing footprints. Long-term viability hinges on PLI scheme utilization sustaining domestic spinning scale against import substitution headwinds. Monitor BIS enforcement intensity across Maharashtra and Gujarat as the signal for which supplier tiers gain platform shelf access versus face delisting.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spinning Capacity | Captive cotton supply insulates Godrej Interio from Gujarat fiber price volatility. |
| BIS Certification Program Expansion | Flame-retardant textile compliance unlocks e-commerce platform access for tier-1 retailers. |
| Direct-to-Consumer Platform Launch | Wakefit-style bundling reduces acquisition costs in Bangalore-Pune residential corridors. |
| Digital-Print Manufacturing Scale-Up | On-demand pattern customization fragments Surat jacquard weaving house dominance. |
| Solid-Wood Customization Network Buildout | Wooden Street positioning above laminate alternatives captures designer specification flows. |
Research Methodology
A spread of perspectives from textile plant managers, furniture manufacturing heads, e-commerce category buyers, and interior design procurement leads converged on the working assumptions. Primary fieldwork combined with secondary validation against BIS certification databases, CDSCO dye compliance filings, PLI scheme disbursement records, and Maharashtra-Gujarat state industrial surveys. Bottom-up spinning cluster capacity estimates triangulated against top-down real estate construction pipeline data.
Segmentation dimensions modeled include product type, material grade tier, customer procurement scale, and distribution channel architecture across the analysis window. CAGRs derived from historical replacement cycle compression in tier-2 cities and PLI-induced domestic capacity expansion trajectories. Forecast inputs incorporated BIS enforcement intensity scenarios and digital-print adoption curves in Surat weaving clusters.
Underlying assumptions cover sustained PLI textile scheme disbursement and BIS certification timeline stability, with deviation risk concentrated in cotton price volatility and CDSCO dye reformulation cost spikes. Practitioners should keep alternative scenarios live as state-level pollution control norm enforcement evolves in Gujarat and Tamil Nadu dyeing clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Mattress Topper Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Gas Fire Table Market