
 Global High Temperature Curtains Market | 2026-2036
Global High Temperature Curtains Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Temperature Curtains Market Analysis
China's specialty textile producers is broadening silica fabric capacity to serve furnace operators across Asia. Morgan Advanced Materials leverages ceramic fiber expertise to anchor European demand for extreme-temperature kiln curtains. SGL Carbon sustains carbon composite leadership in German automotive foundry applications. Saint-Gobain dominates refractory-grade curtain supply through integrated mineral sourcing and melt-spinning operations.
High temperature curtains are engineered textile barriers, typically woven from fiberglass, Kevlar, or ceramic fiber matrices with silicone or vermiculite coatings, designed to withstand continuous exposure above 500°C while containing radiant heat, molten splash, and combustion byproducts in industrial environments. Fire-resistant curtains lead product type demand due to mandatory OSHA and EU workplace safety protocols, while thermal curtains represent the fastest-growing category as data center cooling optimization drives adoption of zoned heat containment. Fiberglass occupies the largest material share by volume given its cost-performance balance, though Kevlar-reinforced fabrics command premium positioning in aerospace and defense heat-shielding applications where tensile strength under thermal load determines specification.
OSHA's combustible dust and heat hazard standards in the United States, combined with REACH chemical safety requirements and CE marking obligations under Europe's Machinery Directive, compel manufacturers to certify curtains against EN ISO 15025 flame spread tests and ASTM E84 surface burning characteristics. China's GB standards for fire safety in industrial buildings add a third compliance layer for exporters serving Asia-Pacific infrastructure projects. Stakeholders must monitor evolving carbon border adjustment mechanisms and localized content rules that could reshape sourcing economics for coated fabric supply chains.
Market Dynamics
The EU Green Deal's industrial emissions standards are forcing immediate replacement of legacy asbestos-based thermal barriers across European heavy manufacturing, creating a structural pull for certified fire-resistant alternatives that cascades through procurement cycles in steel, aluminum, and foundry operations.
Growth Catalysts
- EU Green Deal compliance mandates:REACH chemical safety requirements and CE marking obligations under Europe's Machinery Directive compel furnace operators to upgrade to EN ISO 15025 certified curtains, accelerating replacement demand in Germany's Ruhr industrial cluster.
- Blast furnace expansion:Steel mills and aluminum smelters are broadening procurement of thermal barrier fabrics to protect personnel and equipment near high-temperature zones, sustaining continuous replacement cycles.
- Silica fabric capacity buildout:Specialty textile producers across Asia are scaling woven ceramic fiber output to serve furnace operators seeking alternatives to coated fiberglass in extreme-heat containment applications.
Market Restraints
- Raw material volatility:Alumina and silica precursor costs fluctuate with energy pricing, compressing margins for ceramic fiber weavers dependent on melt-spun mineral feedstocks.
- Supply concentration risk:Refractory-grade mineral sourcing concentrates among integrated producers with captive mining operations, limiting second-tier fabricators' negotiating leverage.
- Technical performance ceilings:Fiberglass matrices degrade above 650°C continuous exposure, constraining specification in next-generation furnace designs targeting higher operating temperatures.
Strategic Opportunities
- Data center thermal zoning:Hyperscale computing facilities are adopting zoned heat containment curtains to optimize cooling efficiency, opening a non-industrial application channel with shorter sales cycles.
- Carbon border adjustment positioning:EU CBAM implementation creates first-mover advantage for curtain suppliers with verified low-carbon mineral sourcing and regional manufacturing footprints.
- Kevlar-aerospace convergence:Defense heat-shielding specifications are migrating toward commercial aerospace thermal protection systems, expanding addressable market for high-tensile aramid-reinforced fabrics.
Industry Challenges
- Certification timeline compression:ASTM E84 and EN ISO 15025 testing protocols require extended burn-characteristic validation, delaying product launches for new coating formulations.
- Legacy system integration friction:Furnace operators with decades-old curtain mounting infrastructure face retrofit complexity when specifying next-generation multilayer barrier designs.
- Technical textile skill scarcity:Weaving expertise for ceramic fiber matrices remains concentrated among specialized operators, limiting workforce scalability for capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Temperature Curtains Market |
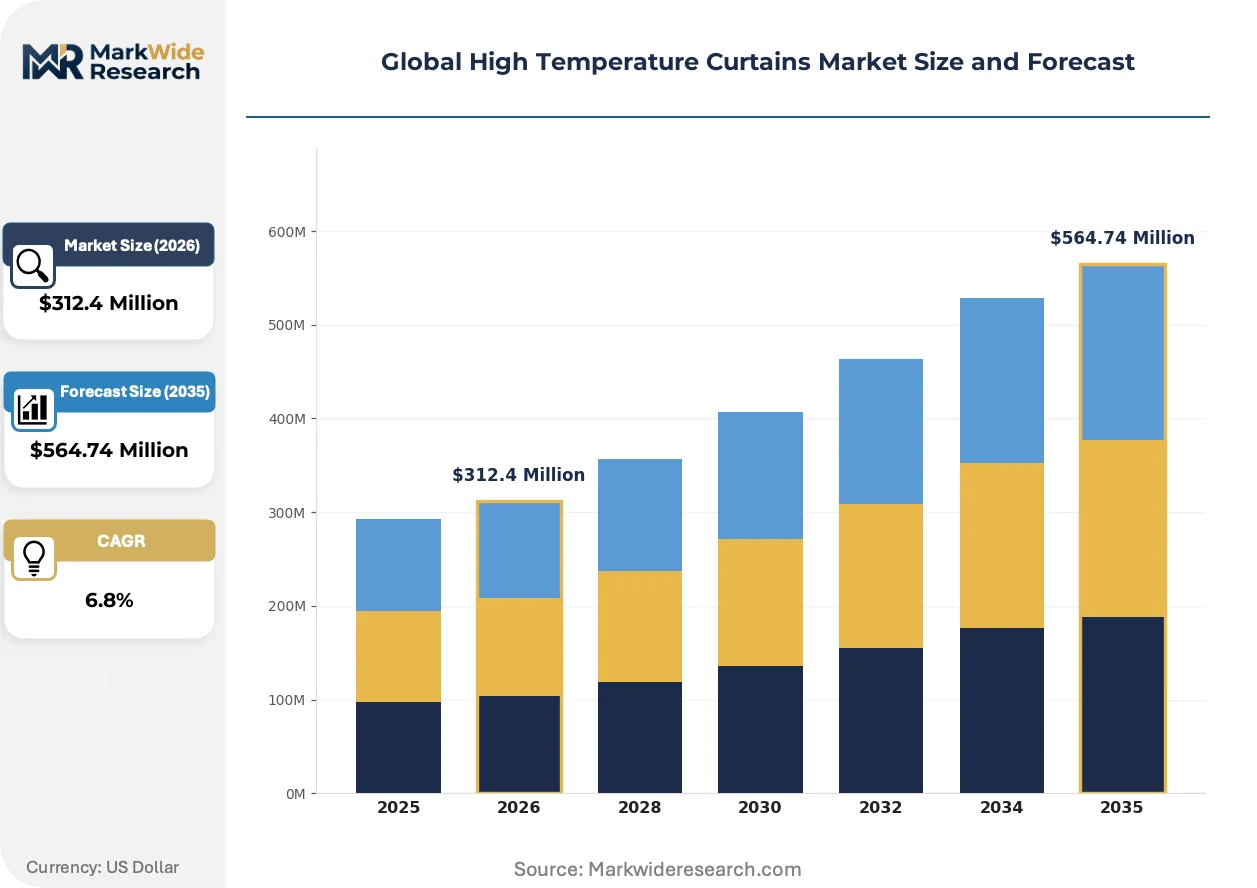
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Resistant Curtains, Thermal Curtains, Insulated Curtains, Soundproof Curtains Application: Industrial Settings, Commercial Spaces, Residential Homes, Automotive Facilities Material: Fiberglass, Kevlar, Cotton Blends, Reinforced Fabrics End User: Manufacturers, Retailers, Contractors, Facility Managers |
| Companies Covered | 3M, Alcoa Corporation, Thermo Fisher Scientific, SEFPRO Group, SGL Carbon, Morgan Advanced Materials, Vesuvius plc, HarbisonWalker International, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Temperature Curtains Market Emerging Trajectories
Digital thermal monitoring systems are weaving sensor arrays directly into curtain substrates, enabling real-time heat flux measurement that transforms passive barriers into active safety infrastructure.
Ceramic fiber composites with embedded thermocouple networks are automating furnace perimeter surveillance, allowing steel producers to detect hotspot formation before barrier degradation occurs. Early adopters in German automotive foundries are deploying these smart curtains across continuous casting lines. The technology is automating preventive maintenance scheduling while reducing unplanned downtime from thermal breach events.
REACH chemical safety requirements are tightening restrictions on boron-based coating additives traditionally used to enhance fiberglass flame resistance, forcing reformulation toward vermiculite and silicone alternatives. European fabricators face compliance deadlines that compress R&D cycles for next-generation products. The regulatory pressure is reshaping competitive positioning toward suppliers with in-house mineral coating expertise.
Long-term service agreements are displacing transactional curtain replacement purchases among integrated steel producers, bundling fabric supply with installation and inspection schedules. This procurement evolution concentrates volume with vertically capable suppliers who can execute turnkey barrier system overhauls. The contract structure is most visible in China's state-owned steel sector, where centralized purchasing favors integrated service providers over component vendors.
Global High Temperature Curtains Market Segmentation
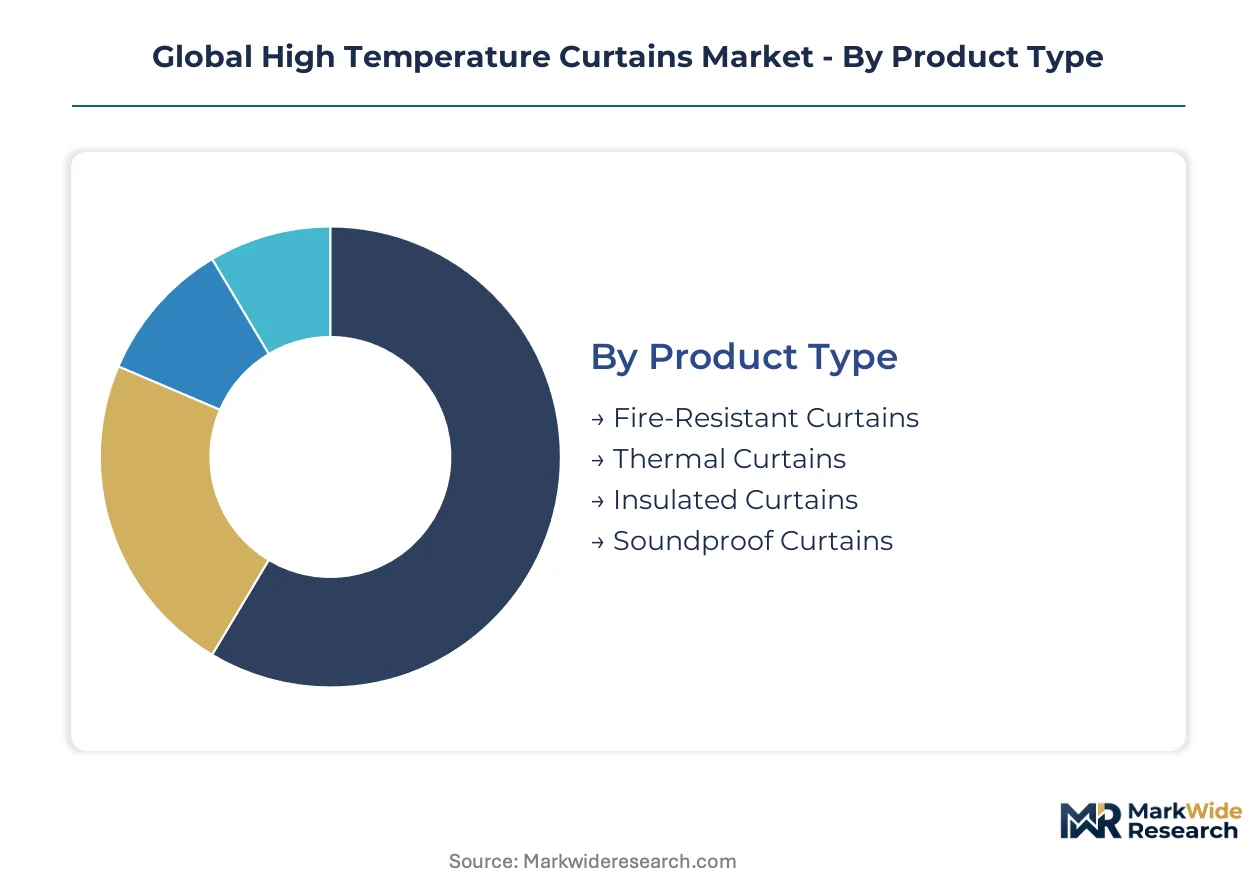
Specification requirements diverge sharply across end-use environments, from blast furnace radiant heat containment to data center thermal zoning. Procurement patterns track these functional demands, with certification-grade products commanding distinct sourcing channels from general industrial barriers.
Product Type:
Performance thresholds and regulatory certification status separate procurement tiers across industrial safety applications.
- Fire-Resistant Curtains:Woven fiberglass or ceramic fiber matrices with vermiculite or silicone coatings, engineered to EN ISO 15025 and ASTM E84 flame spread standards. Steel mills and aluminum smelters in Germany's Ruhr cluster sustain replacement cycles for blast furnace perimeter protection under EU Green Deal compliance mandates.
- Thermal Curtains:Multilayer barriers with reflective metallized surfaces and insulating interlinings, designed for radiant heat containment rather than direct flame exposure. Hyperscale data center operators across the United States and China are deploying zoned heat containment configurations to optimize cooling efficiency and reduce energy consumption.
- Insulated Curtains:Composite assemblies combining thermal barrier fabrics with mineral wool or aerogel cores for temperature differential maintenance.
- Soundproof Curtains:Mass-loaded vinyl or fiberglass composites with acoustic absorption ratings for industrial noise control applications.
Mature deployment sits with fire-resistant curtains across heavy manufacturing. Newer deployment is concentrated in thermal curtains serving non-industrial thermal management.
Application:
Operating environment severity dictates material specification, installation architecture, and replacement frequency.
- Industrial Settings:Continuous exposure to temperatures exceeding 500°C, molten metal splash, and combustion byproducts demands ceramic fiber or Kevlar-reinforced matrices with specialized mounting hardware. Foundries and smelters in China's industrial provinces and India's steel belt drive specification for extreme-duty barrier systems.
- Commercial Spaces:Fire-rated compartmentalization for atriums, egress corridors, and kitchen separation requires lighter-weight fiberglass constructions with faster deployment mechanisms. Building codes in the United States and Japan mandate these installations for occupant safety compliance.
- Residential Homes:Garage fire separation and hearth protection applications utilize consumer-grade fiberglass panels with simpler mounting systems.
- Automotive Facilities:Paint booth fire containment and welding bay isolation employ spark-resistant fabrics with rapid-retract mechanisms.
Volume concentration remains with industrial settings. Application expansion is climbing the fastest in commercial spaces adopting data center thermal management protocols.
Material:
Cost-performance positioning and temperature ceiling requirements determine specification across end-use categories.
- Fiberglass:E-glass or S-glass woven substrates with silicone, PTFE, or vermiculite coatings deliver the dominant cost-performance balance for applications below 650°C continuous exposure. General industrial procurement across Germany, China, and the United States favors this material for replacement cycle economics.
- Kevlar:Aramid fiber matrices provide exceptional tensile strength under thermal load for aerospace heat shielding and defense applications where mechanical integrity at temperature determines specification. Premium positioning reflects raw material costs and specialized weaving requirements.
- Cotton Blends:Treated natural fiber constructions for lower-temperature welding spark protection and light industrial applications.
- Reinforced Fabrics:Hybrid constructions combining multiple fiber types or embedded wire reinforcement for specialized mechanical loading requirements.
Supply concentration favors fiberglass for volume applications. Technology migration is accelerating toward Kevlar-reinforced specifications in aerospace-adjacent thermal protection.
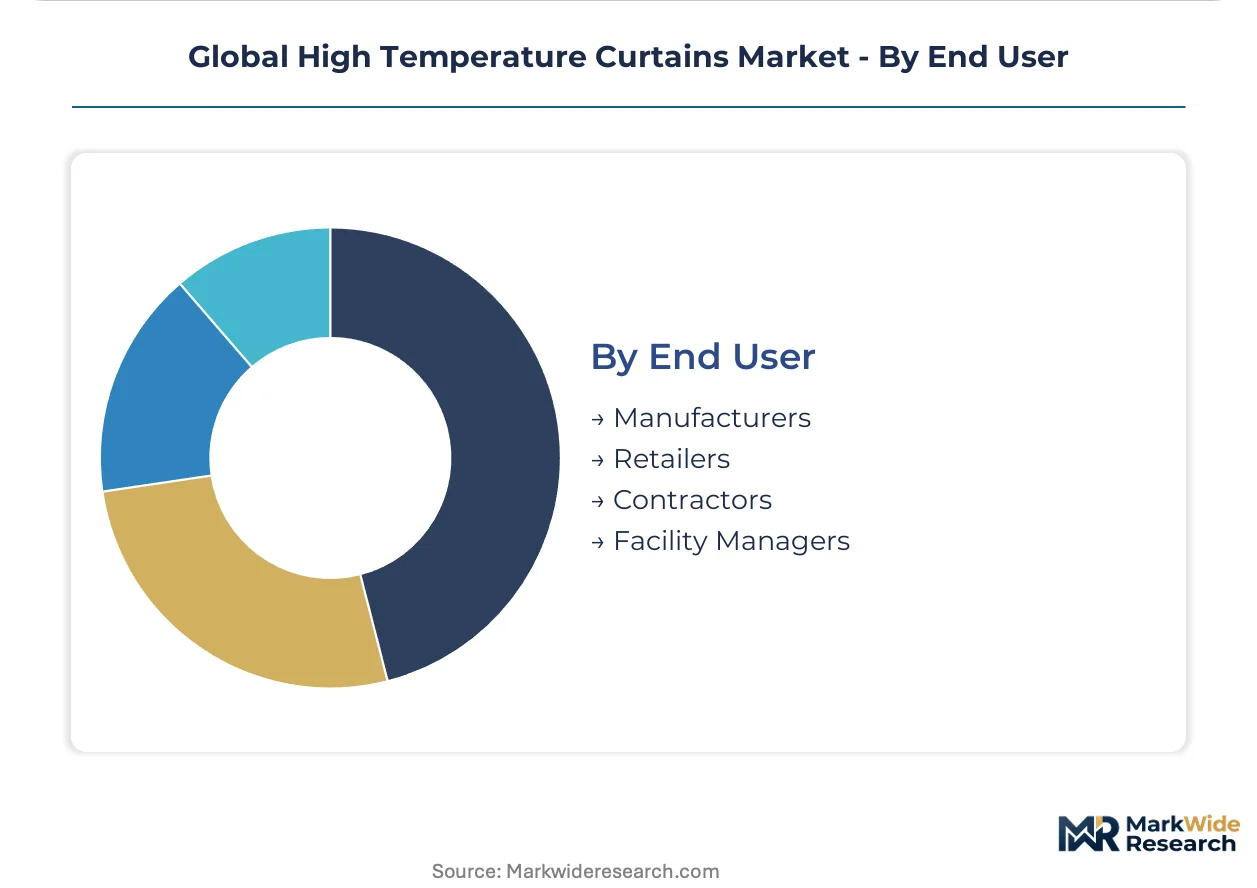
End User:
Purchasing authority and technical specification capability shape channel structure and service bundling.
- Manufacturers:Integrated steel, aluminum, and automotive producers with in-house engineering teams specify custom barrier systems and negotiate long-term service agreements bundling supply with installation and inspection. China's state-owned steel sector exemplifies this procurement evolution toward turnkey providers.
- Contractors:Installation specialists with furnace retrofit expertise capture value from legacy system integration and mounting infrastructure adaptation. Technical textile skill scarcity limits workforce scalability for these service-intensive engagements.
- Retailers:Distribution intermediaries serving smaller commercial and residential accounts with standardized product configurations.
- Facility Managers:Building operations personnel responsible for compliance-driven replacement scheduling in commercial and institutional environments.
Contracting authority concentrates with manufacturers. Procurement pattern evolution is expanding fastest among facility managers adopting predictive maintenance scheduling for thermal barrier assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial cluster anchors European silica precursor supply chains for ceramic fiber weavers serving blast furnace operators. China's Shandong and Jiangsu provinces concentrate woven fabric capacity for Asia-Pacific furnace retrofit demand. The United States maintains integrated mineral sourcing through Appalachian refractory clay deposits.
United States
OSHA combustible dust enforcement drives steel mill procurement of ASTM E84 certified thermal barriers near Cleveland and Pittsburgh blast furnace corridors. The Infrastructure Investment and Jobs Act channels federal procurement toward domestic fabricators for public infrastructure fire safety. Houston's petrochemical complex sustains continuous replacement cycles for extreme-temperature kiln curtains in catalytic cracker maintenance.
Germany
REACH chemical safety deadlines accelerate asbestos replacement in North Rhine-Westphalia's steel and aluminum smelters. EU Green Deal industrial emissions standards mandate EN ISO 15025 certified curtain installations across the Ruhr manufacturing belt. Düsseldorf-based engineering procurement offices consolidate long-term service agreements bundling supply with inspection protocols.
China
GB standards for industrial fire safety compel state-owned steel sector procurement of woven ceramic fiber barriers. Dual carbon goals under MEE oversight push foundry operators toward thermal efficiency upgrades in Hebei and Shandong provinces. Zhengzhou's refractory materials cluster scales silica fabric output for domestic furnace retrofit demand.
India
BIS fire safety certification requirements reshape procurement for Tata Steel and JSW operations across Jharkhand and Odisha steel belts. The PLI scheme for specialty steel production incentivizes integrated barrier system upgrades in new blast furnace installations. Mumbai-Pune industrial corridor demand concentrates with contractors capable of legacy furnace retrofit execution.
Japan
METI energy efficiency directives drive thermal curtain adoption in automotive foundry operations across Aichi Prefecture's Toyota supplier network. JIS standards for industrial fire containment specify multilayer barrier configurations in Nagoya-area manufacturing. Osaka-based trading houses coordinate ceramic fiber imports for Kansai region steel maintenance cycles.
Global High Temperature Curtains Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue smart textile integration and data center thermal management applications. Market structure concentrates among integrated refractory material suppliers with captive mineral sourcing and specialized ceramic fiber weavers serving extreme-temperature specifications. Three archetypes dominate: diversified materials conglomerates with melt-spinning operations, mid-scale fabricators with regional installation capabilities, and technology specialists embedding sensor arrays into barrier substrates. Competitive moves center on backward integration into alumina and silica precursor supply, plus long-term service contract bundling to displace transactional replacement purchases.
Among diversified materials suppliers, Saint-Gobain and Morgan Advanced Materials exemplify the integrated archetype with refractory-grade mineral sourcing and melt-spinning operations. SGL Carbon occupies a distinct position within carbon composite specialization for automotive foundry applications. These three anchors demonstrate how competitive positioning stratifies across mineral feedstock control, weaving expertise concentration, and turnkey service execution capability.
| Leading Market Players |
|---|
| 3M |
| Alcoa Corporation |
| Thermo Fisher Scientific |
| SEFPRO Group |
| SGL Carbon |
| Morgan Advanced Materials |
| Vesuvius plc |
| HarbisonWalker International |
| Saint-Gobain |
| Others |
Supply Flow & Price Mechanics
EU Green Deal compliance mandates for EN ISO 15025 certified curtains are forcing procurement officers toward bundled service contracts, compelling suppliers to absorb installation and inspection costs while recouping margin through long-term offtake agreements rather than transactional spot sales.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium suppliers from commodity fabricators in this market. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service depth. Cost compression in economy-grade fiberglass curtains is intensifying because Chinese producers are scaling woven ceramic fiber capacity. Integrated steel producers with centralized purchasing authority exhibit lowest price sensitivity; small commercial facility managers show highest sensitivity.
Supply Chain Analysis
Regional distribution centers in Düsseldorf, Zhengzhou, and Pittsburgh maintain hub-and-spoke patterns for just-in-time furnace retrofit deliveries. Supply concentrates in Germany, China, and the United States for refractory-grade mineral feedstocks and melt-spun ceramic fiber output. Raw material sourcing draws from alumina refineries, silica sand deposits, and boron derivative processors. Single-source vulnerability concentrates in vermiculite coating supply from South African mining operations. Distribution runs through specialized industrial distributors with furnace engineering expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH chemical safety deadlines and EU Green Deal emissions standards erect regulatory moats favoring incumbent suppliers with certified product portfolios and established testing relationships.
For Market Incumbents: Cement market position by securing captive supply of alumina and silica precursors through backward integration into mineral sourcing, insulating margin from energy-price volatility. Expand long-term service agreement penetration among China's state-owned steel sector before emerging smart-curtain specialists can establish sensor-embedded product credibility. Prioritize EN ISO 15025 certification maintenance as regulatory deadlines compress competitor R&D timelines.
For New Entrants and Emerging Players: Begin with data center thermal zoning applications in hyperscale computing facilities, where shorter sales cycles and less stringent certification requirements lower barrier to entry. Target United States and Chinese markets for zoned heat containment deployments. Pursue partnership routes with HVAC contractors rather than direct furnace operator sales to bypass entrenched supplier relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale fabricators possessing regional installation capabilities and in-house mineral coating expertise given procurement evolution toward turnkey barrier system providers. Long-term viability hinges on exposure to industrial emissions compliance cycles rather than discretionary capital expenditure. Monitor EU Carbon Border Adjustment Mechanism implementation as inflection signal for low-carbon sourcing premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sourcing | Captive alumina and silica supply insulates margin from energy-price volatility affecting ceramic fiber weavers. |
| Smart Curtain Sensor Integration | Embedded thermocouple networks transform passive barriers into predictive maintenance infrastructure for German automotive foundries. |
| Long-term Service Agreement Expansion | Bundle fabric supply with installation and inspection to displace transactional replacement purchases in China's state-owned steel sector. |
| Data Center Thermal Zoning Entry | Zoned heat containment configurations open non-industrial channel with shorter sales cycles than furnace retrofit cycles. |
| EU CBAM Compliance Positioning | Verified low-carbon mineral sourcing creates first-mover advantage as carbon border adjustments reshape sourcing economics. |
Methodological Framework
Multi-period observation of furnace retrofit procurement cycles, certification timeline compression, and silica fabric capacity buildouts anchored the trend analysis, supplemented by interviews with plant engineers at steel mills and aluminum smelters, procurement directors at integrated manufacturers, ceramic fiber weaving specialists, regulatory compliance officers, and aftermarket service providers. Secondary validation drew from customs and trade data for refractory material flows, SEC 10-K filings of diversified materials suppliers, EU ETS emissions registry disclosures, and Chinese GB standards documentation. Bottom-up volume estimates from end-use application sizing triangulated against top-down market value reconstruction from producer revenue disclosures.
Segment-weighting applied product type, application environment severity, material specification tier, and end-user purchasing authority as core dimensions across the modeling period. CAGRs derived from regression analysis of historical replacement cycle frequencies projected against regulatory compliance deadline clustering and industrial capacity expansion announcements. Forecast inputs incorporated blast furnace operating temperature trends, data center cooling efficiency investment trajectories, and REACH chemical restriction implementation schedules.
Underlying measurement precision varies by segment; fire-resistant curtains in heavy manufacturing carry tighter precision than emerging thermal curtain applications in data centers. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and raw material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Table Linen Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
Duvets Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Bedroom Linen Market