
 Spray Covers Market | 2026-2036
Spray Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Covers Market Outlook
ISO 11611 certification for protective welding and allied processes is collapsing the supplier base for industrial-grade spray covers, forcing smaller fabricators to either upgrade testing capabilities or exit. 3M Company leverages its multi-layer laminate expertise to sustain premium positioning in chemical-resistant segments. DuPont de Nemours anchors agricultural demand through Kevlar-reinforced cover architectures that resist abrasion from crop protection chemicals. Kimberly-Clark competes in disposable cover niches where contamination protocols demand single-use solutions.
Spray covers are engineered protective barriers—typically fabricated from polyethylene, PVC, canvas, or nylon composites—designed to shield surfaces, equipment, and personnel from overspray during coating, painting, or chemical application processes; specifications commonly include mil thickness ratings, tensile strength thresholds, and permeation resistance to solvents or pesticides. Polyethylene dominates volume production due to its cost-efficiency and chemical inertness, while PVC commands margin pools in heavy-duty industrial settings requiring welded seams and reinforced grommets. The agriculture application area leads unit demand as Brazilian and Ukrainian grain operators expand fleet coverage, though automotive refinishing generates the highest per-unit value through color-matched, static-dissipating custom sizes required by OEM collision centers.
EPA regulations on volatile organic compound emissions from coating operations directly shape spray cover material specifications and disposal protocols in the United States. REACH and the EU Green Deal are accelerating substitution of phthalate-based PVC formulations across European supply chains. OSHA workplace exposure limits mandate permeation testing intervals that sustain recurring cover replacement cycles. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as pending bans on PFAS-based water repellents threaten existing performance coatings and force material science pivots toward silicone or bio-based alternatives.
Market Dynamics
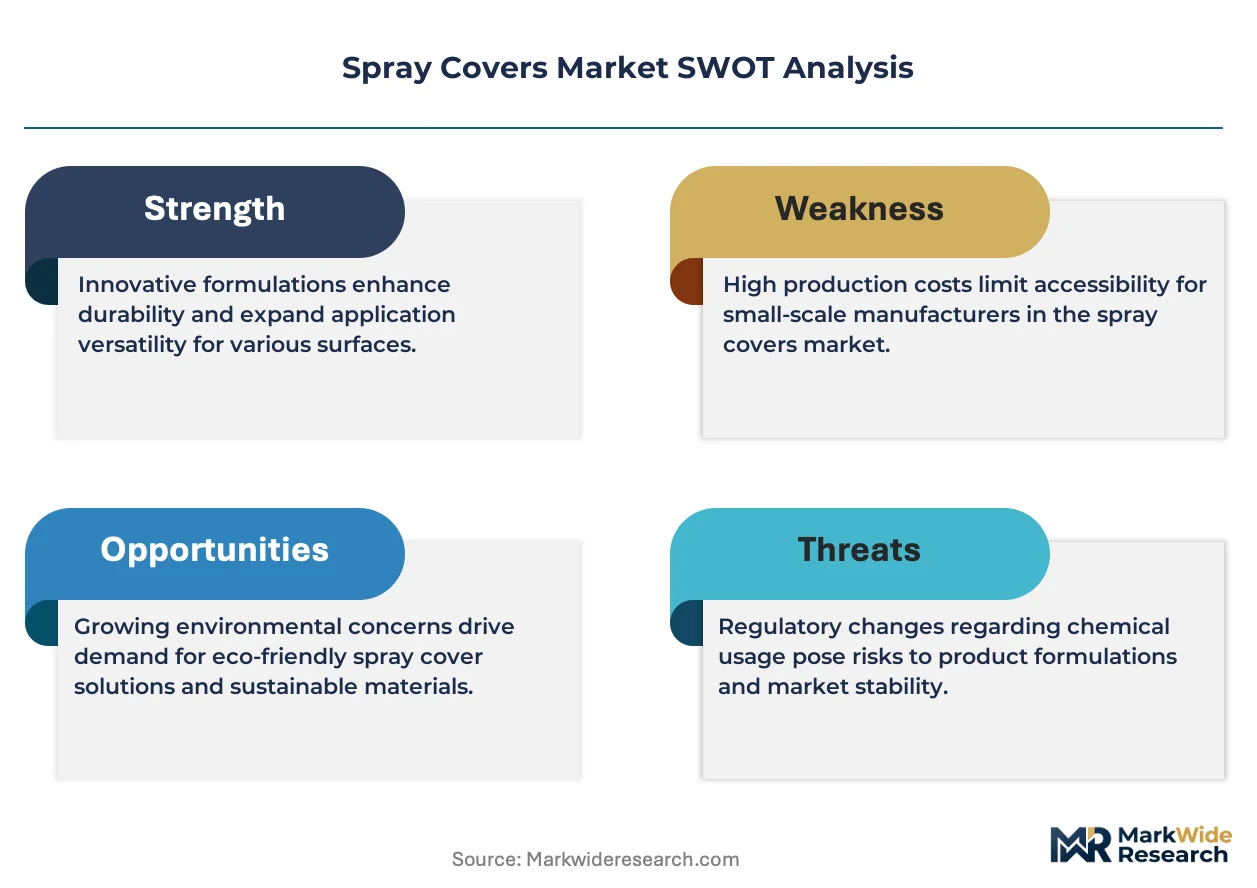
REACH compliance in Europe is collapsing the supplier base for chemical-resistant spray covers, forcing fabricators to abandon phthalate-based PVC formulations and absorb recertification costs that smaller competitors cannot finance.
Growth Catalysts
- Precision farming intensification:Brazilian soybean operators are expanding mechanized spraying fleets, driving cover procurement for equipment protection against crop protection chemical overspray.
- OSHA workplace exposure mandates:Permeation testing intervals for protective barriers sustain recurring replacement cycles in US agricultural and industrial coating operations.
- Multi-layer laminate advances:Enhanced chemical inertness in polyethylene composites is opening premium applications previously reserved for PVC and canvas architectures.
Market Restraints
- Raw material concentration:Polyethylene resin supply concentrates among Gulf Coast petrochemical complexes, exposing cover fabricators to hurricane-related production disruptions.
- PFAS coating phase-out:Pending restrictions on per- and polyfluoroalkyl substance-based water repellents threaten existing performance specifications without mature silicone alternatives.
- ISO 11611 certification barriers:Welding process certification requirements for industrial-grade covers eliminate smaller fabricators lacking in-house testing infrastructure.
Strategic Opportunities
- Ukrainian grain belt expansion:Post-conflict agricultural reconstruction is projected to accelerate mechanized spraying adoption, creating first-mover advantages for cover suppliers.
- EU Green Deal material incentives:Bio-based polymer development programs subsidize R&D into plant-derived alternatives to petroleum-based cover substrates.
- Automotive OEM collision center specifications:Static-dissipating, color-matched custom covers command premium positioning in refinishing operations.
Industry Challenges
- Permeation testing talent scarcity:Qualified laboratory technicians for chemical resistance validation are concentrated among third-party certification bodies, extending product launch timelines.
- Welded seam equipment capex:Heavy-duty industrial cover production requires radio-frequency welding machinery that mid-tier fabricators struggle to finance.
- Legacy cover disposal protocols:EPA hazardous waste classifications for pesticide-contaminated covers impose logistics complexity on agricultural end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Covers Market |
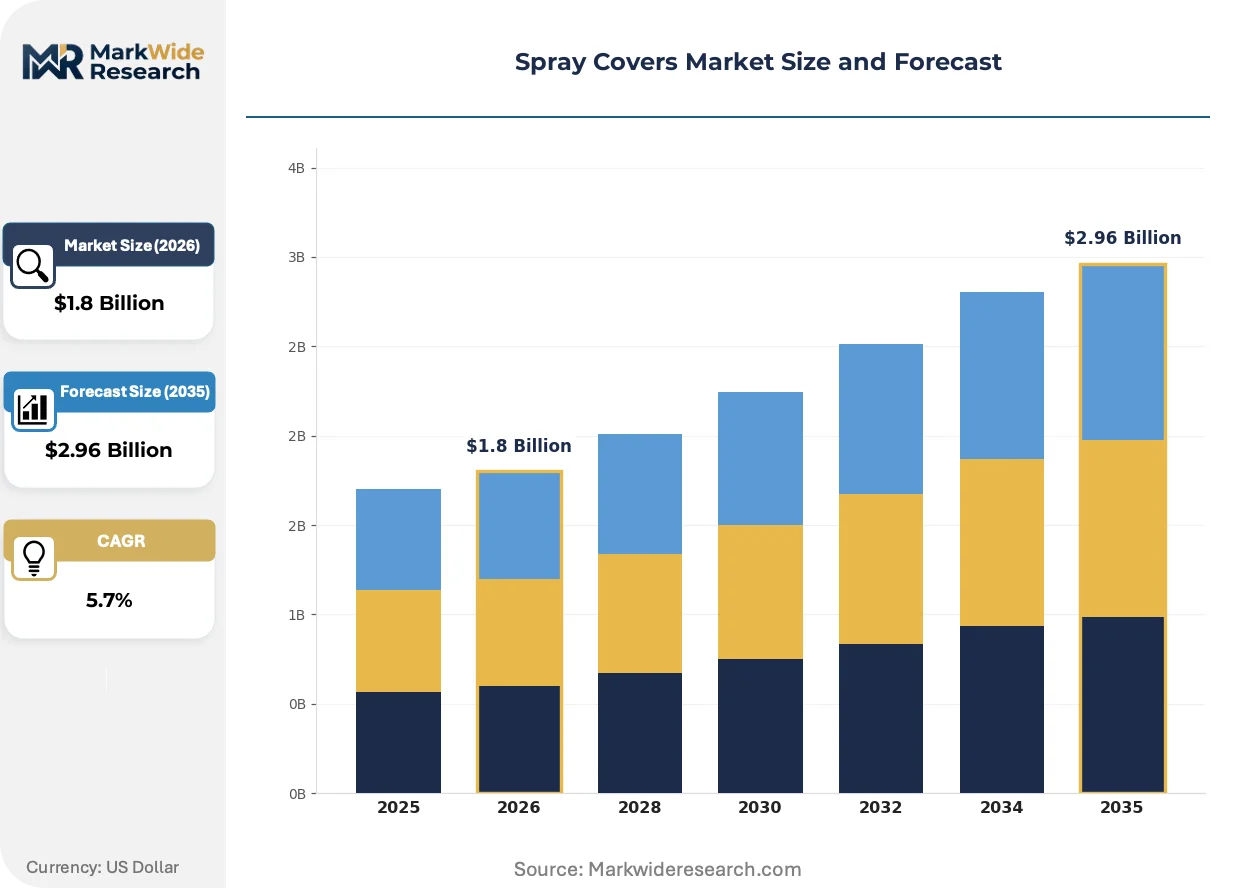
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, PVC, Canvas, Nylon Application Area: Agriculture, Industrial, Construction, Automotive End User: Farmers, Contractors, Manufacturers, Repair Shops Size: Small, Medium, Large, Custom |
| Companies Covered | 3M Company, DuPont de Nemours, Inc., Kimberly-Clark Corporation, Ansell Limited, Alpha Pro Tech, Ltd., Avon Rubber plc, ALPLA, Berry Global, SATA GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Covers Market Strategic Shifts
Material science pivots and regulatory chemistry bans are actively restructuring competitive positioning across spray cover manufacturing, with certification requirements and sustainability mandates compressing the addressable supplier base.
Silicone-based water repellent coatings are displacing legacy PFAS treatments in agricultural and industrial cover specifications. Brazilian grain operators are piloting these formulations at scale to preempt regulatory exclusion. The transition is compressing margins for incumbent coating suppliers while creating entry points for specialty chemical firms with silicone expertise.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC cover fabricators to reformulate or exit European supply chains. The industrial consequence is a supply contraction for welded-seam heavy-duty applications. German automotive refinishing centers are responding by qualifying TPU-laminated alternatives that bypass phthalate constraints entirely.
Collision centers are consolidating cover procurement through distributor-managed inventory programs rather than direct manufacturer relationships. This channel compression disadvantages smaller fabricators lacking national distribution partnerships. The shift is most visible in US metropolitan markets where multi-shop operators dominate automotive refinishing volume.
Spray Covers Market Segmentation
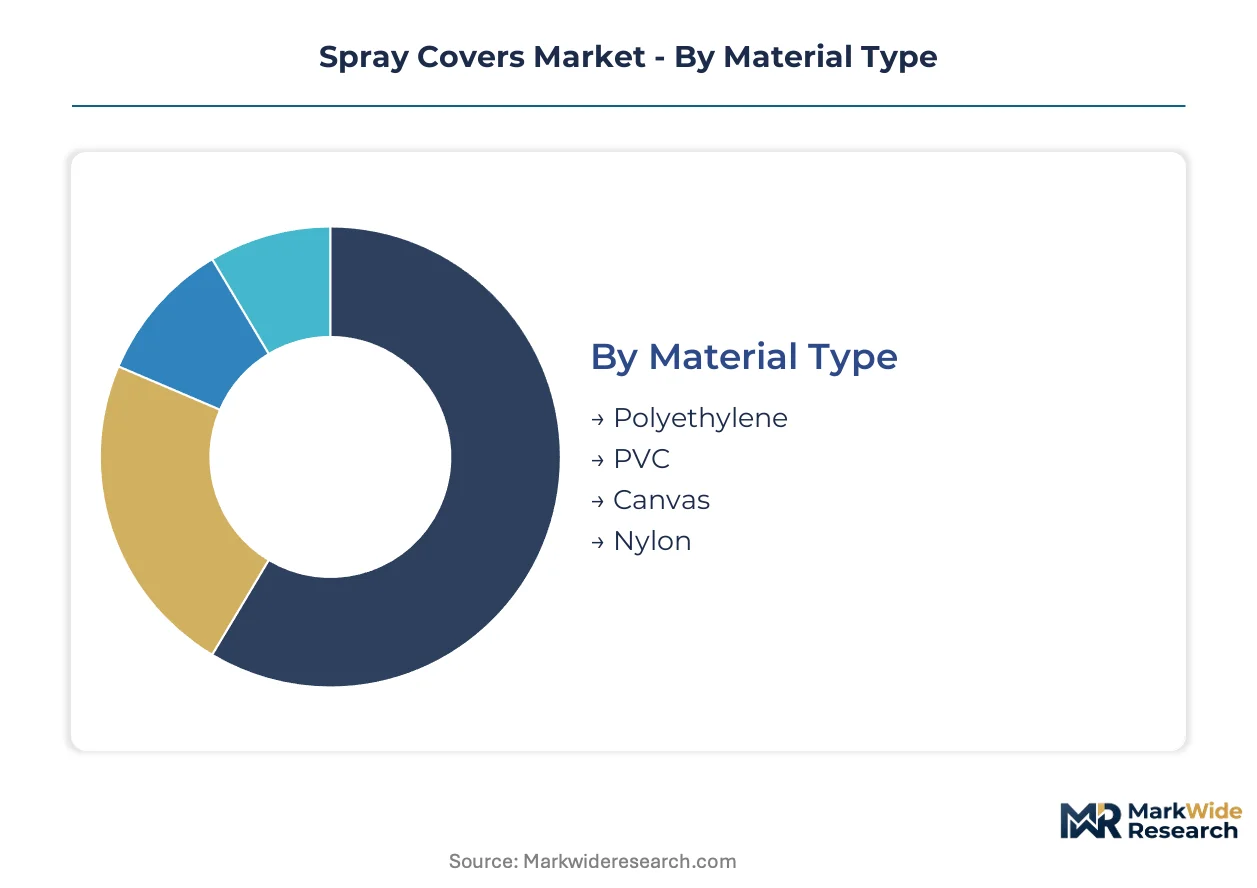
Material substitution pressures and regulatory chemistry bans are fragmenting competitive positioning across spray cover manufacturing, with certification requirements and sustainability mandates compressing the addressable supplier base in each segment category.
Material Type:
Polyethylene faces intensifying substitution pressure from bio-based polymer alternatives as EU Green Deal subsidies accelerate R&D into plant-derived substrates.
- Polyethylene:Low-density and high-density formulations dominate volume production through cost-efficiency and chemical inertness. Brazilian soybean operators are expanding fleet coverage of polyethylene-based equipment protection as mechanized spraying intensifies across the Mato Grosso belt.
- PVC:Heavy-duty industrial applications require welded seams and reinforced grommets for chemical resistance. REACH Annex XVII phthalate restrictions are forcing European fabricators to reformulate or exit, collapsing the supplier base for welded-seam architectures.
- Canvas:Breathable natural fiber construction suits temporary outdoor applications where moisture management matters. German automotive refinishing centers are qualifying canvas alternatives for specific overspray scenarios.
- Nylon:Abrasion-resistant synthetic weave supports high-cycle deployment in construction and repair environments. Ukrainian grain belt reconstruction is projected to accelerate nylon cover procurement for mechanized spraying fleets.
Polyethylene anchors the volume base while PVC gains share at the steepest rate in premium industrial applications despite regulatory headwinds.
Application Area:
Margin concentration varies sharply across application areas, with automotive refinishing commanding premium positioning through color-matched, static-dissipating custom specifications.
- Agriculture:Equipment protection against crop protection chemical overspray drives unit demand. Brazilian and Ukrainian grain operators are expanding fleet coverage as precision farming intensifies mechanized spraying adoption.
- Industrial:Coating and painting operations require permeation-resistant barriers meeting OSHA workplace exposure mandates. EPA volatile organic compound regulations directly shape material specifications and disposal protocols in US manufacturing facilities.
- Construction:Temporary surface protection during exterior finishing and waterproofing applications. Contractors prioritize tear resistance and rapid deployment in multi-site project environments.
- Automotive:OEM collision centers demand static-dissipating, color-matched custom covers for refinishing operations. Distributor-managed inventory programs are consolidating procurement through national partnerships, compressing margins for smaller fabricators.
Agriculture anchors the volume base while automotive climbs the fastest on per-unit value premiums.
End User:
Procurement authority is shifting from direct manufacturer relationships to distributor-managed programs, altering competitive access for each end user category.
- Farmers:Individual and cooperative agricultural operators prioritize cost-efficient polyethylene covers for seasonal equipment protection. Brazilian soybean belt expansion is concentrating demand among large-scale mechanized operators.
- Contractors:Multi-site construction and industrial service firms require rapid-deployment covers with standardized sizing. Inventory program consolidation favors fabricators with national distribution partnerships.
- Manufacturers:In-house coating and finishing operations mandate permeation testing intervals that sustain recurring replacement cycles. OSHA compliance documentation requirements extend product launch timelines.
- Repair Shops:Automotive collision and refinishing centers specify static-dissipating custom sizes. US metropolitan multi-shop operators dominate volume procurement through consolidated distributor channels.
Farmers anchor the volume base while manufacturers expand most quickly on regulatory-driven replacement cycles.
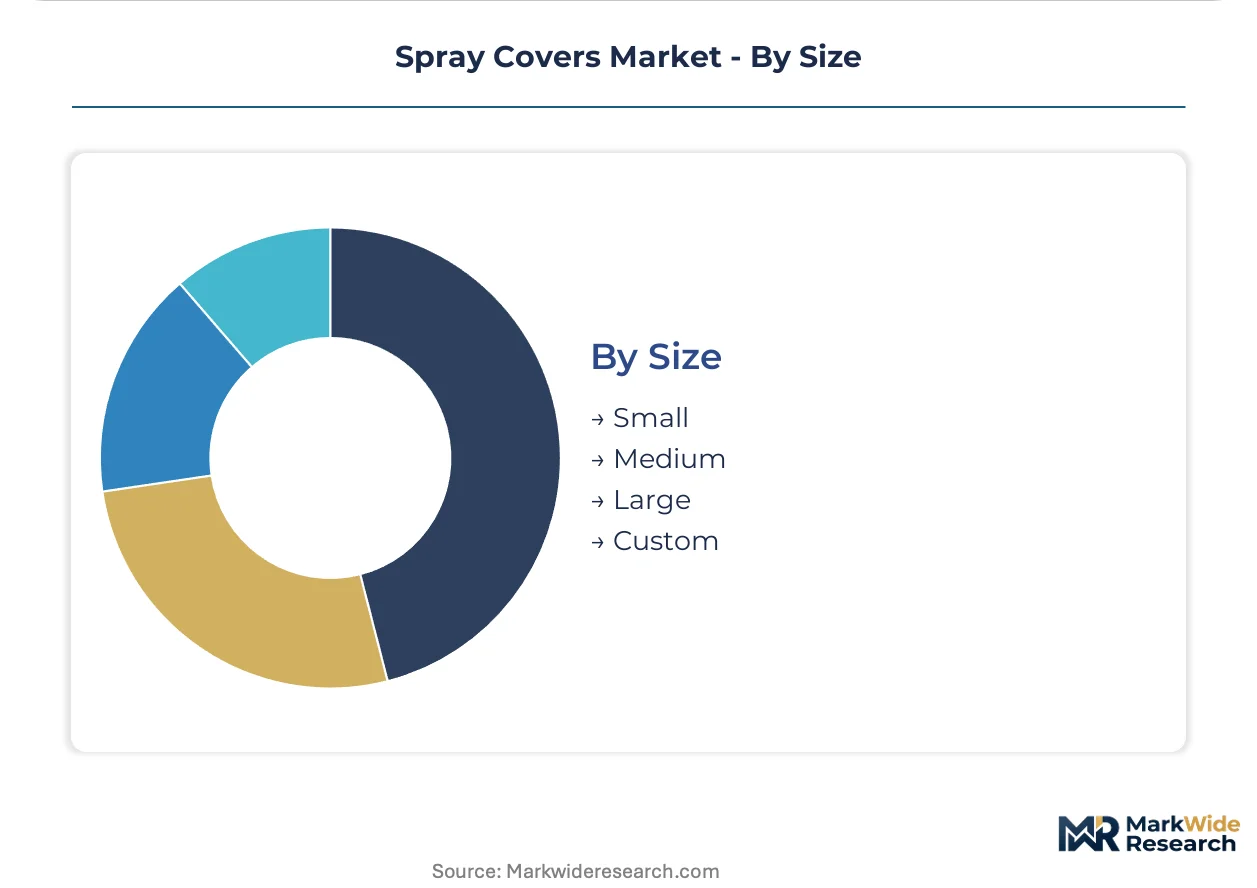
Size:
Customization intensity correlates directly with application premiumization, with automotive and industrial specifications driving bespoke dimension requirements.
- Small:Compact covers for handheld equipment and targeted surface protection. Repair shops and specialty contractors favor rapid-deployment formats.
- Medium:Standard equipment dimensions for agricultural machinery and industrial spray systems. Brazilian fleet operators specify medium covers for tractor-mounted sprayer protection.
- Large:Extended surface coverage for construction sites and manufacturing facility floors. German automotive refinishing centers deploy large formats for booth protection.
- Custom:Dimension-specific, color-matched, and static-dissipating specifications for OEM collision centers. Radio-frequency welding equipment requirements for heavy-duty custom formats disadvantage mid-tier fabricators.
Medium sizes anchor the volume base while custom specifications gain share fastest on automotive premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal subsidies and REACH Annex XVII enforcement are accelerating material substitution across European supply chains, while Brazilian agricultural mechanization and US OSHA mandates sustain replacement-driven demand in the Americas.
United States
OSHA workplace exposure limits for chemical permeation sustain recurring cover replacement cycles across agricultural and industrial coating operations. EPA volatile organic compound regulations directly shape material specifications and disposal protocols for pesticide-contaminated covers. Gulf Coast petrochemical complexes concentrate polyethylene resin supply, exposing fabricators to hurricane-related production disruptions.
Germany
Automotive refinishing centers in Stuttgart and Munich are qualifying TPU-laminated alternatives to phthalate-constrained PVC architectures. REACH Annex XVII restrictions on phthalate plasticizers force fabricators to reformulate or exit European supply chains. The Eindhoven-Randstadt corridor channels distributor-managed inventory programs that consolidate procurement for collision center networks.
Brazil
Soybean operators across the Mato Grosso belt are expanding mechanized spraying fleets, driving polyethylene cover procurement for equipment protection. ANVISA alignment with international chemical safety standards tightens material specifications for crop protection chemical resistance. São Paulo-based distributors are piloting silicone-based water repellent formulations to preempt PFAS regulatory exclusion.
China
MIIT industrial standards for protective equipment are elevating certification requirements for chemical-resistant cover exports. Dual carbon goals accelerate R&D into bio-based polymer alternatives to petroleum-derived substrates. Yangtze River Delta manufacturing clusters concentrate radio-frequency welding equipment capacity for heavy-duty industrial cover production.
Ukraine
Post-conflict agricultural reconstruction is projected to accelerate mechanized spraying adoption among grain belt operators. National recovery programs prioritize equipment protection infrastructure for restored farming operations. Black Sea port cities are emerging as logistics hubs for cover procurement serving reconstructed spraying fleets.
Spray Covers Market Competitive Environment
Listed leaders compete with private specialists across certification-intensive segments, creating a tiered structure where scale advantages concentrate among multi-layer laminate specialists while regional fabricators serve cost-sensitive agricultural demand. Strategic archetypes include diversified materials conglomerates with captive polymer science capabilities, protective equipment specialists with established testing infrastructure, and regional converters focused on polyethylene volume production. Competitive moves center on distributor partnership consolidation and in-house permeation testing capacity expansion.
Within the diversified materials tier, 3M Company and DuPont de Nemours occupy positions anchored by multi-layer laminate expertise and reinforced fabric architectures respectively. Kimberly-Clark exemplifies the disposable cover specialist archetype where contamination protocols demand single-use solutions. These three listed entities represent distinct competitive vectors: chemical-resistant premium positioning, abrasion-resistant agricultural durability, and regulatory-compliant disposability.
| Leading Market Players |
|---|
| 3M Company |
| DuPont de Nemours, Inc. |
| Kimberly-Clark Corporation |
| Ansell Limited |
| Alpha Pro Tech, Ltd. |
| Avon Rubber plc |
| ALPLA |
| Berry Global |
| SATA GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Silicone-based water repellent coatings displacing legacy PFAS treatments are redrawing raw material sourcing maps toward specialty chemical producers in Germany and Japan while compressing margins for incumbent coating suppliers. This substitution simultaneously elevates input costs for cover fabricators and fragments pricing power across the value chain.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 11611-certified industrial covers commanding substantial premiums over uncertified agricultural equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects permeation testing depth, seam welding quality, and chemical resistance ratings. Cost compression in the economy tier is intensifying because Brazilian soybean operators are consolidating procurement through São Paulo-based distributors. Farmers and individual agricultural operators exhibit the highest price sensitivity, while German automotive collision centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate among US agricultural distributors responding to seasonal spraying cycles, while European fabricators maintain strategic stockpiles of phthalate-free PVC formulations to buffer REACH compliance transitions. Polyethylene resin supply concentrates in US Gulf Coast petrochemical complexes, China Yangtze River Delta manufacturing clusters, and Saudi Arabian feedstock operations. Raw material dependencies rest on ethylene feedstock availability, radio-frequency welding equipment capacity, and specialty silicone coating chemicals. Single-source vulnerability in Gulf Coast resin production exposes fabricators to hurricane-related disruptions. Distribution runs through distributor-managed inventory programs consolidating procurement authority away from direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distributor-managed inventory programs are transforming spray cover procurement into a platform-mediated ecosystem where national partnership access determines competitive viability rather than manufacturing scale alone.
For Market Incumbents: Secure exclusive distributor partnerships with São Paulo-based agricultural supply networks and German automotive refinishing consortia to lock out mid-tier competitors lacking national coverage. Invest in captive permeation testing laboratories to compress product launch timelines and meet OSHA documentation requirements. The threat of silicone coating suppliers forward-integrating into finished cover production elevates backward integration into specialty chemical formulation as a defensive priority. For New Entrants and Emerging Players: Anchor in Ukrainian post-conflict agricultural reconstruction where mechanized spraying fleet rebuilds create first-mover advantages absent entrenched supplier relationships. Target the nylon cover segment for grain belt equipment protection, where abrasion resistance specifications favor synthetic weave expertise over laminate complexity. Pursue a technical partnership route with Yangtze River Delta radio-frequency welding equipment providers to bypass capital barriers blocking heavy-duty industrial entry. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated specialists with in-house certification infrastructure and captive polymer science capabilities. Long-term viability over the coming decade rests on positioning ahead of PFAS phase-outs and REACH Annex XVII expansion. Acquisition targets should display established testing laboratory assets and existing distributor network density. Watch for ANVISA alignment with international chemical safety standards as the inflection signal triggering accelerated consolidation among Brazilian market participants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Coating Formulation | Captures margin pools threatened by PFAS phase-out while securing supply continuity for water-repellent specifications. |
| In-House Permeation Testing Laboratory Buildout | Compresses product launch timelines and satisfies OSHA compliance documentation requirements without third-party bottlenecks. |
| Distributor Partnership Consolidation | Locks access to São Paulo agricultural networks and German automotive collision center procurement programs. |
| TPU-Laminated Alternative Qualification | Bypasses REACH Annex XVII phthalate constraints entirely for European welded-seam heavy-duty applications. |
| Bio-Based Polymer R&D Program | Positions for EU Green Deal subsidy capture as plant-derived substrates displace petroleum-based polyethylene volume. |
Study Parameters
Initial hypotheses were tested against primary input from agricultural equipment fleet managers, automotive collision center procurement directors, industrial coating operation safety officers, and specialty chemical coating formulators and refined through secondary validation. Sources included customs and trade data for polyethylene resin flows, ECHA REACH Annex XVII regulatory filings, SEC 10-K disclosures from listed materials conglomerates, and Brazilian ANVISA chemical safety alignment documentation. Bottom-up demand modeling from end-user procurement patterns was triangulated against top-down supply capacity assessments.
Variance decomposition across material type, application area, end user category, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed polyethylene versus PVC versus bio-based substrate chemistry, agriculture versus automotive versus industrial end-use, and certified versus uncertified performance tiers. CAGRs were derived from installed base expansion rates, replacement cycle frequencies driven by OSHA permeation testing mandates, and regulatory-driven material substitution elasticities. Forecast inputs included Brazilian soybean belt mechanization intensity and Ukrainian grain belt reconstruction timelines.
Material uncertainties — REACH Annex XVII expansion scope, PFAS restriction finalization timelines, and Gulf Coast hurricane disruption frequency — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and petrochemical supply continuity. Revision becomes warranted when ANVISA chemical safety alignment accelerates beyond baseline trajectories or silicone coating cost curves cross PFAS parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
North America Awnings Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
India Outdoor Furniture Market
Outdoor Decor
Adirondack Chairs Market
Outdoor Decor
Outdoor Dining Table Market
Outdoor Decor
Outdoor Cushions Market
Outdoor Decor
Sun Lounger Market
Outdoor Decor
Outdoor Kitchen Cabinets Market
Outdoor Decor
Patio Furniture Market
Outdoor Decor
United States Outdoor Furniture Market
Outdoor Decor
Luxury Outdoor Furniture Market
Outdoor Decor
Retractable Awnings Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
North America Residential Outdoor Gas Fire Pits Market
Outdoor Decor
Europe Awnings Market
Outdoor Decor
Middle-East Christmas Tree Market