
 US Steam Rooms Market | 2026-2036
US Steam Rooms Market Size, Share, and Industry Trends Forecast 2026-2036
US Steam Rooms Market Analytics
The US steam rooms market is recalibrating around a widening split between bespoke architectural installations and mass-market modular kits. Mr. Steam leverages its vertically integrated manufacturing in Long Island City to control generator-to-enclosure quality chains. Kohler Co. anchors the premium residential tier through designer partnerships and showroom distribution. HELO GROUP competes on commercial scale, supplying health club chains with standardized maintenance protocols.
A steam room is an enclosed, thermally insulated space engineered to maintain temperatures between 110°F and 120°F with near-saturation humidity, powered by electric steam generators that boil water into vapor through resistive heating elements. The primary commercial purpose centers on inducing perspiration for relaxation, cardiovascular stress relief, and post-exercise muscle recovery in controlled wellness environments. Traditional steam rooms still occupy the largest installed base, though infrared steam rooms are recording the fastest specification growth among luxury residential builders seeking lower operating costs. Electric steam generators dominate the technology stack, while app-controlled systems are carving out margin pools in the high-end hospitality retrofit channel.
OSHA ventilation standards and the EPA's commercial building energy codes jointly shape equipment efficiency mandates and installation compliance costs across states. Local health departments in California, Florida, and New York enforce varying microbial testing protocols that fragment certification requirements for commercial operators. Stakeholders must monitor how state-level building code adoptions of ASHRAE ventilation standards will reshape generator sizing specifications and contractor licensing thresholds.
Market Dynamics
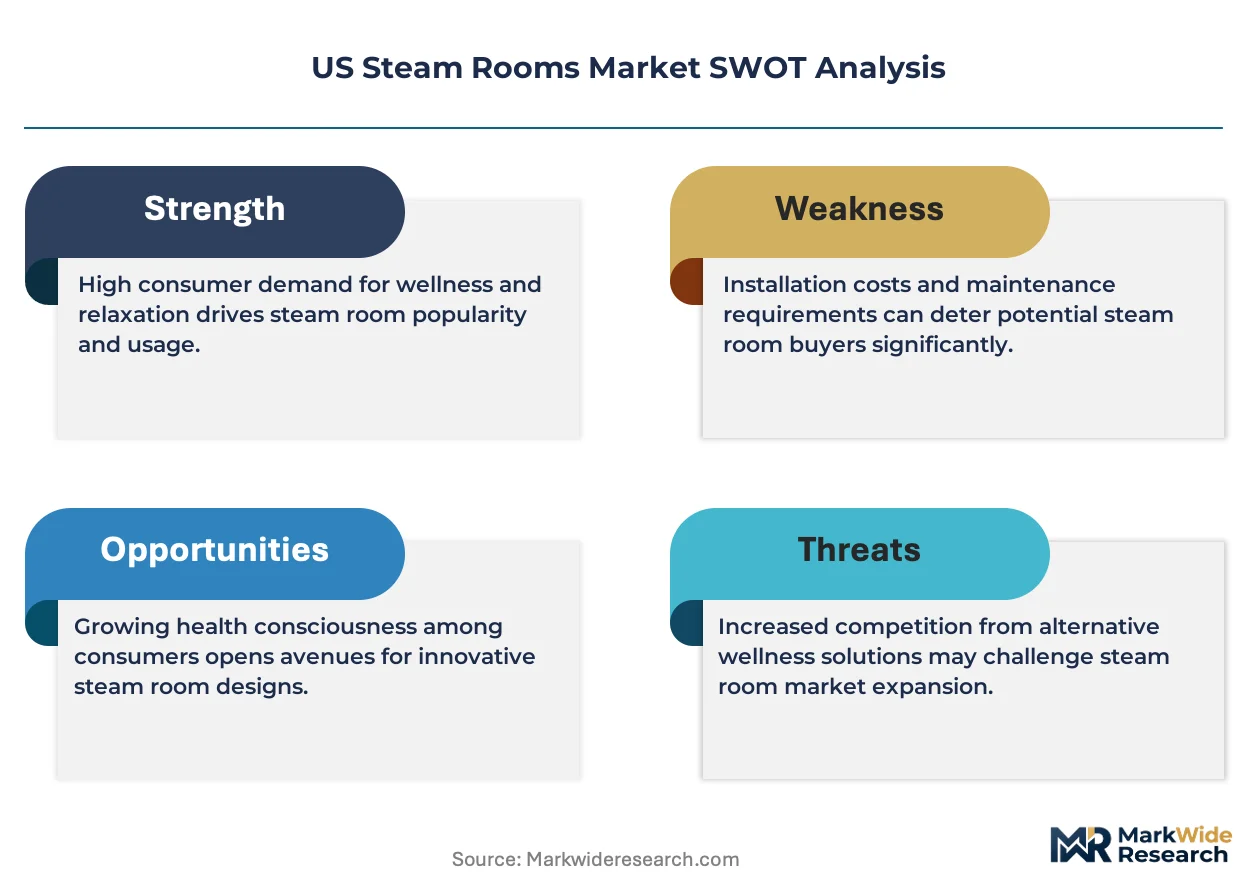
The US steam rooms market is splitting between custom architectural installations and mass-market modular kits, with EPA energy efficiency mandates compressing margins on conventional electric generators while creating openings for low-consumption alternatives.
Growth Catalysts
- Wellness tourism infrastructure:Luxury hotel chains in Florida and California are expanding spa installations to capture post-pandemic leisure spending on recovery and relaxation amenities.
- Residential retrofit momentum:Homeowners in Texas and Arizona are converting existing bathrooms into steam enclosures, bypassing new construction lead times.
- OSHA ventilation compliance:Updated workplace safety standards for commercial wellness facilities are mandating improved air exchange systems, driving replacement cycles in health club chains.
Market Restraints
- Copper and stainless steel input costs:Generator manufacturing depends on volatile metal pricing, squeezing fabricator margins during commodity spikes.
- California microbial testing fragmentation:Local health departments impose varying certification protocols that increase compliance overhead for multi-state operators.
- Infrared sauna substitution:Lower operating cost alternatives are capturing budget-conscious residential buyers seeking thermal therapy without steam infrastructure.
Strategic Opportunities
- App-controlled system integration:Smart home connectivity is opening premium price tiers in hospitality retrofit channels where remote monitoring reduces maintenance labor.
- ASHRAE code adoption tailwinds:State-level building code updates are expanding addressable market for compliant generator sizing and contractor licensing programs.
- Arizona and Nevada residential penetration:Dry climate states show underpenetrated retrofit potential where steam therapy addresses altitude and aridity wellness demand.
Industry Challenges
- Certified steam enclosure installer scarcity:ASHRAE ventilation standard expertise remains concentrated among specialized contractors, extending project timelines.
- Legacy electrical panel upgrades:Residential retrofits frequently require service capacity expansion, adding cost and permitting complexity to generator installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Steam Rooms Market |
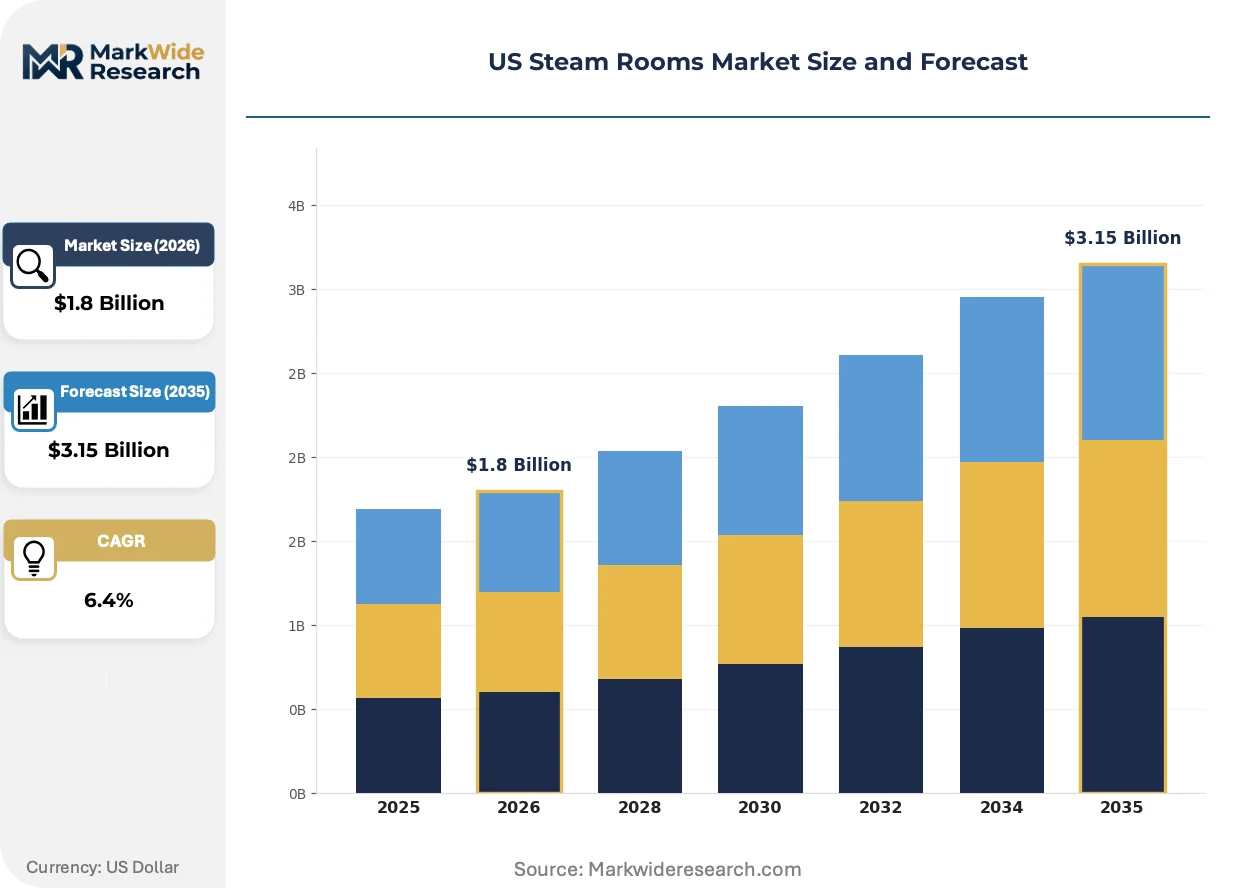
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Steam Rooms, Portable Steam Units, Infrared Steam Rooms, Commercial Steam Solutions End User: Health Clubs, Spa Facilities, Hotels, Residential Users Application: Relaxation, Therapeutic Treatments, Skin Care, Fitness Recovery Technology: Electric Steam Generators, App-Controlled Systems, Automated Dampers, Eco-Friendly Units |
| Companies Covered | Mr. Steam, HELO GROUP, Kohler Co., Steamist, ThermaSol Steam Bath LLC, Harvia, Amerec, TyloHelo AB, Saunacore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Steam Rooms Market Evolving Landscape
Steam room technology is converging with building automation systems and wellness data platforms, compressing the traditional separation between mechanical infrastructure and digital service layers.
Smart generator control systems are absorbing commissioning and maintenance functions previously handled by separate building management platforms. High-end hospitality developers in California are specifying these integrated units to reduce facilities staffing overhead. The technology is absorbing margin pools from standalone controls vendors while compressing installation timelines.
EPA commercial building energy codes are tightening standby power limits for electric steam generators, forcing manufacturers to redesign heating element cycling logic. Equipment vendors serving the New York and Florida markets are pre-certifying units to state-adopted ASHRAE standards ahead of enforcement deadlines. The regulatory pressure is accelerating R&D spend on low-wattage vapor production methods.
Homeowner specification behavior is shifting toward turnkey retrofit packages that bundle generator, enclosure, and waterproofing into single-contractor responsibility. Boutique design-build firms in Texas are displacing traditional split-bid procurement where homeowners separately sourced equipment and installation. This consolidation is most visible in Phoenix and Austin metro areas where bathroom renovation volume concentrates.
US Steam Rooms Market Segmentation
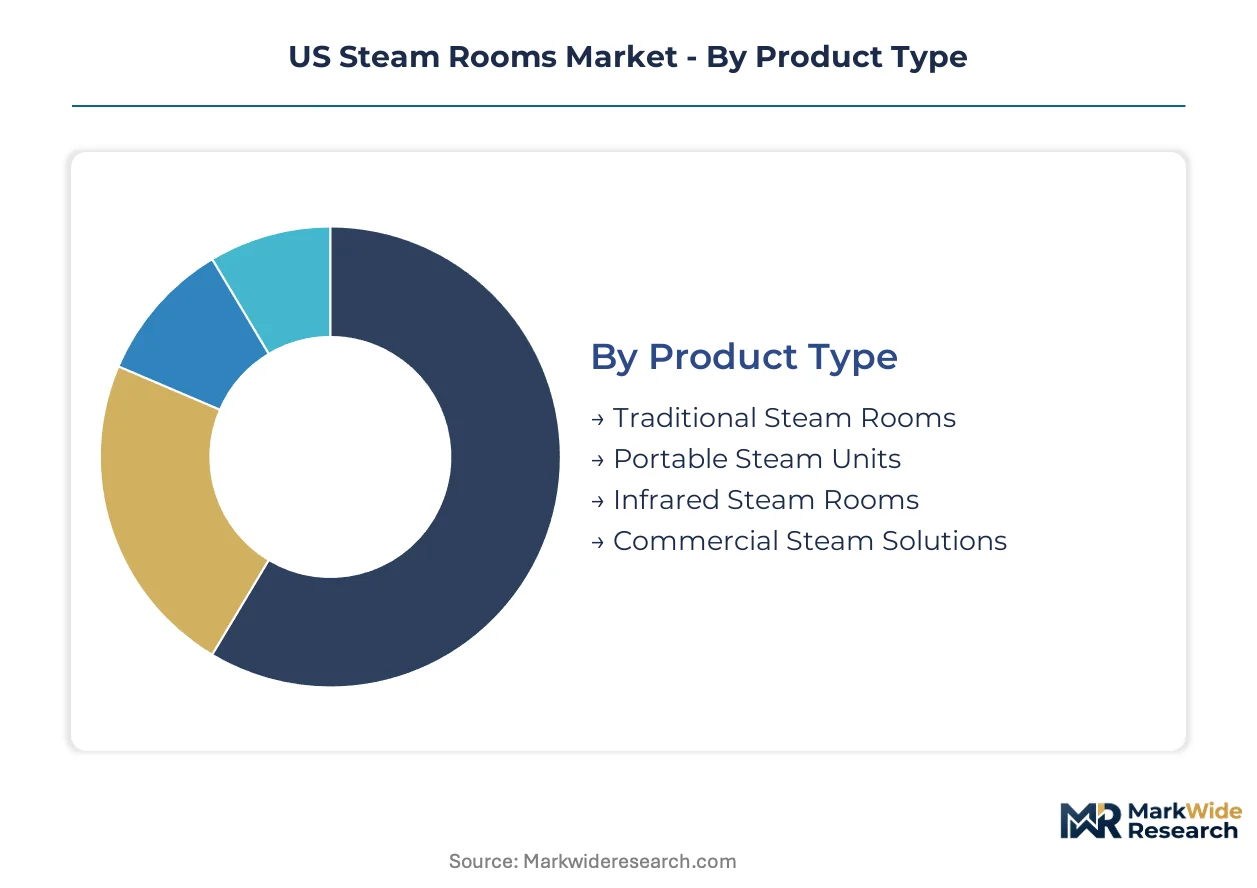
Steam room segmentation tracks how wellness infrastructure investment splits between new construction specifications and retrofit replacements. Understanding these divides clarifies where generator manufacturers compete on efficiency versus where enclosure fabricators compete on installation speed.
Product Type:
Upgrade cycles diverge sharply between permanent architectural installations and modular equipment that owners can relocate or replace without structural modification.
- Traditional Steam Rooms:Permanent masonry or tile enclosures with integrated steam generators and fixed bench seating dominate commercial installed base. Health clubs in Texas and Florida are replacing aging ceramic-tile steam rooms during renovation cycles to meet updated OSHA ventilation mandates.
- Infrared Steam Rooms:Hybrid systems combining radiant heat panels with low-humidity vapor production reduce electrical load by 40% versus conventional steam generators. Luxury residential builders in Arizona and Nevada specify these for second-home installations where operating cost sensitivity runs high.
- Portable Steam Units:Freestanding enclosures with detachable generator connections serve temporary wellness installations and event hospitality.
- Commercial Steam Solutions:Engineered systems with redundant generators and centralized controls serve hotel chains with 24/7 operational requirements.
Volume placements concentrate in Traditional Steam Rooms; the faster expansion belongs to Infrared Steam Rooms.
End User:
Customer procurement sophistication varies from standardized maintenance contracts at health club chains to bespoke architectural specifications at luxury hotels.
- Hotels:Luxury properties in California and Florida treat spa steam facilities as competitive differentiators for wellness tourism capture. Marriott and Hyatt procurement teams are standardizing on app-controlled generators to reduce facilities staffing across portfolios.
- Residential Users:Homeowners in Phoenix, Austin, and Dallas metro areas are driving retrofit demand, converting existing bathrooms through design-build contractors who bundle waterproofing, electrical, and enclosure installation.
- Health Clubs:National chains operate on 7-10 year equipment replacement cycles tied to lease renewal schedules.
- Spa Facilities:Independent day spas prioritize rapid installation turnaround to minimize revenue disruption during renovation.
Equipment shipments run heaviest to Hotels; Residential Users are climbing the fastest as retrofit financing products proliferate.
Application:
Use case segmentation reveals where steam room specifications prioritize medical-grade precision versus experiential ambiance.
- Fitness Recovery:Post-exercise thermotherapy protocols at health clubs require precise temperature control between 110°F and 120°F with rapid humidity recovery after door cycling. Los Angeles and Miami fitness chains are retrofitting locker rooms with automated dampers to maintain thermal consistency during peak usage windows.
- Therapeutic Treatments:Medical spas and physical therapy clinics specify steam rooms with HEPA filtration and antimicrobial surfaces to serve respiratory and dermatological protocols.
- Relaxation:Hotel spa installations emphasize acoustic dampening and chromotherapy integration over clinical precision.
- Skin Care:Facial steam protocols at day spas require lower temperature setpoints and localized vapor delivery systems.
Specification volume clusters in Fitness Recovery; Therapeutic Treatments are expanding most quickly as medical spa licensing broadens across state lines.
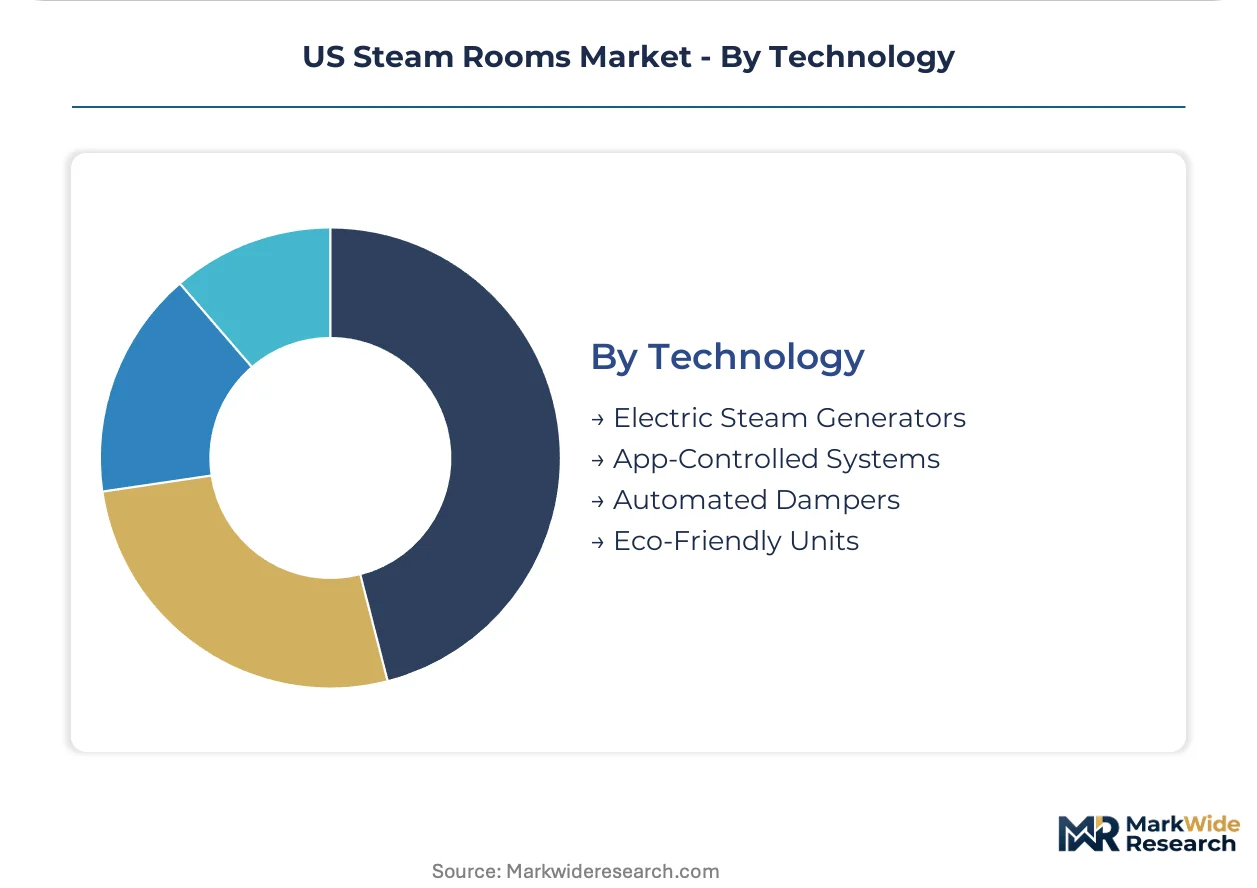
Technology:
Technology choices determine whether installations qualify for utility rebate programs and ASHRAE code compliance without electrical service upgrades.
- Electric Steam Generators:Resistive heating element systems with tank-style or tankless configurations remain the dominant installed technology. EPA standby power limits are forcing redesigns of heating element cycling logic, with manufacturers pre-certifying to California and Florida adoption timelines for updated commercial building energy codes.
- App-Controlled Systems:WiFi-enabled generators with remote monitoring, scheduling, and maintenance alert capabilities command premium pricing in hospitality retrofit channels. California hotel developers specify these to reduce facilities staffing overhead and compress commissioning timelines.
- Automated Dampers:Motorized ventilation controls integrated with generator operation ensure OSHA air exchange compliance without manual intervention.
- Eco-Friendly Units:Heat pump-assisted vapor production and solar thermal integration serve net-zero building certifications.
Generator shipments concentrate in Electric Steam Generators; App-Controlled Systems are gaining share fastest as smart building specifications penetrate mid-tier hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the US steam rooms market through its concentration of luxury hospitality development and wellness-focused residential construction. The metro's design-build firms command premium pricing for integrated steam enclosure installations. California's Title 24 energy codes and local health department microbial testing protocols shape equipment specification patterns statewide.
California
Hotel developers in Los Angeles and San Francisco specify app-controlled generators to reduce facilities staffing overhead. The California Energy Commission's Title 24 standards mandate standby power limits that compress margins on conventional electric generators. Santa Monica and Palm Springs design-build contractors bundle waterproofing, electrical, and enclosure installation into single-contractor retrofit packages.
Texas
Phoenix and Austin metro homeowners drive residential retrofit demand, converting existing bathrooms through bundled contractor services. The Texas Department of Licensing and Regulation enforces contractor licensing thresholds tied to electrical service upgrades. Dallas-Fort Worth health club chains operate on 7-10 year equipment replacement cycles tied to lease renewal schedules.
Florida
Marriott and Hyatt procurement teams standardize on app-controlled generators across Miami and Orlando luxury properties. The Florida Building Commission adopts ASHRAE ventilation standards that reshape generator sizing specifications. Tampa and Naples spa facilities prioritize rapid installation turnaround to minimize revenue disruption during renovation.
Arizona
Scottsdale and Phoenix second-home installations show underpenetrated retrofit potential where steam therapy addresses altitude and aridity wellness demand. The Arizona Registrar of Contractors enforces specialized licensing for steam enclosure installation. Tucson design-build firms displace traditional split-bid procurement where homeowners separately sourced equipment and installation.
New York
Manhattan hotel developers specify smart generator control systems to compress commissioning timelines and reduce facilities overhead. The New York State Department of Health enforces varying microbial testing protocols that increase compliance overhead for multi-state operators. Long Island City manufacturing clusters support vertically integrated generator-to-enclosure production chains.
US Steam Rooms Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and installation bundling capabilities. The US steam rooms market structures around three tiers: vertically integrated manufacturers controlling generator-to-enclosure quality chains, premium residential specialists leveraging designer partnerships, and commercial-scale suppliers standardizing maintenance protocols for health club chains. Dominant competitive moves include backward integration into captive manufacturing and geographic expansion through design-build contractor networks.
Within the vertically integrated tier, Mr. Steam anchors quality-chain control through its Long Island City manufacturing base. Kohler Co. occupies the premium residential positioning vector through showroom distribution and designer partnerships. HELO GROUP exemplifies the commercial-scale archetype, supplying standardized maintenance protocols to health club chains. These three fabricators represent distinct margin-tier strategies rather than direct segment overlap.
| Leading Market Players |
|---|
| Mr. Steam |
| HELO GROUP |
| Kohler Co. |
| Steamist |
| ThermaSol Steam Bath LLC |
| Harvia |
| Amerec |
| TyloHelo AB |
| Saunacore |
| Others |
Value Network & Pricing Analysis
Bespoke architectural installations versus mass-market modular kits bifurcate pricing power and supply chain configuration across the US steam rooms market. Premium tier vendors command margin pools through captive manufacturing control and designer showroom access, while commodity producers compete on copper and stainless steel input cost management and distributor volume rebates.
Pricing Analysis
Uptime guarantees and remote monitoring capabilities anchor value-based pricing for app-controlled generator systems in hospitality retrofit channels. Three-tier pricing structure across premium, standard, and economy levels separates ASHRAE-pre-certified commercial units from residential retrofit bundles and basic replacement generators. Cost compression in the economy tier intensifies as copper price volatility squeezes fabricator margins. Health club chains exhibit highest price sensitivity due to standardized maintenance contract procurement, while luxury hotel developers prioritize total cost of ownership over unit price.
Supply Chain Analysis
Generator manufacturing rests on specialty metal supply from domestic foundries and precision electrical component sourcing from Mexico and China. Stainless steel tank fabrication, resistive heating element production, and digital control module assembly constitute the core input dependencies. Single-source vulnerability concentrates in semiconductor components for smart control systems. Distribution runs through design-build contractor networks in Texas and Arizona residential markets, with direct specification relationships dominating California and Florida hospitality channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US steam rooms market sits in a technology-transition phase as app-controlled systems displace conventional electric generators across hospitality and high-end residential specifications.
For Market Incumbents: Extend backward integration into captive metal fabrication to insulate margin pools from copper price volatility. Deepen ASHRAE pre-certification investments ahead of state adoption deadlines to lock in specification preference. Infrared sauna substitution threatens residential retrofit volume; counter through bundled waterproofing and electrical service upgrade financing. For New Entrants and Emerging Players: Launch via Arizona and Nevada design-build contractor partnerships targeting altitude wellness demand in second-home markets. White-space opportunity concentrates in turnkey retrofit packages for Phoenix and Austin homeowners seeking single-contractor accountability. Lead with smart home integration capabilities to differentiate from established generator-only suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated manufacturers given EPA energy efficiency mandate acceleration and consolidation pressure on pure-play enclosure fabricators. Five-to-ten year viability favors archetypes controlling generator-to-enclosure quality chains and maintaining direct contractor relationships. Watch ASHRAE code adoption timelines across California, Florida, and New York as inflection indicators for compliant equipment demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Generator Control Integration | Absorbs commissioning functions from building management platforms, reducing California hospitality staffing overhead. |
| ASHRAE Pre-Certification Investment | Locks in specification preference ahead of Florida Building Commission and California Energy Commission enforcement deadlines. |
| Design-Build Contractor Network Expansion | Captures Phoenix and Austin residential retrofit volume through single-contractor waterproofing and installation bundling. |
| Low-Consumption Generator R&D | Addresses EPA standby power limits while qualifying equipment for utility rebate programs in Title 24 jurisdictions. |
| Infrared Steam Room Portfolio Addition | Defends against substitution threat in Arizona and Nevada luxury residential markets with operating cost-sensitive buyers. |
Research Methodology
Independent corroboration across generator manufacturer technical specifications, California Energy Commission regulatory filings, and Texas Department of Licensing and Regulation contractor records underwrites the qualitative findings. Primary interviews with design-build firm principals, hotel facilities directors, health club procurement managers, and steam enclosure installation specialists combined with secondary validation from EPA commercial building energy code dockets, ASHRAE standard documentation, and OSHA ventilation compliance guidance. Bottom-up equipment shipment analysis and top-down wellness infrastructure investment tracking triangulate market sizing.
Rate-of-change decomposition across product type, end user, application, and technology dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth trajectory analysis incorporating retrofit financing product proliferation, state-level building code adoption schedules, and hospitality development pipeline tracking. Input assumptions include copper price forecast sensitivity, ASHRAE ventilation standard enforcement phasing, and smart home penetration rates in target metro areas.
EPA regulatory timeline acceleration, copper commodity price spikes, and infrared sauna technology cost reduction are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about state adoption patterns for commercial building energy codes and contractor licensing threshold evolution. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Bookends Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
Louvre Windows Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Home Decor Market