
 Bed Sheets Market | 2026-2036
Bed Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Bed Sheets Market Insights
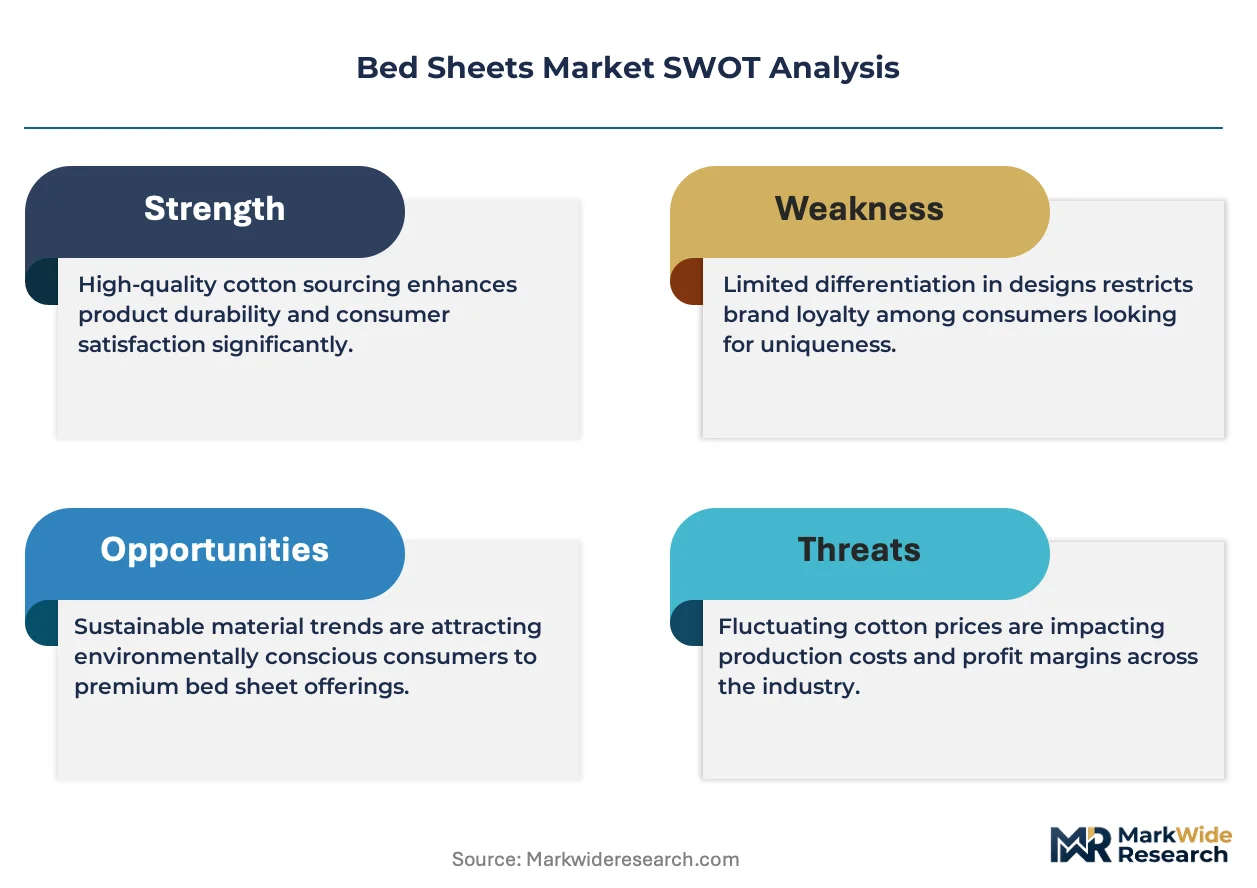
Egyptian cotton and long-staple premium tiers is reorganizing the Bed Sheets Market as consumers trade up from basic percale. Boll & Branch leverages certified organic supply chains to anchor its sustainability positioning. Tempur Sealy International extends its mattress brand equity into adjacent bedding categories. Cozy Earth specializes in bamboo-derived fabric formulations to differentiate within the natural-fiber segment.
Bed sheets are woven textile coverings manufactured from natural or synthetic fibers, typically with thread counts ranging from 200 to 1,000, designed to protect mattresses and provide sleep surfaces for residential and commercial environments. Cotton retains the largest volume share due to breathability and durability, while microfiber gains traction in institutional channels where cost-per-wash economics dominate procurement. Hospitality usage commands premium pricing for high-thread-count sateen weaves, whereas healthcare procurement prioritizes polyester blends for industrial laundering compatibility.
OEKO-TEX Standard 100 and the EU Green Deal textile strategy shape product compliance requirements across European distribution channels, while the US EPA and FTC Green Guides enforce environmental marketing claims in North American retail. India's BIS certification mandates fiber-content labeling for domestic sales, creating a fragmented compliance landscape for multinational suppliers. Stakeholders must monitor evolving chemical-restriction schedules and traceability mandates to preserve market access across jurisdictions.
Market Dynamics
The EU Green Deal textile strategy is forcing hospitality procurement teams to abandon conventional cotton sourcing and rebuild supply chains around certified organic fiber traceability systems.
Growth Catalysts
- EU Green Deal textile regulations:Mandates for sustainable fiber sourcing are redirecting institutional procurement budgets toward certified organic cotton programs across European hospitality chains.
- India's premium residential segment:Rising disposable incomes in metropolitan clusters are accelerating branded bedding adoption among first-time homebuyers seeking quality differentiation.
- Long-staple cotton cultivation:Egyptian and Pima cotton varietals are commanding supply premiums as consumers trade up from basic percale weaves toward durability-focused premium tiers.
Market Restraints
- Raw cotton price volatility:Climate-induced yield fluctuations in Maharashtra and Texas are compressing margin predictability for mid-tier manufacturers dependent on spot-market fiber sourcing.
- Chinese polyester blend dominance:Concentrated capacity in Zhejiang and Jiangsu provinces creates supply vulnerability for healthcare procurement teams requiring industrial-laundering-compatible sheeting.
- Thread count inflation ceiling:Technical limitations in mechanical weaving above 1,000 thread counts are constraining product differentiation beyond marketing claims.
Strategic Opportunities
- Tier-2 Indian cities:Underpenetrated markets in Pune, Hyderabad, and Ahmedabad present whitespace for branded distribution as organized retail expands beyond Mumbai and Delhi corridors.
- Bamboo-derived fabric formulations:Cellulosic fiber technology is opening natural-fiber positioning for sustainability-focused entrants without cotton's agricultural water intensity.
- Direct-to-hospitality digital platforms:B2B procurement portals are disintermediating traditional textile distributors for mid-size hotel chains seeking transparent bulk pricing.
Industry Challenges
- OEKO-TEX Standard 100 certification timelines:Six-to-nine-month testing protocols are delaying product launches for suppliers entering European distribution channels.
- Legacy ERP integration with traceability systems:Fiber-origin tracking requirements are forcing capital-intensive software overhauls at family-owned weaving operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bed Sheets Market |
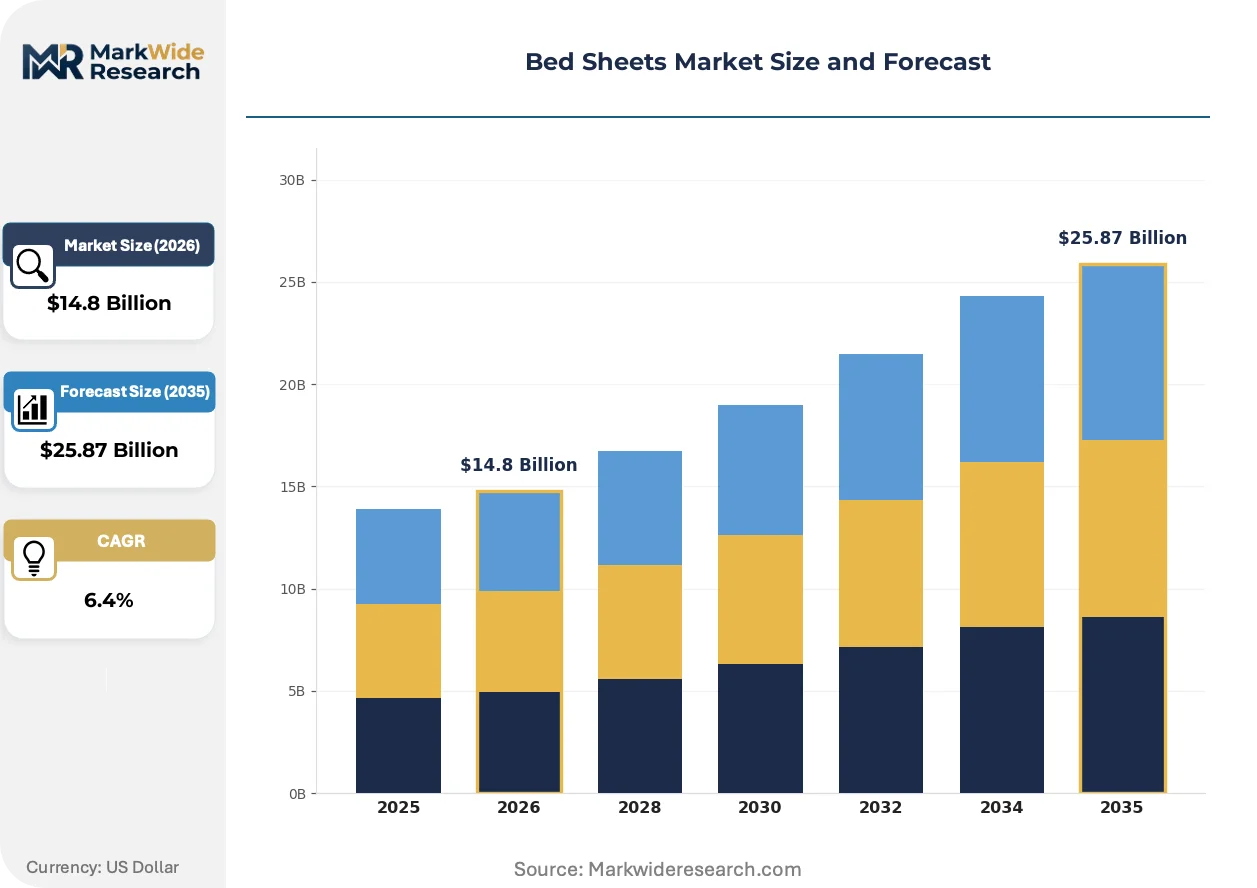
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cotton, Linen, Polyester, Microfiber Weave Type: Satin, Sateen, Percale, Jersey Size: Twin, Full, Queen, King Usage Type: Residential, Hospitality, Healthcare, Institutional |
| Companies Covered | Brooklinen, Serta Simmons Bedding, Tempur Sealy International, Cozy Earth, Boll & Branch, Sleep Number Corporation, Saatva, L.L.Bean, Purple Innovation LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bed Sheets Market Trends and Innovations
Sustainability certification is becoming the primary axis of competitive differentiation as procurement teams embed compliance requirements into supplier scorecards ahead of formal regulatory deadlines.
Cellulosic bamboo fiber technology is bifurcating the natural-fiber segment between agricultural cotton dependence and closed-loop regenerated alternatives. Boutique hotel chains in California and Nordic markets are adopting bamboo-derived sateen at triple the rate of conventional hospitality suppliers. This material shift is compressing pricing premiums for organic cotton while opening margin space for chemical-process innovators.
REACH chemical restriction schedules are expanding banned substance lists across European textile distribution, with ECHA now targeting flame retardants and antimicrobial finishes common in healthcare sheeting. Manufacturers serving German and French hospital systems are reformulating polyester blends to maintain industrial-laundering compatibility without restricted additives. The compliance burden falls heaviest on mid-cap suppliers lacking in-house toxicology testing infrastructure.
Certification-driven preference rotation is displacing thread-count marketing as the primary consumer decision heuristic. Indian premium residential buyers now lead with GOTS and OEKO-TEX inquiries before evaluating weave structure or fiber origin. This behavioral shift is most visible in Mumbai and Bangalore, where organized retail staff report two-thirds of showroom conversations now open with sustainability credential requests rather than price or softness claims.
Bed Sheets Market Segmentation
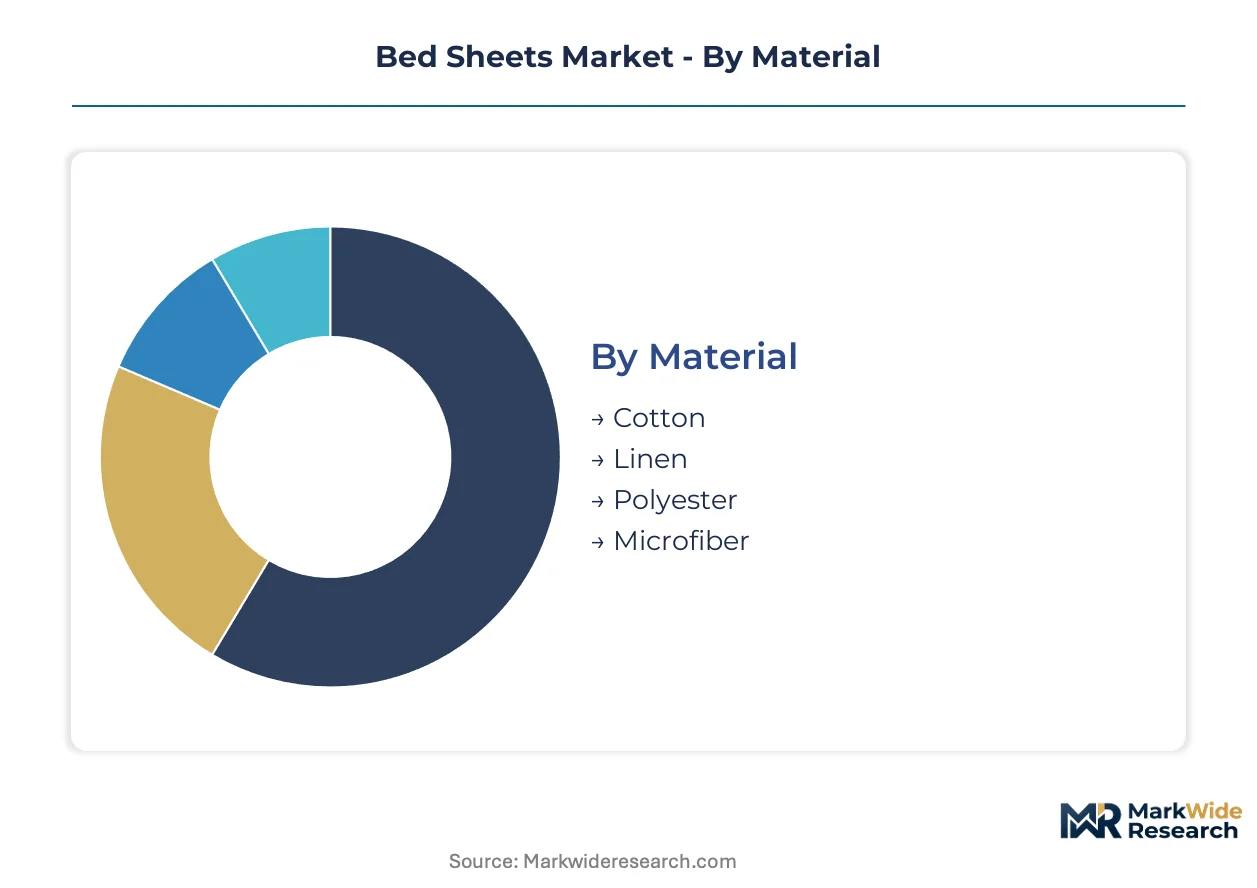
Material selection governs margin capture in bed sheets, with fiber origin and certification tier commanding price premiums that separate commodity suppliers from branded players. Weave construction and end-use specification further stratify procurement budgets across residential and institutional channels.
Material:
Premium margin pools concentrate in certified natural fibers where traceability investments create pricing power against synthetic alternatives.
- Cotton:Long-staple Egyptian and Pima varietals deliver superior durability and breathability through tighter yarn twists. Demand concentrates in India's premium residential segment, where Mumbai and Bangalore homebuyers prioritize GOTS-certified organic grades for master bedroom investments.
- Linen:Flax-derived fibers from Belgian and French cultivation regions offer exceptional moisture-wicking and thermoregulation. European boutique hospitality chains in Copenhagen and Amsterdam specify stonewashed linen for sustainability-positioned guest experiences.
- Polyester:Petroleum-based synthetic fibers dominate healthcare procurement for industrial laundering compatibility. German hospital systems specify polyester-cotton blends meeting REACH chemical restrictions without flame-retardant additives.
- Microfiber:Ultra-fine denier synthetic filaments from Chinese Zhejiang province capacity serve cost-sensitive institutional bulk purchasing. US extended-stay hotel chains specify microfiber for weekly replacement cycles where cost-per-wash economics override hand-feel preferences.
Cotton holds installed capacity across global weaving centers. Microfiber is rotating up the share rankings in institutional procurement.
Weave Type:
Construction method determines surface texture and durability trade-offs that align with distinct end-use performance requirements.
- Satin:Four-over-one float weave creates lustrous surface sheen through maximized yarn exposure on the face side. Luxury hospitality properties in Paris and Dubai specify satin weaves above 600 thread count for suite-tier differentiation.
- Sateen:Three-over-one variation offers similar drape with slightly improved durability for residential washing cycles. California and Nordic boutique hotel chains are adopting bamboo-derived sateen at accelerated rates for natural-fiber positioning.
- Percale:Plain one-over-one weave structure delivers crisp hand-feel and superior breathability through balanced yarn distribution. Basic percale serves entry-level residential segments in Tier-2 Indian cities where first-time branded bedding purchasers prioritize value over luxury cues.
- Jersey:Knitted rather than woven construction produces stretch and softness resembling t-shirt fabric. Dormitory and summer-camp institutional buyers specify jersey for youth demographics prioritizing casual comfort over formal bedding aesthetics.
Sateen holds installed capacity across hospitality supply chains. Jersey is climbing the fastest in youth-focused institutional procurement.
Size:
Dimensional specifications track mattress format standardization and regional bedding conventions that constrain manufacturing flexibility.
- Twin:Single-occupancy format serves dormitory, healthcare, and children's bedroom applications with standardized 38-by-75-inch dimensions. US college housing procurement specifies twin XL variants for adjustable dorm frames.
- Full:Transitional double format retains niche demand in guest rooms and smaller European apartments where queen dimensions exceed spatial constraints. French and Italian urban residential buyers specify full size for secondary bedrooms.
- Queen:North American standard dominates residential volume with 60-by-80-inch coverage for master bedrooms. Indian organized retail reports queen as the fastest-growing format among metropolitan first-time homebuyers in Hyderabad and Pune.
- King:Premium residential and hospitality format commands highest unit pricing through 76-by-80-inch surface area. Dubai and Riyadh luxury residential developments specify king as baseline for primary suites.
Queen holds installed capacity across manufacturing lines. King is expanding most quickly in premium residential and Gulf hospitality development.
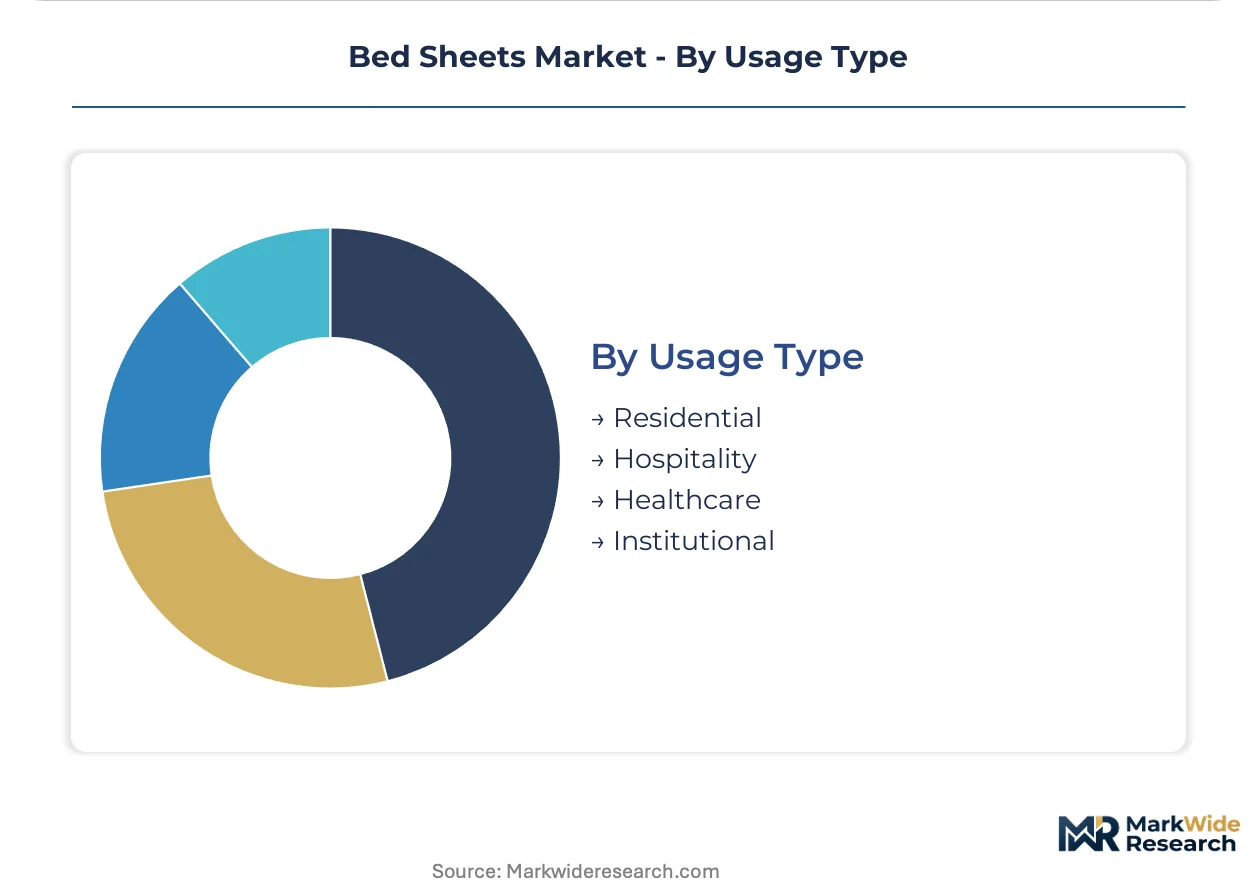
Usage Type:
End-use specifications create divergent procurement logics around replacement cycles, laundering intensity, and guest-experience investment levels.
- Residential:Consumer-direct purchasing emphasizes tactile preference and bedroom aesthetic coordination. Indian premium segment buyers lead with sustainability certification inquiries before evaluating weave or price.
- Hospitality:Commercial procurement prioritizes durability economics and brand alignment across property tiers. EU Green Deal regulations are redirecting European hospitality chain budgets toward certified organic cotton traceability systems.
- Healthcare:Hospital and long-term care procurement demands industrial-laundering compatibility with antimicrobial and flame-retardant formulation constraints. ECHA REACH restrictions are forcing reformulation of polyester blends for German and French hospital systems.
- Institutional:Military, correctional, and educational bulk purchasing emphasizes cost minimization over performance differentiation. US federal procurement specifications prioritize domestic content requirements for military bedding contracts.
Residential holds installed capacity across global retail distribution. Hospitality is gaining share fastest as sustainability compliance investments accelerate supplier consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese weaving capacity in Zhejiang and Jiangsu provinces anchors synthetic fiber supply chains, while Indian cotton cultivation in Maharashtra and Gujarat underpins natural fiber availability for premium tiers. European hospitality procurement is redirecting sourcing patterns through EU Green Deal compliance mandates.
United States
Extended-stay hotel chains and college housing procurement drive microfiber and twin XL format demand. The EPA and FTC Green Guides enforce environmental marketing claims verification for organic cotton positioning. North Carolina textile clusters maintain finishing and distribution infrastructure for hospitality supply chains.
Germany
Hospital systems and boutique hospitality properties command industrial-laundering-compatible sheeting with REACH chemical compliance. ECHA restriction schedules are forcing polyester blend reformulation without flame-retardant additives. Bavarian and North Rhine-Westphalia industrial zones host technical textile finishing operations serving healthcare procurement.
India
Metropolitan first-time homebuyers in Mumbai and Bangalore prioritize GOTS-certified organic cotton for master bedroom investments. BIS certification mandates fiber-content labeling for domestic sales, fragmenting compliance for multinational suppliers. Maharashtra and Gujarat cultivation belts supply long-staple varietals to organized retail channels.
China
Zhejiang and Jiangsu province capacity concentrates microfiber and polyester blend production for institutional bulk purchasing. The country's dual carbon goals are pressuring textile manufacturers toward energy-efficient processing. Yangtze River Delta weaving clusters serve cost-sensitive healthcare and military procurement contracts.
United Arab Emirates
Dubai and Riyadh luxury residential developments specify king-format bedding as baseline for primary suites. MOHAP pharmaceutical and medical device regulations extend to healthcare textile procurement standards. Dubai hospitality supply hubs coordinate redistribution across Gulf Cooperation Council markets.
Bed Sheets Market Competitive Landscape
Concentration sits with brand-architects and sustainability-certifiers rather than commodity weavers. Mid-tier manufacturers face margin compression from raw cotton volatility and compliance cost burdens. Three archetypes dominate: certified organic specialists, mattress brand extenders, and cellulosic fiber innovators. Competitive moves center on supply chain traceability investments and direct-to-hospitality digital platform development.
Within the certified organic tier, Boll & Branch and Cozy Earth exemplify sustainability-positioned entrants leveraging supply chain transparency for pricing power. Tempur Sealy International occupies a position as mattress brand equity extender into adjacent bedding categories. These three represent distinct strategic vectors—organic cotton traceability, bamboo-derived fabric formulation, and cross-category brand leverage—that are reorganizing competitive positioning away from thread-count marketing.
| Leading Market Players |
|---|
| Brooklinen |
| Serta Simmons Bedding |
| Tempur Sealy International |
| Cozy Earth |
| Boll & Branch |
| Sleep Number Corporation |
| Saatva |
| L.L.Bean |
| Purple Innovation LLC |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal textile regulations gate both supply qualification and price differentiation simultaneously, mandating certified organic fiber traceability as a prerequisite for European hospitality procurement while compressing premiums for uncertified cotton tiers. This regulatory architecture forces manufacturers to absorb certification costs upstream or surrender margin downstream, reshaping competitive economics across natural and synthetic fiber segments.
Pricing Analysis
EU Green Deal textile regulations dictate the pricing tier structure across European distribution channels, separating GOTS-certified organic cotton at premium positioning from conventional grades facing margin compression. Certification grade and volume scale drive price differentiation, with hospitality bulk contracts commanding softer unit economics than residential direct-to-consumer channels. Cost compression in mid-tier conventional cotton is intensifying because Maharashtra and Texas climate volatility disrupts spot-market fiber sourcing. Healthcare procurement teams exhibit highest price sensitivity due to institutional budget constraints, while luxury residential buyers in Mumbai and Bangalore demonstrate lowest sensitivity when sustainability credentials align with bedroom investment positioning.
Supply Chain Analysis
Inventory cycles stretch six-to-nine months for OEKO-TEX Standard 100 certification completion, creating working capital intensity that disadvantages smaller weaving operations against scaled competitors. Raw cotton cultivation concentrates in India and Egypt, while polyester filament production clusters in China's Zhejiang and Jiangsu provinces. Supply chain risk hinges on single-source vulnerability in Chinese synthetic fiber capacity, where concentrated manufacturing exposes healthcare procurement to disruption. Distribution runs through hospitality supply hubs in Dubai, North Carolina textile clusters, and European technical finishing zones serving German hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-hospitality digital procurement platforms represent a service-attach opportunity expanding faster than physical bedding hardware, as mid-size hotel chains disintermediate traditional textile distributors for transparent bulk pricing and replenishment automation.
For Market Incumbents: Shield market position by deepening backward integration into Maharashtra and Gujarat cotton cultivation belts to secure long-staple varietal supply against climate-induced yield volatility. Accelerate ERP traceability system deployment to preempt EU Green Deal fiber-origin documentation mandates before compliance deadlines tighten supplier qualification windows. Certification investment serves as the critical defensive lever against emerging bamboo-derived fiber entrants capturing California and Nordic boutique hospitality share. For New Entrants and Emerging Players: Differentiate on cellulosic bamboo fiber formulation technology to bypass agricultural water intensity constraints plaguing conventional cotton supply chains. Target underpenetrated Tier-2 Indian cities—Pune, Hyderabad, Ahmedabad—where organized retail expansion creates whitespace for branded distribution beyond saturated Mumbai-Delhi corridors. A sustainability-native go-to-market angle, anchored by closed-loop manufacturing narratives, penetrates procurement scorecards faster than thread-count parity plays. For Investors and Strategic Acquirers: EU Green Deal implementation timelines reshape the acquisition landscape toward certified organic specialists with established traceability infrastructure and hospitality procurement relationships. Long-term viability across the analysis window favors targets with demonstrated compliance execution rather than commodity scale. Watch OEKO-TEX Standard 100 certification backlog duration as the inflection indicator—extended testing queues signal supply constraint pricing power for qualified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Supply Chain Rebuild | EU Green Deal mandates force hospitality procurement teams to abandon conventional cotton sourcing for traceable fiber systems. |
| Direct-to-Hospitality Digital Platform Launch | B2B procurement portals disintermediate traditional textile distributors for mid-size European hotel chains seeking transparent bulk pricing. |
| Cellulosic Bamboo Fiber Scale-Up | Closed-loop regenerated alternatives bypass cotton's agricultural water intensity while capturing Nordic and California boutique hospitality demand. |
| ERP Traceability System Integration | Fiber-origin tracking requirements force capital-intensive software overhauls at family-owned weaving operations to preserve market access. |
| Tier-2 Indian City Distribution Expansion | Organized retail growth in Pune, Hyderabad, and Ahmedabad creates whitespace for branded bedding penetration beyond metropolitan corridors. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with hospitality procurement directors, textile supply chain managers, and sustainability certification auditors; and secondary validation through customs trade records, EU ECHA restriction schedules, and BIS fiber-content labeling filings. Primary interviews captured procurement budget reallocation patterns under EU Green Deal compliance pressure, while secondary sources anchored volume estimates to disclosed institutional purchasing and cultivation belt output data. Bottom-up triangulation across weaving capacity and top-down reconciliation against hospitality property development pipelines ensured convergence.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning material grade tier, weave construction type, end-use application, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, property development pipelines, and certification adoption curves. Forecast inputs incorporated Maharashtra and Gujarat cotton yield variability, Zhejiang province polyester capacity utilization, and European hospitality chain sustainability procurement scorecard weightings.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement trajectory, stable Indian organized retail expansion, or continued Chinese synthetic fiber capacity dominance would require recalibration. Forecasts reflect documented assumptions regarding certification timeline standardization and hospitality procurement centralization trends. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
United States Bed and Bath Linen Market
Textiles and Linens
Table Linen Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Duvets Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market
Textiles and Linens
Global Textiles Home Decor Market