
 Smart Vase Market | 2026-2036
Smart Vase Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Vase Market Analytics
The smart vase category is recalibrating around a sharp split between artisan-crafted ceramic vessels with embedded IoT modules and mass-produced plastic units competing on app connectivity alone. Parrot leverages its avionics sensor heritage to anchor precision moisture detection in premium European households. Modern Sprout competes through design-forward glass formats that dominate North American specialty retail channels. Click & Grow extends its indoor farming brand equity into self-contained vase ecosystems with proprietary seed-pod compatibility.
A smart vase constitutes a connected horticultural container integrating capacitive soil sensors, micro-pump irrigation circuits, and Bluetooth or Wi-Fi telemetry to automate plant maintenance via mobile application control. Ceramic and glass material segments command the widest margin pools due to perceived durability and aesthetic compatibility with interior design schemes, while plastic variants lead volume in entry-level residential penetration. LED-equipped product types are gaining fastest among commercial end users seeking programmable ambient lighting integration in hotel lobbies and corporate reception areas. Water level monitoring functionality remains the baseline specification, though fertilizer dispensing modules are emerging as the primary upgrade driver in the residential segment.
The Federal Communications Commission governs radio frequency emissions for Bluetooth-enabled devices sold in the United States, while the EU's Radio Equipment Directive mandates interoperability and cybersecurity standards for connected vases marketed across member states. China's Ministry of Industry and Information Technology enforces GB standard compliance for wireless transmission modules in smart home accessories manufactured domestically. Stakeholders must weigh regional certification burdens against the cost of platform fragmentation when selecting wireless protocol architectures for new product families.
Market Dynamics
The EU's Ecodesign for Sustainable Products Regulation is forcing a material disclosure overhaul across connected home accessories, compelling manufacturers to reengineer supply chains for ceramic and glass smart vase production before the full enforcement window closes.
Growth Catalysts
- Sensor miniaturization:Capacitive soil moisture modules now integrate into hand-thrown ceramic walls without compromising artisan aesthetics, unlocking premium residential demand in Germany's retrofit sector.
- Luxury hospitality procurement:Dubai and Singapore hotel groups are specifying sensor-embedded floral displays as standard guest room amenities, creating a B2B revenue channel with 3-5 year replacement cycles.
- REACH compliance differentiation:Vessels certified under EU chemical safety standards command shelf placement priority in specialty retail chains across France and the Netherlands.
Market Restraints
- Lithium-ion cell cost volatility:Micro-pump irrigation circuits depend on compact rechargeable batteries whose input costs swing with cobalt and nickel spot markets, compressing margins on sub-$150 units.
- Guangdong electronics concentration:Bluetooth module fabrication clusters in southern China create single-source vulnerability for Wi-Fi telemetry subassemblies during port congestion events.
- Waterproofing technical ceiling:Current IP67 ratings fail under prolonged submersion in fertilizer-dispensing configurations, limiting outdoor terrace applications for luxury hospitality buyers.
Strategic Opportunities
- India premium residential penetration:Mumbai and Bangalore high-rise developments show sub-4% smart home accessory attachment rates, offering first-mover positioning before BIS certification requirements tighten.
- Proprietary seed-pod ecosystems:Closed-loop vase formats with locked fertilizer cartridges generate recurring consumable revenue streams analogous to printer-ink models.
- Japan METI energy efficiency labeling:LED-equipped commercial variants qualifying for top-tier ratings gain preferential procurement status in Tokyo corporate reception fit-outs.
Industry Challenges
- RF certification timeline compression:FCC Part 15 and EU Radio Equipment Directive testing queues now extend 14-18 weeks, delaying seasonal product launches for North American and European retail windows.
- Legacy home automation integration:Matter protocol adoption gaps force manufacturers to maintain three parallel firmware branches for Amazon Alexa, Google Home, and Apple HomeKit compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Vase Market |
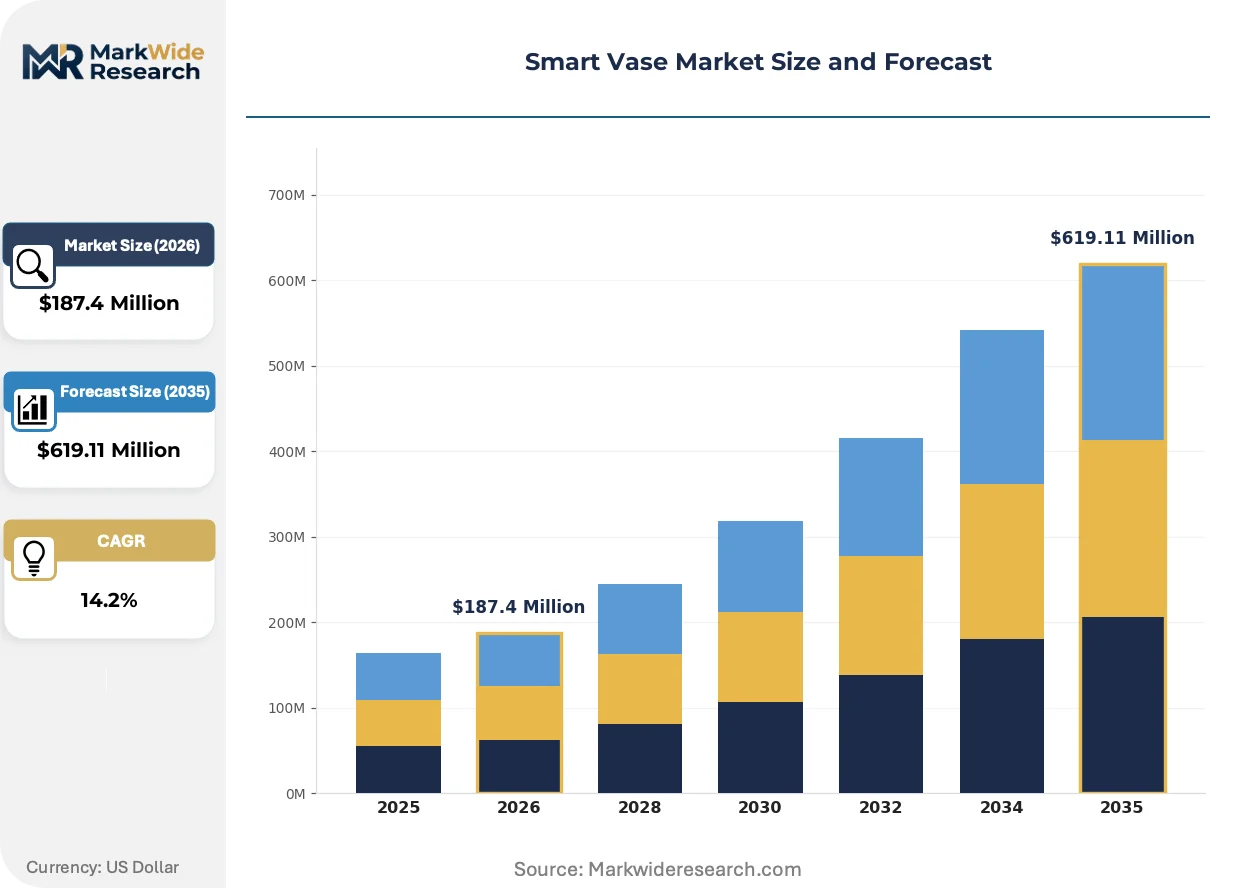
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Watering, Smart Sensors, LED-Equipped, Bluetooth-Enabled Material: Ceramic, Glass, Plastic, Metal End User: Residential, Commercial, Offices, Retail Spaces Functionality: Water Level Monitoring, Light Adjustment, Fertilizer Dispensing, Temperature Control |
| Companies Covered | Parrot, Modern Sprout, Edyn, LetPot, GAOBI, Yoolax, Click & Grow, MiFlora, Plantui, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Vase Market Evolving Landscape
Product evolution in connected horticulture is bifurcating between invisible embedded intelligence and overt technological display, with material science and regulatory compliance now determining competitive positioning as much as app functionality.
Photocatalytic self-cleaning ceramic glazes are rewriting maintenance expectations for premium smart vases. Luxury hospitality buyers in Singapore and Dubai are specifying these surfaces for lobby installations where manual cleaning labor costs exceed hardware premiums. The technology compresses total cost of ownership calculations and displaces conventional sealed glass formats in RFP evaluations.
The EU's Ecodesign for Sustainable Products Regulation mandates digital product passports for connected home accessories entering member states after 2027. Manufacturers must embed material provenance and end-of-life handling data into QR-linked databases. Ceramic and glass segments face the steepest compliance burden due to multi-source supply chains spanning Italian clay deposits and German kiln operations.
Direct-to-consumer subscription bundling is displacing single-unit retail for residential smart vase purchases. North American specialty channels now lead with "plant-vase-app" triads on 24-month replacement cycles rather than hardware-only transactions. This model concentrates customer lifetime value data with vertically integrated brands and fragments traditional garden center distribution.
Smart Vase Market Segmentation
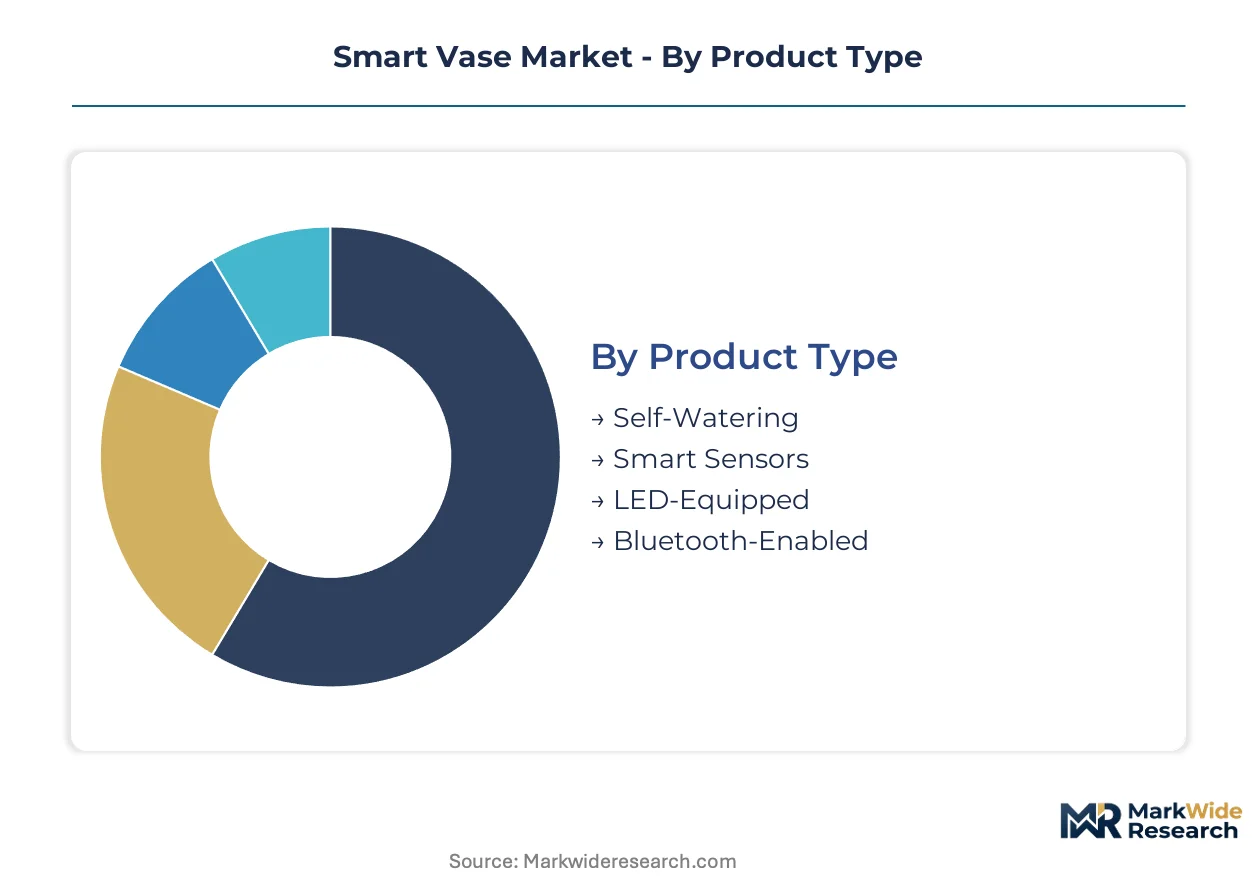
Smart vase segmentation reveals how hardware architecture choices lock manufacturers into distinct margin structures and certification pathways. Integration depth varies sharply across product categories, with standalone units demanding simpler RF compliance while embedded systems require complex home automation protocols.
Product Type:
Standalone self-contained units dominate entry-level residential penetration, while sensor-embedded formats integrate into broader smart home ecosystems with higher switching costs.
- Self-Watering:Micro-pump irrigation circuits automate hydration schedules through capacitive soil sensors. Demand concentrates in Germany's premium residential retrofit sector, where homeowners prioritize low-maintenance plant care amid rising labor costs for domestic services.
- Smart Sensors:Capacitive moisture and ambient light telemetry feed mobile applications with real-time plant health data. Singapore and Dubai luxury hospitality buyers specify these for guest room differentiation, creating B2B replacement cycles stretching 3-5 years.
- LED-Equipped:Programmable spectrum arrays support photosynthesis optimization. Tokyo corporate reception fit-outs favor METI top-tier energy efficiency ratings for these variants.
- Bluetooth-Enabled:Short-range wireless modules enable localized smartphone control without Wi-Fi infrastructure. FCC Part 15 certification queues now extend 14-18 weeks, compressing North American seasonal launch windows.
Self-Watering leads volumes today; Smart Sensors is gaining share fastest.
Material:
Material selection determines supply chain geographic concentration and regulatory exposure under tightening chemical disclosure mandates.
- Ceramic:Hand-thrown vessels with embedded IoT modules command the widest margin pools due to perceived durability and artisan authenticity. EU Ecodesign for Sustainable Products Regulation mandates digital product passports for these formats, forcing multi-source supply chain documentation across Italian clay deposits and German kiln operations.
- Glass:Design-forward transparent formats dominate North American specialty retail channels. Modern Sprout has built brand equity around borosilicate constructions that showcase root systems.
- Plastic:Injection-molded ABS and polypropylene variants lead volume in sub-$150 entry-level penetration. Guangdong fabrication clusters create single-source vulnerability during port congestion events.
- Metal:Brushed aluminum and stainless steel enclosures target commercial installations requiring vandal resistance. Mumbai high-rise developments show nascent attachment for these premium formats.
Plastic leads volumes today; Ceramic is expanding most quickly.
End User:
Customer type dictates pricing architecture and replacement cycle length, with commercial contracts amortizing hardware costs across multi-year service agreements.
- Residential:Direct-to-consumer subscription bundling now dominates, with "plant-vase-app" triads on 24-month cycles replacing single-unit transactions. This model concentrates customer lifetime value data with vertically integrated brands.
- Commercial:Hotel groups and corporate facilities specify sensor-embedded floral displays as standard amenities. Procurement runs through facilities management contracts with 3-5 year refresh schedules.
- Offices:Wellness-focused workplace design drives demand for ambient greenery with minimal maintenance overhead. LED-equipped variants integrate with building management systems for centralized lighting control.
- Retail Spaces:Visual merchandising applications prioritize aesthetic impact over sensor sophistication. Photocatalytic self-cleaning ceramic glazes reduce manual maintenance labor in high-traffic environments.
Residential leads volumes today; Commercial is climbing the fastest.
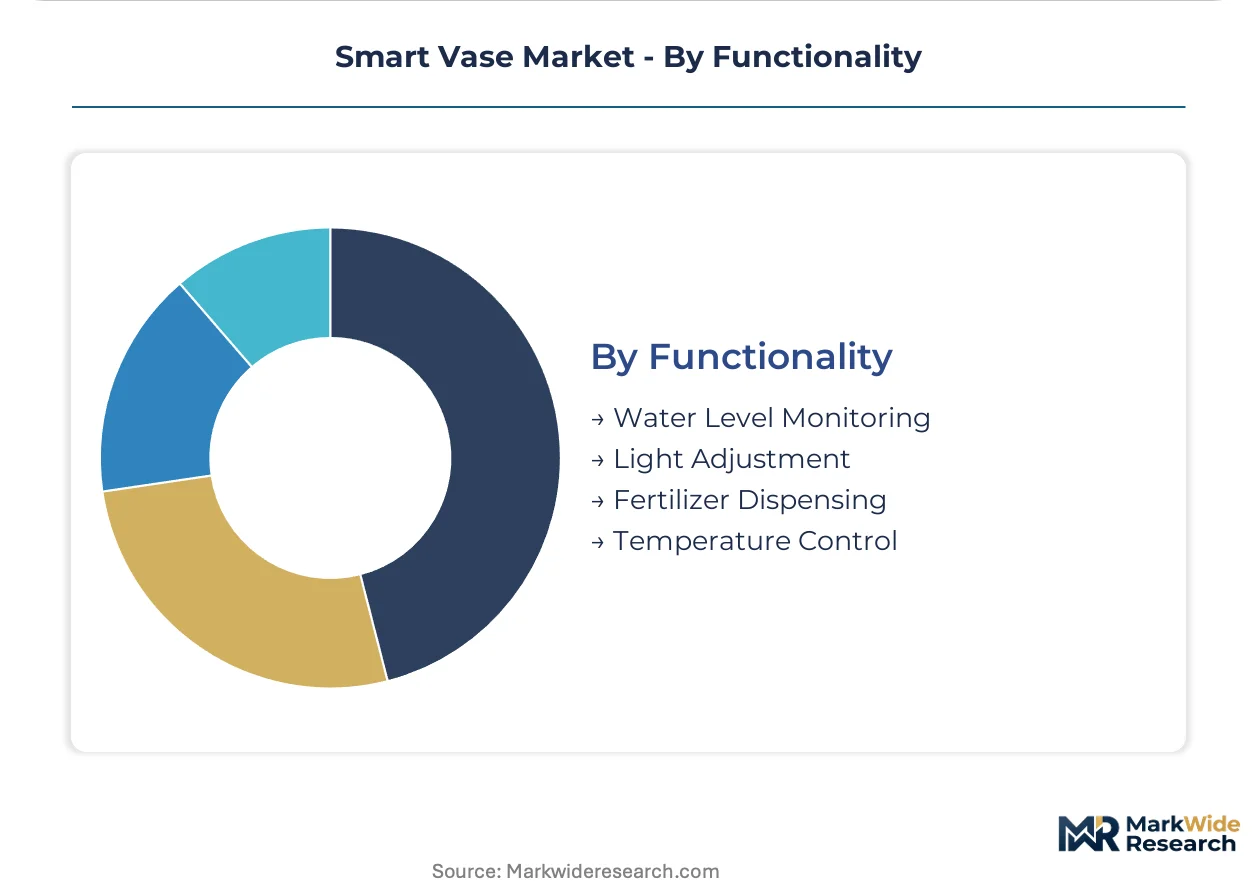
Functionality:
Feature stacking determines bill-of-materials cost structure and firmware complexity, with manufacturers forced to maintain parallel protocol branches for competing home automation platforms.
- Water Level Monitoring:Capacitive and ultrasonic sensors provide baseline hydration alerts. This specification has become table stakes across all price tiers.
- Light Adjustment:Photosynthetically active radiation sensors trigger LED spectrum shifts. Japan METI energy efficiency labeling creates procurement preference for optimized variants.
- Fertilizer Dispensing:Locked cartridge systems generate recurring consumable revenue streams analogous to printer-ink models. Current IP67 waterproofing ratings fail under prolonged submersion, limiting outdoor terrace applications.
- Temperature Control:Peltier or resistive heating elements extend viable plant ranges in climate-stressed environments. This functionality adds the steepest hardware cost premium and remains concentrated in premium ceramic formats.
Water Level Monitoring leads volumes today; Fertilizer Dispensing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial design talent clusters in Germany's Ruhr Valley and Italy's Emilia-Romagna region anchor European smart vase development, while firmware engineering concentrates in Shenzhen's electronics corridor and Bangalore's IoT startup ecosystem.
Germany
Premium residential retrofit demand and luxury hospitality procurement drive German market expansion. The EU's Ecodesign for Sustainable Products Regulation mandates digital product passports for connected home accessories entering member states after 2027. Munich and Stuttgart host the densest concentration of ceramic-embedded IoT manufacturers serving high-margin residential segments.
United States
Direct-to-consumer subscription bundling and specialty retail channel dominance characterize American demand patterns. FCC Part 15 governs Bluetooth-enabled device emissions, with certification queues now extending 14-18 weeks. San Francisco and New York City anchor design-forward glass format distribution networks targeting urban apartment dwellers.
China
Guangdong Province fabrication clusters supply the majority of global Bluetooth module and micro-pump subassemblies. MIIT enforces GB standard compliance for wireless transmission modules in domestically manufactured smart home accessories. Shenzhen's electronics corridor faces single-source vulnerability during port congestion events affecting Wi-Fi telemetry component flows.
Singapore
Luxury hospitality procurement specifications treat sensor-embedded floral displays as standard guest room amenities. The country's national telecommunications regulator enforces cybersecurity standards for connected devices deployed in commercial installations. Marina Bay and Sentosa hotel groups drive 3-5 year replacement cycle demand for B2B revenue channels.
Japan
Corporate reception fit-outs and wellness-focused workplace design propel LED-equipped variant demand. METI energy efficiency labeling creates procurement preference for top-tier rated commercial formats in Tokyo metropolitan developments. Osaka and Nagoya manufacturing bases supply precision ceramic glazing technologies for photocatalytic self-cleaning surfaces.
Smart Vase Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the smart vase category, with ceramic kiln operators and glass foundries facing margin pressure from injection-molded ABS assemblers. The vendor base fragments across three strategic tiers: vertically integrated horticultural technology brands, specialty home décor houses with licensed IoT modules, and contract electronics manufacturers white-labeling for retail channels. Dominant competitive moves include backward integration into sensor module fabrication and exclusive seed-pod ecosystem lock-in strategies.
Within the avionics heritage tier, Parrot anchors precision moisture detection positioning for premium European households. Among North American design-forward specialists, Modern Sprout exemplifies borosilicate glass format dominance in specialty retail channels. Click & Grow occupies a position as the vertically integrated horticultural technology anchor, extending indoor farming brand equity into self-contained vase ecosystems with proprietary consumable compatibility.
| Leading Market Players |
|---|
| Parrot |
| Modern Sprout |
| Edyn |
| LetPot |
| GAOBI |
| Yoolax |
| Click & Grow |
| MiFlora |
| Plantui |
| Others |
Value Network & Pricing Analysis
A sharp split between artisan-crafted ceramic vessels and mass-produced plastic units manifests in divergent pricing architectures and sourcing geographies. Premium ceramic formats command margin pools through German kiln operations and Italian clay deposits, while plastic variants anchor entry-level positioning via Guangdong injection-molding clusters. This bifurcation forces manufacturers to maintain parallel supply chain configurations with incompatible certification burdens and inventory risk profiles.
Pricing Analysis
Bundled subscription triads displace single-unit transactions as the dominant pricing model across North American residential channels. Price differentiation separates REACH-certified ceramic vessels from uncertified plastic alternatives, with EU Ecodesign compliance emerging as a tiering mechanism. Pricing pressure stems from lithium-ion cell cost volatility compressing margins on sub-$150 units. Residential buyers exhibit highest price sensitivity, while luxury hospitality procurement in Dubai and Singapore tolerates hardware premiums when total cost of ownership calculations favor photocatalytic self-cleaning surfaces.
Supply Chain Analysis
Freight cost volatility from Guangdong port congestion events ripples through Wi-Fi telemetry subassembly flows. Component fabrication concentrates in China, Germany, and Japan, with ceramic glazing technologies anchored in Osaka and Nagoya manufacturing bases. Raw material dependencies span Italian clay deposits, German kiln equipment, and southern China Bluetooth module clusters. Single-source vulnerability in Guangdong electronics corridors creates structural risk during logistics chokepoints. Distribution runs through direct-to-consumer subscription channels and B2B facilities management contracts with diverging working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart vase market functions as a stable compounder, with sensor miniaturization driving steady replacement cycles across hospitality and residential retrofit segments. Recurring consumable revenue from proprietary seed-pod ecosystems locks in predictable cash flows.
For Market Incumbents: Lock in hospitality procurement relationships through photocatalytic self-cleaning ceramic specifications that compress total cost of ownership calculations. Backward integration into capacitive soil sensor module fabrication defends margin pools against commodity plastic assemblers. Prioritize EU digital product passport compliance before enforcement windows tighten, securing shelf placement priority in French and Dutch specialty retail chains. For New Entrants and Emerging Players: Photocatalytic glaze technology offers a technology-first wedge into Singapore and Dubai luxury hospitality RFP evaluations where manual cleaning labor costs exceed hardware premiums. Target Mumbai and Bangalore high-rise developments showing sub-4% smart home accessory attachment rates before BIS certification requirements tighten. Pursue direct-to-consumer "plant-vase-app" triad bundling to capture customer lifetime value data and fragment traditional garden center distribution. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated horticultural technology brands controlling proprietary seed-pod ecosystems and locked fertilizer cartridge revenue streams. Five-to-ten year viability hinges on Matter protocol adoption gaps forcing parallel firmware maintenance for competing home automation platforms. Watch FCC Part 15 and EU Radio Equipment Directive testing queue compression as an inflection indicator for seasonal launch timing risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Module Fabrication | Captive supply of capacitive soil moisture components insulates margin pools from Guangdong single-source vulnerability. |
| Proprietary Seed-Pod Ecosystem Lock-In | Locked fertilizer cartridges generate recurring consumable revenue analogous to printer-ink models across residential segments. |
| Photocatalytic Self-Cleaning Glaze Certification | Marina Bay and Sentosa hotel procurement specifications prioritize these surfaces for lobby installation RFPs. |
| EU Digital Product Passport Compliance | Mandatory material provenance documentation secures shelf placement in French and Dutch specialty retail chains. |
| Matter Protocol Multi-Platform Support | Parallel firmware branches for Amazon Alexa, Google Home, and Apple HomeKit compatibility defend addressable market coverage. |
Research Methodology
Direct dialogue with ceramic kiln operators, IoT firmware engineers, luxury hospitality procurement directors, specialty retail category buyers, and connected home accessory distributors grounded the qualitative foundation. Secondary validation drew from FCC Part 15 certification databases, EU Ecodesign regulatory filings, MIIT GB standard compliance records, METI energy efficiency labeling registries, and customs trade data for Bluetooth module flows. Bottom-up unit economics triangulated against top-down market sizing across product type, material, end user, and functionality dimensions.
Bottom-up demand modeling segmented the market by self-watering versus sensor-embedded formats, ceramic versus glass versus plastic materials, residential versus commercial end users, and water level monitoring versus fertilizer dispensing functionality. Top-down validation incorporated hospitality procurement cycle analysis and smart home integration rate trajectories. CAGRs derived from replacement cycle compression in B2B channels and subscription bundling penetration in residential segments. Forecast inputs included sensor miniaturization cost curves and REACH compliance differentiation premiums.
The model holds under stable lithium-ion cell cost assumptions and intact Guangdong logistics corridors; deviation in cobalt-nickel spot market volatility or port congestion severity would shift margin pool distribution between ceramic and plastic formats. Stakeholders should weight assumptions against their own operating context and certification timeline constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Louvre Windows Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
Mattress Topper Market