
 US Mattress Bases Market | 2026-2036
US Mattress Bases Market Size, Share, and Industry Trends Forecast 2026-2036
US Mattress Bases Market Insights
Premium-grade upholstered bases with reinforced slat systems and higher dynamic load ratings is redrawing competitive boundaries in the US mattress bases landscape. Leggett & Platt, Inc. leverages its vertically integrated steel component production to control input costs across adjustable base assemblies. Tempur Sealy International anchors its position through exclusive retail partnerships with national furniture chains. Saatva, Inc. differentiates via direct-to-consumer logistics that bypass traditional wholesale markups entirely.
A mattress base is a structural support platform engineered to bear distributed sleeper loads, typically constructed with steel grid frameworks, solid wood slats spaced at prescribed intervals, or motorized articulated decks with lift actuators rated for repeated cycle durability. Its primary commercial function is to extend mattress longevity, ensure ergonomic sleep surface alignment, and enable positional adjustability for therapeutic or convenience applications. Adjustable bases command the strongest margin pools as aging demographics and wellness positioning expand their addressable buyer base beyond clinical settings. Platform beds in solid wood and composite materials sustain volume leadership among first-time homebuyers and apartment furnishers prioritizing minimalist aesthetics. Metal folding futon frames occupy a mature replacement cycle segment with limited innovation headroom but steady rental and dormitory demand.
The Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability standards that mandate open-flame resistance testing for mattress base assemblies sold in interstate commerce. California's SB 1019 requires polyurethane foam component disclosure, compelling manufacturers to reformulate upholstered platforms or source certified low-emission substrates. The Federal Trade Commission monitors green marketing claims under its Guides for the Use of Environmental Marketing Claims, constraining how brands label sustainable wood or recycled steel content. Stakeholders must track evolving state chemical restriction patchworks and assess whether adjustable base motor and electronics sourcing requires expanded FCC equipment authorization compliance.
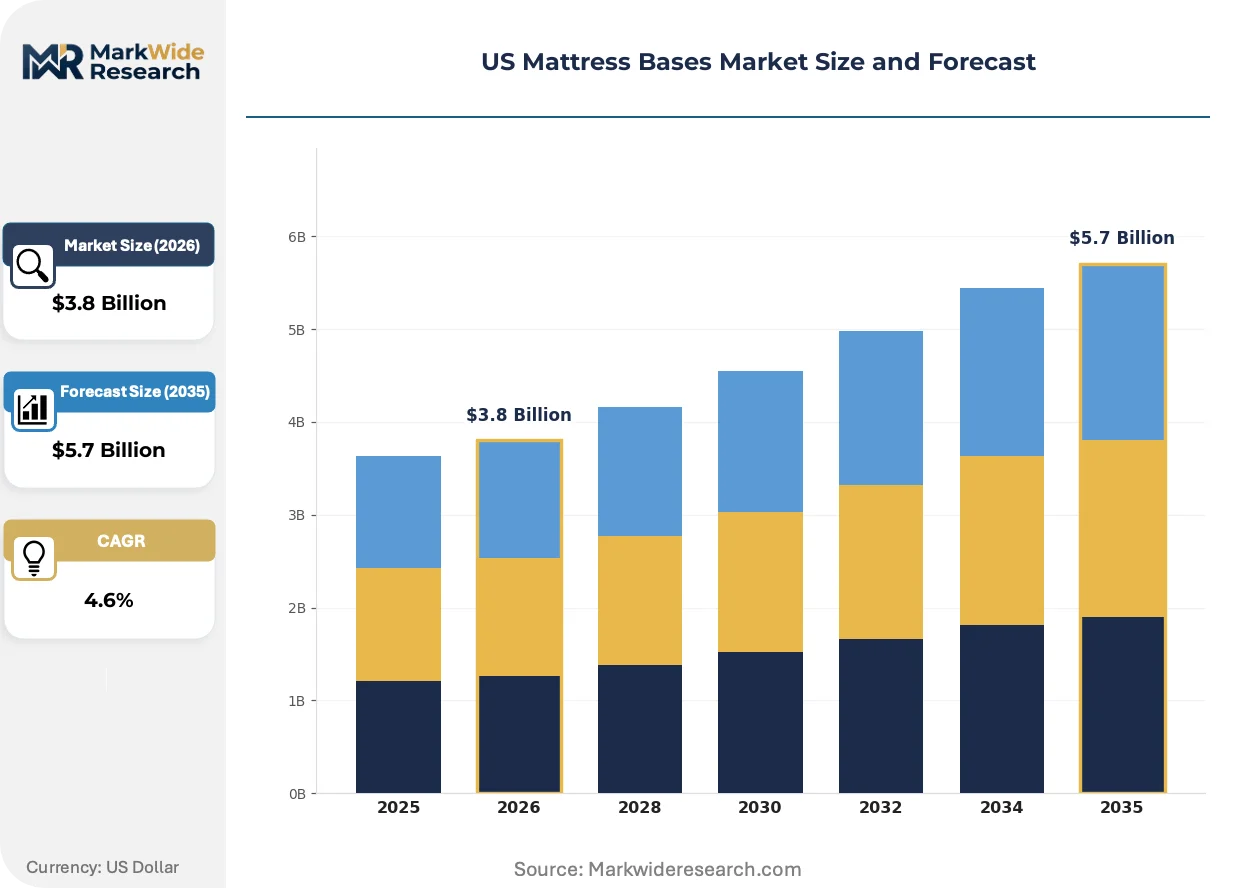
Market Dynamics
California's SB 1019 chemical disclosure mandate and the CPSC's 16 CFR Part 1633 flammability standard are forcing manufacturers to reformulate upholstered platforms and requalify supply chains, compressing margin structures while creating compliance-based competitive moats.
Growth Catalysts
- Hospitality replacement cycles:Hotel chains are compressing base refresh timelines from seven to four years, creating predictable institutional demand corridors in the Southeast manufacturing belt.
- 16 CFR Part 1633 compliance:Federal open-flame resistance testing mandates elevate certified manufacturers above uncertified imports, concentrating procurement with domestic qualified suppliers.
- Motorized articulation:Aging demographics and clinical-to-consumer wellness positioning expand adjustable base adoption beyond hospital settings into residential master bedrooms.
Market Restraints
- Steel input volatility:Grid framework and actuator housing production faces commodity price swings that adjustable base assemblers cannot fully pass through to price-sensitive platform bed buyers.
- Southeast supply concentration:Georgia and North Carolina host disproportionate finished goods and component capacity, exposing national fulfillment to localized weather and logistics disruptions.
- Polyurethane reformulation costs:SB 1019-compliant low-emission foam substrates command 15-25% premiums over conventional grades, squeezing upholstered base margins without commensurate price elasticity.
Strategic Opportunities
- Direct-to-consumer logistics:Bypassing wholesale furniture mart markups via white-glove delivery networks captures margin pools previously allocated to regional distributors.
- FCC equipment authorization:Adjustable base motor and electronics compliance creates a regulatory barrier that domestic assemblers can leverage against unlicensed import competition.
- Texas and Florida demand corridors:Sun Belt population migration and new construction velocity outpace legacy manufacturing footprint, rewarding regional fulfillment center placement.
Industry Challenges
- Cross-functional compliance talent:Manufacturers need staff fluent in CPSC testing protocols, California chemical disclosure, and FCC authorization workflows simultaneously.
- Dual certification timelines:New upholstered adjustable platforms require sequential 16 CFR Part 1633 flammancy validation and SB 1019 component documentation, extending product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mattress Bases Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Spring, Platform Bed, Adjustable Base, Futon Frame Material: Wood, Metal, Upholstered, Composite Size: Twin, Full, Queen, King Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales |
| Companies Covered | Leggett & Platt, Inc., Ergomotion Inc., Tempur Sealy International, Serta Simmons Bedding LLC, Sleep Number Corporation, Casper, Inc., Saatva, Inc., Purple Innovations, Inc., Spring Air International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mattress Bases Market Trends and Innovations
Modular assembly architectures and embedded sensor systems are redrawing how mattress bases are specified, priced, and serviced. The convergence of furniture and consumer electronics is forcing traditional manufacturers to acquire firmware competencies.
Reinforced steel slat systems with dynamic load ratings exceeding 1,200 pounds are decomposing the historical trade-off between platform bed aesthetics and foundation durability. First-time homebuyers in Texas and Florida are specifying these upgraded frames at accelerating rates. This specification shift compresses demand for basic metal grid foundations while elevating average selling prices in the replacement segment.
The FTC's Guides for the Use of Environmental Marketing Claims constrains how brands label sustainable wood sourcing or recycled steel content. Manufacturers must substantiate green claims with third-party chain-of-custody documentation or face enforcement exposure. Upholstered base producers marketing certified low-emission substrates are most affected, with several reformulating marketing language to emphasize performance rather than environmental positioning.
Buyers are unbundling after-sales service from product purchase, treating mattress bases as replaceable appliances rather than long-term furniture investments. Online pure-play retailers capture this behavioral shift with compressed delivery windows and simplified return policies. The phenomenon is most visible in urban apartment markets where lease durations drive furnishing decisions.
US Mattress Bases Market Segmentation
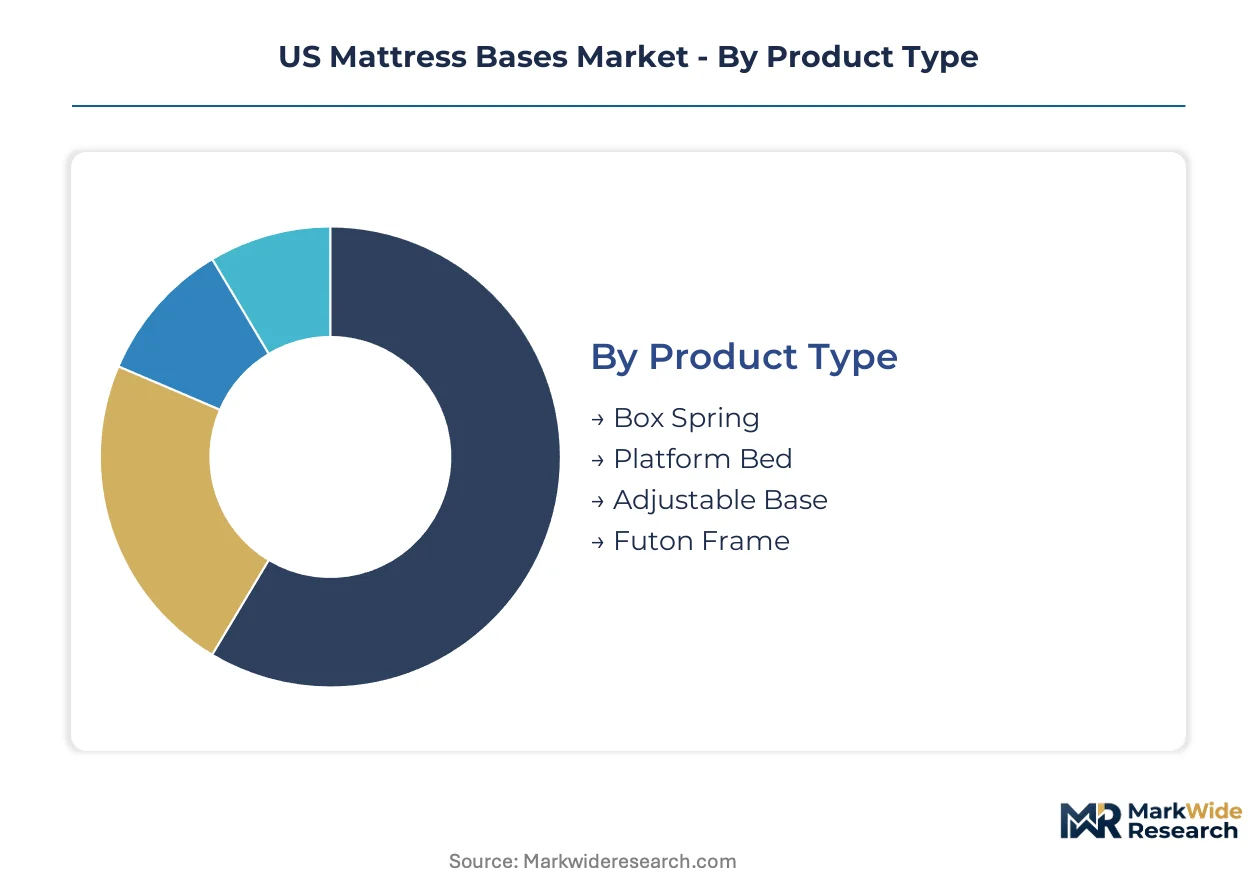
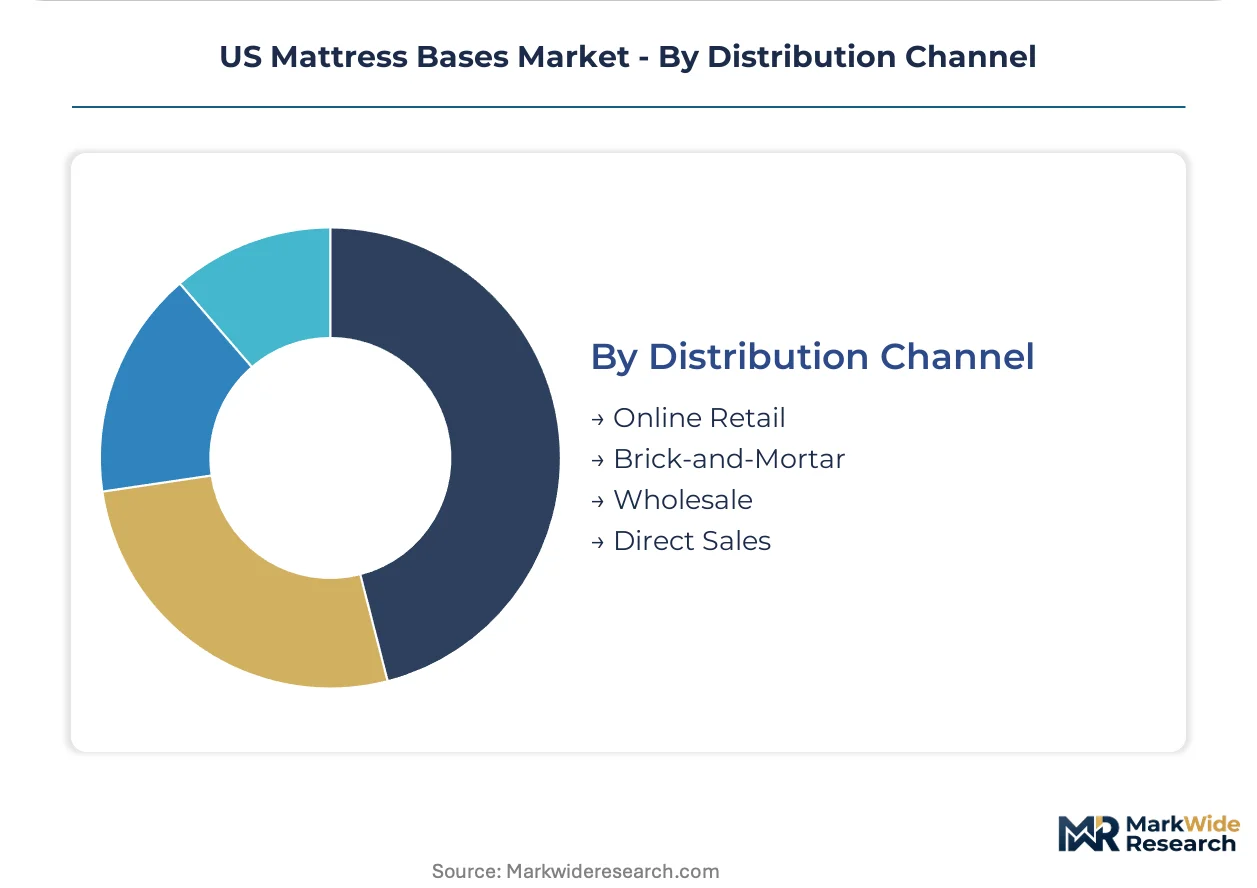
Mattress base segmentation reveals divergent margin architectures across construction methods and procurement pathways. Product type and distribution channel classifications expose where value capture concentrates versus where volume throughput dominates.
Product Type:
Margin pools concentrate in motorized assemblies and premium upholstered platforms rather than commodity foundations.
- Box Spring:Traditional coil-spring foundation with fabric-wrapped wood frame construction. Demand concentrates in replacement cycles across the Southeast manufacturing corridor where legacy supply chains sustain cost-competitive production. Hotel chains compressing refresh timelines from seven to four years generate predictable institutional procurement.
- Adjustable Base:Motorized articulated deck with lift actuators rated for repeated cycle durability. Aging demographics and clinical-to-consumer wellness positioning expand adoption beyond hospital settings into residential master bedrooms across Texas and Florida migration corridors.
- Platform Bed:Solid wood or composite slat system providing rigid surface support. First-time homebuyers in Sun Belt apartment markets prioritize minimalist aesthetics with reinforced dynamic load ratings.
- Futon Frame:Metal folding frame accommodating convertible mattress configurations. Rental and dormitory demand sustains steady replacement cycles with limited innovation headroom.
The dominant share belongs to Box Spring foundations, while Adjustable Base is closing the gap fastest.
Material:
Cost tier stratification separates certified low-emission substrates from commodity inputs facing regulatory pressure.
- Upholstered:Fabric-wrapped platform with polyurethane foam padding and reinforced perimeter support. California's SB 1019 chemical disclosure mandate forces reformulation toward certified low-emission substrates commanding 15-25% input premiums.
- Metal:Steel grid framework or folding mechanism with powder-coat finish. Georgia and North Carolina steel component production faces commodity price volatility that assemblers cannot fully pass through to price-sensitive buyers.
- Wood:Solid hardwood or engineered lumber slat construction with natural or stained finish. FTC Guides for Environmental Marketing Claims constrain sustainable sourcing claims without third-party chain-of-custody documentation.
- Composite:Engineered wood product or recycled material matrix with uniform structural properties. Emerging specification among cost-optimized platform bed producers seeking dimensional stability.
Metal retains volume leadership, though Upholstered platforms are expanding most quickly.
Size:
Application context determines specification, with residential master bedrooms and hospitality suites driving divergent dimension requirements.
- Queen:Standard residential specification for couples and guest accommodations. Dominates first-time homebuyer procurement in Texas and Florida new construction corridors.
- King:Premium residential and upscale hospitality standard. Hotel chain base refresh programs concentrate procurement with domestic qualified suppliers meeting CPSC flammability standards.
- Twin:Single-occupancy specification for children's rooms, dormitories, and military housing. Sustained demand from institutional procurement with compressed replacement cycles.
- Full:Transitional size for adolescent rooms and compact apartments. Limited growth trajectory as consumers bypass for Queen specification.
Queen holds the dominant position, while King is gaining share fastest among premium residential buyers.
Distribution Channel:
Customer type and geography together determine channel selection, with urban apartment markets exhibiting distinct procurement behavior.
- Online Retail:Pure-play digital storefront with compressed delivery windows and simplified return policies. Urban lease-duration furnishing decisions treat bases as replaceable appliances rather than long-term investments.
- Brick-and-Mortar:Furniture mart and big-box retail with tactile evaluation and white-glove delivery coordination. Regional distributors capture value in markets where physical inspection dominates purchase decisions.
- Wholesale:Bulk procurement channel serving furniture retailers and hospitality procurement departments. Traditional markup structures face erosion from direct-to-consumer logistics bypassing intermediary tiers.
- Direct Sales:Manufacturer-owned channel with captive fulfillment network. Captures margin pools previously allocated to regional distributors through controlled last-mile delivery.
Brick-and-Mortar maintains the largest share, though Online Retail is climbing the fastest among first-time buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finished goods capacity clusters disproportionately in Georgia and North Carolina, exposing national fulfillment networks to localized weather disruptions while compressing logistics costs for Southeast-adjacent demand corridors. This concentration shapes how manufacturers calibrate inventory positioning against Sun Belt population migration patterns.
Southeast Manufacturing Belt
Georgia and North Carolina host the dominant share of steel component fabrication and upholstered base assembly, with hotel chain procurement compressing refresh cycles from seven to four years. CPSC 16 CFR Part 1633 flammability enforcement elevates certified domestic suppliers above uncertified imports. Charlotte and High Point furniture manufacturing corridors concentrate adjustable base motor integration and final assembly operations.
Texas Demand Corridor
Houston and Dallas-Fort Worth new construction velocity outpaces legacy manufacturing footprint, creating fulfillment gaps that reward regional distribution center placement. First-time homebuyers in these metros specify reinforced platform beds with dynamic load ratings exceeding 1,200 pounds. Austin and San Antonio apartment markets exhibit accelerated online procurement treating bases as replaceable appliances.
Florida Migration Zone
Tampa and Orlando retirement communities drive adjustable base adoption beyond clinical settings into residential master bedrooms. Miami hospitality procurement concentrates with domestic suppliers meeting federal flammability standards. Jacksonville and Fort Lauderdale logistics hubs face capacity constraints from inbound component flows serving Southeast assembly plants.
California Regulatory Zone
Los Angeles and San Francisco Bay Area demand concentrates in upholstered platforms reformulated for SB 1019 chemical disclosure compliance. Low-emission foam substrates command 15-25% input premiums, squeezing margins without commensurate price elasticity. Sacramento regulatory proximity shapes manufacturer legal staffing and compliance documentation workflows.
Midwest Replacement Market
Chicago and Detroit legacy housing stock sustains steady box spring replacement cycles through brick-and-mortar furniture mart channels. Cleveland and Indianapolis procurement patterns favor tactile evaluation over digital purchasing. Regional distributors capture value in markets where physical inspection dominates purchase decisions despite wholesale markup structures.
US Mattress Bases Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with motorized articulation specialists commanding premium positioning while metal grid fabricators compete on input cost management. The vendor base separates into three strategic tiers: vertically integrated steel component producers controlling actuator housing supply, direct-to-consumer logistics operators bypassing wholesale markups, and traditional upholstered platform assemblers dependent on regional distributor networks. Competitive moves concentrate on exclusive retail partnerships and white-glove delivery network expansion.
Among publicly traded bedding specialists, Tempur Sealy International and Sleep Number Corporation occupy positions emphasizing adjustable base technology integration, while Leggett & Platt, Inc. anchors the component supply tier with captive steel production. Private operators including Saatva, Inc. and Casper, Inc. exemplify direct-to-consumer archetypes that capture margin pools previously allocated to intermediary distribution layers.
| Leading Market Players |
|---|
| Leggett & Platt, Inc. |
| Ergomotion Inc. |
| Tempur Sealy International |
| Serta Simmons Bedding LLC |
| Sleep Number Corporation |
| Casper, Inc. |
| Saatva, Inc. |
| Purple Innovations, Inc. |
| Spring Air International |
| Others |
Pricing and Supply Chain Analysis
Steel component scale economies in Georgia and North Carolina compress per-unit fixed costs for grid framework production while simultaneously anchoring price floors through concentrated capacity utilization. This geographic clustering shapes how manufacturers calibrate margin recovery against input volatility and regulatory compliance premiums.
Pricing Analysis
CPSC 16 CFR Part 1633 dictates the pricing tier structure by elevating certified domestic suppliers above uncertified import competition. Three-tier pricing structure across premium, standard, and economy levels separates adjustable base motorized assemblies from upholstered platforms and commodity box springs. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in upholstered platforms is intensifying because SB 1019-compliant foam substrates command input premiums without commensurate price elasticity. Platform bed buyers in Texas and Florida exhibit highest price sensitivity, while hospitality procurement for King specifications shows lowest sensitivity due to compressed replacement cycle predictability.
Supply Chain Analysis
Georgia and North Carolina anchor steel component fabrication, upholstered base assembly, and adjustable base motor integration. Raw material dependencies draw from domestic steel coil supply, polyurethane foam substrates, and lift actuator electronics. Single-source vulnerability concentrates in Southeast manufacturing corridors where localized weather disruptions expose national fulfillment networks. Distribution runs through wholesale furniture mart channels, direct-to-consumer white-glove networks, and hospitality procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adjustable base adoption is accelerating residential penetration beyond clinical settings, creating early-cycle expansion tailwinds for motorized assembly specialists and component suppliers.
For Market Incumbents: Shield margin pools by securing exclusive retail partnerships with national furniture chains against direct-to-consumer logistics operators. Invest in CPSC 16 CFR Part 1633 and FCC equipment authorization compliance to create regulatory moats against unlicensed import competition. Expand white-glove delivery networks in Texas and Florida demand corridors to capture fulfillment gaps from legacy manufacturing footprint misalignment. For New Entrants and Emerging Players: Lead with modular platform bed architectures targeting first-time homebuyers in Sun Belt apartment markets who treat bases as replaceable appliances. Target online retail channels with compressed delivery windows and simplified return policies. Pursue direct-to-consumer logistics bypassing wholesale markups entirely, capturing margin pools previously allocated to regional distributors. For Investors and Strategic Acquirers: Motorized articulation specialists with captive electronics integration capabilities represent priority acquisition targets given clinical-to-consumer wellness positioning tailwinds. Long-term viability frames around demographic aging and smart home convergence. Monitor hospitality base refresh program announcements as inflection indicators for institutional demand corridor expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SB 1019 Compliance Investment | California chemical disclosure mandates force substrate reformulation, creating certified-supplier competitive moats. |
| Direct-to-Consumer Launch | White-glove delivery networks capture margin pools previously allocated to wholesale furniture mart intermediaries. |
| Regional Fulfillment Expansion | Texas and Florida distribution centers address Sun Belt population migration outpacing legacy manufacturing footprint. |
| Embedded Sensor Integration | Firmware competencies enable smart home convergence and recurring service revenue attachment. |
| Hospitality Partnership Program | Compressed seven-to-four-year replacement cycles generate predictable institutional procurement corridors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with mattress base manufacturers, hospitality procurement directors, furniture retail buyers, and logistics operators; and secondary validation through CPSC enforcement records, California SB 1019 disclosure filings, FCC equipment authorization databases, and trade customs data. Bottom-up and top-down triangulation cross-referenced component production volumes against finished goods shipment patterns.
Across the analysis window, the forecasting framework modeled product type segmentation, material grade tiers, distribution channel dynamics, and regional demand corridor velocity. CAGRs were derived from regression analysis of replacement cycle compression, demographic aging trajectories, and new construction permit flows. Industry-specific inputs included hospitality procurement schedule disclosures and motor actuator cycle durability specifications.
Forecasts assume regulatory continuity in CPSC flammability enforcement and California chemical disclosure regimes; material policy shifts would require re-modeling. Forecasts reflect assumptions about steel input price stability and Southeast manufacturing corridor operational continuity. Recalibration cycles align with material shifts in hospitality replacement timelines and Sun Belt migration velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Balcony Accessories Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market