
 MDF Decorative Overlays Market | 2026-2036
MDF Decorative Overlays Market Size, Share, and Industry Trends Forecast 2026-2036
MDF Decorative Overlays Market Analysis
The EU Green Deal's embodied carbon reporting requirements is hardening demand for low-emission overlay solutions across European furniture manufacturing. Wilsonart leverages its North American manufacturing scale to supply certified product lines into EU commercial projects. EGGER Group anchors its competitive position through backward integration into resin-impregnated paper production. Hueck Folien GmbH specializes in technical films that meet stringent German indoor air quality standards.
MDF decorative overlays are surfacing materials composed of resin-impregnated papers or thermoplastic films thermally fused onto medium-density fiberboard substrates, typically achieving wear resistance ratings of AC3 to AC5 under EN 438 testing protocols. Their primary purpose is to deliver aesthetic versatility and surface durability to engineered wood panels at lower cost than solid wood or high-pressure laminate alternatives. The textured product category dominates volume flows in European residential cabinetry where tactile authenticity commands price premiums. Laminated overlays lead commercial and hospitality applications where abrasion resistance and hygienic cleanability outweigh design nuance. The 9mm thickness segment captures disproportionate margin pools in wall panel systems where dimensional stability and screw-holding strength determine specification outcomes.
REACH compliance through ECHA and CE marking under the Construction Products Regulation govern chemical content and fire performance of overlay-faced panels entering EU member states. Germany's KBA and France's ANSM do not regulate this sector directly, but national building codes in both countries incorporate EN standards that restrict formaldehyde emissions and flammability ratings in public buildings. Stakeholders must monitor evolving EU taxonomy criteria for sustainable construction materials, as forthcoming delegated acts will likely reclassify overlay chemistry profiles and reshape supplier qualification requirements.
Market Dynamics
EU Green Deal embodied carbon reporting requirements are redirecting procurement decisions toward certified low-emission overlay suppliers, compressing specification timelines for furniture manufacturers across Western Europe.
Growth Catalysts
- REACH compliance mandates:Chemical content restrictions under ECHA are eliminating high-formaldehyde overlay chemistries from EU supply chains, creating replacement demand for compliant alternatives.
- Kitchen retrofit intensity:Residential renovation activity across Germany, France, and the UK is hardening demand for premium textured overlays with tactile authenticity.
- Digital printing advancement:High-resolution direct-to-substrate decoration is reducing minimum order quantities and enabling mass-customization workflows for regional furniture producers.
Market Restraints
- Resin cost volatility:Melamine and urea-formaldehyde resin prices fluctuate with natural gas feedstock costs, compressing margin stability for overlay laminators.
- Supplier concentration:Decorative paper impregnation capacity clusters in Germany and Austria, creating geographic supply risk for southern European panel producers.
- Thickness standardization:EN 438 testing protocols limit product differentiation to surface performance rather than structural innovation, constraining premium positioning.
Strategic Opportunities
- Commercial hospitality expansion:Abrasion-rated laminated overlays for hotel and healthcare furniture remain underpenetrated in Spain and Italy relative to northern markets.
- FSC certification premiums:Chain-of-custody documentation requirements under EU taxonomy delegated acts are creating price stratification favoring certified suppliers.
- Recycled content integration:Post-consumer paper fiber incorporation in overlay substrates aligns with circular economy procurement criteria in public sector tenders.
Industry Challenges
- Color-matching precision:Batch-to-batch consistency in textured embossing requires skilled press operators, and talent scarcity in this function constrains output scaling.
- CE marking timelines:Construction Products Regulation fire performance testing for wall panel applications extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MDF Decorative Overlays Market |
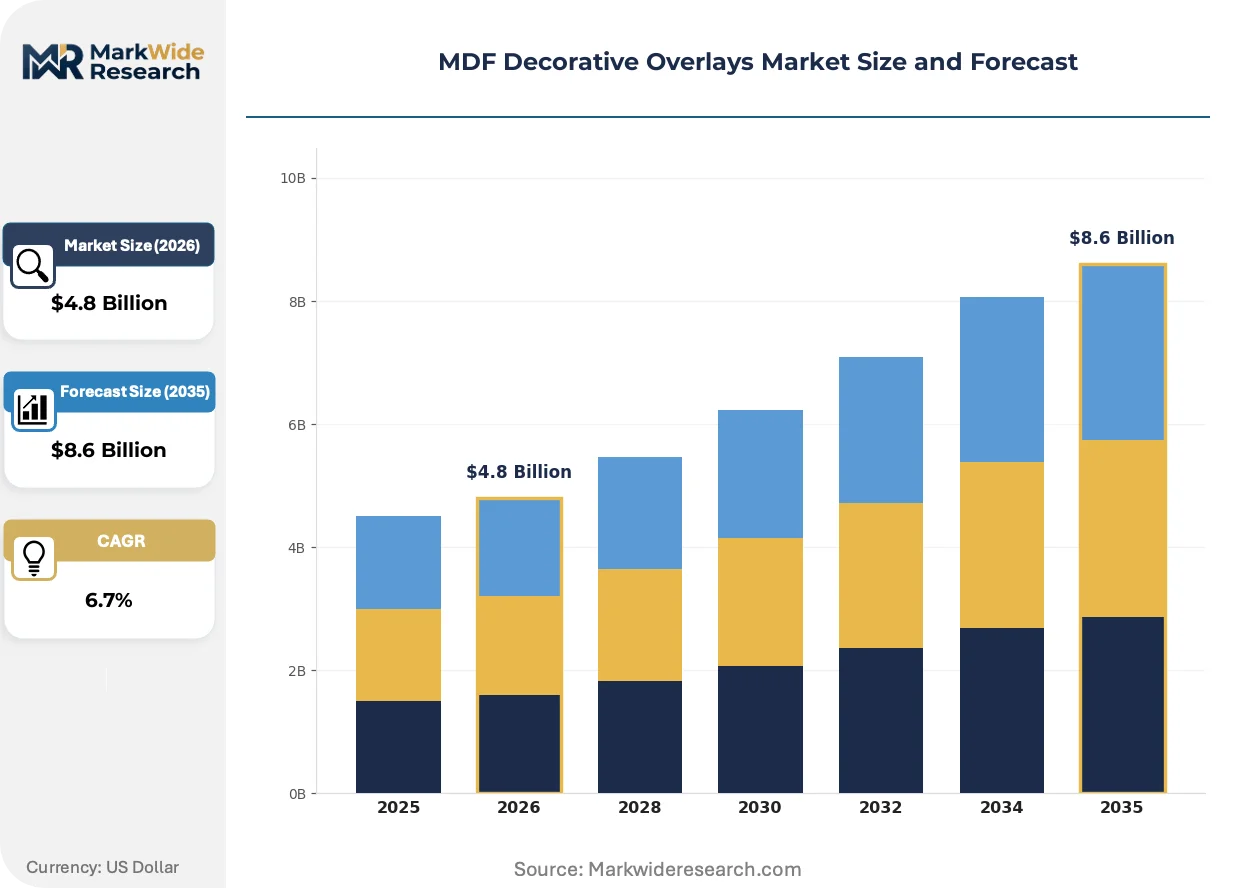
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured, Smooth, Laminated, Veneered Application: Furniture, Wall Panels, Cabinetry, Displays End Use: Residential, Commercial, Institutional, Hospitality Thickness: 3mm, 6mm, 9mm, 12mm |
| Companies Covered | Wilsonart, Hyundai L&C Europe, Omnova Solutions, EGGER Group, Hueck Folien GmbH, Taghleef Industries, Formica Group, Arpa Industriale, Renolit SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MDF Decorative Overlays Market Emerging Trajectories
Surface engineering and regulatory chemistry are converging to redefine competitive advantage in decorative overlays, with sustainability documentation becoming as critical as physical performance.
Digital texture replication technology is decentralizing design authority away from centralized pattern houses toward regional furniture brands. Mid-sized kitchen manufacturers in the UK and Netherlands are adopting cloud-based surface libraries to customize embossing patterns with two-week turnaround. This capability is decentralizing volume concentration historically held by large-format laminate producers.
France's ANSM indoor air quality guidelines are tightening formaldehyde emission thresholds for products installed in schools and healthcare facilities. Overlay suppliers must now maintain dual inventory streams: standard-grade for residential and ultra-low-emission for institutional specification. German cabinetry producers serving both segments are absorbing the inventory complexity to maintain market access.
Direct mill procurement is replacing distributor intermediation for volume furniture manufacturers. Large kitchen OEMs in northern Italy are negotiating frame contracts with impregnation plants, bypassing traditional overlay trading houses. This pattern is most visible in the 9mm thickness segment where annual volume commitments justify dedicated production slots.
MDF Decorative Overlays Market Segmentation
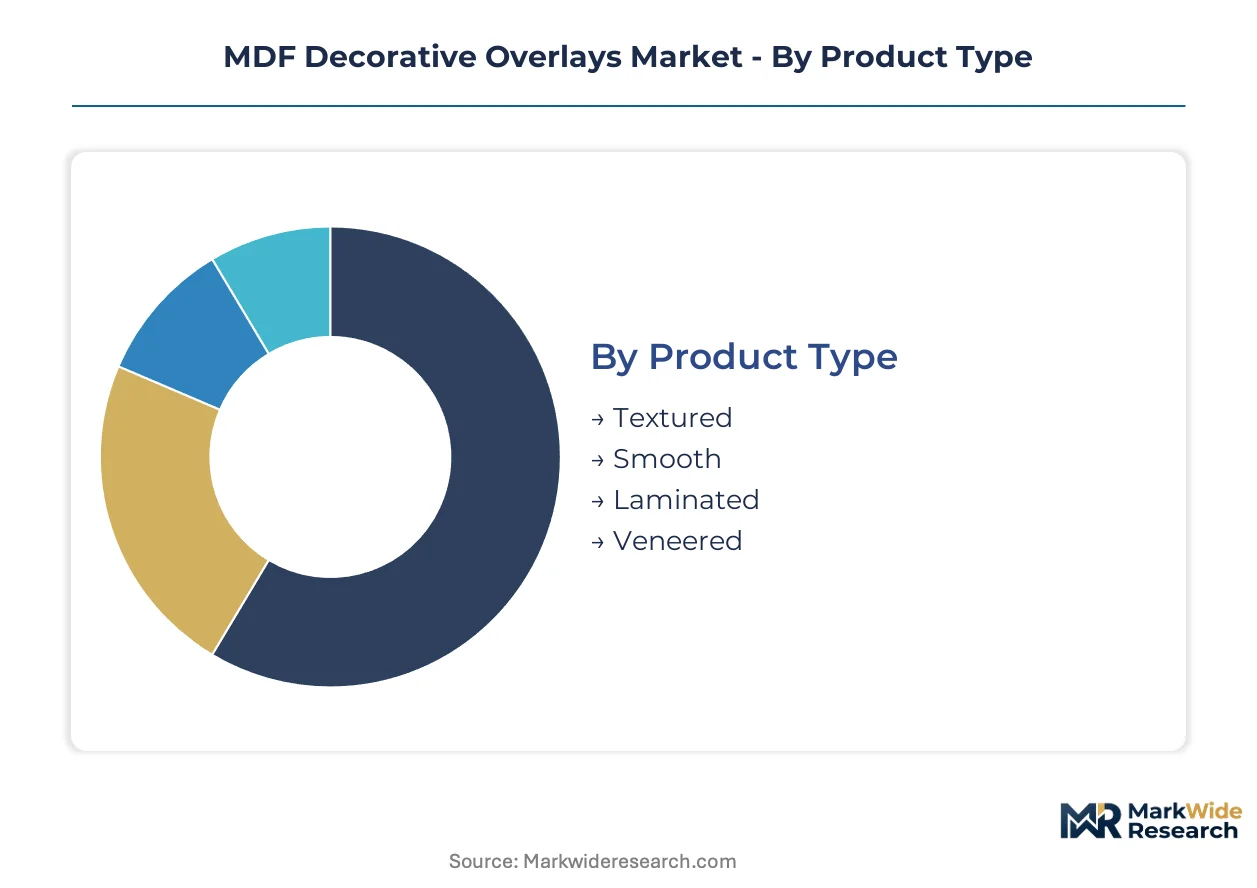
MDF decorative overlays segment across four dimensions that shape procurement workflows and margin structures differently. Product type determines wear resistance specifications and press technology requirements. Application dictates fire performance testing protocols under EN standards. End use governs formaldehyde emission thresholds. Thickness influences substrate sourcing economics and logistics density.
Product Type:
Buyer selection hinges on tactile authenticity requirements versus abrasion resistance priorities in the intended installation environment.
- Textured:Embossed surfaces replicate wood grain or stone patterns through synchronized steel press plates. German and French kitchen retrofit segments absorb the majority of European volume, with end-users paying premiums for haptic authenticity that differentiates mass-market cabinetry.
- Laminated:Thermosetting resin-impregnated papers fused under heat and pressure deliver AC4-AC5 wear ratings. Hotel and healthcare furniture specifications across Spain and Italy favor these overlays where hygienic cleanability and scratch resistance outweigh design nuance.
- Smooth:Flat-finish overlays suit minimalist interior schemes and painted surface preparations. Contemporary wall panel systems in Dutch residential construction specify smooth substrates for uniform coating adhesion.
- Veneered:Thin natural wood slices bonded to MDF cores occupy premium furniture niches. Italian luxury cabinetry producers maintain dedicated veneer sourcing relationships for high-end residential commissions.
Volume sits with Textured; growth tilts toward Laminated.
Application:
Specification intensity varies by installation permanence and exposure to mechanical wear or moisture.
- Furniture:Tables, shelving, and case goods require surface durability against daily contact abrasion. UK flat-pack manufacturers specify 9mm substrates with AC3-rated overlays to balance freight weight with screw-holding strength.
- Wall Panels:Vertical installations prioritize dimensional stability and fire performance over wear resistance. German commercial fit-out contractors source CE-marked 12mm panels for public building applications under national construction codes.
- Cabinetry:Kitchen and bathroom storage units demand moisture-resistant edge sealing alongside decorative faces. French renovation activity concentrates demand in this segment, with replacement cycles accelerating in Paris and Lyon metropolitan areas.
- Displays:Retail fixtures and exhibition systems emphasize lightweight construction and rapid reconfigurability. Temporary installations in Benelux trade show circuits specify thinner substrates for logistical efficiency.
Furniture commands current volume; Wall Panels are climbing the fastest as commercial refurbishment accelerates.
End Use:
Regulatory thresholds for indoor air quality and fire safety segment procurement channels sharply.
- Residential:Private dwelling renovations tolerate standard-grade formaldehyde emissions under EN 13986. German single-family housing retrofits sustain the largest addressable volume in this category.
- Commercial:Office and retail fit-outs balance aesthetic flexibility with replacement cost economics. French corporate real estate managers specify mid-tier overlays for three-to-five-year lease cycle compatibility.
- Institutional:Schools and healthcare facilities face ANSM-guided emission limits in France and comparable state-level protocols in Germany. Dual inventory maintenance raises complexity for suppliers serving both residential and institutional channels.
- Hospitality:Hotels and restaurants demand abrasion-rated surfaces with rapid turnaround replacement capability. Spanish coastal tourism properties drive seasonal specification peaks in this segment.
Residential dominates installed base; Institutional shows the steepest expansion trajectory as public sector procurement tightens environmental criteria.
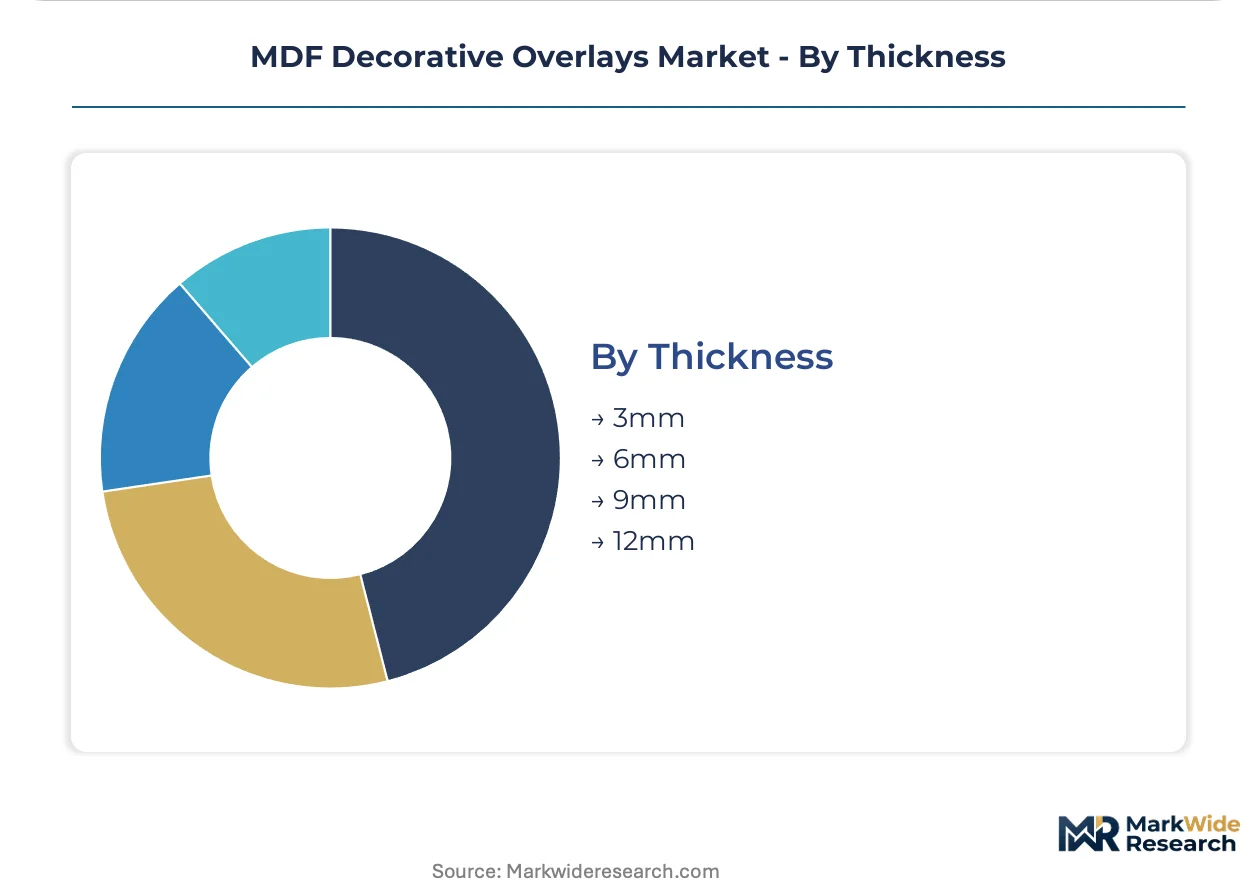
Thickness:
Structural performance requirements and machining characteristics determine substrate selection.
- 3mm:Ultra-thin overlays serve as surface refinishing layers over existing substrates. Display and temporary fixture applications in Netherlands favor this gauge for weight minimization.
- 6mm:Mid-range thickness balances material cost with handling rigidity. Standard furniture production across Italian SMEs concentrates in this specification band.
- 9mm:Enhanced dimensional stability and screw retention support wall-mounted cabinetry and shelving systems. Northern Italian kitchen OEMs negotiate direct mill procurement for annual volume commitments at this thickness.
- 12mm:Maximum rigidity for load-bearing applications and fire-rated wall assemblies. German commercial construction specifications require this gauge for CE-marked compliance in public buildings.
9mm captures disproportionate margin contribution; 12mm is gaining share fastest as fire performance regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhineland industrial corridors concentrate Europe's decorative overlay capacity, with Leverkusen and Cologne hosting resin-impregnated paper production clusters that supply kitchen manufacturers across Western Europe.
Germany
Kitchen retrofit cycles in Bavaria and North Rhine-Westphalia sustain premium textured overlay consumption. KBA-aligned building codes enforce formaldehyde emission thresholds in public construction. Stuttgart's furniture engineering cluster demands AC4-rated laminates for commercial hospitality fixtures.
France
Paris and Lyon metropolitan renovation activity hardens specification timelines for cabinetry overlays. ANSM indoor air quality guidelines mandate dual inventory streams for institutional versus residential supply. Auvergne-Rhône-Alpes hosts impregnation capacity serving southern European panel producers.
United Kingdom
Flat-pack furniture manufacturers in Midlands industrial zones specify 9mm substrates for screw-holding strength in self-assembly cabinetry. REACH compliance through ECHA redirects procurement toward low-emission certified suppliers. Greater Manchester's kitchen OEMs negotiate direct mill contracts bypassing traditional distributors.
Italy
Northern Italian kitchen OEMs in Lombardy and Veneto drive direct procurement patterns for annual volume commitments. CE marking under the Construction Products Regulation governs fire performance testing for wall panel exports. Emilia-Romagna's luxury cabinetry producers maintain dedicated veneer sourcing relationships for high-end residential commissions.
Spain
Coastal tourism properties in Catalonia and Andalusia generate seasonal specification peaks for abrasion-rated hospitality overlays. EN 438 testing protocols limit product differentiation to surface performance ratings. Valencia's commercial fit-out contractors source laminated overlays for hotel refurbishment cycles.
MDF Decorative Overlays Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with FSC chain-of-custody documentation and ultra-low-emission chemistry commanding price stratification. The vendor base clusters around three strategic archetypes: integrated resin-to-overlay manufacturers, specialized technical film producers, and trading houses managing impregnation capacity access. Dominant competitive moves include backward integration into decorative paper production and frame contract negotiations that bypass traditional distribution intermediaries.
Among Germany-based specialists, Hueck Folien GmbH exemplifies the technical film archetype focused on stringent indoor air quality compliance. Wilsonart represents North American manufacturing scale leveraged for EU commercial project supply. EGGER Group anchors the integrated manufacturer tier through captive resin-impregnated paper production.
| Leading Market Players |
|---|
| Wilsonart |
| Hyundai L&C Europe |
| Omnova Solutions |
| EGGER Group |
| Hueck Folien GmbH |
| Taghleef Industries |
| Formica Group |
| Arpa Industriale |
| Renolit SE |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied carbon reporting requirements are forcing furniture manufacturers to certify low-emission overlay sourcing, compelling suppliers to absorb dual-inventory costs and pass through premiums for FSC-certified and ultra-low-formaldehyde product streams.
Pricing Analysis
Performance-based pricing anchored to wear resistance ratings and indoor air quality certification tiers stratifies the market across premium, standard, and economy levels. FSC chain-of-custody documentation and ANSM-compliant ultra-low-emission chemistry command substantial premiums over standard-grade residential offerings. Cost compression in commodity textured overlays is intensifying because resin cost volatility tied to natural gas feedstock prices squeezes laminator margins. Large kitchen OEMs negotiating direct mill procurement exhibit lowest price sensitivity, while Italian SME furniture producers remain most exposed to spot-market resin fluctuations.
Supply Chain Analysis
Direct-to-OEM channels handle volume commitments from northern Italian kitchen manufacturers, while distributor intermediation persists for smaller Spanish and southern European panel producers. Decorative paper impregnation capacity clusters in Germany and Austria, with Rhineland industrial corridors feeding resin-impregnated substrates across Western Europe. Melamine resin, urea-formaldehyde binders, and post-consumer paper fiber constitute critical input dependencies. Single-source vulnerability concentrates in German-Austrian impregnation clusters, exposing southern European producers to geographic supply risk. Distribution runs through frame contracts for annual volume commitments above threshold levels, with trading houses managing residual spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable suppliers as REACH compliance and EU taxonomy delegated acts eliminate high-formaldehyde chemistries and uncertified competitors.
For Market Incumbents: Extend backward integration into decorative paper production to secure captive resin-impregnation capacity and defend margin pools against direct mill procurement trends. Anchor competitive position through dual-certification maintenance for both residential-grade and institutional ultra-low-emission product streams, as ANSM-guided thresholds in France and comparable German state protocols harden specification requirements. For New Entrants and Emerging Players: Begin with commercial hospitality applications in Spain and Italy, where abrasion-rated laminated overlays remain underpenetrated relative to northern European markets. Target Valencia and Catalonia hotel refurbishment cycles with AC4-AC5 rated products emphasizing rapid turnaround replacement capability. Build initial volume through seasonal specification peaks before expanding into year-round institutional procurement channels. For Investors and Strategic Acquirers: Re-rating potential sits with integrated resin-to-overlay manufacturers given EU Green Deal procurement redirection toward certified low-emission suppliers. Long-term viability favors archetypes with captive impregnation capacity and established FSC chain-of-custody documentation. Monitor ECHA delegated act timing for sustainable construction material reclassification as the critical inflection signal for supplier qualification reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Decorative Paper Production | Captive resin-impregnation capacity secures margin pools against direct procurement trends bypassing distributors. |
| Dual-Certification Investment for Institutional and Residential Tiers | ANSM-guided emission limits in France and German state protocols require parallel inventory streams for market access. |
| Digital Texture Replication Technology Deployment | Cloud-based surface libraries enable regional furniture brands to customize embossing patterns with compressed turnaround. |
| Direct Mill Procurement Frame Contracts | Northern Italian kitchen OEMs negotiate annual volume commitments at 9mm thickness, displacing traditional trading houses. |
| Post-Consumer Paper Fiber Integration | Circular economy procurement criteria in public sector tenders favor overlay substrates with recycled content documentation. |
Methodological Framework
Multi-period observation of resin cost volatility patterns, certification adoption rates, and procurement channel migration anchored the trend analysis, supplemented by interviews with overlay laminator plant managers, furniture OEM procurement leads, decorative paper impregnation specialists, and ECHA regulatory affairs consultants. Secondary validation drew from REACH compliance filings, EU Construction Products Regulation databases, FSC chain-of-custody registry records, and German KBA-aligned building code documentation. Bottom-up volume modeling across thickness segments and product categories triangulated against top-down European furniture production indices.
Input-output matrices mapped resin feedstock cost pass-through mechanics to overlay pricing tiers, with segmentation dimensions spanning product type, application intensity, end-use regulatory threshold, and thickness-dependent structural performance. CAGRs were derived through regression analysis of historical retrofit cycle data and forward projection of EU taxonomy implementation timelines. Forecast inputs included natural gas price trajectory assumptions and digital printing technology diffusion rates among mid-sized regional manufacturers.
Resin cost volatility spikes, ECHA delegated act timing delays, and abrupt shifts in public sector circular economy procurement criteria are the dominant revision risks to overlay demand projections. Practitioners should monitor ANSM guideline updates and EU taxonomy construction material reclassification signals for early indicators of specification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Window Covering Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Louvre Windows Market