
 United States Wall Coverings Market | 2026-2036
United States Wall Coverings Market Size, Share, and Industry Trends Forecast 2026-2036
United States Wall Coverings Market Analytics
Skilled installer availability is rotating toward scarcity in major metropolitan markets, pushing project timelines outward and elevating labor costs for professional-grade applications. Mohawk Industries leverages its integrated manufacturing footprint to control substrate supply for luxury vinyl wall products. Sherwin-Williams Company anchors its position through proprietary coating chemistries that extend product durability in high-traffic commercial environments. York Wallcoverings specializes in digital print customization, competing on design velocity rather than scale economics.
Wall coverings comprise surface-applied materials and coatings designed to protect, decorate, or acoustically modify interior vertical surfaces, with vinyl wallpaper typically manufactured through calendering or spread-coating PVC onto fabric or paper backings at thicknesses ranging from 0.15 to 0.50 millimeters. These products serve primarily to enhance aesthetic environments while providing scrubbability, moisture resistance, or sound attenuation in residential and commercial spaces. Paint commands the largest installed base due to its low material cost and universal applicability, though fabric wall coverings capture disproportionate margin pools in luxury hospitality and corporate interiors where tactile quality differentiates space value. DIY installation channels are expanding fastest among vinyl wallpaper and peelable products, reflecting consumer preference for weekend-project accessibility and reduced contractor dependency.
The EPA regulates VOC emissions through its Architectural Coatings Rule, while OSHA workplace safety standards govern installer exposure to adhesives and surface preparation chemicals; California Air Resources Board amendments to Suggested Control Measures further constrain solvent-based product formulations in the country's largest state economy. The Federal Trade Commission's Green Guides shape marketing claims around recycled content and biodegradability, influencing manufacturer R&D priorities and product labeling strategies. Stakeholders must monitor evolving state-level chemical disclosure requirements and building code harmonization efforts that could fragment compliance obligations across multi-state project portfolios.
Market Dynamics
California's Title 24 building energy standards are tightening material performance requirements for interior finishes, forcing manufacturers to reformulate substrates and coatings while reshaping competitive positioning across residential and commercial segments.
Growth Catalysts
- Millennial renovation spending:Residential investment by millennial homeowners is amplifying demand for premium vinyl wallpaper and fabric wall coverings in Sun Belt housing markets.
- DIY channel expansion:Peelable vinyl products and weekend-installation formats are reducing contractor dependency and opening new consumer segments.
- OSHA workplace safety standards:Stricter installer exposure protocols for adhesives and surface preparation chemicals are driving water-based adhesive adoption and product reformulation.
Market Restraints
- PVC resin price volatility:Feedstock cost fluctuations for calendered vinyl substrates compress margin stability for mid-tier manufacturers.
- Paint substitution threat:Low-cost interior paint retains dominant installed base across price-sensitive residential renovations and maintenance cycles.
- Skilled installer scarcity:Labor availability constraints in major metropolitan markets elongate project timelines and elevate professional application costs.
Strategic Opportunities
- Texas and Florida construction concentration:New construction and remodeling activity in these Sun Belt states outpaces national averages, creating localized demand pull.
- Digital print customization:On-demand manufacturing workflows enable design velocity competition and reduced inventory carrying costs for specialty producers.
- Federal Trade Commission Green Guides:Marketing claim standards around recycled content are directing R&D investment toward bio-based backings and circular material flows.
Industry Challenges
- Multi-state compliance fragmentation:Evolving state-level chemical disclosure requirements create administrative burden for project portfolios spanning jurisdictions.
- Acoustic performance specification complexity:Integration of sound attenuation ratings with aesthetic requirements demands cross-functional engineering coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Wall Coverings Market |
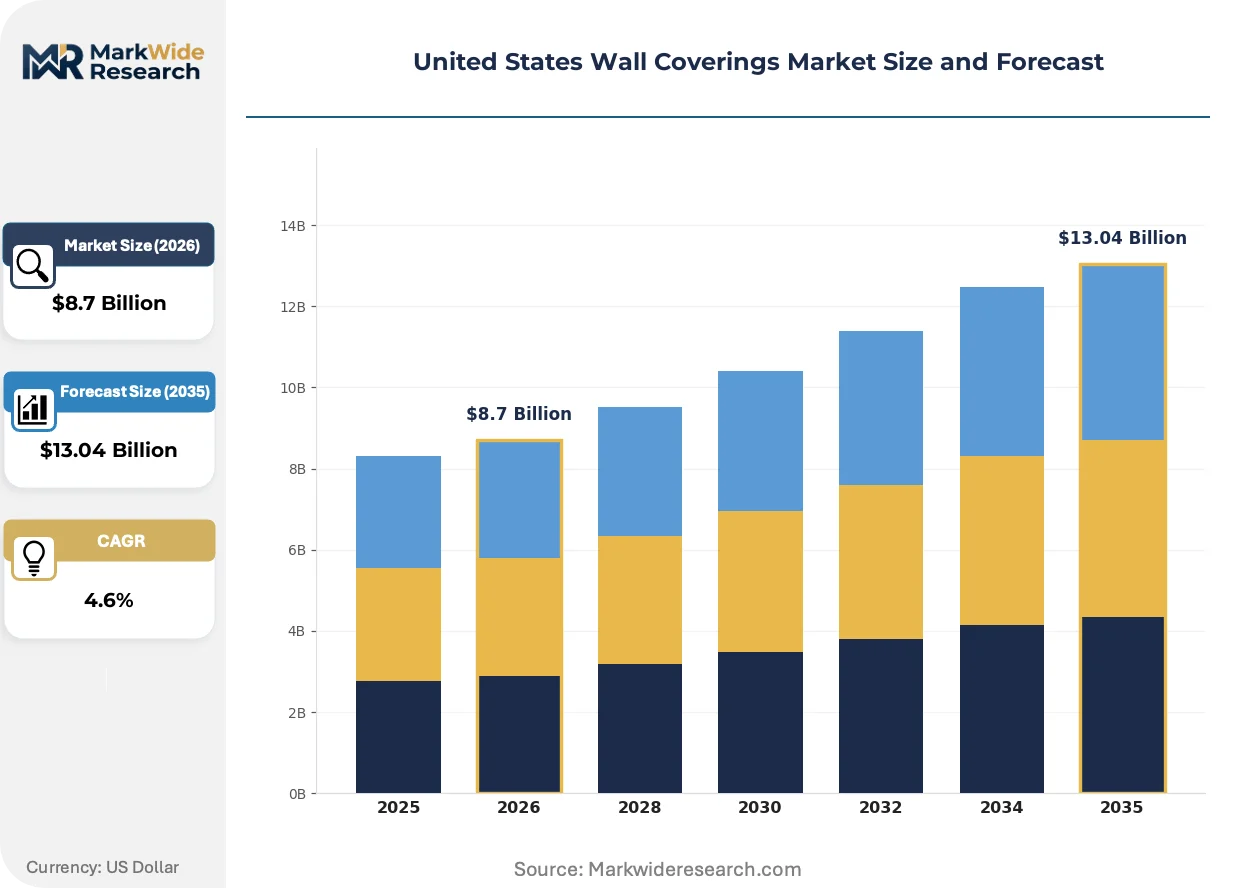
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Wallpaper, Fabric Wall Coverings, Paint, Wood Paneling Application: Residential, Commercial, Industrial, Hospitality Installation Type: DIY, Professional, Temporary, Permanent Design Style: Modern, Traditional, Vintage, Abstract |
| Companies Covered | Benjamin Moore & Co., Mohawk Industries, Sherwin-Williams Company, Crossville Inc., Georgia-Pacific, F. Schumacher & Co., Brewster Home Fashions, Maya Romanoff Corporation, York Wallcoverings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Wall Coverings Market Evolving Landscape
Material science advances and regulatory chemistry constraints are actively splitting the market between high-performance commercial specifications and accessible residential formats, with manufacturing investment flowing toward digital production capabilities.
Digital printing technology for vinyl substrates is bifurcating the market between mass-customization specialists and scale-oriented producers. Hospitality and corporate interior designers are adopting short-run custom patterns at accelerating pace. This technology is compressing traditional design-to-installation cycles while enabling geographic proximity between production and project sites.
The EPA's Architectural Coatings Rule and California Air Resources Board amendments to Suggested Control Measures are constraining solvent-based adhesive formulations. Manufacturers are reformulating toward waterborne and hot-melt systems to maintain distribution access. Commercial high-traffic applications face the steepest compliance transition costs as durability requirements clash with VOC reduction mandates.
Buyer preference for tactile quality in luxury hospitality and corporate interiors is rotating specification authority toward interior designers and away from general contractors. Fabric wall coverings capture disproportionate margin pools in these segments as surface material becomes a differentiated space-value component. This shift concentrates demand in coastal metropolitan corridors with dense luxury commercial development pipelines.
United States Wall Coverings Market Segmentation
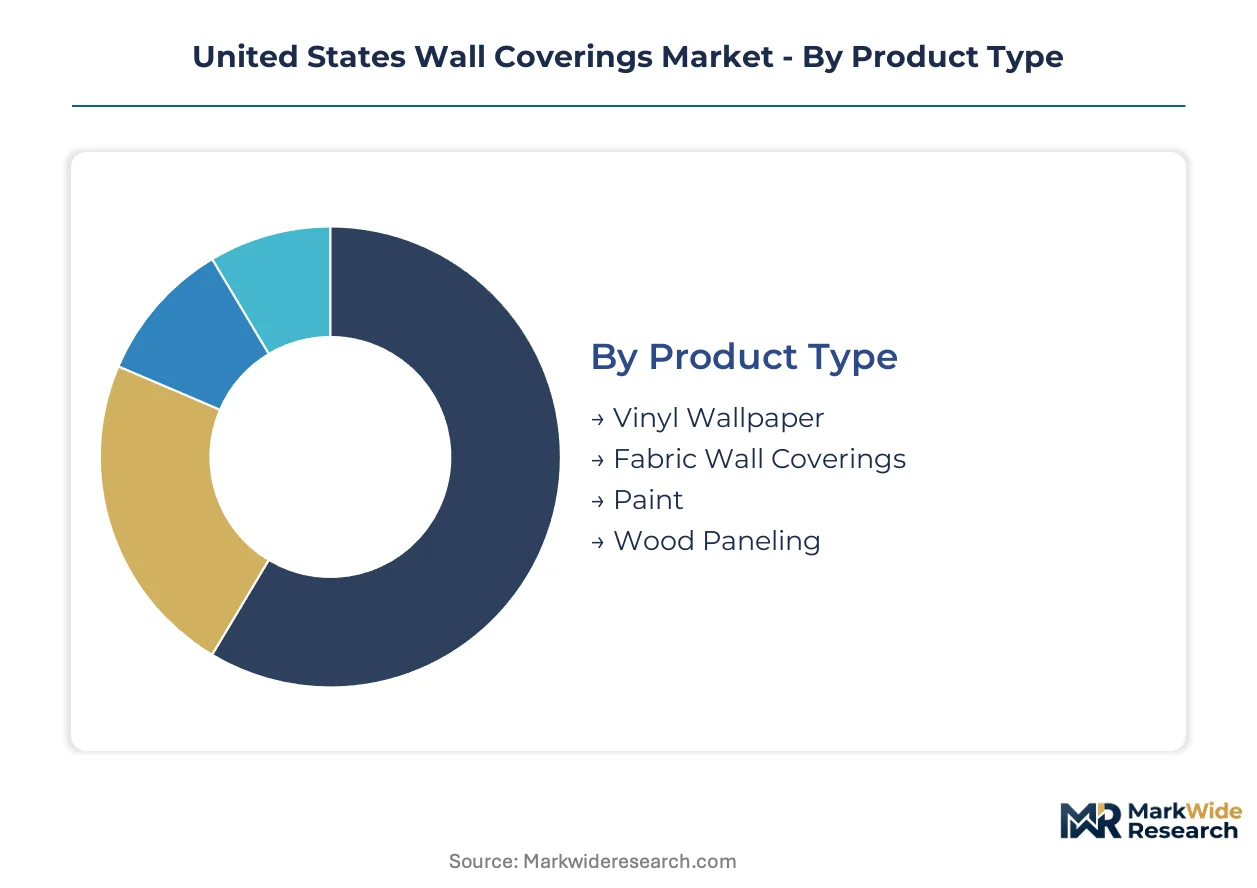
Wall coverings in the United States fragment across material chemistry, installation expertise, and design specification authority. Each segmentation axis captures distinct margin pools and competitive dynamics that manufacturers must navigate simultaneously.
Product Type:
Premium margin pools concentrate in specialized substrates where tactile quality differentiates space value, while volume economics dominate commoditized alternatives.
- Vinyl Wallpaper:Calendered PVC substrates at 0.15-0.50 millimeter thickness deliver scrubbability and moisture resistance for high-traffic residential kitchens and bathrooms. Sun Belt millennial renovation spending is amplifying demand for peelable formats that reduce contractor dependency.
- Fabric Wall Coverings:Woven textile substrates bonded to paper or non-woven backings provide acoustic attenuation and tactile luxury in corporate boardrooms and hospitality suites. California Title 24 energy standards are tightening material performance requirements for these specification-driven applications.
- Paint:Acrylic and alkyd resin formulations command the largest installed base through low material cost and universal applicability across price-sensitive maintenance cycles.
- Wood Paneling:Engineered veneer and solid lumber systems serve accent walls and commercial warmth specifications where natural material authenticity carries design premium.
Vinyl wallpaper holds installed capacity. Fabric wall coverings are rotating up the share rankings.
Application:
Geographic construction concentration in Texas and Florida is reshaping demand distribution across end-use categories.
- Residential:Single-family and multifamily housing units drive volume consumption of DIY-friendly formats. Millennial homeowners in Sun Belt markets are prioritizing weekend-installation accessibility over professional application.
- Commercial:Office, retail, and institutional spaces specify durability-rated products for high-traffic endurance. OSHA workplace safety standards for adhesive exposure are forcing water-based system adoption in professional installation workflows.
- Industrial:Manufacturing and warehouse facilities utilize heavy-duty vinyl and protective coatings where chemical resistance and cleanability override aesthetic priorities.
- Hospitality:Hotels, restaurants, and entertainment venues capture disproportionate margin pools through designer-specified fabric wall coverings. Digital print customization is compressing design-to-installation cycles for property refresh programs.
Residential commands volume leadership. Hospitality is climbing the fastest.
Installation Type:
Skilled labor scarcity in major metropolitan markets is elevating the strategic importance of installation accessibility.
- DIY:Peel-and-stick vinyl products and pre-pasted wallpapers enable consumer-direct purchase without contractor coordination. Channel expansion is opening new consumer segments previously excluded by professional installation cost barriers.
- Professional:Contracted application ensures substrate preparation, pattern matching, and warranty compliance for premium specifications. Labor availability constraints in California and Northeast corridors are elongating project timelines and elevating costs.
- Temporary:Removable adhesive systems serve rental properties and event staging where surface restoration obligations limit permanent modification.
- Permanent:Traditional paste-applied and mechanical fastening methods anchor long-term installations in owner-occupied commercial and residential assets.
Professional installation holds legacy dominance. DIY is gaining share fastest.
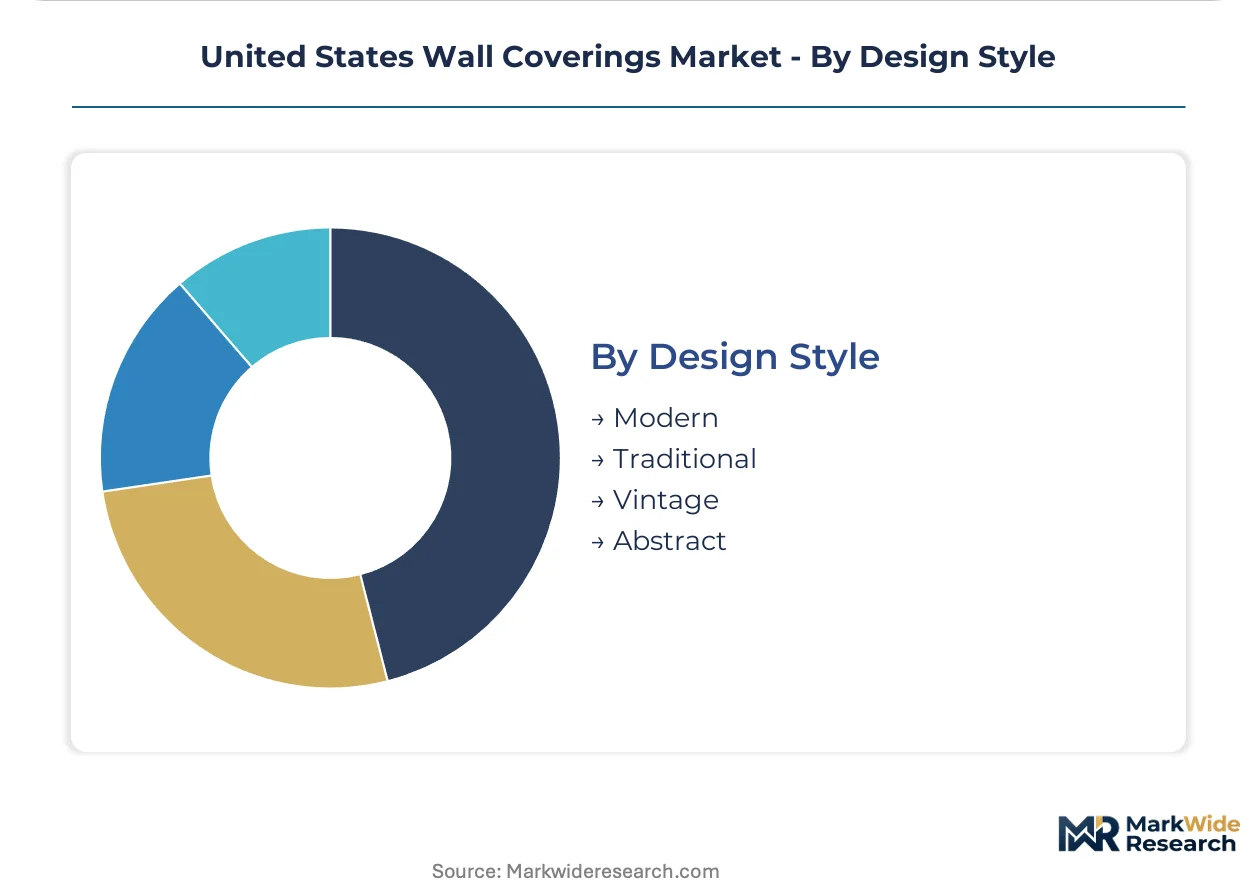
Design Style:
Specification authority is rotating toward interior designers and away from general contractors in luxury commercial segments.
- Modern:Clean lines, geometric patterns, and neutral palettes align with contemporary corporate and residential minimalism. Digital printing technology enables rapid customization of short-run contemporary motifs.
- Traditional:Classic damasks, florals, and architectural motifs persist in heritage hospitality and residential restoration projects. York Wallcoverings competes on design velocity for this specification segment.
- Vintage:Reproduction patterns and aged-effect textures serve boutique hospitality and residential nostalgia trends. Federal Trade Commission Green Guides constrain marketing claims around recycled content authenticity.
- Abstract:Non-representational forms and experimental color fields differentiate luxury commercial spaces where surface material becomes a space-value component.
Traditional styling holds specification heritage. Modern is ascending fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's Architectural Coatings Rule and California Air Resources Board amendments anchor regulatory pressure across the dominant geography, while state-level building codes fragment compliance obligations across multi-state project portfolios.
California
Title 24 building energy standards tighten material performance requirements for interior finishes, forcing substrate reformulation among manufacturers serving the country's largest state economy. The California Air Resources Board constrains solvent-based adhesive formulations through Suggested Control Measures amendments. Los Angeles and San Francisco metropolitan corridors concentrate specification-driven demand for fabric wall coverings in luxury commercial developments.
Texas
New construction and remodeling activity in Dallas-Fort Worth and Houston outpaces national averages, creating localized demand pull for vinyl wallpaper in residential applications. The Texas Commission on Environmental Quality administers VOC regulations that align with federal EPA standards while allowing regional formulation flexibility. Austin's technology sector expansion drives corporate interior renovation cycles specifying digital-print customization.
Florida
Sun Belt migration patterns amplify residential renovation spending, with Miami and Tampa Bay markets prioritizing moisture-resistant vinyl products for humid climates. The Florida Building Code incorporates wind-load and moisture-performance standards that influence interior finish specifications in coastal construction. Orlando's hospitality development pipeline sustains demand for designer-specified wall coverings in hotel refresh programs.
New York Metro
Skilled installer scarcity in Manhattan and Brooklyn elongates project timelines and elevates labor costs for professional-grade applications. The New York State Department of Environmental Conservation enforces VOC limits stricter than federal baselines for architectural coatings. Corporate headquarters renovations in Midtown and Hudson Yards rotate specification authority toward interior designers for fabric wall coverings.
Pacific Northwest
Seattle and Portland housing markets prioritize sustainable material specifications, with the Oregon Department of Environmental Quality and Washington Department of Ecology advancing chemical disclosure requirements beyond federal standards. Regional preference for bio-based backings directs procurement toward products marketing recycled content claims. Tech sector office expansions in Seattle's South Lake Union district drive commercial interior specification velocity.
United States Wall Coverings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers controlling substrate supply while specialty producers compete on design velocity. The vendor base splits between scale-oriented producers serving volume residential channels and customization specialists capturing premium commercial specifications. Three archetypes dominate: integrated chemical-coating conglomerates, digital-print customization specialists, and regional fabrication houses. Competitive moves concentrate on backward integration into substrate supply and geographic proximity between production and Sun Belt project sites.
Among integrated manufacturers, Mohawk Industries anchors the scale-driven tier through captive control of luxury vinyl substrate production. Sherwin-Williams Company occupies a position exemplifying coating chemistry specialization for high-traffic commercial durability requirements. York Wallcoverings represents the design-velocity archetype, competing through digital print customization rather than manufacturing scale. These three companies illustrate the strategic divergence between supply-chain control, chemical formulation expertise, and on-demand manufacturing workflows.
| Leading Market Players |
|---|
| Benjamin Moore & Co. |
| Mohawk Industries |
| Sherwin-Williams Company |
| Crossville Inc. |
| Georgia-Pacific |
| F. Schumacher & Co. |
| Brewster Home Fashions |
| Maya Romanoff Corporation |
| York Wallcoverings |
| Others |
Value Network & Pricing Analysis
California Air Resources Board amendments to Suggested Control Measures gate distribution access for solvent-based formulations while simultaneously stratifying price tiers between compliant waterborne systems and legacy products. This regulatory filter concentrates pricing power among integrated manufacturers with reformulation capabilities while fragmenting competitive positioning for mid-tier suppliers dependent on commodity substrates.
Pricing Analysis
Geographic price spreads between Sun Belt installation markets and Northeast metropolitan corridors reflect labor cost differentials and material transportation distances. Three-tier pricing structure across premium, standard, and economy levels segments by substrate chemistry and customization depth, with fabric wall coverings commanding substantial premiums over calendered vinyl in hospitality specifications. Pricing pressure stems from PVC resin feedstock volatility compressing margins for non-integrated producers. Residential renovation buyers exhibit highest price sensitivity, while corporate interior designers prioritize tactile quality over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate residential vinyl wallpaper distribution, while hospitality fabric specifications require strategic stockpiling of specialty textile substrates to accommodate compressed design-to-installation cycles. Domestic manufacturing concentrates in Georgia, North Carolina, and Ohio, with raw material dependencies spanning PVC resin from Gulf Coast petrochemical corridors, textile backings from Southeast Asian weaving operations, and coating chemicals from Ohio River Valley specialty chemical producers. Single-source vulnerability concentrates in digital print ink supply chains. Distribution runs through big-box retail channels for DIY formats and specification houses for commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against interior paint's persistent cost advantage and universal applicability across price-sensitive residential maintenance cycles.
For Market Incumbents: Shield market position through backward integration into substrate supply and captive control of coating chemistry formulation capabilities. Mohawk Industries exemplifies this defensive posture through integrated luxury vinyl production. Prioritize certification investment for California Title 24 compliance to maintain access to the country's largest state economy. Channel control through specification house relationships defends against DIY format commoditization. For New Entrants and Emerging Players: Differentiate on digital print customization velocity rather than manufacturing scale economics. Target hospitality refresh programs in Orlando and Miami where compressed renovation cycles reward design responsiveness. White-space exists in bio-based backing development for Pacific Northwest sustainable procurement preferences. Go-to-market angle should emphasize geographic proximity between production and Texas-Florida project clusters. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent companies seeking to divest non-core interior finish divisions with stranded solvent-based product portfolios. Long-term viability hinges on reformulation capabilities aligned with VOC reduction trajectories across multiple state jurisdictions. Acquisition archetype: regional fabrication houses with established installer networks in Sun Belt growth corridors. Signal to watch: California Air Resources Board expansion of Suggested Control Measures to additional chemical categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Mohawk Industries controls captive PVC production for margin stability against resin volatility. |
| Digital Print Customization Capability | York Wallcoverings compresses design cycles for hospitality short-run specifications. |
| Water-Based Adhesive Reformulation | Sherwin-Williams maintains EPA Architectural Coatings Rule compliance for commercial distribution. |
| Sun Belt Distribution Expansion | Proximity to Texas and Florida construction clusters reduces logistics costs for residential volume. |
| Bio-Based Backing Development | Federal Trade Commission Green Guides compliance opens Pacific Northwest specification channels. |
Research Methodology
Desk research of EPA regulatory filings, California Air Resources Board rulemakings, and OSHA workplace safety standards preceded structured interviews with wall covering plant managers, specification house buyers, hospitality interior designers, and residential contractor procurement leads. Secondary validation drew from customs trade data, SEC 10-K disclosures of publicly traded manufacturers, and building permit databases for Sun Belt metropolitan areas. Bottom-up volume estimates triangulated against top-down construction spending allocations across the analysis window.
Variance decomposition across material chemistry, installation type, and end-use application segments shaped the analytical framework over the projection horizon. Modeled dimensions included substrate type, design specification authority, geographic construction cluster, and regulatory compliance tier. CAGRs derived from regression against housing starts, renovation spending indices, and commercial construction put-in-place series. Industry-specific inputs encompassed PVC resin price indices and skilled labor availability metrics for major metropolitan markets.
Material uncertainties — feedstock cost volatility, state-level regulatory fragmentation, and installer labor scarcity — sit outside the modeled envelope. Forecasts reflect assumptions around millennial homeownership trajectories and Sun Belt migration persistence. Revision becomes warranted when California Title 24 amendments accelerate beyond modeled timelines or PVC resin supply disruptions cross thresholds affecting mid-tier manufacturer viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Mattress Topper Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
Removable Wallpaper Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Stained Glass Market
Homecare and Decor
USA Bed Pillow Market