
 ASEAN UPVC Doors and Windows Market | 2026-2036
ASEAN UPVC Doors and Windows Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN UPVC Doors and Windows Market Outlook
SNI certification for UPVC profile extrusion is unwinding the competitive landscape across Indonesia and neighboring markets. VEKA Group leverages its European technical heritage to sustain premium positioning in specification-driven projects. Deceuninck anchors its ASEAN presence through localized compounding operations that reduce lead times for tropical-grade formulations. LG Hausys competes aggressively on color stability warranties, a critical differentiator under intense UV exposure.
ASEAN UPVC doors and windows comprise rigid polyvinyl chloride profiles reinforced with galvanized steel inserts, extruded into multi-chamber hollow sections that achieve thermal transmittance values below 1.8 W/m²K when glazed with low-emissivity glass. These assemblies serve primarily as thermally broken envelope elements in climates where cooling loads dominate operational energy. Double-glazed configurations now lead volume shipments across new construction applications, while renovation installations of custom designs command the widest margin pools due to measurement-intensive fabrication requirements. Triple-glazed systems remain nascent outside Singapore's Green Mark-certified commercial towers, where stringent U-value thresholds justify premium pricing.
Indonesia's BIS-equivalent SNI standards, Thailand's TISI product conformity marks, and Vietnam's QCVN building energy codes collectively determine market access and profile specification minimums. These frameworks increasingly mandate solar heat gain coefficient disclosure, pushing fabricators toward co-extruded laminates with infrared-reflective pigments. Stakeholders must monitor divergence between national testing protocols, as mutual recognition gaps between Thai TISI and Vietnamese STAMEQ certifications continue to fragment cross-border supply efficiency.
Market Dynamics
Indonesia's SNI certification mandate for thermal performance disclosure is compressing margins for non-compliant fabricators while accelerating consolidation among extruders capable of co-extruded infrared-reflective laminates.
Growth Catalysts
- Malaysia's Green Building Index:Mandatory energy efficiency thresholds for commercial developments in Kuala Lumpur and Penang are specifying double-glazed UPVC systems over aluminum alternatives in new construction tenders.
- Vietnam's Ho Chi Minh City corridor:Mid-rise condominium absorption in peripheral districts is consuming premium window systems as cooling-load reduction becomes a developer selling point.
- Co-extruded infrared-reflective pigments:Tropical-grade formulations with enhanced solar heat gain coefficient performance are winning specification in Thailand's TISI-marked projects.
Market Restraints
- Petrochemical feedstock volatility:Rigid PVC resin prices fluctuate with ethylene and chlorine derivatives, compressing extrusion margins for mid-tier fabricators in Indonesia and Vietnam.
- Cross-border certification fragmentation:Non-mutual recognition between Thai TISI and Vietnamese STAMEQ testing protocols forces redundant laboratory testing for regional suppliers.
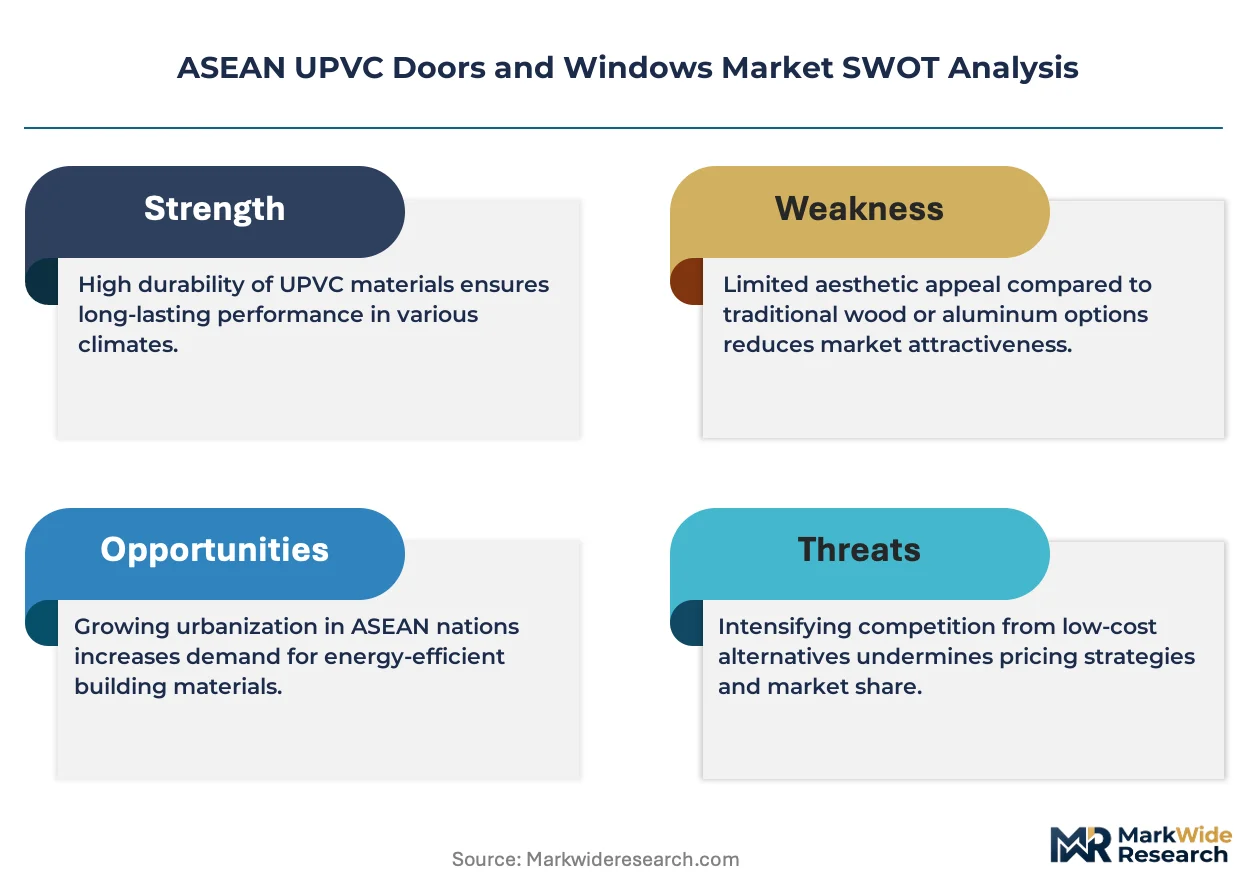
- Aluminum frame substitution:Powder-coated aluminum systems retain cost advantage in single-glazed budget residential segments across secondary Indonesian cities.
Strategic Opportunities
- Philippines building energy code implementation:Pending adoption of QCVN-equivalent standards in Metro Manila and Cebu creates first-mover positioning for certified UPVC fabricators.
- Renovation channel expansion:Measurement-intensive custom fabrication for replacement windows in Bangkok's aging condominium stock commands margin premiums over new construction.
- Triple-glazed commercial towers:Singapore's Green Mark-certified high-rise developments are specifying U-value thresholds below 1.4 W/m²K that only multi-chamber UPVC systems can achieve cost-effectively.
Industry Challenges
- Fabrication technician scarcity:Precision welding and glazing assembly skills for multi-chamber profiles remain concentrated in Thai and Malaysian training centers, constraining Vietnamese and Indonesian capacity expansion.
- Lead time compression:Just-in-time delivery requirements from Bangkok and Ho Chi Minh City developers are forcing fabricators to hold finished-goods inventory without guaranteed offtake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN UPVC Doors and Windows Market |
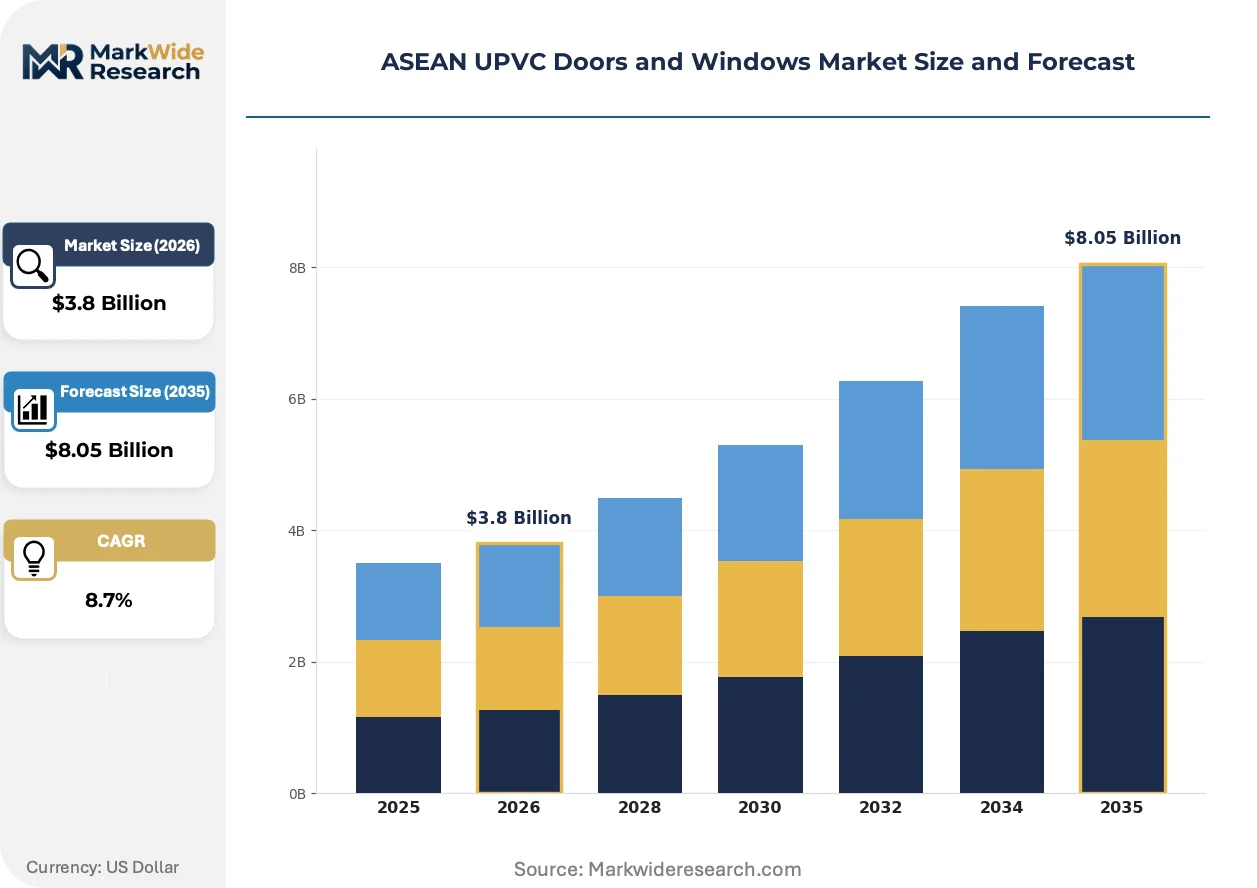
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Glazed, Double-Glazed, Triple-Glazed, Custom Designs Installation Type: New Construction, Renovation, Commercial Buildings, Residential Properties Frame Material: UPVC, Aluminum, Wood, Hybrid End User: Contractors, Architects, Homeowners, Builders |
| Companies Covered | INTI PERKASA INDONESIA, SOLID UPVC Doors & Windows System, PHILCONCH, Gartner.vn, Fenestram Corp., VEKA Group, Aluplast, Deceuninck, LG Hausys, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN UPVC Doors and Windows Market Strategic Shifts
Tropical climate adaptation is reshaping material science priorities across ASEAN fabrication, with thermal performance and color stability emerging as non-negotiable specification criteria.
Co-extruded surface laminates with infrared-reflective pigments are displacing conventional white profiles in premium specification channels. Indonesian and Malaysian developers facing Green Building Index compliance deadlines are mandating solar heat gain coefficient disclosure in tender documents. This technology is displacing standard titanium dioxide formulations in projects where cooling-load reduction determines envelope material selection.
Thailand's TISI product conformity marks and Indonesia's SNI thermal performance standards are mandating third-party laboratory certification for profile extrusion. Fabricators without captive testing facilities face six-month compliance timelines that disqualify them from government project tenders. Vietnamese QCVN building energy codes are following similar disclosure requirements, compressing procurement cycles for non-certified suppliers.
Direct specification relationships between fabricators and residential developers in Vietnam and Thailand are compressing traditional distributor margins. Mid-rise condominium projects in Ho Chi Minh City's District 2 and Bangkok's Bang Na corridor are sourcing through fabricator-direct channels that bypass wholesale building material markets. This channel shift is most visible in projects above 200 units where envelope package standardization enables volume contracting.
ASEAN UPVC Doors and Windows Market Segmentation
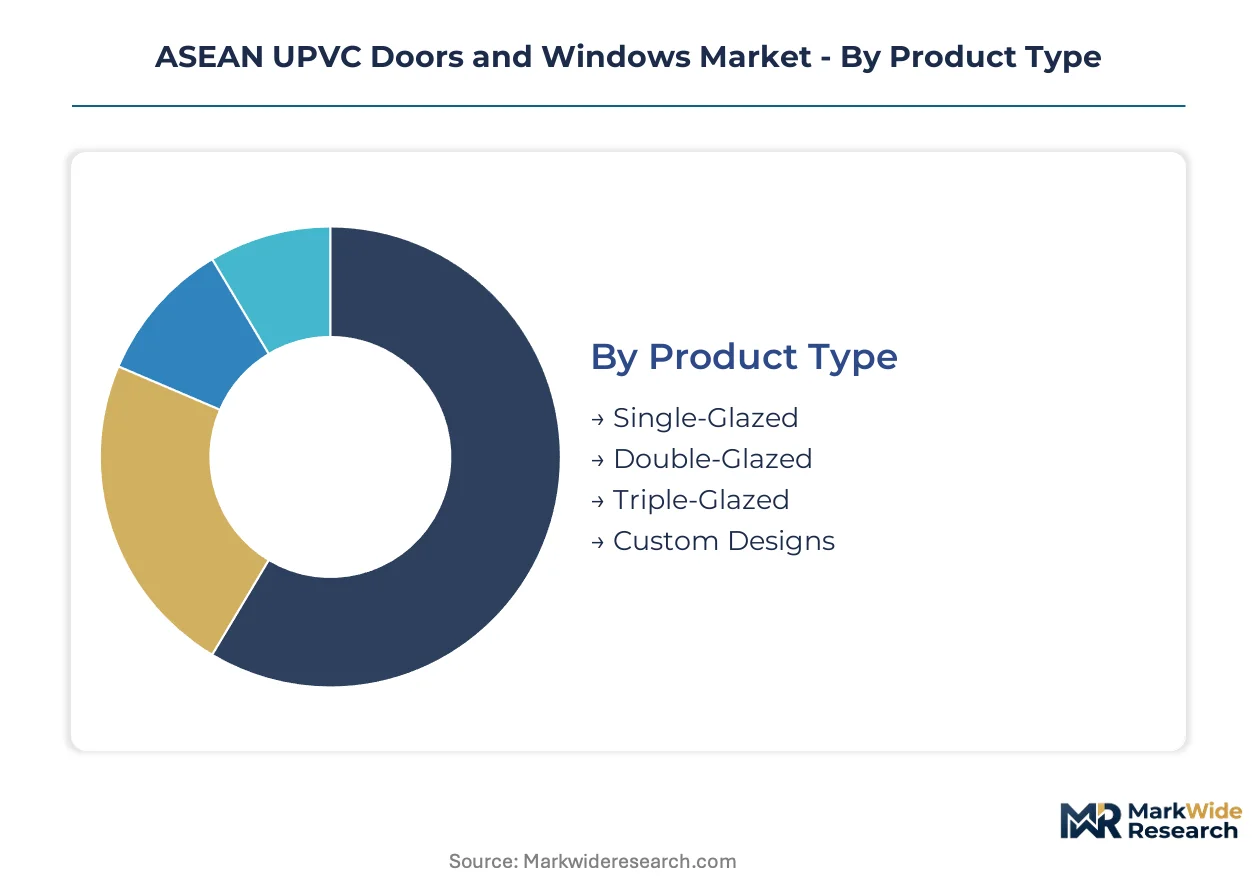
ASEAN UPVC doors and windows flow through distinct specification channels where product type determines margin structure and installation type governs procurement cadence. Fabricators calibrate extrusion capacity and inventory positioning against these segment boundaries.
Product Type:
Channel mix splits sharply between specification-grade systems for Green Building Index compliance and commodity-grade units for budget residential developments.
- Double-Glazed:Multi-chamber hollow sections with galvanized steel reinforcement achieve thermal transmittance below 1.8 W/m²K. Ho Chi Minh City's District 2 mid-rise condominiums absorb premium volumes as developers market cooling-load reduction to buyers. Indonesia's SNI thermal performance disclosure mandates are compressing procurement toward certified fabricators.
- Custom Designs:Measurement-intensive fabrication for replacement installations commands widest margin pools due to non-standard dimensions and field-verified glazing. Bangkok's aging condominium stock drives renovation channel premiums where distributor bypass is standard practice.
- Single-Glazed:Budget residential segments in secondary Indonesian cities where aluminum frames retain cost advantage.
- Triple-Glazed:Singapore's Green Mark-certified commercial towers specifying U-value thresholds below 1.4 W/m²K.
By volume, Double-Glazed leads. By growth pace, Custom Designs is climbing the fastest.
Installation Type:
Cost tier stratification separates high-velocity new construction from margin-rich renovation with distinct working capital requirements.
- New Construction:Standardized envelope packages in projects above 200 units enable fabricator-direct contracting that bypasses wholesale building material markets. Vietnam's QCVN building energy codes are tightening specification minimums for thermal performance disclosure.
- Renovation:Field-measured fabrication with extended lead times and higher rejection risk concentrates among Thai and Malaysian training centers where welding technician scarcity constrains capacity expansion.
- Commercial Buildings:Green Building Index compliance deadlines in Kuala Lumpur and Penang mandating solar heat gain coefficient disclosure.
- Residential Properties:Peripheral Bangkok zones and Ho Chi Minh City corridor absorbing mid-rise development volumes.
New Construction dominates absolute shipments. Renovation delivers superior unit economics.
Frame Material:
Application context determines material selection with thermal performance and UV stability as non-negotiable specification criteria in tropical climates.
- UPVC:Rigid PVC profiles with co-extruded infrared-reflective laminates displacing conventional white formulations in premium channels. Malaysia's Green Building Index and Indonesia's SNI standards mandate third-party laboratory certification.
- Aluminum:Powder-coated systems retaining position in single-glazed budget segments across secondary Indonesian cities where cost sensitivity overrides thermal performance.
- Wood:Heritage restoration and high-end residential applications with limited ASEAN volume penetration.
- Hybrid:Aluminum-clad UPVC composites emerging in specification-driven projects seeking structural rigidity with thermal break performance.
UPVC captures specification momentum. Aluminum defends cost-sensitive volume.
End User:
Customer type dictates relationship depth with direct specification replacing traditional distribution in large-scale developments.
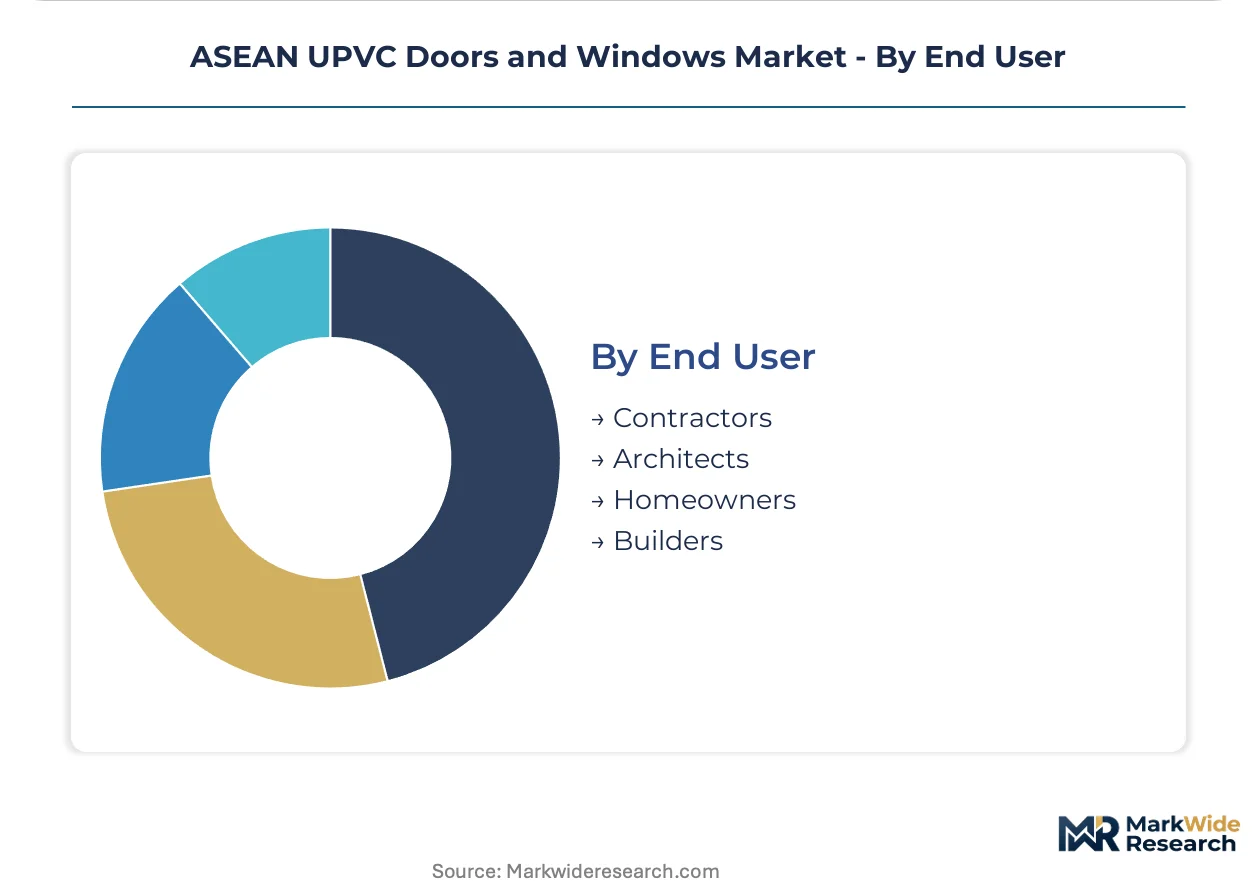
- Builders:Volume contractors in Vietnam and Thailand establishing direct procurement relationships with extruders for standardized envelope packages. Just-in-time delivery requirements force finished-goods inventory holding without guaranteed offtake.
- Architects:Specification authority in Green Building Index and Green Mark-certified projects where thermal transmittance values determine material selection.
- Contractors:Installation execution with fabrication technician scarcity concentrated in Thai and Malaysian training centers.
- Homeowners:Replacement window demand in Bangkok's aging stock channeled through renovation specialists.
Builders drive procurement volume. Architects control specification value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential developers and commercial contractors in Thailand, Vietnam, and Indonesia drive specification volume, while Malaysia and Singapore set thermal performance benchmarks that reshape procurement across the region.
Thailand
Bangkok's peripheral residential zones absorb premium double-glazed systems as mid-rise condominium construction accelerates. The Thai Industrial Standards Institute (TISI) mandates product conformity marks for thermal performance disclosure. Fabricators in Bang Na corridor establish direct procurement relationships with volume contractors, bypassing wholesale building material markets.
Vietnam
Ho Chi Minh City's District 2 corridor consumes specification-grade UPVC systems as cooling-load reduction becomes a developer selling point. The QCVN building energy codes tighten thermal transmittance minimums for new construction. Peripheral districts absorb mid-rise volumes where envelope package standardization enables fabricator-direct contracting.
Indonesia
Jakarta and secondary city developers face margin compression from SNI certification mandates for thermal performance disclosure. The National Standardization Agency requires third-party laboratory certification for profile extrusion. Certified fabricators in Java consolidate market access while non-compliant suppliers exit government project tenders.
Malaysia
Kuala Lumpur and Penang commercial developments specify double-glazed UPVC over aluminum alternatives under Green Building Index compliance deadlines. The Green Building Index mandates energy efficiency thresholds that favor thermally broken envelope systems. Fabricators serving Klang Valley projects hold co-extruded infrared-reflective inventory to meet solar heat gain coefficient requirements.
Singapore
Green Mark-certified commercial towers specify triple-glazed systems achieving U-values below 1.4 W/m²K. The Building and Construction Authority administers Green Mark standards that justify premium pricing for multi-chamber profiles. Marina Bay and Orchard Road high-rise developments anchor demand for specification-grade thermal performance.
ASEAN UPVC Doors and Windows Market Competitive Environment
Player mix skews toward European technical specialists and Asian volume fabricators competing across certification-tiered procurement channels. Market structure concentrates specification authority among extruders with captive testing facilities and tropical-grade formulation capabilities. Two strategic archetypes dominate: heritage European profile suppliers leveraging technical certification, and localized compounders optimizing lead times for regional climate adaptation. Competitive moves center on backward integration into resin compounding and strategic partnerships with residential developers for direct specification.
Among European heritage suppliers, VEKA Group, Deceuninck, and LG Hausys occupy positions that exemplify divergent competitive vectors. VEKA represents the technical-certification archetype sustaining premium positioning in specification-driven projects. Deceuninck anchors the localized-compounding model through regional formulation capabilities. LG Hausys exemplifies warranty-based differentiation targeting color stability under tropical UV exposure. These three collectively illustrate how technical heritage, supply chain proximity, and product-specific guarantees fragment competitive positioning across ASEAN procurement tiers.
| Leading Market Players |
|---|
| INTI PERKASA INDONESIA |
| SOLID UPVC Doors & Windows System |
| PHILCONCH |
| Gartner.vn |
| Fenestram Corp. |
| VEKA Group |
| Aluplast |
| Deceuninck |
| LG Hausys |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Thai and Vietnamese fabricators and ethylene derivative suppliers lock in resin access while capping price volatility exposure for certified extruders. This contract structure concentrates procurement power among incumbents with TISI and SNI laboratory certification, compressing margin flexibility for spot-market dependent mid-tier players.
Pricing Analysis
Cost-plus contracts indexed to ethylene and chlorine derivative spot markets dominate raw material procurement for ASEAN extruders. Price differentiation hinges on certification tier—SNI/TISI-compliant fabricators command premium positioning—versus volume scale for standardized envelope packages. Cost compression intensifies in budget residential segments where aluminum frames retain substitution leverage. Government project tenders exhibit lowest price sensitivity; spot-market fabricators in secondary Indonesian cities face highest buyer pressure.
Supply Chain Analysis
Just-in-time delivery requirements from Bangkok and Ho Chi Minh City developers favor strategic stockpiling of tropical-grade co-extruded laminates among certified fabricators. Supply concentrates in Thailand, Vietnam, and Malaysia where precision welding technician training infrastructure exists. Raw material flows draw from petrochemical feedstocks—rigid PVC resin, galvanized steel inserts, low-emissivity glass—anchored in regional ethylene production clusters. Single-source vulnerability runs through Indonesian resin compounding capacity. Distribution runs through fabricator-direct channels for projects above 200 units, bypassing wholesale building material markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified welding technician scarcity constrains Vietnamese and Indonesian capacity expansion, creating defendable positioning for Thai and Malaysian incumbents with captive training infrastructure. This capability gap shapes competitive dynamics across specification tiers.
For Market Incumbents: Consolidate procurement relationships with residential developers in Ho Chi Minh City's District 2 and Bangkok's Bang Na corridor through standardized envelope packages. Deepen backward integration into tropical-grade resin compounding to defend margin position against petrochemical feedstock volatility. Lock in SNI and TISI certification renewal timelines before compliance windows compress. For New Entrants and Emerging Players: Post-installation warranty and field service networks represent a service-layer gap where European heritage suppliers under-serve renovation channel demand. Target Bangkok's aging condominium stock with measurement-intensive custom fabrication bypassing distributor markups. Penetrate through certified technician apprenticeship partnerships with Thai training centers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors extruders with captive laboratory testing and tropical-formulation capabilities. Five-to-ten year viability favors SNI/TISI-certified fabricators with direct developer relationships. Watch Philippine QCVN building energy code implementation timing as inflection indicator for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive tropical-grade formulation reduces lead times and ethylene price exposure for TISI-certified Thai fabricators. |
| Certified Technician Training Center Expansion | Vietnamese extruders overcome welding skill scarcity by licensing Malaysian training protocols for multi-chamber assembly. |
| Direct Developer Specification Partnerships | Bangkok and Ho Chi Minh City mid-rise projects bypass wholesale markets through fabricator-direct envelope contracting. |
| Infrared-Reflective Co-Extrusion Capacity Addition | Indonesian fabricators meet SNI solar heat gain coefficient mandates for Green Building Index procurement. |
| Cross-Border Certification Harmonization Lobbying | Regional suppliers reduce redundant TISI-STAMEQ testing costs through mutual recognition advocacy. |
Study Parameters
Operator-level perspectives from extrusion plant managers, procurement leads at Thai and Vietnamese residential developers, TISI laboratory certification officers, and distributor channel heads anchored the qualitative base. Secondary validation drew from SNI and TISI regulatory filings, ASEAN customs trade data for rigid PVC resin flows, and Green Building Index project registries. Bottom-up fabrication capacity surveys triangulated against top-down construction permit analysis across the five core markets.
Sensitivity analysis tested forecast outputs against ethylene price volatility bands and certification adoption rate scenarios across the projection horizon. The analytical framework modeled segmentation dimensions spanning glazing configuration, installation type, frame material grade, and end-user procurement channel. CAGRs derived from unit shipment trajectories weighted by thermal performance tier and regional building code enforcement intensity. Industry-specific inputs included QCVN implementation timelines and Green Mark U-value threshold revisions.
Underlying assumptions cover petrochemical feedstock stability, certification mutual recognition progress, and technician training capacity expansion, with deviation risk concentrated in Indonesian SNI enforcement variability and Philippine regulatory adoption delays. Revision becomes warranted when cross-border testing protocol harmonization crosses implementation thresholds or when aluminum substitution rates in budget residential segments exceed modeled bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Bookends Market
Homecare and Decor
Louvre Windows Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
India Sustainable Home Decor Market